
 Multistrain Probiotics Market | 2026-2036
Multistrain Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Multistrain Probiotics Market Foresight
European fermentation capacity is pivoting toward multistrain production suites as dairy and supplement processors expand output. Novonesis A/S leverages its enzymology heritage to anchor high-throughput strain screening platforms. Lallemand Inc. sustains decades of yeast and bacteria expertise to dominate human nutrition applications. Probi AB competes through specialized gastrointestinal and immune-modulating strain portfolios.
Multistrain probiotics are live microbial preparations containing two or more characterized bacterial strains, typically formulated at colony-forming unit counts exceeding 10 billion CFU per dose, designed to colonize the host gut microbiome and confer synergistic health benefits beyond single-strain equivalents. Capsule and powder formats lead volume due to shelf stability and dosing precision, while liquid formulations represent the fastest-growing category as beverage manufacturers integrate live cultures into functional drinks. Digestive health applications occupy the largest margin pool, though immune support segments are gaining share as post-pandemic consumers prioritize resilience.
EFSA in Europe, FDA in the United States, and FSSAI in India enforce divergent strain approval pathways and label claim standards, compelling manufacturers to maintain jurisdiction-specific dossiers and clinical evidence packages. The EU's Novel Food Regulation and pending harmonization of postbiotic definitions will reshape market access timelines for next-generation formulations. Stakeholders must monitor regulatory divergence between GRAS self-affirmation in the United States and pre-market authorization requirements in Europe to optimize portfolio allocation and clinical trial investment.
Market Dynamics
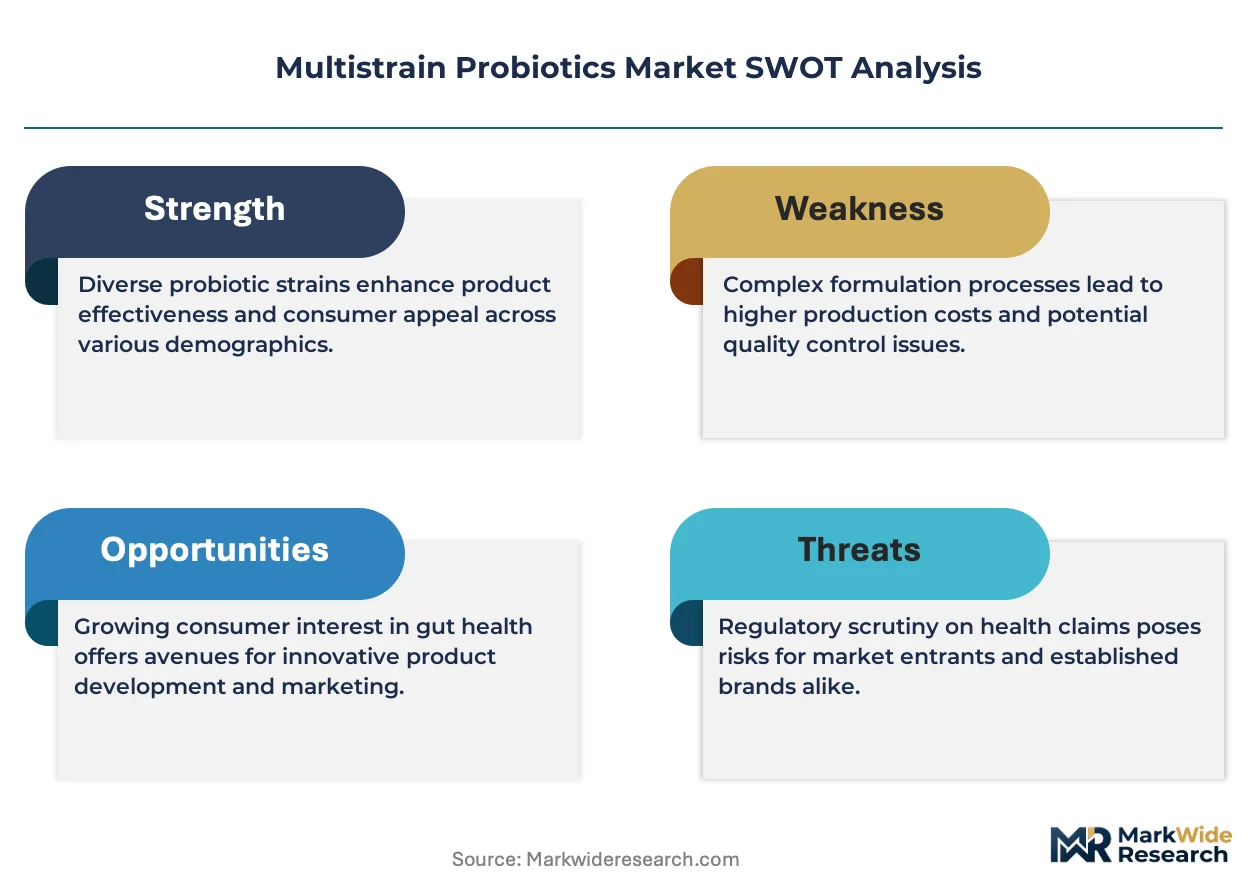
Strain-specific health claim validation under EFSA and FDA frameworks is compressing product development timelines and forcing manufacturers to front-load clinical investment before commercialization.
Growth Catalysts
- EFSA Article 13.1/13.5 Pathways:European regulators are clarifying probiotic claim substantiation requirements, reducing regulatory uncertainty for dossier-ready manufacturers seeking gut health and immune function endorsements.
- Fermented Beverage Integration:Functional drink manufacturers in Germany and Japan are embedding multistrain cultures into dairy alternatives and kombucha variants, expanding consumption occasions beyond supplement formats.
- Aging Demographics:Preventive healthcare spending among consumers over 55 in the United States is elevating microbiome-targeted product adoption as first-line wellness interventions.
Market Restraints
- Cryoprotectant Input Volatility:Trehalose and skim milk powder prices fluctuate with dairy commodity cycles, destabilizing formulation cost structures for freeze-dried probiotic suppliers.
- Strain Bank Concentration:Master cell repositories and proprietary culture collections cluster among a handful of European and North American biobanks, creating supply chokepoints for new market entrants.
- Stability Shelf-Life Limitations:Viability decay above 25°C restricts ambient distribution channels, forcing cold chain investments that compress margins in tropical and subtropical markets.
Strategic Opportunities
- Postbiotic Regulatory Tailwinds:Pending harmonization of postbiotic definitions under EU Novel Food Regulation will unlock accelerated market access for heat-inactivated and cell-free formulations.
- Pediatric Application White Space:Strain portfolios targeting infant gut colonization and early immune education remain underdeveloped relative to adult digestive health saturation.
- Direct-to-Consumer Microbiome Testing:Integration of at-home gut health diagnostics with personalized probiotic subscription models is emerging as a channel innovation in the United States.
Industry Challenges
- Clinical Trial Talent Scarcity:Microbiome study design expertise and biostatisticians specializing in gut microbiota endpoints command premium compensation, constraining trial execution capacity.
- Multi-Jurisdiction Dossier Maintenance:Parallel GRAS self-affirmation in the United States and pre-market authorization in Europe force redundant safety and efficacy documentation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multistrain Probiotics Market |
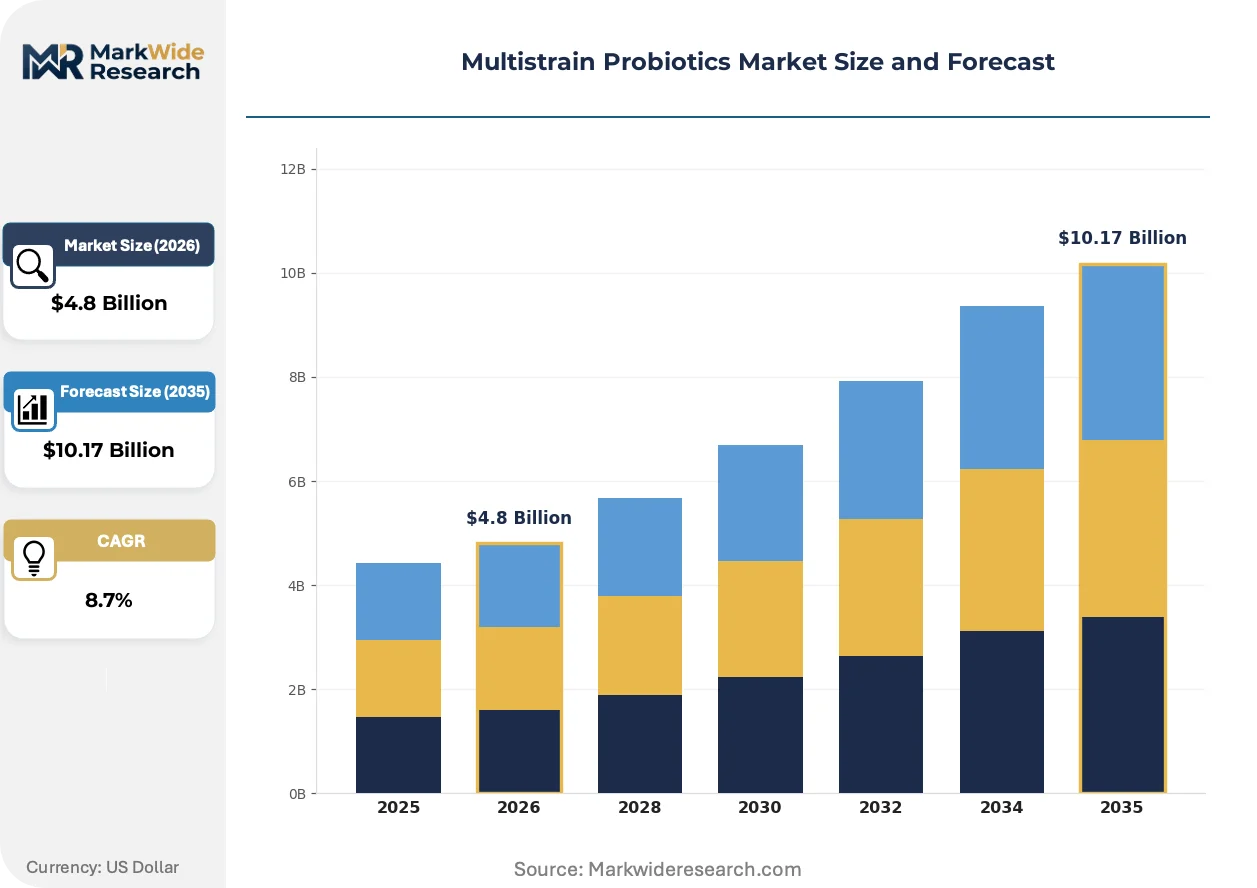
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Tablets, Liquid Formulations Application: Digestive Health, Immune Support, Weight Management, Oral Health Distribution Channel: Supermarkets, E-Commerce, Pharmacies, Health Food Stores End User: Adults, Children, Athletes, Seniors |
| Companies Covered | Yakult Honsha Co., Ltd., Deerland Enzymes, Inc., Protexin, Danisco, BioGaia, Novonesis A/S, Lallemand Inc., Probi AB, DuPont Nutrition & Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multistrain Probiotics Market Shifts & Advancements
Manufacturing automation and strain characterization technologies are compressing development cycles while regulatory clarity around next-generation formats is reshaping competitive positioning.
High-throughput screening platforms combining genomic sequencing with artificial intelligence-driven phenotype prediction are modularizing strain selection workflows. Contract manufacturers in Denmark and the Netherlands are adopting these integrated systems to reduce candidate-to-product timelines from 36 months to 18 months. This compression is enabling smaller players to challenge established portfolios without captive R&D infrastructure.
EFSA's evolving stance on live microorganism health claims is forcing European manufacturers to pivot from generic "probiotic" labeling toward strain-specific, condition-specific dossiers. The industrial consequence is a bifurcation between companies with completed clinical packages and those reformulating as "fermented" products without live culture claims. Digestive health applications face the steepest compliance burden, while immune modulation claims are attracting accelerated investment.
Subscription-based replenishment models are displacing traditional retail purchasing for core supplement users. Direct-to-consumer channels in the United States and Germany are capturing recurring revenue through personalized dosing protocols tied to lifestyle data inputs. This shift is most visible among urban consumers aged 30-45, where convenience and perceived customization outweigh pharmacy channel loyalty.
Multistrain Probiotics Market Segmentation
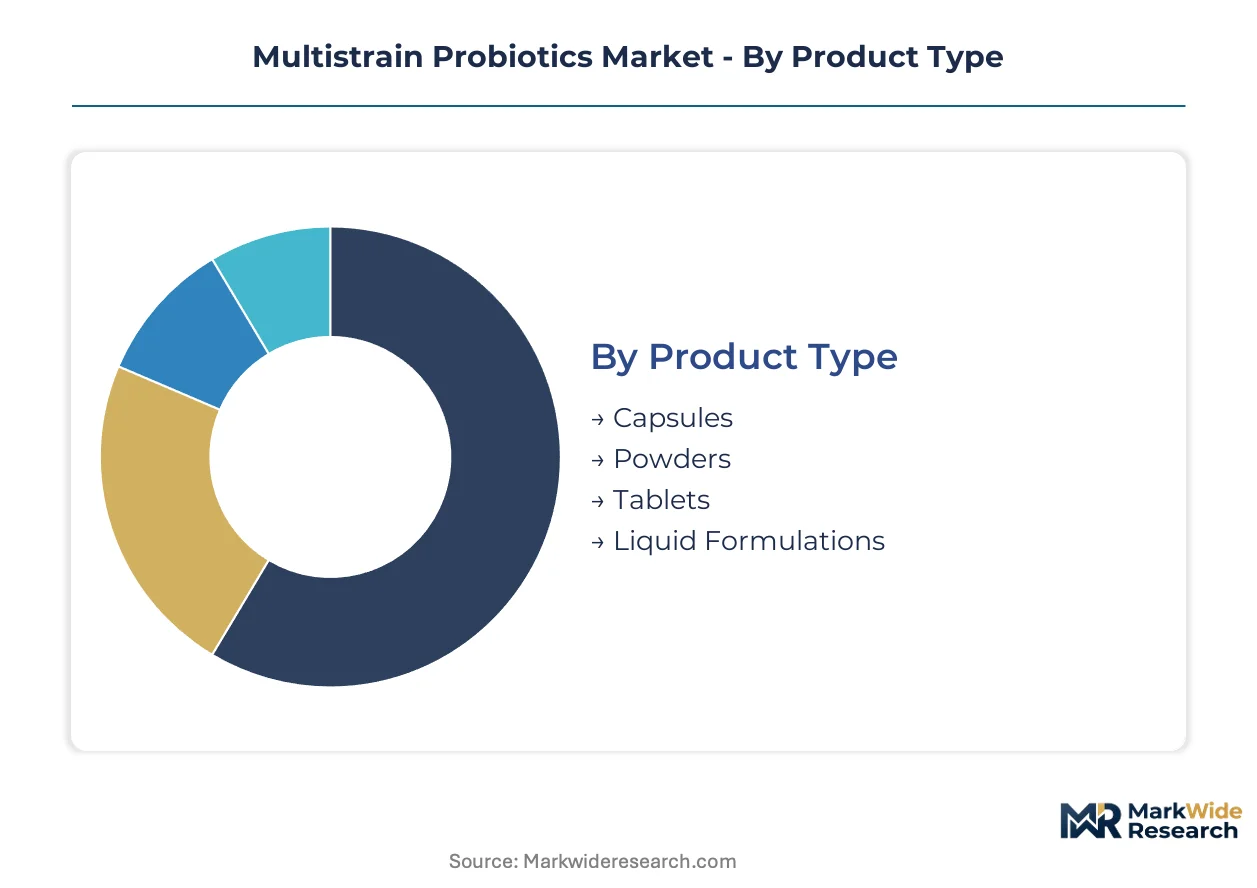
Multistrain probiotic manufacturers allocate capital unevenly across format technologies and claim categories, with freeze-drying infrastructure and clinical dossier development consuming the largest upfront outlays. Segment-specific regulatory burdens and shelf-stability requirements further stratify investment thresholds across the value chain.
Product Type:
Capsule and powder formats demand the heaviest capital commitment due to lyophilization equipment and cryoprotectant formulation suites, while liquid production lines require aseptic filling but lower per-unit equipment costs.
- Capsules:Hard gelatin and hydroxypropyl methylcellulose shells encapsulate freeze-dried cultures at 10-50 billion CFU per unit, with enteric coating adding 15-20% to manufacturing cost. German and Japanese pharmaceutical contract manufacturers dominate capacity for high-potency enteric formulations serving aging populations with compromised gastric acid profiles.
- Powders:Sachet and bulk formats blend multistrain concentrates with prebiotic fibers and flavor masking agents, enabling flexible dosing protocols. Demand clusters in direct-to-consumer channels across the United States, where subscription models favor portion-controlled daily sachets over bottle-based replenishment cycles.
- Tablets:Compression-based formats expose cultures to mechanical shear and elevated temperatures, limiting viability preservation to hardy spore-forming strains such as Bacillus coagulans.
- Liquid Formulations:Aseptically fermented beverages and shot formats integrate live cultures into kombucha, kefir, and plant-based dairy alternatives.
Capsules absorb the bulk of installed capacity; liquid formulations are expanding most quickly.
Application:
Margin structures diverge sharply between mature digestive health claims and emerging immune modulation categories, with the latter commanding premium pricing but requiring heavier clinical investment.
- Digestive Health:Irritable bowel syndrome, antibiotic-associated diarrhea, and general gut maintenance applications constitute the largest revenue pool, though EFSA and FDA claim substantiation requirements have compressed margins for non-dossiered products. European manufacturers face particular pressure to reformulate or retire generic "probiotic" labeling.
- Immune Support:Upper respiratory tract infection prevention and vaccine adjuvant applications attract accelerated R&D spending from Japanese and North American suppliers targeting post-pandemic preventive health budgets. Strain-specific evidence packages for Lactobacillus rhamnosus GG and Bifidobacterium lactis BB-12 dominate regulatory submissions.
- Weight Management:Metabolic syndrome and satiety modulation claims remain underdeveloped relative to digestive and immune categories, with inconsistent clinical outcomes limiting mainstream adoption.
- Oral Health:Periodontal disease and halitosis applications leverage Streptococcus salivarius strains in lozenge and chewable formats.
Digestive health commands the deepest clinical evidence base; immune support is climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity, with e-commerce requiring inventory flexibility and pharmacies demanding extended payment terms and regulatory documentation.
- Supermarkets:Mass retail placement in refrigerated dairy and supplement aisles drives volume but squeezes margins through slotting fees and promotional fund requirements. German and Japanese retail consolidation limits new entrant access.
- E-Commerce:Direct-to-consumer platforms and marketplace aggregators enable personalized subscription models with recurring revenue capture. Urban United States consumers aged 30-45 demonstrate highest channel loyalty for microbiome testing-integrated replenishment services.
- Pharmacies:Behind-the-counter and pharmacist-recommended positioning supports premium pricing but requires extensive safety documentation and cold chain integrity guarantees.
- Health Food Stores:Independent and specialty retailers emphasize strain transparency and organic certification credentials.
E-Commerce captures the steepest expansion trajectory; pharmacies retain the highest margin per unit.
End User:
Demographic targeting dictates strain portfolio composition and dosing architecture, with pediatric and senior segments imposing the most stringent safety and palatability requirements.
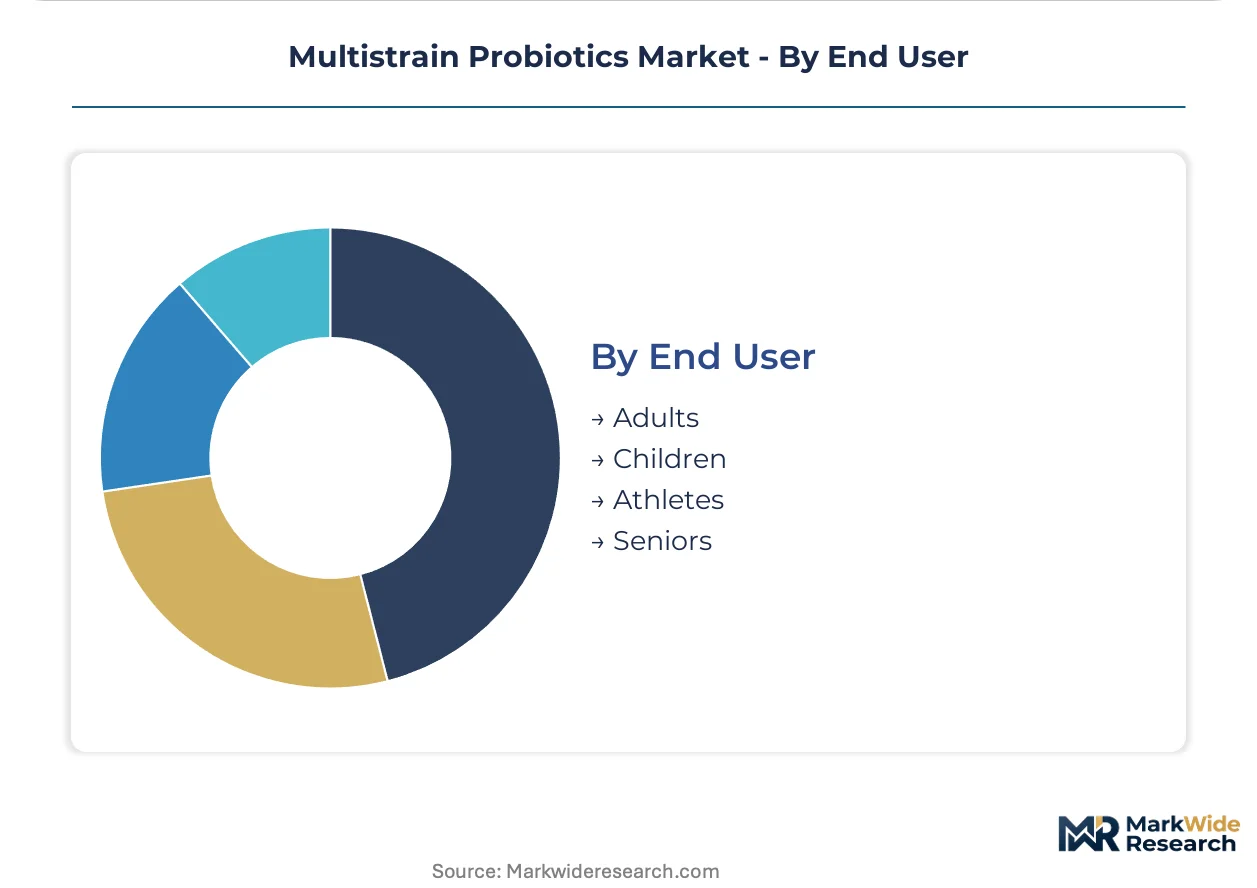
- Adults:General wellness and condition-specific formulations dominate volume, with 25-55 age brackets driving capsule and powder consumption across developed markets. Functional beverage integration targets this cohort for occasion expansion beyond morning supplement routines.
- Children:Early gut colonization and immune education applications remain underdeveloped relative to adult saturation, with strain selection limited to historically safe species and delivery formats constrained to powders and chewables. Regulatory caution from EFSA and FDA delays novel strain introduction.
- Athletes:Exercise-induced immune suppression and gastrointestinal distress during endurance events drive demand for high-CFU, multi-species formulations with rapid colonization kinetics.
- Seniors:Age-related microbiome depletion and medication-induced dysbiosis elevate probiotic adoption among consumers over 65 in the United States and Japan.
Adults represent the largest addressable population; children present the most significant white space for portfolio expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy fermentation clusters in Denmark and the Netherlands anchor European strain production capacity, while Japanese and North American markets drive formulation innovation through aging demographics and preventive health spending.
United States
Consumers over 55 allocate rising shares of wellness budgets toward microbiome-targeted interventions, elevating demand for high-CFU capsule and powder formats. FDA GRAS self-affirmation pathways allow faster market entry than European pre-market authorization, though strain-specific health claims still require substantial clinical dossiers. Greater Boston and Research Triangle Park host contract research organizations specializing in gut microbiota endpoints.
Germany
Fermented beverage manufacturers embed multistrain cultures into oat-based dairy alternatives and kombucha variants, expanding consumption occasions beyond traditional supplement routines. EFSA Article 13.1/13.5 claim substantiation requirements pressure manufacturers to retire generic "probiotic" labeling in favor of strain-specific dossiers. Bavarian and Baden-Württemberg fermentation facilities are pivoting toward multistrain production suites.
Japan
Post-pandemic preventive health budgets elevate immune-modulating probiotic adoption among urban professionals and seniors alike. PMDA and Ministry of Health, Labour and Welfare regulations enforce stringent stability and viability labeling standards. Tokyo-Osaka corridor pharmaceutical contract manufacturers dominate high-potency enteric formulation capacity.
Denmark
Enzymology heritage and strain banking infrastructure concentrate bioprocessing expertise around Copenhagen and Aarhus. Novo Nordisk Foundation-funded research institutions accelerate high-throughput screening platform adoption. Danish contract manufacturers are compressing candidate-to-product timelines through genomic sequencing and artificial intelligence-driven phenotype prediction integration.
India
FSSAI strain approval pathways and label claim standards diverge from Western frameworks, compelling manufacturers to maintain jurisdiction-specific dossiers. Rising middle-class preventive health awareness drives powder and sachet format demand in metropolitan centers. Hyderabad and Bangalore biotech clusters are developing localized strain characterization capabilities.
Multistrain Probiotics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue postbiotic and pediatric application white space. The market structure reflects moderate consolidation around heritage fermentation specialists and pharmaceutical-grade contract manufacturers. Three archetypes dominate: enzymology-anchored bioprocessors, yeast and bacteria heritage houses, and specialized gastrointestinal strain portfolio developers. Capacity expansion and clinical trial front-loading constitute the dominant competitive moves as regulatory claim substantiation requirements harden.
Within the heritage fermentation tier, Novonesis A/S and Lallemand Inc. exemplify scale-driven bioprocessing archetypes, while Probi AB occupies a position among specialized strain portfolio developers. Novonesis leverages Danish enzymology infrastructure, Lallemand represents North American yeast and bacteria expertise, and Probi exemplifies focused gastrointestinal and immune-modulating strain development. These three entities anchor the competitive landscape through distinct capability concentrations rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Yakult Honsha Co., Ltd. |
| Deerland Enzymes, Inc. |
| Protexin |
| Danisco |
| BioGaia |
| Novonesis A/S |
| Lallemand Inc. |
| Probi AB |
| DuPont Nutrition & Health |
| Others |
Supply & Pricing Matrix
EFSA Article 13.1/13.5 claim substantiation mandates are forcing manufacturers to front-load clinical investment before commercialization, compelling supply chain reconfiguration toward high-throughput screening platforms and jurisdiction-specific dossier maintenance that compresses margin structures across freeze-dried and liquid formulation tiers.
Pricing Analysis
Extended stability warranties and cold chain integrity guarantees are increasingly unbundled from base product pricing, with pharmaceutical-grade enteric coatings and cryoprotectant formulations commanding 15-20% premiums over standard capsules. Three-tier pricing structure across premium, standard, and economy levels separates strain-specific dossiered products from generic fermented alternatives and bulk powder sachets. Pricing pressure stems from trehalose and skim milk powder commodity volatility destabilizing freeze-dried formulation costs. Direct-to-consumer subscription buyers aged 30-45 in the United States exhibit lowest price sensitivity, while mass retail pharmacy channels in Germany face acute margin compression from slotting fee escalation.
Supply Chain Analysis
Single-source vulnerability sits with Danish and Dutch contract manufacturers controlling high-throughput genomic screening platforms and master cell repositories. Probiotic strain banking concentrates in Copenhagen-Aarhus and Bavarian fermentation clusters, with cryoprotectant inputs drawing from dairy commodity markets in Germany and the Netherlands. Supply chain risk manifests as regulatory restriction divergence between FDA GRAS self-affirmation and EFSA pre-market authorization pathways forcing redundant documentation investments. Distribution runs through cold chain-dependent pharmacy networks in Japan and direct-to-consumer platforms in the United States, with ambient distribution blocked by viability decay above 25°C.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around heritage fermentation specialists with completed clinical dossiers, as EFSA and FDA claim substantiation requirements force smaller players lacking strain-specific evidence packages toward reformulation or exit.
For Market Incumbents: To counter emerging AI-driven strain screening platforms from Danish contract manufacturers, Novonesis A/S and Lallemand Inc. must deepen captive supply of high-throughput genomic infrastructure and accelerate pediatric application portfolio expansion. Defensive consolidation should prioritize Bavarian and Baden-Württemberg fermentation facility acquisition to secure multistrain production capacity ahead of European Novel Food Regulation harmonization. For New Entrants and Emerging Players: Capture underdeveloped pediatric gut colonization and early immune education segments where EFSA and FDA regulatory caution has limited established player penetration. White space exists in infant-safe strain portfolios and powder format delivery systems for children under five. Go-to-market execution should leverage direct-to-consumer microbiome testing integration in the United States, mirroring subscription models already validated among urban professionals aged 30-45. For Investors and Strategic Acquirers: The window for entry favors specialized gastrointestinal strain portfolio developers with completed Lactobacillus rhamnosus GG or Bifidobacterium lactis BB-12 dossiers. Long-term viability hinges on regulatory navigation capability across FDA, EFSA, and FSSAI frameworks rather than manufacturing scale alone. Signal to monitor: EFSA postbiotic definition harmonization timeline, which will revalue heat-inactivated formulation assets.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Dossier Front-Loading | Strain-specific EFSA Article 13.5 submissions now precede commercialization rather than follow market entry. |
| High-Throughput Platform Acquisition | AI-driven genomic screening integration compresses candidate-to-product timelines from 36 months toward 18 months. |
| Pediatric Strain Portfolio Development | Infant gut colonization applications remain underdeveloped relative to adult digestive health saturation. |
| Cold Chain Infrastructure Expansion | Viability decay above 25°C restricts ambient distribution, forcing refrigerated logistics investment in tropical markets. |
| Postbiotic Formulation Pivot | Pending EU Novel Food Regulation harmonization unlocks accelerated market access for heat-inactivated products. |
Research Methodology
Document review covered EFSA health claim register entries, FDA GRAS notification filings, FSSAI strain approval records, and clinical trial registrations on ClinicalTrials.gov, complemented by interviews with fermentation facility operations directors, regulatory affairs specialists at probiotic manufacturers, pharmaceutical contract manufacturing executives, and direct-to-consumer brand managers. Secondary validation drew from customs trade data on cryoprotectant inputs, dairy commodity price indices, and SEC 10-K disclosures from publicly traded nutrition companies. Bottom-up strain production capacity estimates were triangulated against top-down preventive healthcare spending projections.
Cross-referencing historical fermentation capacity expansion patterns with expert panel input on regulatory timeline expectations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included product format (capsule, powder, liquid), application category (digestive health, immune support, pediatric), distribution channel (e-commerce, pharmacy, mass retail), and end-user demographic (adults, children, seniors). CAGRs were derived from iterative reconciliation of supply-side capacity constraints with demand-side adoption curves, incorporating strain-specific clinical evidence completion rates and jurisdiction-specific approval pathway durations as probiotic industry inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA postbiotic definition finalization, trehalose commodity price volatility, and FSSAI regulatory convergence with Western frameworks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
South America Feed Probiotics Market