
 Instant Tea Market | 2026-2036
Instant Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Tea Market Foresight
E-commerce fulfillment networks is reconfiguring how instant tea reaches end users, with direct-to-pantry subscriptions and quick-commerce platforms capturing share from traditional grocery aisles. Nestlé leverages its Nespresso infrastructure to cross-merchandise instant tea pods through established subscription channels. Tata Consumer Products Limited anchors South Asian demand through its deep distribution in Indian kirana stores and modern trade. PepsiCo competes aggressively in the ready-to-drink adjacent space, using its beverage logistics muscle to place liquid concentrates in convenience stores.
Instant tea comprises dehydrated or concentrated tea extracts reconstituted with water, typically manufactured through spray-drying, freeze-drying, or hot-brew extraction followed by concentration to preserve polyphenol content and aromatic compounds. Powdered tea dominates manufacturing scale due to lower logistics cost per serving and extended shelf stability, though liquid concentrate commands margin pools in foodservice channels where speed of preparation outweighs unit economics. Green tea within the flavor profile dimension leads household penetration in East Asian markets, while fruit flavors capture younger demographics in Western markets through social media-driven trial. Supermarkets still occupy the largest volume share among distribution channels, but online retail represents the fastest-growing route as pantry-stockpiling behaviors normalize post-pandemic.
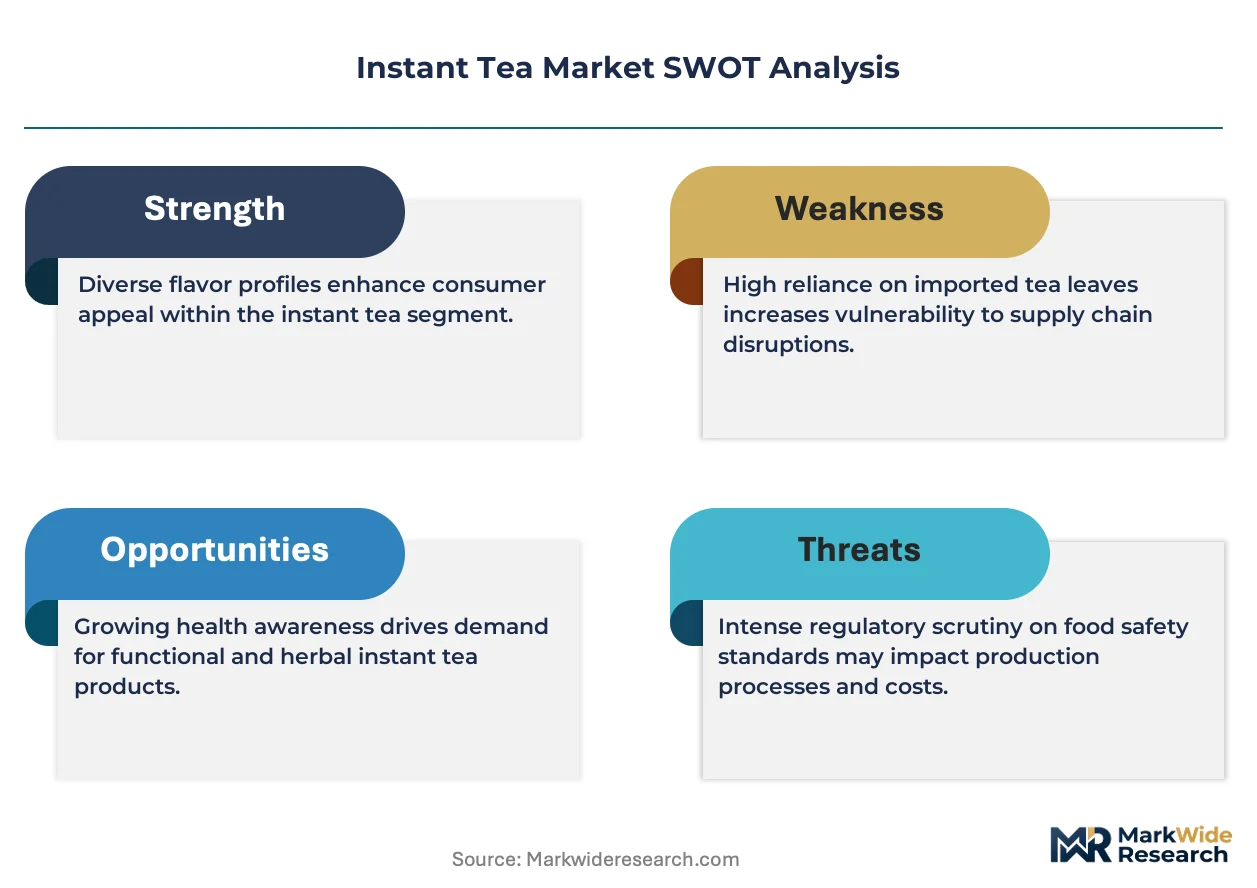
FDA nutrition labeling mandates on added sugars and the EU's Farm to Fork Strategy under the EU Green Deal are reshaping formulation standards and ingredient sourcing transparency for instant tea sold in North America and Europe. BIS certification requirements in India and FSSAI standards govern product claims and quality benchmarks for domestic manufacturers and importers alike. Stakeholders must monitor how evolving sugar taxation regimes and packaging waste directives alter both cost structures and consumer perception of convenience-oriented tea formats.
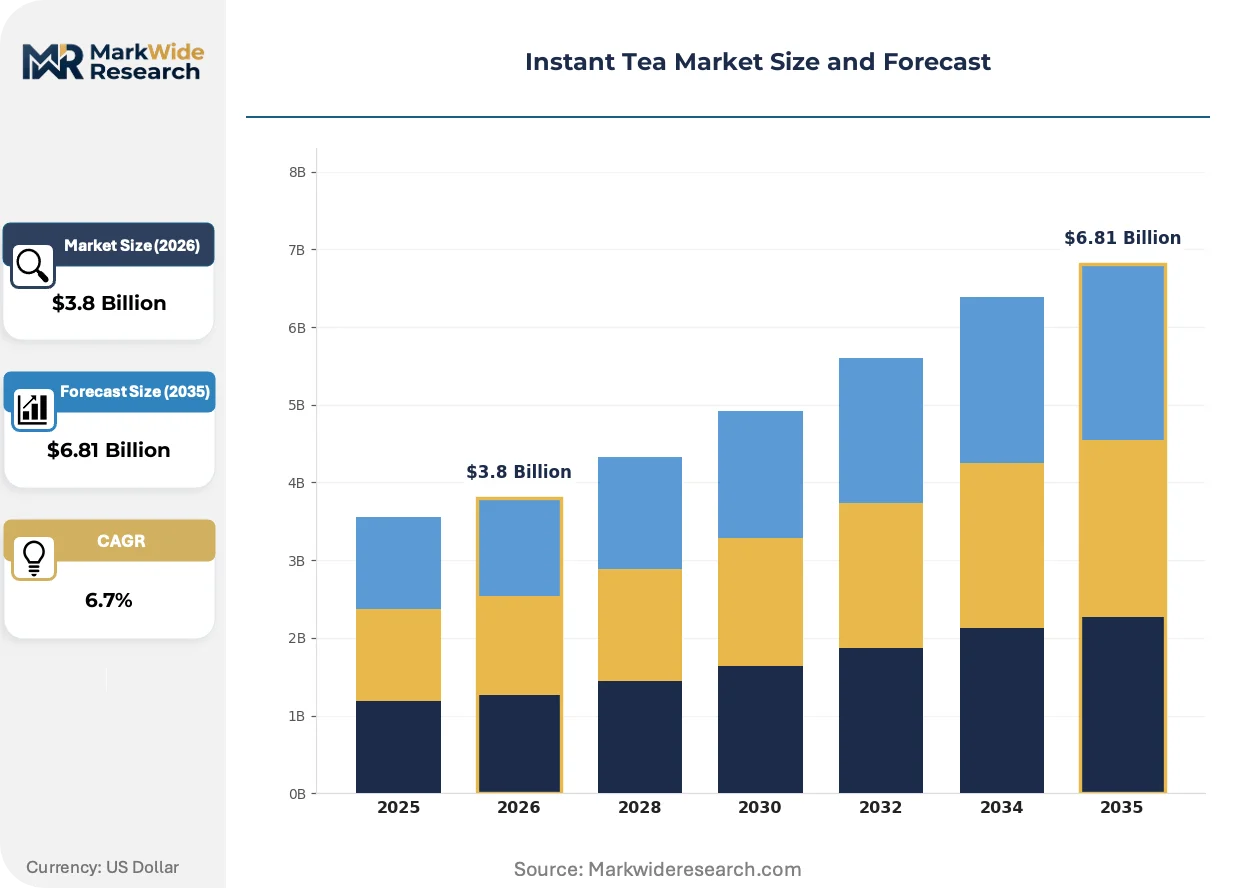
Market Dynamics
E-commerce fulfillment networks are reconfiguring how instant tea reaches end users, with direct-to-pantry subscriptions and quick-commerce platforms capturing share from traditional grocery aisles while FDA sugar labeling mandates force reformulation across North American portfolios.
Growth Catalysts
- Clean-label reformulation:The FDA's updated nutrition labeling requirements for added sugars are pushing manufacturers toward concentrates with transparent ingredient decks and reduced sweetener loads.
- Workplace beverage programs:Office spaces across North America and Europe are expanding procurement of single-serve formats for employee amenity packages, normalizing pod-based tea consumption during business hours.
- Freeze-drying technology:Advanced dehydration methods are preserving polyphenol content and aromatic compounds at levels previously unattainable through spray-drying, elevating sensory quality in premium powder segments.
Market Restraints
- Input cost volatility:Tea leaf prices fluctuate with rainfall patterns in Assam and Kenya, squeezing margin predictability for concentrate manufacturers locked into annual procurement contracts.
- Supply concentration risk:Spray-drying capacity clusters in Guangdong province, creating single-point vulnerability for powder-format producers dependent on Chinese toll processing.
- Substitution threat from RTD:Ready-to-drink bottled teas in Japanese convenience stores and American gas stations capture trial occasions that powdered formats struggle to access.
Strategic Opportunities
- Quick-commerce penetration:Urban India and Southeast Asian megacities present underexploited routes for sub-15-minute delivery of instant tea sachets through dark-store networks.
- EU Farm to Fork alignment:The EU Green Deal's sustainability disclosure requirements reward early movers in regenerative tea sourcing and biodegradable pod materials with preferential retail placement.
- Functional ingredient convergence:Marriage of instant tea extracts with adaptogens and nootropics is opening wellness-positioned SKUs in pharmacy and specialty nutrition channels.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise in natural flavor stabilization commands premium compensation, constraining mid-tier manufacturers from matching clean-label claims of market leaders.
- Legacy equipment retrofit costs:Transitioning spray-drying facilities to lower-temperature processing for heat-sensitive catechins requires capital outlays that strain private-label contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Tea Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Tea, Liquid Concentrate, Tea Bags, Instant Tea Premixes Flavor Profile: Green Tea, Black Tea, Herbal Infusions, Fruit Flavors Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores End User: Households, Restaurants, Cafés, Office Spaces |
| Companies Covered | Nestlé, Unilever, PepsiCo, The Coca-Cola Company, Ito En Ltd., Tata Consumer Products Limited, Starbucks Corporation, Ajinomoto General Foods Inc., Wagh Bakri Tea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Tea Market Shifts & Advancements
Cold-brew extraction methods and sustainable packaging substrates are reshaping competitive positioning, while regulatory pressure on sugar content and packaging waste accelerates format experimentation across developed markets.
Freeze-drying technology is rendering obsolete conventional spray-dried powders in premium household segments. Specialty retailers in Japan and South Korea are prioritizing shelf space for granules that dissolve at lower temperatures and retain volatile aromatic compounds. This preservation capability is compressing the quality gap between instant formats and loose-leaf brewing, forcing mid-market brands to upgrade processing investments or retreat to commodity positioning.
The EU's Farm to Fork Strategy under the EU Green Deal mandates ingredient sourcing transparency and packaging recyclability benchmarks for food and beverage products sold in member states. Manufacturers are reformulating around certified sustainable tea estates and piloting compostable pod materials to preempt non-compliance penalties. Northern European markets exhibit the strictest retailer enforcement, with German and Dutch chains delisting SKUs failing to meet extended producer responsibility thresholds.
Pantry-stockpiling behaviors normalized during the pandemic continue to favor online retail over impulse grocery purchases. Subscription platforms are displacing traditional supermarket restocking for routine consumables, with auto-replenishment algorithms reducing price sensitivity among enrolled households. This channel shift is most pronounced in American and British urban centers where delivery density supports free-shipping thresholds on bulk powder purchases.
Instant Tea Market Segmentation
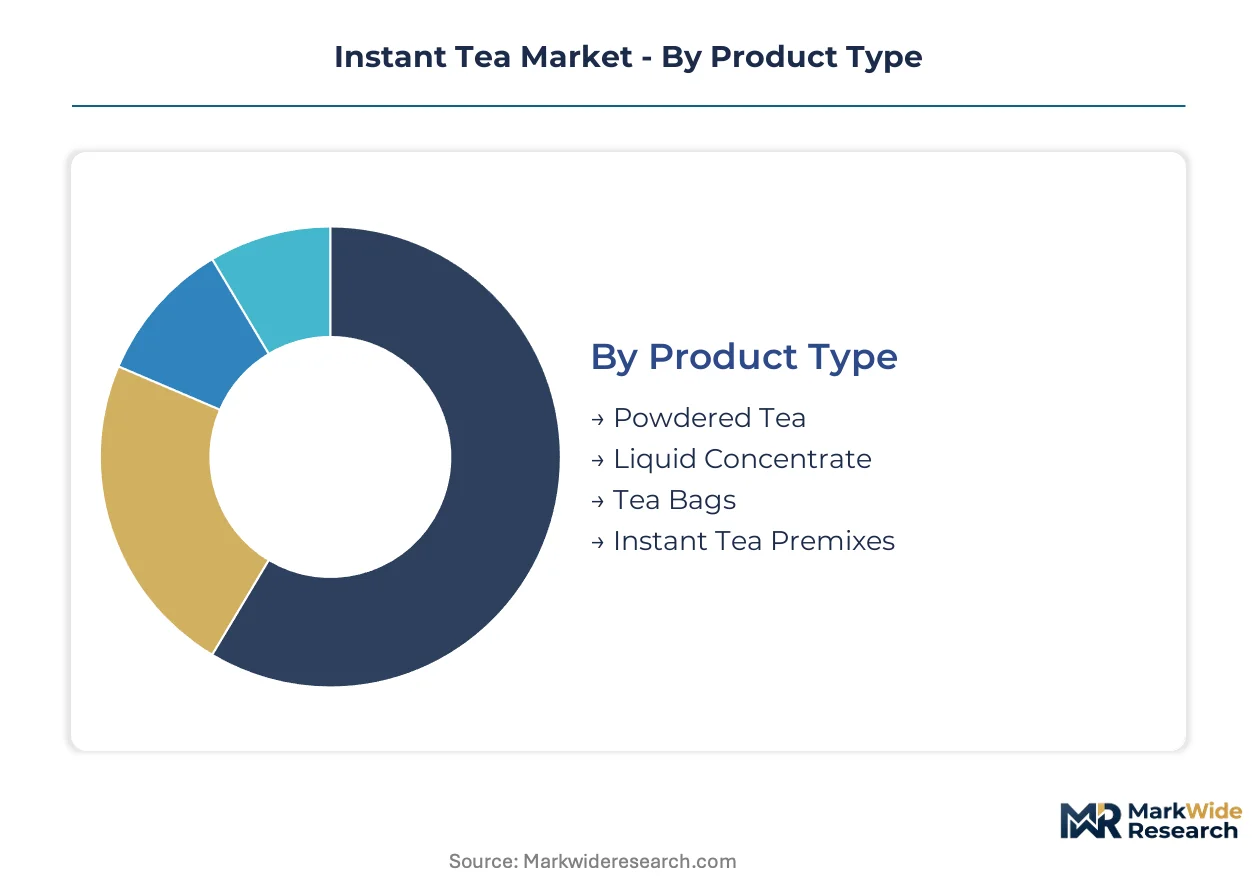
Instant tea manufacturers configure production lines and procurement strategies around four distinct segmentation axes. Product format determines capital intensity and shelf stability. Flavor positioning drives regional preference patterns. Channel selection dictates margin structure and brand control. End-user targeting shapes packaging formats and serving sizes.
Product Type:
Mature spray-drying infrastructure dominates powder manufacturing, while freeze-drying and liquid concentration represent emerging technology tiers with premium positioning.
- Powdered Tea:Spray-dried granules reconstitute in hot water with minimal residue, commanding manufacturing scale due to lower logistics cost per serving and extended ambient shelf stability. Demand concentrates in Indian kirana stores and American pantry-stockpiling households through bulk canister formats, though heat degradation of catechins constrains premium positioning.
- Liquid Concentrate:Hot-brew extraction followed by vacuum concentration preserves aromatic compounds at higher fidelity than dehydration methods, enabling foodservice speed-of-preparation advantages. North American office beverage programs and Japanese convenience stores drive procurement, where unit economics surrender to labor efficiency and portion control.
- Tea Bags:Single-serve sachets containing instant-dissolving granules bridge convenience and ritual, finding traction in European hotel in-room amenities and airline catering.
- Instant Tea Premixes:Pre-sweetened and dairy-integrated formulations target Southeast Asian street vending and automated dispensing machines in South Korean office towers.
Powdered tea handles the majority of throughput; liquid concentrate is the fastest mover on share.
Flavor Profile:
Cost tier segmentation separates commodity-grade black tea extracts from premium-positioned green tea and functional herbal blends.
- Green Tea:Unoxidized leaf processing retains higher epigallocatechin gallate concentrations, supporting wellness claims in pharmacy and specialty nutrition channels. Japanese household penetration remains deepest, where Ito En and Ajinomoto General Foods built decades of consumer loyalty around ready-to-drink tea culture extending into instant formats.
- Black Tea:Fully oxidized extracts deliver robust flavor profiles familiar to Western palates, anchoring volume in British and American supermarket aisles. Assam and Kenyan leaf sourcing exposes margins to monsoon rainfall volatility.
- Herbal Infusions:Rooibos, chamomile, and hibiscus variants capture caffeine-avoidant demographics through natural positioning and sleep-support claims.
- Fruit Flavors:Mango, peach, and passionfruit infusions target younger demographics in Western markets through social media-driven trial and seasonal limited releases.
Black tea handles the majority of throughput; fruit flavors are expanding most quickly.
Distribution Channel:
Volume concentration in legacy retail conflicts with margin expansion through direct-to-consumer routes and quick-commerce platforms.
- Supermarkets:Mass merchandisers and grocery chains still occupy the largest volume share, leveraging established beverage aisle traffic and promotional slotting fees to maintain brand visibility.
- Online Retail:Auto-replenishment algorithms and subscription platforms reduce price sensitivity among enrolled households, with delivery density in American and British urban centers supporting free-shipping thresholds on bulk powder purchases.
- Convenience Stores:Impulse-oriented single-serve sachets and ready-to-drink adjacent liquid concentrates capture trial occasions in Japanese convenience stores and American gas stations.
- Specialty Stores:Premium freeze-dried granules and ceremonial-grade matcha powders command shelf space in Japanese and South Korean specialty retailers prioritizing sensory quality.
Supermarkets handle the majority of throughput; online retail is gaining share fastest.
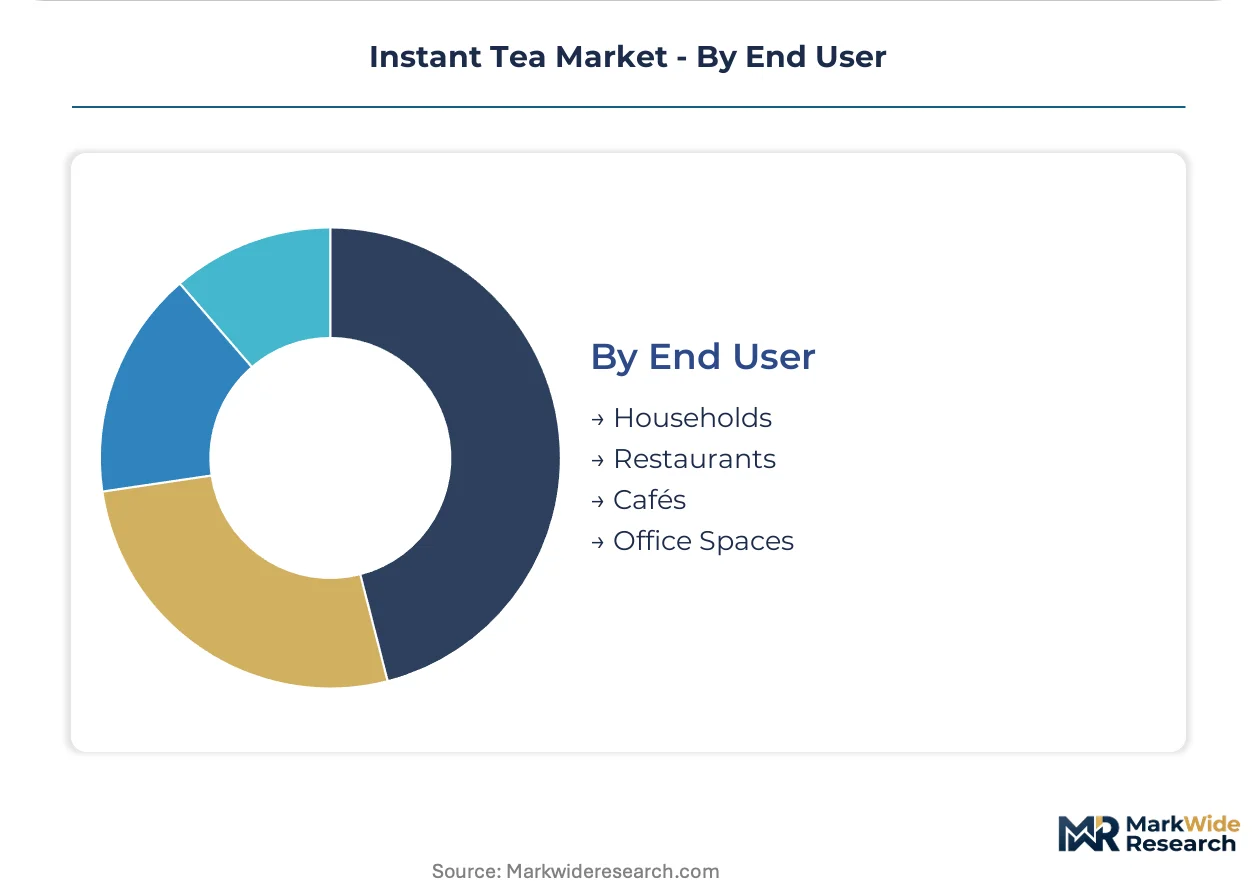
End User:
Customer type segmentation differentiates household replenishment cycles from foodservice procurement patterns and workplace amenity programs.
- Households:Pantry-stockpiling behaviors normalized post-pandemic favor bulk canister formats and subscription replenishment over impulse purchasing.
- Restaurants:Back-of-house speed requirements drive liquid concentrate adoption in casual dining chains, though specialty tea houses maintain loose-leaf brewing for experience differentiation.
- Cafés:Third-wave coffee culture spillover elevates expectations for single-origin instant tea extracts in premium café chains.
- Office Spaces:Workplace beverage programs across North America and Europe normalize pod-based tea consumption during business hours, expanding procurement of single-serve formats for employee amenity packages.
Households handle the majority of throughput; office spaces show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium freeze-dried formats command 40% price premiums in Japanese specialty channels versus commodity spray-dried powders dominating Indian mass retail, creating a two-tier pricing architecture that manufacturers navigate through format-specific production investments.
United States
Workplace beverage programs and pantry-stockpiling behaviors drive single-serve pod and bulk powder procurement through subscription platforms. FDA nutrition labeling mandates on added sugars force reformulation toward clean-label concentrates. Dark-store networks in New York and Chicago enable sub-15-minute delivery of instant tea sachets through quick-commerce platforms.
Japan
Decades of consumer loyalty around ready-to-drink tea culture extend into premium freeze-dried granule segments. METI standards govern food labeling and quality benchmarks for domestic manufacturers. Specialty retailers in Tokyo and Osaka prioritize shelf space for cold-brew extraction products that retain volatile aromatic compounds.
India
Deep distribution through kirana stores and modern trade anchors South Asian demand for powdered tea in bulk canister formats. FSSAI standards and BIS certification requirements govern product claims and quality benchmarks. Processing clusters in Gujarat and Maharashtra concentrate spray-drying capacity for domestic and export markets.
Germany
Strict retailer enforcement of EU Green Deal extended producer responsibility thresholds drives compostable pod material pilots. The Farm to Fork Strategy mandates ingredient sourcing transparency for products sold in member states. Northern European distribution hubs in Hamburg and Rotterdam prioritize SKUs meeting regenerative tea sourcing benchmarks.
United Kingdom
Auto-replenishment algorithms reduce price sensitivity among subscription-enrolled households in London and Birmingham urban centers. Post-pandemic pantry-stockpiling behaviors continue favoring online retail over impulse grocery purchases. British supermarket chains negotiate promotional slotting fees to maintain brand visibility in established beverage aisles.
Instant Tea Market Competitive Landscape
Multinational beverage conglomerates and regional tea specialists split the market between scale-driven commodity powder production and premium-positioned freeze-dried segments. The vendor base concentrates around three strategic archetypes: diversified food-and-beverage majors leveraging cross-category infrastructure, dedicated tea processors with captive sourcing relationships, and private-label contract manufacturers serving retail channel brands. Dominant competitive moves include backward integration into tea estate sourcing and technology licensing agreements for low-temperature dehydration processing.
Within the diversified multinational tier, Nestlé and Unilever exemplify cross-merchandising strategies that deploy instant tea through established subscription and retail channels. Tata Consumer Products Limited anchors the regional specialist archetype with India-centric distribution depth. PepsiCo occupies a position bridging ready-to-drink adjacencies and concentrate formats through beverage logistics networks.
| Leading Market Players |
|---|
| Nestlé |
| Unilever |
| PepsiCo |
| The Coca-Cola Company |
| Ito En Ltd. |
| Tata Consumer Products Limited |
| Starbucks Corporation |
| Ajinomoto General Foods Inc. |
| Wagh Bakri Tea Group |
| Others |
Supply & Pricing Matrix
Guangdong province's spray-drying capacity concentration grants toll processors outsized leverage over powder-format producers, translating upstream equipment scarcity into premium pricing for contract manufacturing slots during peak procurement seasons.
Pricing Analysis
Configured-to-order pricing for custom flavor profiles and private-label formulations commands spreads of 35-50% above standard catalog pricing for off-the-shelf extracts. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy-grade concentrates segments buyers by quality tolerance and application requirements. Pricing pressure stems from monsoon-driven Assam leaf cost volatility squeezing margin pools for black tea extractors locked into annual procurement contracts. Foodservice channels exhibit lowest price sensitivity due to labor-cost arbitrage from speed-of-preparation advantages, while Indian kirana store distributors negotiate aggressively on bulk powder volumes.
Supply Chain Analysis
Tariff exposure between China and North American markets dominates supply chain risk calculus for powder-format producers dependent on Guangdong toll processing capacity. Tea leaf sourcing concentrates in Assam, Kenya, and Sri Lanka for black tea extracts, while Japanese and Chinese estates anchor green tea supply. Raw material dependencies rest on rainfall-sensitive orthodox leaf grades, natural flavor stabilizers, and compostable pod substrate innovations. Single-source vulnerability in spray-drying equipment manufacturing creates bottleneck risk for capacity expansion. Distribution runs through diversified routes: direct-to-pantry subscriptions in American urban centers, kirana store networks across Indian states, and quick-commerce dark stores in Southeast Asian megacities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instant tea formats are becoming a service-attach opportunity as subscription replenishment algorithms and workplace beverage program management contracts expand faster than standalone product sales.
For Market Incumbents: Insulate core powder volumes through backward integration into Assam and Kenyan estate sourcing to neutralize leaf price volatility, while accelerating freeze-drying capacity additions in Gujarat and Maharashtra to capture premium positioning before mid-tier competitors upgrade equipment. FDA sugar labeling mandates and EU Green Deal packaging requirements threaten private-label contract manufacturers unable to fund compliance investments. For New Entrants and Emerging Players: Southeast Asian quick-commerce corridors in Jakarta, Bangkok, and Ho Chi Minh City offer underpenetrated routes for sub-15-minute delivery of functional tea-adaptogen blends targeting pharmacy and specialty nutrition channels. Foodservice liquid concentrate white space in European casual dining chains presents the most penetrable application, with speed-of-preparation advantages justifying premium unit economics against loose-leaf alternatives. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because spray-drying equipment scarcity and flavor chemist talent shortages will drive mid-tier contract manufacturers toward distressed sale scenarios. Acquisition targets should exhibit captive estate relationships or patented low-temperature extraction licenses. The signal to watch is BIS and FSSAI enforcement tightening on import quality benchmarks, which would accelerate compliance-cost driven exits among non-compliant regional processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Estate Sourcing | Captive Assam and Kenyan leaf supply neutralizes monsoon-driven input cost volatility for extractors. |
| Freeze-Drying Capacity Expansion | Low-temperature processing preserves catechins and aromatic compounds for Japanese and South Korean specialty retail placement. |
| Compostable Pod Material Pilots | EU Green Deal extended producer responsibility thresholds in Germany and the Netherlands reward early compliance with preferential shelf access. |
| Quick-Commerce Dark Store Penetration | Sub-15-minute delivery networks in urban India and Southeast Asia capture pantry-replenishment occasions from traditional grocery. |
| Functional Ingredient Convergence | Adaptogen and nootropic marriage with tea extracts opens wellness-positioned SKUs in pharmacy channels beyond conventional beverage aisles. |
Research Methodology
A standing panel of brand managers at multinational beverage conglomerates, category buyers at British and German supermarket chains, procurement leads at North American foodservice distributors, and plant engineers at Gujarat spray-drying facilities provided ongoing calibration against operating reality. Primary interview insights combined with secondary validation from FSSAI compliance filings, BIS certification records, EU Farm to Fork Strategy implementation guidance, and customs trade data on tea extract imports. Bottom-up volume triangulation across product formats, flavor profiles, and distribution channels reconciled against top-down macroeconomic drivers.
Scenario-bracketing around rainfall volatility in Assam, regulatory enforcement timing in the EU, and quick-commerce penetration rates in Southeast Asia bounded the projection range. Segmentation dimensions modeled include product type, flavor profile, distribution channel, and end-user category across the analysis window. CAGRs derived from trend extrapolation of historical volume shifts, adjusted for structural breaks in pantry-stockpiling behavior and workplace consumption normalization. Forecast inputs incorporated tea leaf futures pricing patterns and freeze-drying equipment capacity utilization rates.
Practitioners should monitor monsoon forecasts for Assam and Kenya, EU packaging waste directive enforcement actions, and FDA added-sugar labeling compliance deadlines for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Tea Infuser Market
Tea
Tea Packaging Market
Tea
Asia-Pacific Organic Tea Market
Tea
Tea Pitchers Market
Tea
Green Tea Market
Tea
Tea Concentrate Market
Tea
Global Catechin Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Rooibos Tea Market
Tea
White Tea Market
Tea
Global Fruit Tea Market
Tea
Matcha Products Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Europe Tea Market