
 Ink Additives Market | 2026-2036
Ink Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Ink Additives Market Analysis
Specialty formulation services is reshaping margin capture in the ink additives value chain. BASF SE leverages its integrated pigment-additive portfolio to control raw material quality from monomer to finished dispersant. Evonik Industries AG anchors its position through silicone-based surface modifiers that command premium pricing in high-speed flexographic applications. ALTANA AG specializes in effect pigment and additive combinations for decorative packaging segments where visual differentiation sustains pricing power.
Ink additives comprise functional chemicals—typically surfactants, dispersants, rheology modifiers, and defoamers—incorporated at 0.5–5.0 wt% to control viscosity, wetting, drying speed, and substrate adhesion in printing ink formulations. These additives determine print fidelity, production line efficiency, and regulatory compliance across solvent-based, water-based, and UV-curable ink systems. Dispersants dominate product-type value pools because pigment stability directly impacts color consistency and shelf life in concentrated base inks. Liquid forms lead volume shipments due to ease of incorporation in continuous manufacturing, though powder grades gain traction in powder-to-liquid blending operations for regional ink compounders. Packaging absorbs the largest end-use share as brand owners specify migration-compliant additives for direct food-contact films and folding cartons.
FDA indirect food contact regulations and EU REACH restrict specific phthalate plasticizers and heavy metal pigments, forcing reformulation toward bio-based dispersants and mineral oil-free defoamers. EPA VOC emission limits for commercial printing operations in the United States accelerate water-based and UV ink adoption, which in turn demands specialized silicone and polymeric surfactants with distinct compatibility profiles. Stakeholders must monitor regulatory divergence between jurisdictions, as additive approvals granted under FDA or EMA frameworks do not automatically transfer to China's NMPA or India's BIS standards, complicating global product line management.
Market Dynamics
Migration from solvent-based to water-based and UV-curable ink systems is compressing formulation windows and forcing additive suppliers to rebuild compatibility matrices around silicone surfactants and bio-derived dispersants.
Growth Catalysts
- EPA VOC emission limits:Commercial printing operations in the United States face tightening volatile organic compound caps, accelerating water-based ink adoption and specialized surfactant demand.
- Flexible packaging converters:Asia-Pacific converters are expanding additive procurement for solvent-free ink systems to meet brand owner sustainability specifications.
- REACH compliance trajectory:ECHA restrictions on phthalate plasticizers and heavy metal pigments force reformulation toward mineral oil-free defoamers and bio-based dispersants across European ink manufacturing.
Market Restraints
- Petrochemical feedstock volatility:Silicone intermediate and acrylic monomer prices swing with crude oil indices, compressing margin predictability for surfactant and rheology modifier producers.
- Regulatory fragmentation:FDA indirect food contact approvals do not automatically transfer to China's NMPA or India's BIS standards, forcing parallel certification tracks for global product lines.
- Performance ceiling in high-speed flexography:Water-based systems still lag solvent-based inks in drying speed on non-porous films, limiting full substitution in premium packaging segments.
Strategic Opportunities
- India's packaging production expansion:Domestic folding carton and flexible film manufacturing clusters in Gujarat and Maharashtra are localizing additive sourcing to reduce import dependency.
- UV-LED curing convergence:Narrower wavelength emission profiles demand photoinitiator-additive co-formulation services, opening specialty service revenue pools.
- EU Green Deal chemistry incentives:Bio-based dispersant development receives accelerated regulatory review and public procurement preference under sustainable chemistry frameworks.
Industry Challenges
- Formulation chemist scarcity:Expertise in silicone-polymer compatibility and pigment surface chemistry concentrates at mid-career levels, creating recruitment bottlenecks for regional ink compounders.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and NMPA food contact additive approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ink Additives Market |
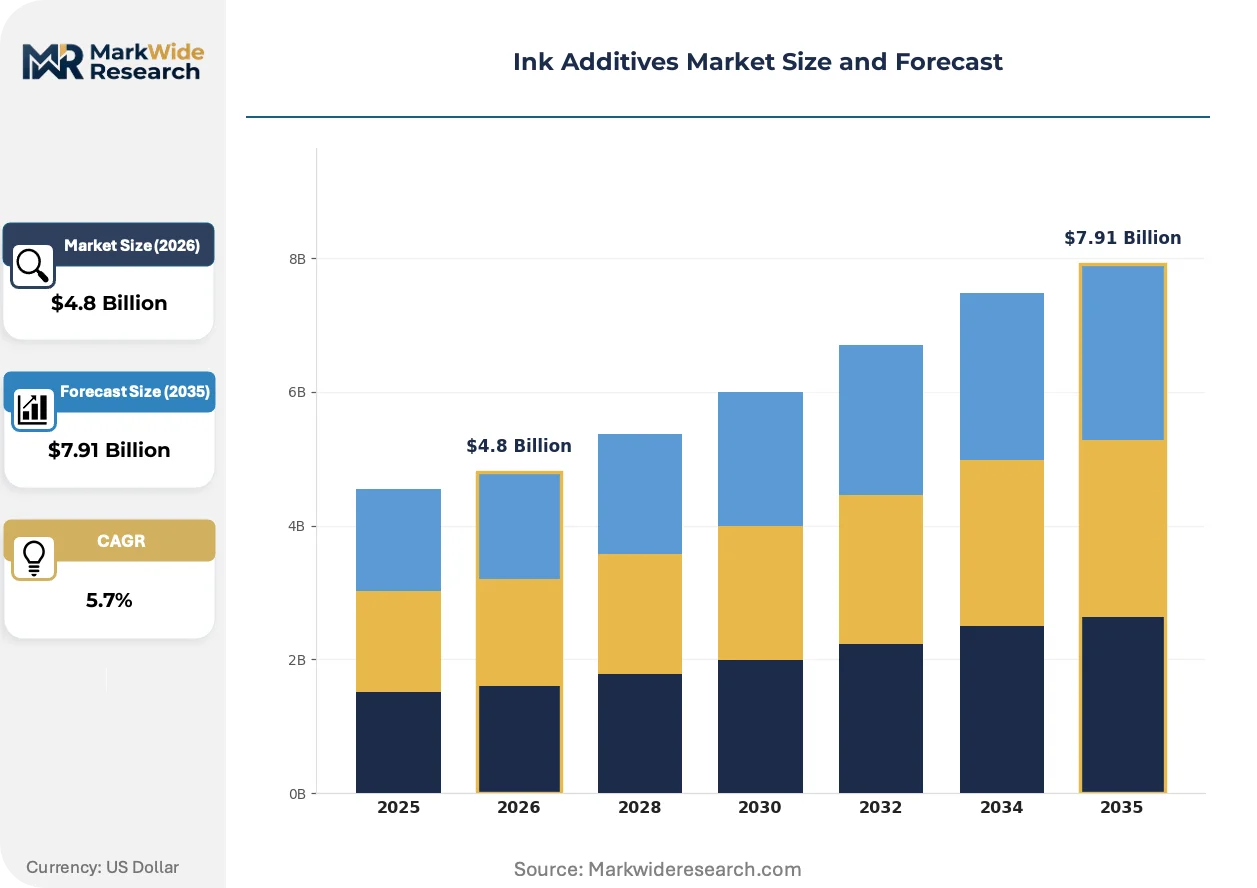
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colorants, Dispersants, Resins, Surfactants End Use Industry: Packaging, Commercial Printing, Home Decor, Textile Form: Liquid, Powder, Gel, Paste Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesalers |
| Companies Covered | BASF SE, Evonik Industries AG, ALTANA AG, Elementis plc, Dow Corning, Shamrock Technologies, Harima Chemicals Group, Lubrizol, Munzing Chemie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ink Additives Market Emerging Trajectories
Digital formulation platforms and predictive compatibility modeling are compressing R&D cycles while regulatory chemistry restrictions force step-changes in bio-based additive architectures.
Silicone-polyether block copolymer surfactants are virtualizing traditional hydrocarbon-based wetting agents in high-speed flexographic applications. Folding carton converters in Germany and the United States are adopting these modifiers at pilot scale to achieve substrate wetting at water-based viscosity levels previously unattainable. The technology is virtualizing legacy surfactant supply relationships by enabling ink compounders to source directly from specialty silicone houses rather than through integrated pigment-additive distributors.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated surfactants from food-contact ink formulations by 2026. European ink manufacturers are reformulating with hydrocarbon and silicone alternatives that sacrifice some grease resistance but meet migration limits. Premium dairy and meat packaging segments in France and Germany are absorbing the highest compliance costs as they transition laminated structures to PFAS-free barrier systems.
Brand owner specification of migration-compliant additives is compressing supplier qualification cycles from annual reviews to batch-level certification. Large flexible packaging converters in China and India are unbundling after-sales technical service from product supply, sourcing additives through distributors while retaining formulation troubleshooting in-house. This pattern is most visible in direct food-contact film applications where retailer audit requirements demand documented additive traceability.
Ink Additives Market Segmentation
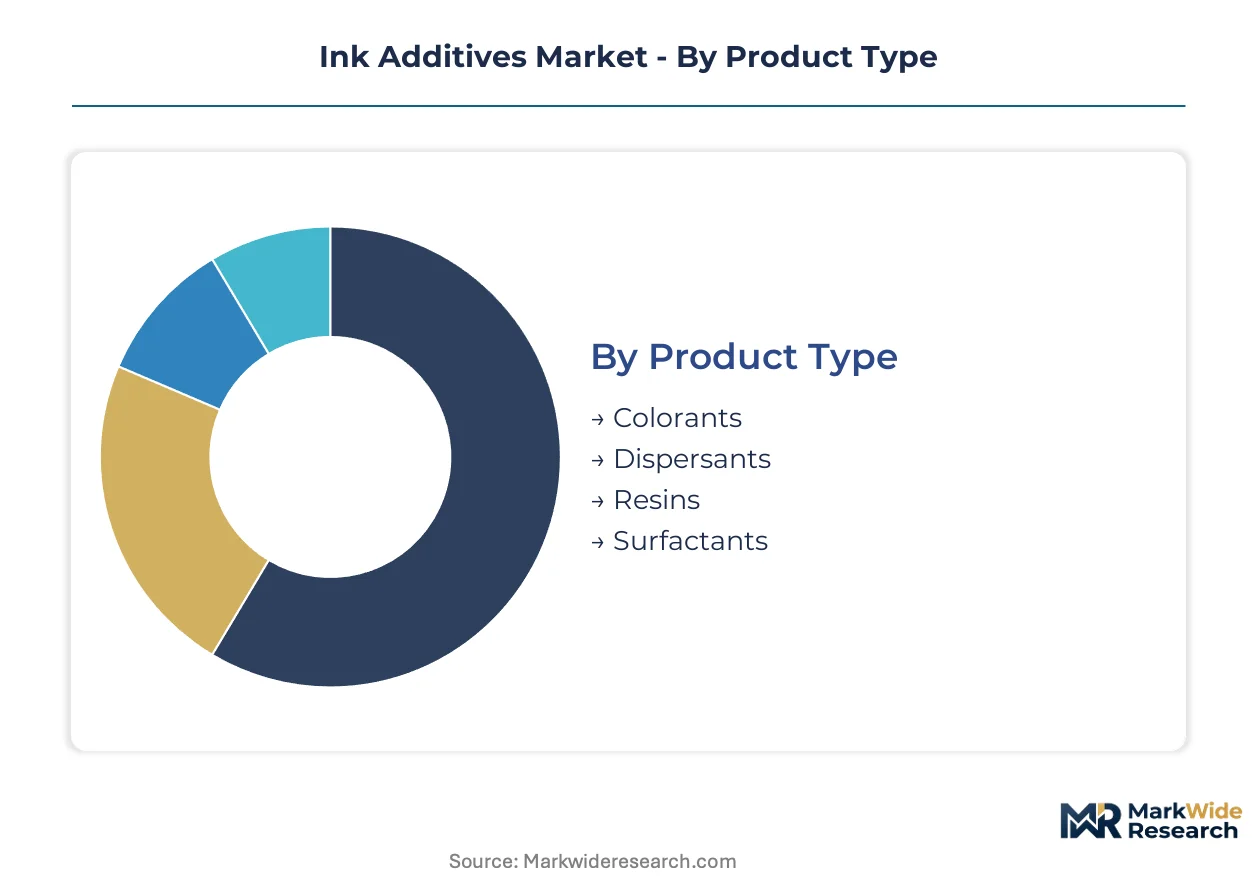
Segmentation in ink additives reflects divergent technical requirements across formulation chemistries and end-use compliance regimes. Additive selection varies sharply by ink system compatibility, regulatory exposure, and incorporation method in continuous manufacturing.
Product Type:
Functional chemistry determines formulation hierarchy and margin capture across pigment stabilization and flow control applications.
- Dispersants:Polymeric and surfactant-based systems anchor pigment stability in concentrated base inks, with demand concentrating in flexible packaging converters across Germany and China seeking migration-compliant grades for food-contact films.
- Resins:Acrylic, polyurethane, and nitrocellulose variants govern film formation and substrate adhesion, with water-based resin demand climbing fastest in folding carton applications subject to EPA VOC emission limits.
- Surfactants:Silicone-polyether block copolymers and hydrocarbon wetting agents control surface tension in high-speed flexographic presses.
- Colorants:Organic and inorganic pigments provide optical density, with heavy metal-free grades mandated under REACH Annex XVII restrictions.
Dispersants hold installed capacity. Resins are rotating up the share rankings.
End Use Industry:
Regulatory exposure and substrate complexity segment demand across consumer-facing and industrial applications.
- Packaging:Flexible film and folding carton converters specify migration-compliant additives for direct food-contact applications, with procurement concentrating in India and China as domestic manufacturing clusters localize supply chains.
- Commercial Printing:Sheet-fed and web offset operations prioritize drying speed and rub resistance, with UV-curable ink adoption accelerating specialized photoinitiator-additive co-formulation demand.
- Textile:Digital and rotary screen printing on synthetic and natural fibers requires dispersants compatible with high-temperature fixation processes.
- Home Decor:Wallpaper and decorative laminate applications emphasize color consistency across batch production.
Packaging dominates current formulation volumes. Commercial Printing is gaining share fastest as UV-LED curing penetrates premium segments.
Form:
Physical state governs incorporation efficiency and supply chain configuration for regional compounders versus integrated manufacturers.
- Liquid:Pumpable concentrates enable continuous manufacturing with minimal dust exposure, with demand anchored in high-volume solvent-free ink systems across Asia-Pacific flexible packaging operations.
- Powder:Free-flowing grades support powder-to-liquid blending at regional ink compounders, with adoption climbing in India and China as domestic producers seek import substitution for dispersant intermediates.
- Gel:Thixotropic systems provide controlled viscosity in high-solids UV ink formulations.
- Paste:Semi-solid concentrates suit small-batch decorative and specialty color matching.
Liquid forms command current shipment volumes. Powder is climbing the fastest as regional compounding capacity expands.
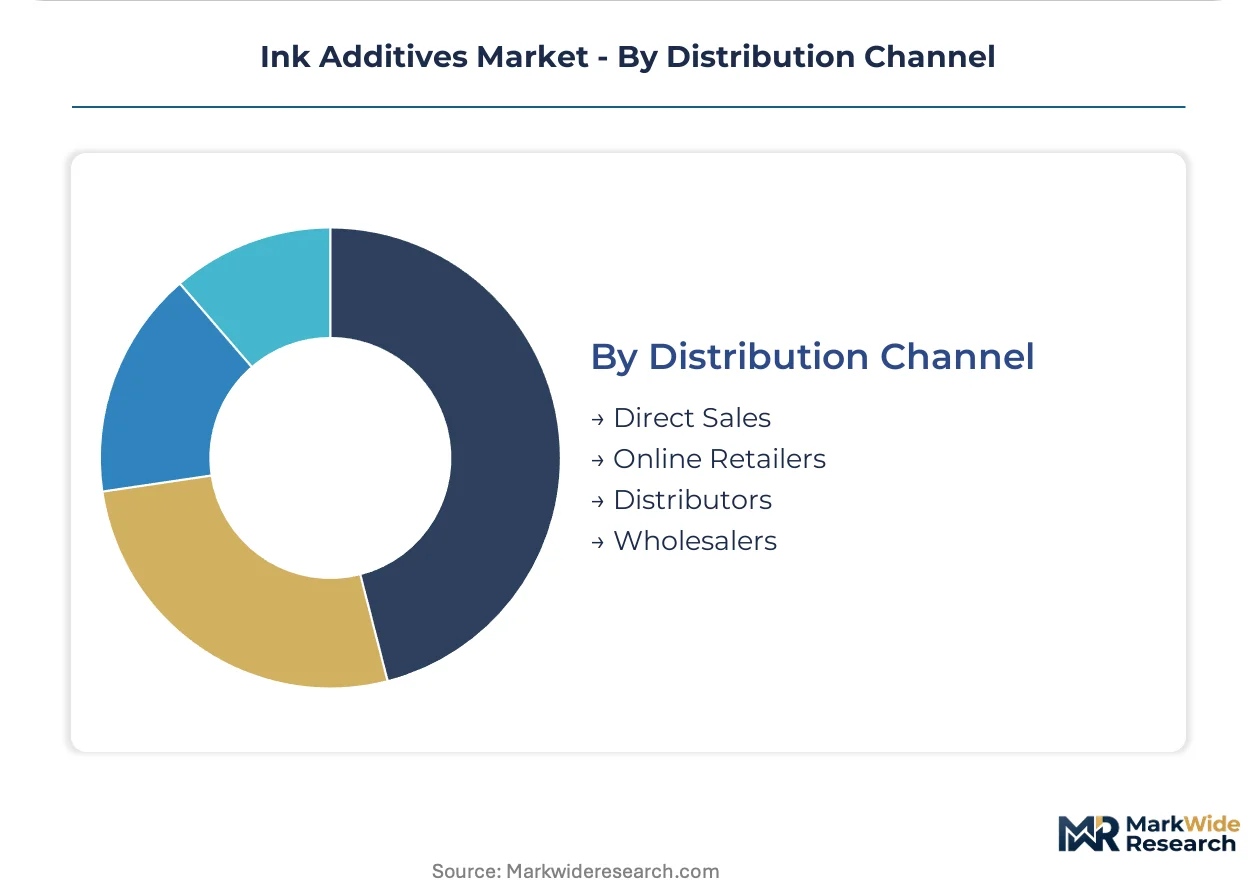
Distribution Channel:
Channel selection reflects technical service intensity and certification documentation requirements for food-contact applications.
- Distributors:Technical specialists provide formulation troubleshooting and batch-level certification documentation, with demand concentrating in China and India where converters unbundle after-sales service from product supply.
- Direct Sales:Integrated pigment-additive suppliers capture premium accounts through captive raw material quality control from monomer to finished dispersant.
- Online Retailers:Standardized grades for non-food-contact applications move through digital procurement platforms.
- Wholesalers:Volume aggregation serves mid-tier ink compounders with predictable consumption patterns.
Distributors hold established relationships. Direct Sales is rotating up the share rankings as integrated suppliers deepen technical partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical manufacturing for ink additives clusters in Germany, China, India, and the United States, with each hub serving distinct regulatory and formulation requirements across solvent-based, water-based, and UV-curable systems.
China
Flexible packaging converters in Guangdong and Zhejiang provinces are scaling solvent-free ink production to meet brand owner sustainability mandates. NMPA food contact additive approvals operate on parallel tracks to FDA and EFSA frameworks, complicating export qualification for domestic manufacturers. The Yangtze River Delta hosts concentrated dispersant production serving both regional ink compounders and multinational formulators.
Germany
REACH Annex XVII restrictions on PFAS and heavy metal pigments are forcing reformulation of food-contact inks by 2026. Folding carton manufacturers in Baden-Württemberg and North Rhine-Westphalia are piloting silicone-polyether surfactants to achieve water-based performance parity with solvent systems. BASF SE and ALTANA AG anchor integrated supply chains from monomer synthesis to finished additive distribution.
United States
EPA VOC emission limits for commercial printing operations in California and the Northeast are accelerating water-based and UV ink conversion. FDA indirect food contact rules govern additive selection for direct-contact flexible films, with batch-level certification now standard for major converters. The Great Lakes region maintains legacy solvent-based capacity while coastal markets lead regulatory-driven formulation shifts.
India
Domestic packaging production expansion in Gujarat and Maharashtra is localizing additive sourcing to reduce import dependency on European and Chinese suppliers. BIS standards for food contact materials operate independently from FDA and EFSA approvals, requiring parallel certification investments. Regional ink compounders are unbundling technical service from product supply, sourcing dispersants through distributors while retaining formulation expertise in-house.
Japan
High-speed flexographic printing for premium packaging maintains stringent performance specifications that favor silicone-based surface modifiers. METI chemical management frameworks align with REACH restrictions while maintaining distinct approval timelines for novel additives. The Kansai region concentrates specialty surfactant production serving both domestic converters and export markets across Southeast Asia.
Ink Additives Market Vendor Landscape
Integrated chemical conglomerates and specialty additive specialists split the market across formulation complexity tiers. Three to five multinational suppliers control premium dispersant and surfactant value pools through captive raw material positions, while regional compounders and distributors serve mid-tier ink manufacturers with standardized grades. Strategic moves concentrate on backward integration into silicone intermediates and acrylic monomers, plus geographic expansion through distributor partnerships in India and Southeast Asia.
Within the integrated chemical tier, BASF SE, Evonik Industries AG, and ALTANA AG occupy positions defined by portfolio breadth and raw material control. BASF SE exemplifies the pigment-additive integration archetype, Evonik Industries AG anchors silicone-based surface modification expertise, and ALTANA AG represents the effect pigment-additive combination specialist serving decorative packaging segments. These three German-origin entities sit alongside Elementis plc and Dow Corning as reference points for formulation service intensity and regulatory compliance depth.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| ALTANA AG |
| Elementis plc |
| Dow Corning |
| Shamrock Technologies |
| Harima Chemicals Group |
| Lubrizol |
| Munzing Chemie GmbH |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor anchors cost dynamics for silicone intermediate and acrylic monomer shipments, compressing margins for European surfactant producers while enabling Chinese dispersant manufacturers to undercut on delivered price. This freight-cost asymmetry concentrates procurement power among Asia-Pacific flexible packaging converters and forces Western additive suppliers to differentiate through certification-grade premiums rather than volume scale.
Pricing Analysis
REACH compliance and FDA indirect food contact rules dictate the pricing tier structure across the ink additives market. Three-tier pricing separates migration-certified grades for direct food-contact films from standard industrial formulations and economy-grade defoamers for non-regulated applications. Price differentiation rests on batch-level certification documentation and silicone-polyether block copolymer performance premiums. Pricing pressure stems from petrochemical feedstock volatility in acrylic monomer and silicone intermediate markets. Mid-tier ink compounders in India and China exhibit highest price sensitivity, while German folding carton converters absorb premiums for REACH-compliant dispersants.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement relationships between Chinese dispersant producers and Asia-Pacific flexible packaging converters, straining working capital for regional compounders. Supply concentrates in China, Germany, and India for dispersant intermediates, with silicone surfactant production anchored in Japan and the United States. Raw material dependencies center on petrochemical-derived acrylic monomers, silicone intermediates from quartz processing, and bio-based feedstocks for mineral oil-free defoamers. Single-source vulnerability runs through Yangtze River Delta dispersant clusters exposed to environmental compliance shutdowns. Distribution runs through technical specialist distributors in China and India, with direct sales dominating German and United States premium accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based and UV-curable ink conversion sits in early-cycle expansion as EPA VOC limits and EU REACH restrictions force formulation architecture changes. This regulatory tailwind creates asymmetric opportunity for additive suppliers with pre-certified migration-compliant portfolios.
For Market Incumbents: Pre-empt silicone-polyether surfactant supply constraints by securing captive backward integration into silicone intermediate production or long-term offtake agreements with German and Japanese specialty chemical houses. Defend distributor relationships in India and China through embedded technical service teams that ink compounders cannot replicate in-house. Regulatory divergence between FDA, EFSA, and NMPA frameworks threatens margin capture for suppliers lacking parallel certification infrastructure.
For New Entrants and Emerging Players: Mid-market water-based ink compounders in Gujarat and Maharashtra represent the most penetrable entry point, as these regional producers seek import substitution for European dispersants while lacking in-house formulation expertise. UV-LED curing additive co-formulation services for commercial printing operations in the United States offer a second white-space target with premium pricing potential. A technical partnership model with existing distributor networks bypasses capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: Specialty silicone surfactant houses with established photoinitiator compatibility expertise offer the strongest acquisition profile for the UV-LED curing convergence. Long-term viability hinges on regulatory chemistry restrictions accelerating bio-based dispersant development timelines. The signal to watch is batch-level certification documentation becoming standard contract terms in Chinese flexible packaging procurement, indicating irreversible compliance premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Captive supply of polyether raw materials secures margin control against petrochemical volatility. |
| Parallel Certification Investment | Simultaneous FDA, EFSA, and NMPA approvals compress product launch cycles for global ink formulators. |
| Regional Compounding Partnership | Joint ventures with Gujarat and Maharashtra ink producers localize supply chains for India's packaging expansion. |
| UV-LED Co-Formulation Service Launch | Photoinitiator-additive technical services capture premium pricing in commercial printing segments. |
| Bio-Based Dispersant R&D Program | EU Green Deal chemistry incentives accelerate regulatory review timelines for sustainable alternatives. |
Methodological Framework
Desk research of trade flow databases, customs records, and ECHA regulatory filings preceded structured interviews with ink formulation chemists, flexible packaging procurement managers, and specialty chemical distribution executives. Primary fieldwork captured formulation compatibility requirements and certification documentation practices across solvent-based, water-based, and UV-curable systems. Secondary validation drew from SEC 10-K filings of integrated chemical conglomerates, Cefic industry reports, and FDA food contact substance notifications. Bottom-up additive consumption estimates triangulated against top-down ink production volume data.
Assumptions held fixed include REACH Annex XVII enforcement timelines, EPA VOC emission limit trajectories, and NMPA food contact additive approval frameworks. Variables modeled across the analysis window encompass water-based ink penetration rates, UV-LED curing adoption curves, and regional packaging production growth. Segmentation dimensions included functional chemistry type, ink system compatibility, regulatory exposure tier, and physical incorporation form. CAGRs derived from regression analysis of historical additive intensity ratios applied to projected ink formulation volumes, with cross-checks against plant capacity announcements and distributor inventory patterns.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, maritime freight rates, or currency exchange volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Zink Printing Market
Printing Inks
Printing Plate Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Radiation Curable Inks Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
North America Printing Inks Market
Printing Inks
Offset Ink Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Low-Odor Inkjet Inks for On-Line Food Coding in Aseptic Filling Market
Printing Inks
Water-Based Metal-Deco Beverage Can Inks Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Non-Conductive Ink Market