
 Copier, MFP and Printer Market | 2026-2036
Copier, MFP and Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Copier, MFP and Printer Market Insights
REACH compliance is decoupling low-cost assembly from profitable market participation in the European Union. HP Inc. leverages its captive ink supply chain to sustain margin control across enterprise contracts. Canon Inc. anchors its position through in-house optical engine manufacturing that competitors struggle to replicate. Brother Industries Ltd. specializes in compact desktop units that dominate home-office replenishment cycles.
Copiers, MFPs, and printers constitute electrophotographic and inkjet output devices that fuse toner or deposit pigment onto substrates at resolutions typically ranging from 600 to 2400 dots per inch, serving document reproduction, archival, and transactional communication needs across organizations. Laser printers and multifunction printers together command the dominant installed base, though inkjet technology captures faster refresh rates in photo-specialist and wide-format niches where piezoelectric heads enable variable droplet precision. LED technology segments are maturing in high-speed monochrome fleets where thermal limits constrain arc lamp alternatives, while impact technology persists in point-of-sale and logistics environments requiring multi-part forms.
The EPA Energy Star program in the United States and the EU Ecodesign Directive collectively enforce standby power thresholds and cartridge recyclability standards that OEMs must embed at the design stage. China's MIIT publishes GB standards for electromagnetic compatibility and toner safety that gate access to public procurement tenders. Stakeholders should monitor how right-to-repair legislation evolves across jurisdictions, as spare parts availability mandates could reshape aftermarket revenue models faster than hardware refresh cycles.

Market Dynamics
Hybrid work permanence is fragmenting print volumes across distributed endpoints, forcing hardware economics toward lower-duty-cycle devices and cloud-managed fleet services rather than centralized high-volume installations.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits and cartridge recyclability standards accelerate OEM refresh cycles as manufacturers redesign portfolios to retain market access.
- Educational infrastructure:Public sector modernization programs in India, China, and the United States drive replacement demand for managed print services in K-12 and university systems.
- Piezoelectric inkjet heads:Variable droplet precision technology captures photo-specialist and wide-format niches where laser thermal constraints limit competitive response.
Market Restraints
- Toner resin supply concentration:Specialty polymer feedstocks for electrophotographic drums cluster among Japanese and German chemical suppliers, exposing OEMs to input cost volatility.
- REACH substance restrictions:ECHA authorization requirements for chromium compounds in photoconductor coatings force reformulation timelines that lag hardware development cycles.
- Digital document substitution:Electronic signature platforms and cloud-based collaboration tools compress transactional print volumes in corporate legal and financial workflows.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing attract component localization investments that reduce import duty exposure on optical engines.
- Right-to-repair mandates:Spare parts availability legislation across multiple jurisdictions creates aftermarket service revenue streams independent of hardware refresh cadence.
- AI-driven predictive maintenance:Machine learning integration with printer fleet telemetry enables proactive consumable replenishment and reduces customer downtime incidents.
Industry Challenges
- Firmware security certification:Common Criteria and FIPS 140-2 validation timelines for government and financial sector deployments extend product launch windows by 8-14 months.
- Legacy MFP integration:Cloud-native document management platforms require middleware development to bridge proprietary job description languages in installed base equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copier, MFP and Printer Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $240.53 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Printers, Inkjet Printers, Multifunction Printers, Dot Matrix Printers Technology: LED, Thermal Inkjet, Piezoelectric, Impact End User: Corporate Offices, Educational Institutions, Retail Stores, Government Agencies Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | HP Inc., Canon Inc., Seiko Epson Corporation, Brother Industries Ltd., Ricoh Company Ltd., Xerox Corporation, Kyocera Corporation, Konica Minolta Inc., Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copier, MFP and Printer Market Trends and Innovations
Active developments across hardware architecture, regulatory compliance frameworks, and service delivery models are compressing traditional product lifecycles while expanding addressable use cases beyond conventional document reproduction.
LED printhead arrays are integrating into high-speed monochrome fleets where thermal management constraints limit arc lamp alternatives, enabling compact chassis designs that reduce shipping costs and warehouse footprint. Enterprise fleet managers in logistics and legal verticals adopt these configurations for 60-90 page-per-minute departmental installations. The technology is integrating downstream control over fuser temperature profiles, extending component longevity and reducing service dispatch frequency.
REACH substance authorization procedures are tightening scrutiny of photoconductor drum coatings containing hexavalent chromium compounds, compelling OEMs to accelerate alternative charge transport layer formulations. ECHA's sunset date enforcement creates binary market access conditions where non-compliant hardware faces automatic withdrawal from EU distribution channels. High-volume production lines in electrophotographic manufacturing absorb the bulk of compliance engineering resources, delaying specialty product introductions.
Subscription-based page-per-print contracts are displacing capital equipment purchases in mid-market corporate accounts, transferring ownership risk to manufacturers while locking in multi-year consumable commitments. Channel partners in North America and Western Europe restructure compensation models around service annuity rather than hardware margin. Legal and healthcare verticals exhibit the fastest contract velocity, driven by HIPAA and GDPR audit requirements that favor vendor-managed security patching.
Copier, MFP and Printer Market Segmentation
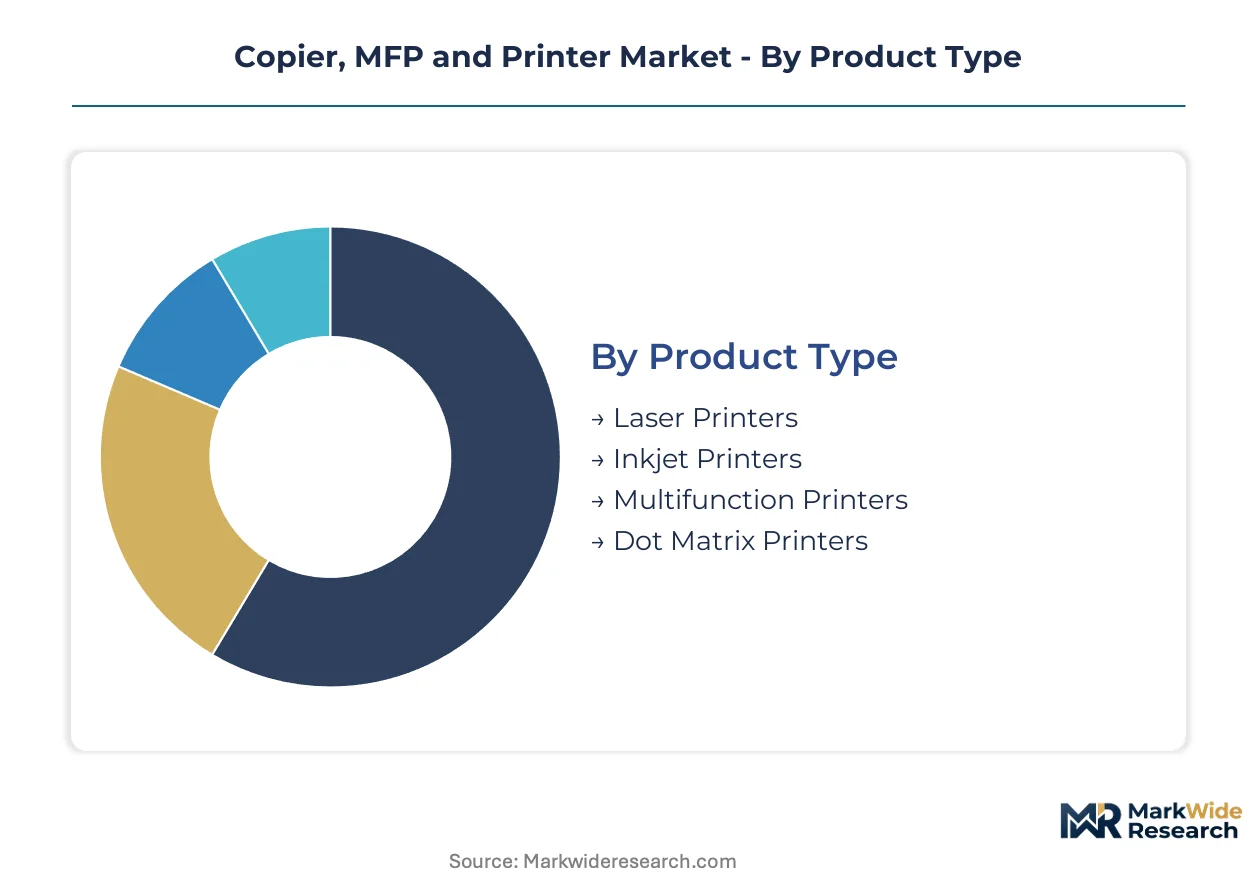
Segmentation in the copier, MFP and printer market reveals how capital deployment, regulatory exposure, and channel economics concentrate profitability in distinct pockets. Manufacturers optimize portfolio mix across these dimensions to defend margin structures against commoditization pressures.
Product Type:
Laser printers and multifunction printers demand the heaviest upfront engineering investment in optical engines and fuser assemblies, while inkjet architectures spread fixed costs across disposable cartridge economics.
- Laser Printers:Electrophotographic devices fuse dry toner onto substrates using organic photoconductor drums and laser scanning assemblies. Corporate offices in the United States and Germany concentrate procurement of A4 monochrome fleets exceeding 40 pages per minute, driven by HIPAA and GDPR audit requirements for on-premise document processing.
- Inkjet Printers:Piezoelectric or thermal printheads deposit liquid pigment at resolutions reaching 4800 dots per inch. Photo-specialist studios and architectural firms in Japan and Italy drive refresh cycles for wide-format variants, constrained by archival longevity standards for pigment versus dye-based formulations.
- Multifunction Printers:Consolidated devices integrating print, scan, copy, and fax functions dominate educational infrastructure tenders in India and China. BIS certification and MIIT GB standards gate access to public sector procurement channels.
- Dot Matrix Printers:Impact technology persists in logistics and retail environments requiring multi-part carbonless forms. Warehouse management systems in Brazil and Mexico sustain replacement demand despite digital substitution in adjacent segments.
Multifunction printers absorb the bulk of installed capacity; inkjet printers are expanding most quickly in photo-specialist and wide-format niches.
Technology:
Technology selection determines thermal management complexity, supply chain dependencies on Japanese and German chemical feedstocks, and compliance timelines under REACH substance authorization procedures.
- LED:Solid-state printhead arrays eliminate scanning mirror mechanisms, enabling compact chassis designs with reduced moving parts. High-speed monochrome fleets in legal and logistics verticals adopt LED architectures for 60-90 page-per-minute departmental installations, with downstream control over fuser temperature profiles extending component longevity.
- Piezoelectric:Variable droplet precision technology modulates ink volume per dot through mechanical deformation of ceramic actuators. Fine art reproduction and packaging proofing applications in France and Switzerland command premium pricing for archival pigment formulations.
- Thermal Inkjet:Resistive heating elements vaporize ink to eject droplets through micro-nozzles. Consumer desktop units dominate home-office replenishment cycles, with Brother Industries and HP Inc. competing on cartridge page yield and instant ink subscription attach rates.
- Impact:Electromechanical pins strike ribbon against substrate for multi-part form reproduction. Point-of-sale and banking sectors in India and Indonesia sustain demand despite minimal R&D investment from OEMs.
LED technology captures the steepest expansion trajectory in enterprise monochrome fleets; impact technology contracts to maintenance-only revenue pools.
End User:
End-user segmentation maps divergent procurement authority structures, with government tenders subject to electromagnetic compatibility certification and educational buyers prioritizing total cost of ownership over acquisition price.
- Corporate Offices:Hybrid work permanence fragments print volumes across distributed endpoints, forcing hardware economics toward lower-duty-cycle devices and cloud-managed fleet services. Managed print service contracts in the United States and United Kingdom transfer ownership risk to manufacturers while locking in multi-year consumable commitments.
- Educational Institutions:K-12 and university systems in China, India, and the United States drive replacement demand through public sector modernization programs. EPA Energy Star and EU Ecodesign Directive compliance gates access to institutional procurement frameworks.
- Retail Stores:Receipt printing and inventory labeling applications concentrate demand for compact thermal and impact devices. Franchise networks in Brazil and Mexico standardize on specific OEM platforms to simplify remote diagnostics and spare parts logistics.
- Government Agencies:Common Criteria and FIPS 140-2 firmware security certification requirements extend product launch windows by 8-14 months for federal deployments. India's PLI scheme for electronics manufacturing attracts component localization investments that reduce import duty exposure on optical engines.
Corporate offices command the largest revenue pool; educational institutions are gaining share fastest through infrastructure modernization cycles.
Distribution Channel:
Channel selection determines margin capture between hardware sale and service annuity, with direct sales enabling subscription-based page-per-print contracts that displace capital equipment purchases.
- Direct Sales:OEM field organizations engage enterprise accounts with customized fleet optimization proposals and vendor-managed security patching. Legal and healthcare verticals in Germany and the United States exhibit fastest contract velocity, driven by GDPR and HIPAA audit requirements.
- Distributors:National and regional wholesalers aggregate volume across fragmented reseller bases, absorbing inventory risk and providing credit facilities to channel partners. Ingram Micro and TD Synnex maintain dominant positions in North American and Western European logistics.
- Online Retail:Amazon and specialized B2B platforms capture consumer and small-office segments with transparent pricing and rapid fulfillment. Cartridge replenishment subscriptions lock in recurring revenue independent of hardware refresh cadence.
- Resellers:Value-added resellers bundle hardware with document management software and change management services. Channel partners restructure compensation models around service annuity rather than hardware margin, particularly in mature markets.
Direct sales channels concentrate the highest-value enterprise contracts; online retail is climbing the fastest in small-office and home-office segments.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Electronics Manufacturing Clusters in Uttar Pradesh and Tamil Nadu concentrate new assembly investments for optical engines and fuser assemblies, attracted by the PLI scheme's production-linked incentives for hardware localization.
United States
Corporate offices in Texas and Illinois fragment print volumes across hybrid work endpoints, driving demand for cloud-managed fleet services and lower-duty-cycle devices. The EPA Energy Star program enforces standby power thresholds that OEMs must embed at design stage. Greater Boston hosts enterprise software integrators bridging legacy MFP job description languages with cloud-native document platforms.
China
Educational infrastructure tenders in Jiangsu and Guangdong provinces drive replacement demand for multifunction printers serving K-12 and university systems. The MIIT publishes GB standards for electromagnetic compatibility and toner safety that gate access to public procurement channels. The Yangtze River Delta concentrates electrophotographic drum manufacturing where specialty polymer feedstock suppliers cluster.
Germany
Legal and healthcare verticals in Bavaria and North Rhine-Westphalia exhibit fastest contract velocity for managed print services, driven by GDPR audit requirements favoring vendor-managed security patching. The EU Ecodesign Directive mandates cartridge recyclability standards that accelerate OEM refresh cycles. Baden-Württemberg anchors precision optical component fabrication for LED printhead arrays.
Japan
Fine art reproduction studios and packaging proofing applications in Tokyo and Osaka command premium pricing for archival pigment inkjet formulations. The country's national chemical regulator enforces substance restrictions affecting photoconductor coatings. The Chubu region around Nagoya maintains concentration of piezoelectric printhead manufacturing expertise.
Copier, MFP and Printer Market Competitive Landscape
Japanese producers anchor one tier; American specialists hold enterprise service contracts. The vendor base concentrates around electrophotographic engine manufacturers with in-house optical capabilities and inkjet specialists with captive cartridge economics. Three archetypes dominate: vertically integrated engine fabricators, subscription-based service platforms, and compact desktop specialists. Competitive moves center on backward integration into specialty chemical feedstocks and geographic expansion through India's PLI scheme incentives.
Within the vertically integrated tier, Canon Inc. and Ricoh Company Ltd. exemplify producers controlling optical engine manufacturing in-house. HP Inc. occupies a position representing subscription-based page-per-print contract models that transfer ownership risk to manufacturers. Brother Industries Ltd. anchors the compact desktop specialist archetype, serving home-office replenishment cycles where cartridge yield economics determine repeat purchase frequency.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Seiko Epson Corporation |
| Brother Industries Ltd. |
| Ricoh Company Ltd. |
| Xerox Corporation |
| Kyocera Corporation |
| Konica Minolta Inc. |
| Sharp Corporation |
| Others |
Pricing and Supply Chain Analysis
Toner resin feedstocks from Japanese and German chemical suppliers cascade through electrophotographic drum manufacturing into three-tier pricing structures across premium, standard, and economy levels, with OEMs passing polymer cost volatility downstream to enterprise fleet contracts and home-office cartridge economics.
Pricing Analysis
Short lead-time premiums for optical engine assemblies and fuser units command 15-25 percent markups over spot inventory liquidated through distributor channels. Subscription-based page-per-print contracts dominate mid-market corporate accounts, transferring ownership risk to manufacturers while locking in multi-year consumable commitments. Price differentiation hinges on certification tier (Energy Star, Ecodesign Directive compliance) and after-sales service bundling. Cost compression in entry-level inkjet segments is intensifying because instant ink subscription attach rates determine repeat purchase frequency. Educational institutions exhibit highest price sensitivity due to total cost of ownership procurement frameworks; legal and healthcare verticals show lowest sensitivity given HIPAA and GDPR audit requirements.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Singapore operate hub-and-spoke patterns feeding European and Asia-Pacific reseller networks. Manufacturing concentrates in China, Japan, and Vietnam for optical engines, piezoelectric printheads, and compact chassis assemblies. Specialty polymer feedstocks for photoconductor drums draw from German and Japanese chemical suppliers. Single-source vulnerability in hexavalent chromium coatings for charge transport layers threatens EU market access under REACH sunset date enforcement. Distribution runs through national wholesalers absorbing inventory risk, with direct sales channels capturing highest-value enterprise contracts.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over toner resin supply and captive ink cartridge economics separates profitable participants from assembly-dependent competitors.
For Market Incumbents: Cement control over optical engine manufacturing through in-house fabrication investments in India's Electronics Manufacturing Clusters, insulating against PLI scheme localization requirements. Deepen backward integration into specialty polymer feedstocks to reduce exposure to Japanese and German chemical supplier concentration. Defend against subscription-based service platforms by embedding AI-driven predictive maintenance into existing fleet management contracts.
For New Entrants and Emerging Players: Capture aftermarket service revenue pools in Brazil and Mexico where impact printer maintenance contracts sustain replacement demand despite minimal OEM R&D investment. Target India's educational infrastructure tenders where BIS certification gates access but local assembly partnerships reduce import duty exposure. Pursue white-label cartridge manufacturing for home-office replenishment cycles where yield economics determine repeat purchase frequency.
For Investors and Strategic Acquirers: ECHA authorization timeline acceleration for chromium compound alternatives is the leading indicator that reformulation-capable electrophotographic drum manufacturers will command scarcity premiums. Position for 5-10 year consolidation around vertically integrated engine fabricators with REACH-compliant coating expertise. Monitor right-to-repair legislation progression across multiple jurisdictions as the signal for aftermarket service revenue model viability independent of hardware refresh cadence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Chemical Feedstocks | Captures margin from Japanese and German polymer suppliers while hedging REACH reformulation costs. |
| Production Localization under India's PLI Scheme | Reduces import duty exposure on optical engines for public sector tenders in Uttar Pradesh and Tamil Nadu. |
| Subscription-Based Page-per-Print Contract Expansion | Transfers ownership risk to manufacturers while locking legal and healthcare verticals into multi-year consumable commitments. |
| AI-Driven Predictive Maintenance Platform Launch | Reduces customer downtime incidents through machine learning integration with printer fleet telemetry. |
| REACH-Compliant Photoconductor Coating Development | Ensures continued EU market access as ECHA sunset dates force alternative charge transport layer formulations. |
Research Methodology
Document review covered SEC 10-K filings from electrophotographic and inkjet OEMs, EPA Energy Star certification databases, ECHA substance authorization registers, and MIIT GB standards publications, complemented by interviews with fleet procurement managers at K-12 and university systems, managed print service channel partners, optical component fabrication engineers, and regulatory affairs specialists at chemical feedstock suppliers. Bottom-up triangulation across hardware shipment data, consumable replenishment cycles, and service contract values was cross-validated against top-down macroeconomic indicators and public sector modernization budget disclosures.
Installed base projections and revenue segmentation outputs were generated through multi-dimensional modeling across product type, technology architecture, end-user vertical, and distribution channel, with CAGRs derived from regression analysis of historical refresh cycles and forward-looking policy implementation timelines. Industry-specific forecast inputs included REACH substance authorization enforcement schedules, India's PLI scheme incentive disbursement patterns, and hybrid work permanence indicators affecting print volume fragmentation.
The model holds under stable regulatory enforcement timelines and continued public sector infrastructure investment; deviation in right-to-repair legislation velocity or toner resin supply disruption would shift hardware refresh cycle assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Retail Printers and Consumables Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Indonesia Thermal Printer Market
Printers
Refurbished Printers Market
Printers
Electrophotographic Printing Market
Printers
Thermal Inkjet Printer Market
Printers
Laser Printer Market
Printers
Printer Ribbons Market
Printers
India Inkjet Printer Market
Printers
Ink Tank Printer Market
Printers
Global UV LED Printers Market
Printers
Dot Matrix Printer Market
Printers
Global Printer Market
Printers
NCR Printers Market
Printers
Global Thermal Printing Market
Printers
Thermal and Inkjet Disc Printers Market