
 Mobile Printer Market | 2026-2036
Mobile Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Printer Market Outlook
Subscription-based fleet management software is expanding what mobile printer vendors monetize beyond hardware. Zebra Technologies leverages its Zebra OneCare service contracts to sustain recurring revenue from enterprise logistics clients. Brother Industries anchors its position in small-business channels through compact thermal units with low total cost of ownership. SATO HOLDINGS dominates industrial label printing in Asia-Pacific manufacturing corridors.
A mobile printer is a battery-powered, portable output device typically weighing under two kilograms, employing direct thermal or thermal transfer mechanisms to produce labels, receipts, or tickets without fixed AC power. These units serve commercial and industrial users requiring on-site documentation in warehouses, hospital wards, delivery vehicles, and retail floors. Thermal technology leads unit shipments due to its absence of ink cartridges and minimal maintenance requirements, though inkjet variants command margin pools in color-critical applications such as healthcare wristband and specimen labeling. Bluetooth connectivity occupies the largest installed base among wireless protocols, while NFC-enabled tap-to-print configurations represent the fastest-growing pairing method for field service workflows.
The US FCC governs radio frequency emissions for wireless-enabled mobile printers, while the EU RoHS directive and CE marking framework restrict hazardous substances and mandate electromagnetic compatibility for devices sold across member states. Japan's METI enforces energy-efficiency standards that shape battery and charging subsystem design for products entering that market. Stakeholders must monitor evolving e-waste regulations in target geographies, as extended producer responsibility rules are tightening collection and recycling obligations for battery-containing portable electronics.
Market Dynamics
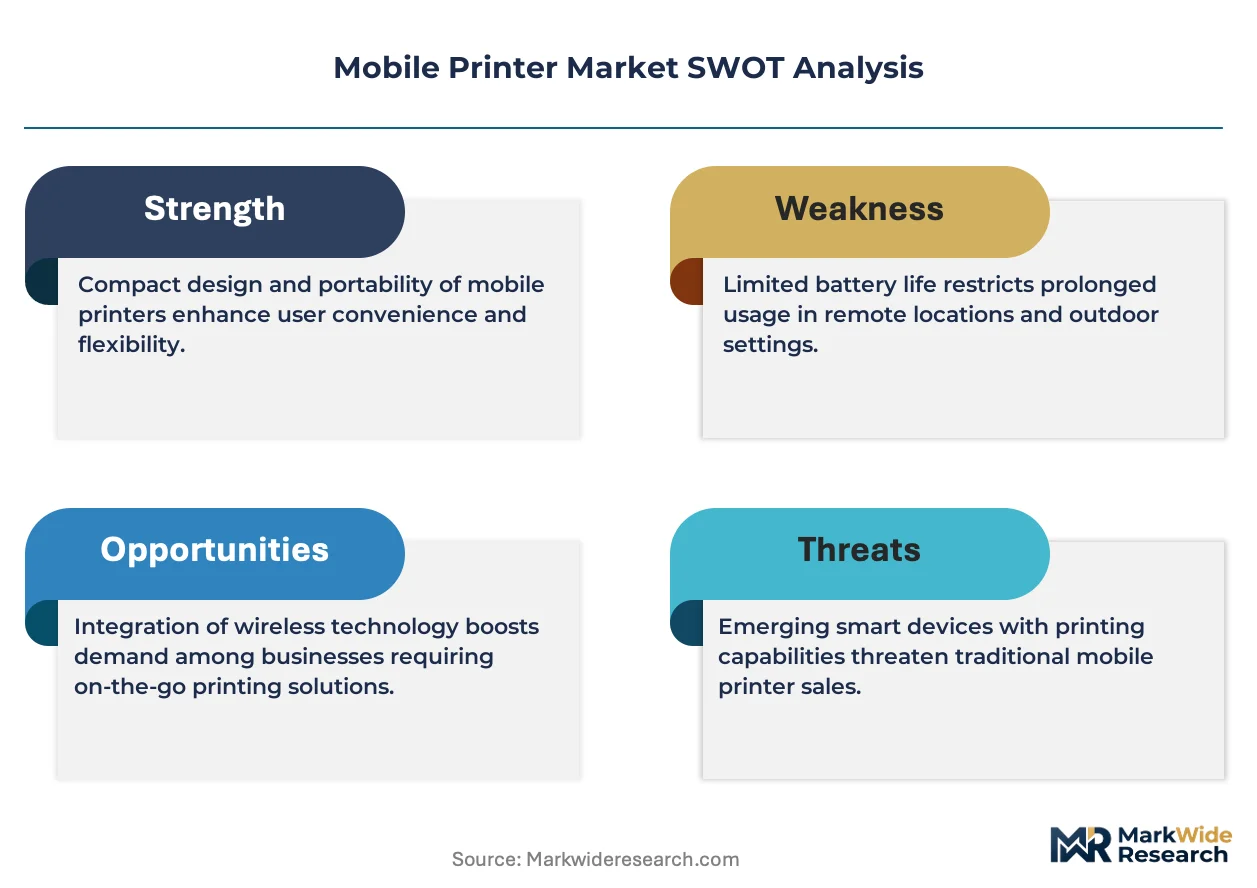
EU RoHS directive enforcement on lead-free solder and REACH-mandated thermal coating reformulations are forcing manufacturers to requalify supply chains and absorb material cost premiums, compressing margins across mid-tier hardware vendors while advantaging vertically integrated producers with captive chemistry capabilities.
Growth Catalysts
- REACH chemical safety mandates:Regulatory pressure on hazardous substance disclosure is accelerating replacement cycles in European logistics fleets as operators retire non-compliant hardware ahead of enforcement deadlines.
- Bluetooth Low Energy pairing:Warehouse management system vendors are embedding native BLE print triggers into their mobile applications, reducing IT integration friction for floor staff.
- German warehouse digitization:Industrial automation investments in Baden-Württemberg and Bavaria are concentrating enterprise procurement of ruggedized mobile printing hardware for real-time inventory tracking.
Market Restraints
- Lithium-polymer cell volatility:Battery raw material price swings and concentrated cell production in East Asia create input cost unpredictability for portable power subsystems.
- Thermal printhead supplier concentration:Precision ceramic heating element fabrication relies on a narrow base of Japanese and Korean component specialists, exposing assemblers to single-source risk.
- Inkjet color durability limits:Pigment fade resistance under UV exposure and chemical contact restricts inkjet mobile units to short-lifecycle applications, ceding industrial label share to thermal transfer.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for domestic manufacturing are creating tariff-advantaged assembly capacity for brands serving South Asian logistics networks.
- Healthcare specimen labeling convergence:Integration of antimicrobial casing materials with color thermal media is opening hospital laboratory workflows previously served by stationary desktop units.
- NFC tap-to-print protocols:Pairing simplification is reducing training burden for seasonal retail and gig delivery workforces, expanding addressable user bases beyond technically proficient field technicians.
Industry Challenges
- EMC certification timelines:FCC Part 15 and CE marking electromagnetic compatibility testing queues are extending product launch schedules, compressing revenue recognition windows for seasonal hardware releases.
- Legacy WMS integration:Enterprise warehouse management platforms built on proprietary print command languages require middleware development, inflating deployment cost and technical risk for vendor implementation teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Printer Market |
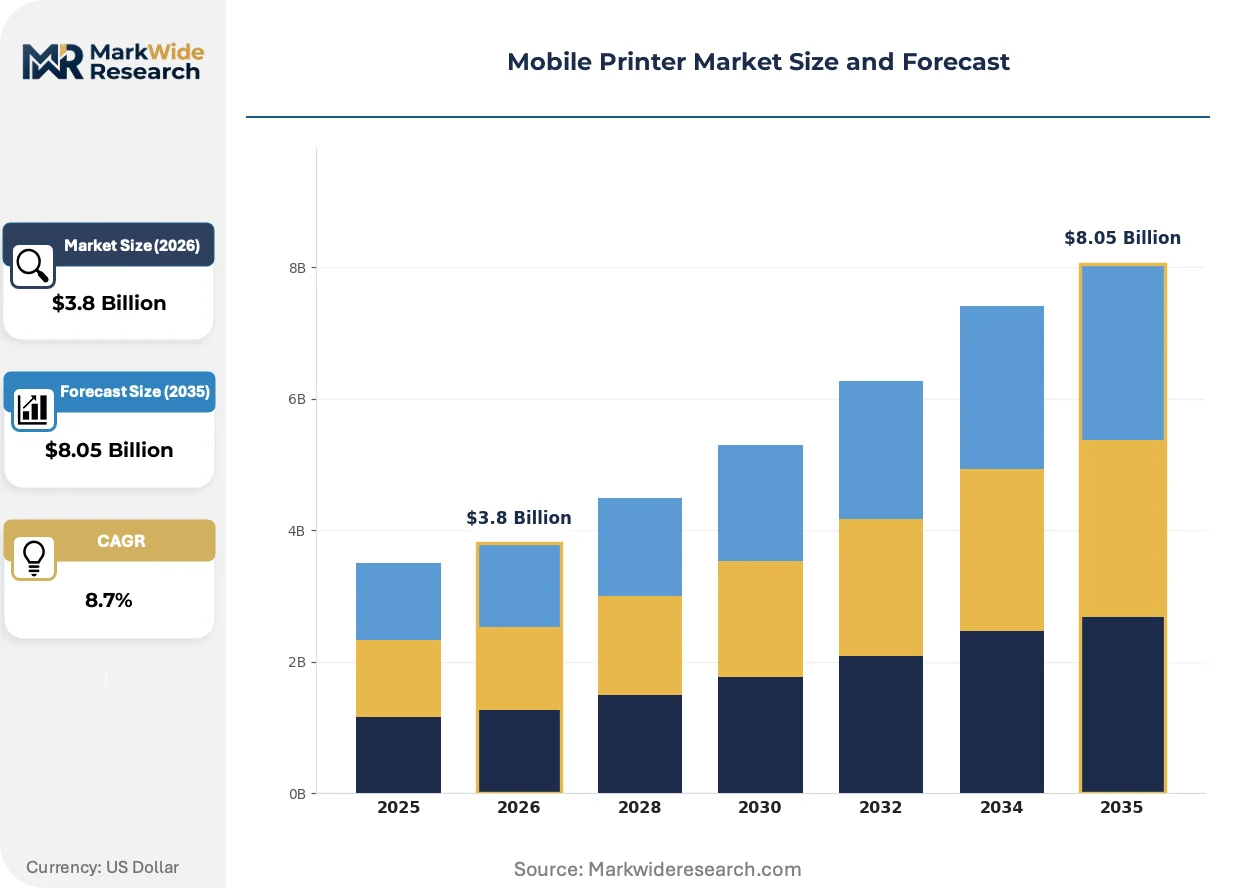
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Inkjet, Dot Matrix, Impact Application: Retail, Healthcare, Transportation, Field Services Connectivity: Bluetooth, Wi-Fi, USB, NFC End User: Small Businesses, Large Enterprises, Government, Education |
| Companies Covered | Canon, Xiamen Paperang Technology, Seiko Epson, TOSHIBA TEC, Pantum, Brother Industries, HP, SATO HOLDINGS, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Printer Market Strategic Shifts
Mobile printer hardware architecture is converging with enterprise mobility software stacks, eroding the boundary between physical output devices and fleet management platforms. Three developments are compressing vendor business models and reshaping buyer value assessments.
Direct thermal film formulations with extended image stability are rewriting durability expectations for receipt and short-term label applications. Quick-service restaurant chains and last-mile delivery operators are adopting these media in high-turnover thermal units, displacing ribbon-based thermal transfer in applications previously requiring six-month legibility guarantees. This chemistry shift is compressing aftermarket consumable revenue pools while expanding hardware placement volumes.
Japan's METI energy-efficiency standards for battery-powered equipment are mandating standby power draw thresholds and charging cycle efficiency metrics that shape subsystem design. Manufacturers targeting the Japanese market must redesign power management firmware and qualify lower-leakage cell chemistries, adding development cost that filters product portfolios toward premium-tier SKUs. Industrial field service vendors are responding by segmenting their Japan-bound offerings from global platforms.
Subscription-based fleet management software is displacing perpetual-license device management tools in enterprise procurement evaluations. Logistics operators in Germany and the Netherlands are bundling hardware procurement with multi-year service contracts that include predictive maintenance analytics and remote diagnostics, unbundling traditional break-fix support relationships. This model shift concentrates vendor relationships with platform-integrated providers and marginalizes hardware-only suppliers.
Mobile Printer Market Segmentation
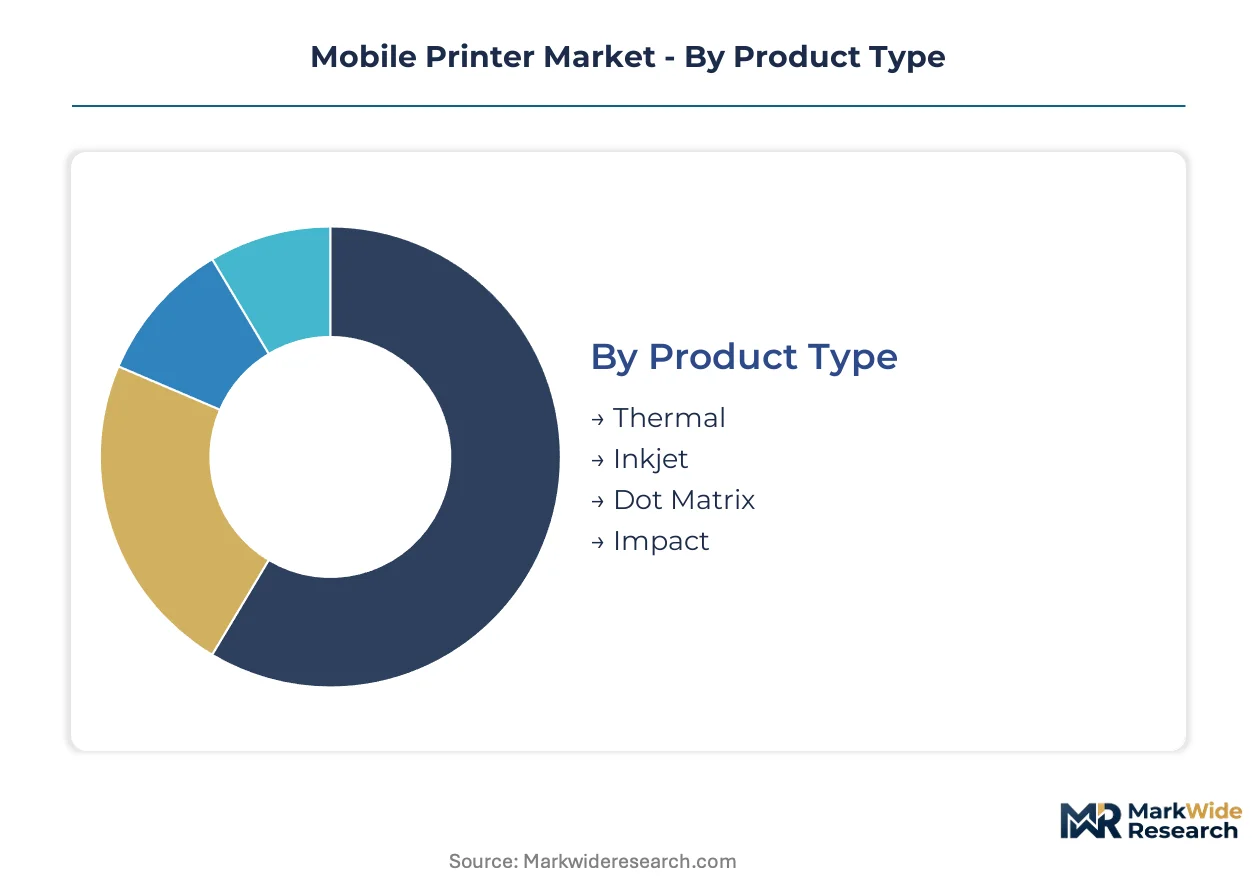
Mobile printer procurement decisions hinge on print mechanism durability, wireless protocol compatibility, and workforce mobility requirements. Segment boundaries are blurring as hardware vendors bundle fleet management software with specific connectivity configurations.
Product Type:
Thermal mechanisms dominate unit economics through elimination of ink cartridges and reduced field maintenance.
- Thermal:Direct thermal and thermal transfer variants employ ceramic heating elements to activate heat-sensitive media or melt wax/resin ribbons onto substrates. German logistics operators in Baden-Württemberg are standardizing on thermal transfer units for inventory labels requiring six-month outdoor legibility.
- Inkjet:Piezoelectric or thermal inkjet heads deposit pigment or dye-based inks onto paper or synthetic media. Healthcare specimen labeling in US hospital networks is absorbing compact color inkjet units for wristband applications despite UV fade limitations.
- Dot Matrix:Impact pin arrays strike inked ribbons against paper, producing multi-part forms through carbon copying. Legacy transportation billing systems in India retain these units for freight documentation requiring physical duplicates.
- Impact:Solenoid-driven hammers imprint characters through ribbon-to-paper contact. Kitchen receipt printing in quick-service restaurant chains exploits impact durability against grease and heat exposure.
Thermal leads on scale; inkjet leads on momentum.
Application:
End-use environments dictate ruggedization grades, media formats, and software integration depth.
- Retail:Shelf-edge label printing and mobile point-of-sale receipt output demand compact Bluetooth-enabled units with sub-500-gram weights. Seasonal workforce turnover in European grocery chains is accelerating NFC tap-to-print adoption to reduce training overhead.
- Healthcare:Antimicrobial casings and specimen barcode compliance dominate procurement specifications. US hospital laboratory workflows are migrating from stationary desktop units to portable thermal units with ISO-standard barcode formatting.
- Transportation:Proof-of-delivery documentation and customs paperwork require wide-format media handling and extended battery endurance. Last-mile delivery fleets in the Netherlands are consolidating on ruggedized hardware with predictive maintenance analytics.
- Field Services:Utility meter reading and equipment inspection tagging prioritize IP54+ ingress protection and all-weather operability. German industrial automation corridors are driving enterprise procurement of MIL-STD-810G tested units.
Retail captures the largest installed base; field services exhibits the steepest expansion trajectory.
Connectivity:
Wireless protocol selection determines IT integration friction and fleet management architecture.
- Bluetooth:Low Energy pairing dominates warehouse floor deployments through native integration with Android-based handheld computers. BLE print triggers embedded in warehouse management system mobile applications are reducing deployment timelines.
- Wi-Fi:Enterprise-grade WPA3 security and centralized SSID management suit fixed-route delivery vehicles with depot docking. Large enterprise logistics operators are mandating Wi-Fi 6 compatibility for future-proofing infrastructure investments.
- USB:Wired connectivity persists in government procurement specifications requiring air-gapped security architectures. Education sector deployments in India rely on USB tethering for examination hall ticketing with minimal RF interference risk.
- NFC:Tap-to-print protocols eliminate manual pairing sequences for gig economy delivery workforces. Small business adoption in Japan is climbing fastest as METI energy-efficiency standards favor low-power standby modes that NFC wake-on-demand enables.
Bluetooth commands the installed base; NFC gains share fastest.
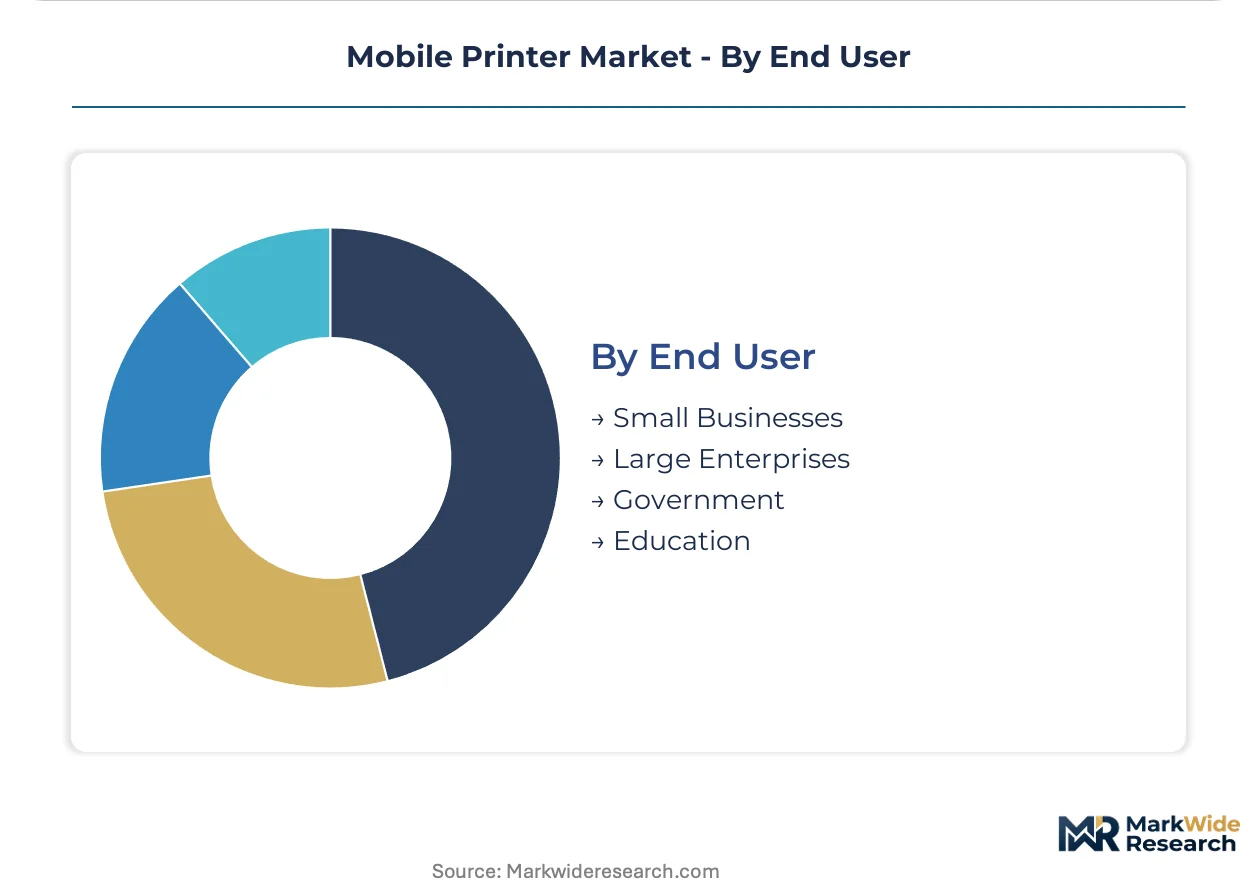
End User:
Organizational scale shapes pricing tolerance, service contract structure, and compliance burden.
- Small Businesses:Total cost of ownership sensitivity drives compact thermal unit selection with minimal consumable variety. Brother Industries anchors this channel through low-maintenance hardware with standardized media compatibility.
- Large Enterprises:Multi-year fleet management contracts with predictive analytics and remote diagnostics are displacing break-fix support relationships. Zebra Technologies leverages Zebra OneCare service contracts to sustain recurring revenue from logistics clients.
- Government:Extended procurement cycles and domestic content requirements favor established vendor relationships with certified repair networks. India's PLI scheme for electronics manufacturing is creating tariff-advantaged assembly capacity for brands serving public sector tenders.
- Education:Seasonal demand spikes and constrained capital budgets prioritize rental and lease financing structures. Examination administration workflows in Germany concentrate procurement timing around academic calendar cycles.
Large enterprises dominate revenue concentration; small businesses represent the broadest addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting assembly footprints toward jurisdictions with production-linked incentives and lighter chemical-compliance burdens, while mature markets absorb premium hardware with embedded service contracts.
United States
Last-mile delivery fleet expansion and healthcare specimen labeling are absorbing ruggedized thermal units. FCC Part 15 governs Bluetooth and Wi-Fi emissions for warehouse floor deployments. Dallas-Fort Worth logistics corridors are consolidating procurement of predictive-maintenance-enabled hardware for real-time inventory tracking.
Germany
Industrial automation investments and warehouse digitization are driving enterprise procurement of MIL-STD-810G tested units. EU RoHS and REACH mandates on lead-free solder and thermal coatings are accelerating hardware replacement cycles ahead of enforcement deadlines. Baden-Württemberg and Bavaria automation clusters are standardizing on thermal transfer units for six-month outdoor legibility requirements.
Japan
METI energy-efficiency standards for battery-powered equipment are mandating standby power thresholds and charging cycle metrics. These regulations filter product portfolios toward premium-tier SKUs with redesigned power management firmware. Kanto and Kansai industrial corridors are adopting NFC tap-to-print configurations to exploit low-power standby modes.
India
PLI scheme incentives for electronics manufacturing are creating tariff-advantaged assembly capacity for South Asian logistics networks. Domestic content requirements in government tenders favor certified repair networks and local fabrication. Maharashtra and Gujarat industrial zones are absorbing compact thermal units for freight documentation and examination hall ticketing.
Netherlands
Enterprise logistics operators are bundling hardware procurement with multi-year service contracts including predictive maintenance analytics. CE marking electromagnetic compatibility requirements shape product launch timelines for EU market entry. Rotterdam port logistics corridors are consolidating on ruggedized hardware with remote diagnostics capabilities.
Mobile Printer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hardware-only suppliers facing margin compression against platform-integrated providers. The vendor base organizes around three archetypes: diversified electronics conglomerates with captive distribution, pure-play mobile printing specialists with vertical software integration, and regional contract manufacturers serving price-sensitive channels. Consolidation pressure favors M&A activity among mid-tier hardware vendors, while strategic partnerships between printer OEMs and warehouse management system vendors are reshaping procurement evaluation criteria.
Among diversified electronics conglomerates, Canon, Seiko Epson, and HP exemplify scale-driven positioning through broad imaging and printing portfolios. These Japan- and US-based entities occupy positions spanning consumer, commercial, and industrial segments, leveraging existing distribution infrastructure and brand recognition. Their market presence reflects hardware-software bundling strategies and multi-channel reach rather than mobile-specific specialization.
| Leading Market Players |
|---|
| Canon |
| Xiamen Paperang Technology |
| Seiko Epson |
| TOSHIBA TEC |
| Pantum |
| Brother Industries |
| HP |
| SATO HOLDINGS |
| Zebra Technologies |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between MIL-STD-810G tested enterprise units and commodity consumer hardware manifests in pricing spreads exceeding three-to-one, with premium-tier vendors capturing captive supply of Japanese ceramic heating elements while mid-tier assemblers absorb REACH-mandated thermal coating cost premiums without commensurate pricing power.
Pricing Analysis
Distributor margin layers in enterprise channels run 18-25 points above direct-to-OEM arrangements for volume logistics operators. Three-tier pricing structure across premium, standard, and economy levels separates predictive-analytics-bundled fleet contracts from break-fix hardware sales. Pricing pressure stems from lithium-polymer cell volatility and concentrated Japanese thermal printhead sourcing. Small-business buyers exhibit highest price sensitivity, while German industrial automation clusters prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Precision ceramic heating element fabrication rests on Japanese and Korean component specialists, creating single-source exposure for thermal printhead supply. Battery cell production concentrates in China, South Korea, and Taiwan, with raw material dependencies spanning cobalt, lithium carbonate, and specialized electrolyte formulations. Tariff exposure intensifies for brands lacking India PLI scheme qualification. Distribution runs through certified repair networks in government channels and direct field service relationships in enterprise logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme incentives and lighter chemical-compliance burdens attract assembly migration away from REACH-heavy European production, compressing landed cost for South Asian logistics networks by 12-18 points against EU-origin hardware.
For Market Incumbents: Extend predictive maintenance analytics capabilities to deepen subscription revenue retention against hardware-only challengers. Secure backward integration into thermal coating chemistry to absorb REACH reformulation costs without margin sacrifice. Defend German industrial corridor relationships through MIL-STD-810G certification investment and localized repair network density. For New Entrants and Emerging Players: E-commerce marketplace routes into small-business channels bypass incumbent distributor control and reduce customer acquisition cost versus field sales investment. Target India's examination administration and freight documentation segments where domestic content requirements favor tariff-advantaged assembly. Lead with NFC tap-to-print simplicity to reduce training burden for seasonal retail workforces. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier hardware vendors lack captive chemistry capabilities and bleed margin on REACH compliance without platform-integrated service revenue to offset. Five-to-ten year viability favors vendors with fleet management software attach rates above thirty percent. Watch thermal film formulation patents as inflection signal for consumable revenue compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Coating Chemistry | REACH compliance cost absorption protects margin structure against reformulation mandates. |
| NFC Tap-to-Print Protocol Development | METI energy-efficiency alignment opens Japanese small-business channel expansion. |
| India PLI Scheme Assembly Qualification | Tariff-advantaged production capacity captures South Asian logistics procurement growth. |
| Predictive Maintenance Platform Launch | Subscription revenue displacement of break-fix relationships concentrates vendor relationships. |
| Antimicrobial Casing Material Certification | Healthcare specimen labeling convergence opens hospital laboratory workflow migration. |
Study Parameters
Bottom-up logistics fleet deployment modeling reconciled against top-down thermal printhead and battery cell production tracking forms the analytical core. Primary interviews with warehouse operations directors, mobile device procurement managers, thermal media R&D leads, and aftermarket service heads combined with secondary validation against FCC equipment authorization databases, EU REACH substance restriction filings, Japan METI efficiency standard registrations, and India PLI scheme beneficiary disclosures. Triangulation across these sources yields shipment and revenue estimates.
Input-output matrices map connectivity protocol adoption rates, print mechanism durability requirements, and end-use ruggedization grades against regional regulatory clusters across the analysis window. Segmentation dimensions span product type, application environment, wireless protocol, and organizational scale tier. CAGRs derive from logistic operator capex cycle analysis and replacement timing triggered by RoHS enforcement deadlines. Forecast inputs incorporate battery chemistry cost curves and thermal film formulation patent expiration schedules.
The model assumes a particular technology adoption path; alternative pathways for inkjet pigment durability breakthroughs would alter the outlook. Forecasts reflect assumptions regarding REACH enforcement timing and lithium supply contract renegotiation patterns. A small set of triggers—thermal printhead supplier consolidation, India PLI scheme expansion, and NFC protocol standardization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Electrophotographic Printing Market
Printers
Single Function Printer Market
Printers
Copier, MFP and Printer Market
Printers
Nanographic Printing Market
Printers
Aerosol Printing and Graphics Market
Printers
Thermal and Inkjet Disc Printers Market
Printers
Continuous Inkjet Printers Market
Printers
Production Printer Market
Printers
Retail Printers and Consumables Market
Printers
Multi-Functional Printer Market
Printers
Mobile Photo Printer Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Global UV LED Printers Market
Printers
Photocopiers Market
Printers
Thermal Printer Market
Printers
Portable Printer Market