
 Direct-To-Shape Inkjet Printers Market | 2026-2036
Direct-To-Shape Inkjet Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-To-Shape Inkjet Printers Market Analysis
Equipment leasing and print-as-a-service contracts is reconfiguring capital deployment across the Direct-To-Shape Inkjet Printers landscape, lowering barriers for mid-sized decorators. Xerox Corporation leverages its enterprise financing arm to bundle hardware with managed print services. Roland DG Corporation anchors its position through deep specialization in compact UV systems for short-run customization. Mimaki Engineering Co., Ltd. competes by sustaining intensive R&D in multi-layer ink deposition for textured effects on curved substrates.
Direct-to-shape inkjet printers apply piezoelectric or thermal drop-on-demand inkjet heads to print directly onto three-dimensional objects, achieving resolutions up to 1200 dpi without pre-treatment on many polymer surfaces. Their primary purpose is eliminating label application steps while enabling versioning and personalization at production speeds. UV inkjet technology leads installed value due to instant curing and broad substrate compatibility, though hybrid printer configurations are gaining fastest in facilities running both rigid and flexible goods. Multi-station printer architectures concentrate margin pools where automotive and electronics end users demand parallel processing of complex geometries.
FDA substrate-contact regulations and REACH chemical restrictions in Europe govern ink migration limits and photoinitiator safety, compelling reformulation investments from equipment-ink integrated suppliers. ISO print quality standards and CE marking requirements shape product development cycles and market access timelines. Stakeholders must monitor evolving state-level extended producer responsibility rules and decide whether to internalize ink chemistry development or lock into captive supply partnerships.
Market Dynamics
Equipment leasing and print-as-a-service contracts are reconfiguring capital deployment across the Direct-To-Shape Inkjet Printers landscape, lowering barriers for mid-sized decorators while compressing traditional hardware sales cycles.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on photoinitiator safety are compelling ink reformulation investments that favor integrated equipment-ink suppliers with captive chemistry capabilities.
- Beverage packaging versioning:North American bottling lines are accelerating adoption to eliminate pre-printed label inventories and enable real-time SKU customization.
- UV-curable ink advances:Instant curing technology with broad polymer compatibility is displacing solvent-based systems in automotive and cosmetics decorating hubs.
Market Restraints
- Photoinitiator supply concentration:Specialty chemical production for UV inks clusters in Germany and China, exposing decorators to input cost volatility and single-source risk.
- FDA substrate-contact compliance:Evolving FDA migration limits for food-contact packaging create reformulation friction and extend product qualification timelines.
- Hybrid printer capex thresholds:Multi-station architectures for parallel processing of complex geometries require capital intensity that excludes smaller contract decorators.
Strategic Opportunities
- India PLI scheme for electronics:Domestic manufacturing incentives are attracting component labeling investments where direct-to-shape personalization replaces imported pre-printed housings.
- Extended producer responsibility mandates:EU state-level EPR rules are forcing brands to eliminate label adhesives and substrates, favoring printed decoration as compliance pathway.
- AI-driven print optimization:Machine vision convergence with inkjet deposition is enabling real-time defect correction on curved automotive trim pieces.
Industry Challenges
- Multi-physics simulation expertise:Drop behavior on curved substrates requires computational fluid dynamics and materials science skills scarce in traditional screen-printing workforces.
- ISO print quality certification:Achieving consistent 1200 dpi resolution on untreated polymers demands extended validation protocols that delay commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-To-Shape Inkjet Printers Market |
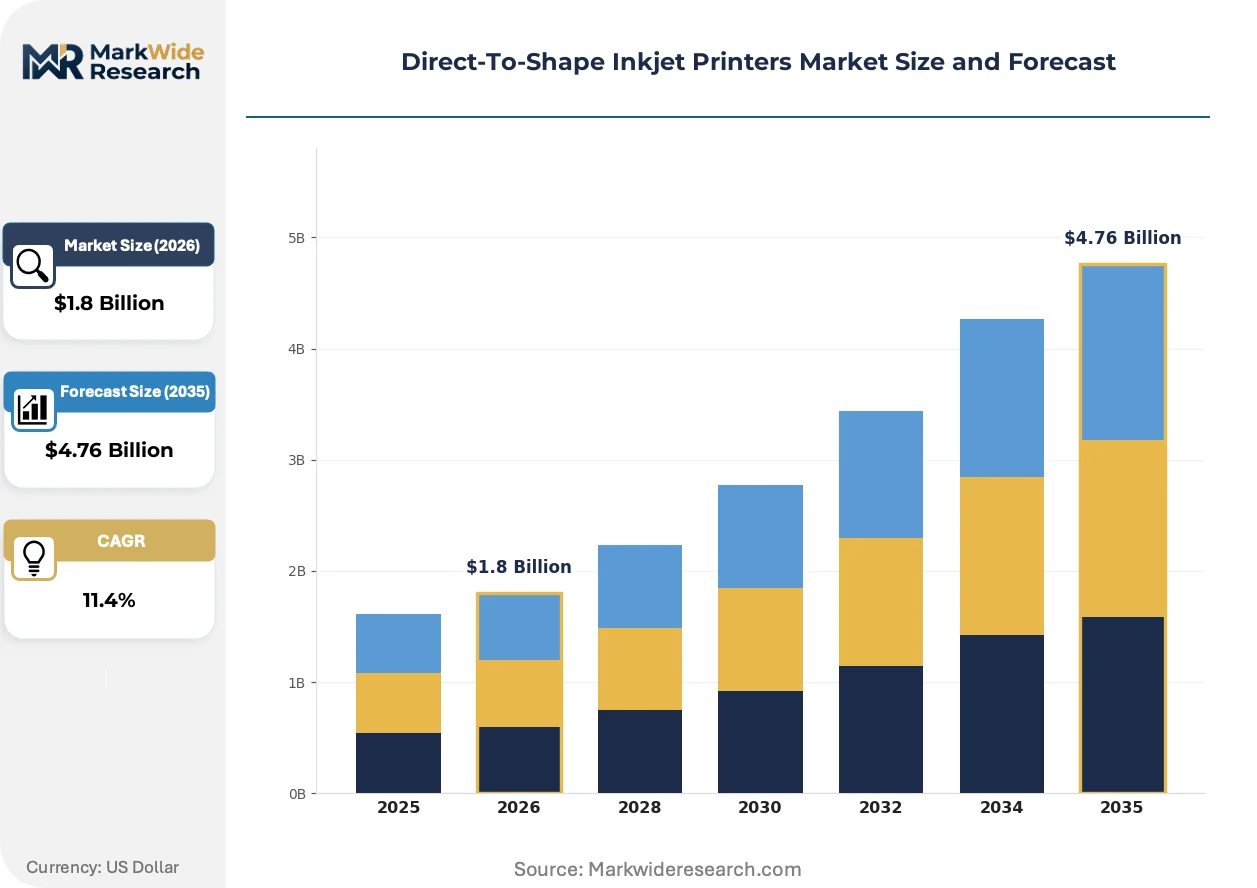
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Station Printers, Multi-Station Printers, Hybrid Printers, Portable Printers Technology: Piezoelectric Technology, Thermal Inkjet Technology, UV Inkjet Technology, Solvent Ink Technology End User: Consumer Goods, Automotive Parts, Packaging Industry, Electronics Application: Labeling, Custom Branding, Product Decoration, Industrial Marking |
| Companies Covered | Xerox Corporation, Roland DG Corporation, Mimaki Engineering Co., Ltd., Xaar plc, Durst Group, EFI, Canon Inc., Seiko Epson Corporation, Koenig & Bauer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-To-Shape Inkjet Printers Market Emerging Trajectories
Digital decoration workflows are compressing design-to-production timelines while fragmenting batch economics, forcing equipment suppliers to embed software-defined manufacturing capabilities alongside hardware.
Single-pass piezoelectric arrays with variable droplet volume control are virtualizing the pre-press tooling layer that previously dominated short-run customization economics. Automotive tier-one suppliers in Germany and premium cosmetics contract manufacturers in France are adopting these systems at replacement cycle pace. This virtualization is compressing minimum viable order quantities from thousands to single-digit units without plate or screen changeover costs.
ECHA REACH Annex XVII restrictions on benzophenone and ITX photoinitiators are forcing systematic ink chemistry redesign across UV-curable formulations. Industrial consequence includes accelerated supplier consolidation as standalone ink houses lack reformulation R&D scale. Food-contact packaging segments in Italy and Spain are responding fastest, locking into captive supply partnerships with equipment-integrated chemistry providers.
After-sales service unbundling is displacing bundled maintenance contracts in mid-cap decorator procurement. Equipment financiers and third-party technical service networks are capturing recurring revenue streams that OEMs previously monopolized. This pattern concentrates in North American beverage co-packers and German automotive suppliers seeking operational expenditure predictability over capital ownership.
Direct-To-Shape Inkjet Printers Market Segmentation
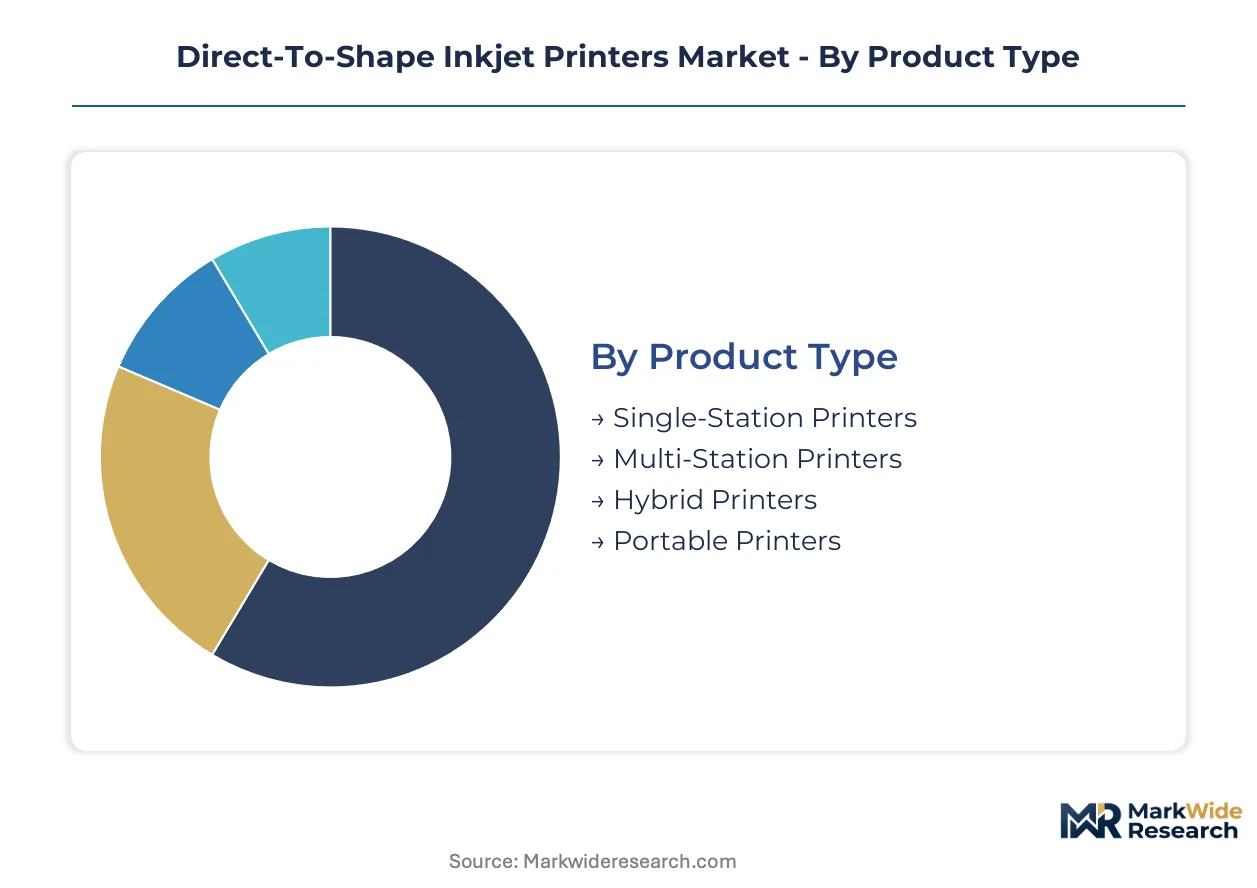
Direct-to-shape inkjet printer segmentation reveals how hardware architecture, ink chemistry, and end-use requirements intersect to determine equipment selection and supplier relationships. Understanding these dimensions exposes where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Mature industrial configurations dominate installed base value while emerging portable formats unlock new deployment contexts.
- Multi-Station Printers:Parallel processing architectures handle complex geometries through synchronized print heads on rotating fixtures. Automotive tier-one suppliers in Germany and premium cosmetics contract manufacturers in France concentrate procurement here for high-mix, low-volume production.
- Hybrid Printers:Dual-mode systems switch between rigid and flexible substrates without reconfiguration. Beverage co-packers in the United States accelerate adoption to collapse separate label and direct-print workflows into single capital investments.
- Single-Station Printers:Compact units with fixed print beds serve entry-level decorators and prototyping labs with sub-$50K capital thresholds.
- Portable Printers:Handheld or cart-mounted systems enable on-site customization at retail locations and event marketing activations.
Multi-Station Printers retain volume leadership; Portable Printers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium UV-curable systems from economy solvent alternatives, with piezoelectric precision commanding intermediate positioning.
- UV Inkjet Technology:Instant photopolymer curing enables direct printing on untreated polymers, glass, and metal without drying infrastructure. REACH Annex XVII restrictions on benzophenone and ITX photoinitiators in Europe compel reformulation investments that favor integrated equipment-ink suppliers.
- Piezoelectric Technology:Piezoelectric drop-on-demand heads achieve 1200 dpi resolution through variable droplet volume control. Japanese precision component manufacturers and German automotive decorators prioritize these systems for textured effects on curved trim pieces.
- Thermal Inkjet Technology:Bubble-jet mechanisms deliver lower capital costs but restrict ink viscosity ranges, limiting substrate compatibility.
- Solvent Ink Technology:Slow-evaporation solvent systems persist in emerging markets where UV chemistry supply chains remain underdeveloped and regulatory enforcement varies.
UV Inkjet Technology commands the premium tier; Piezoelectric systems are gaining share fastest in precision applications.
End User:
Application intensity varies sharply across customer type, with packaging velocity requirements diverging from automotive durability specifications.
- Packaging Industry:Beverage bottling lines and food-contact container producers drive the fastest equipment refresh cycles. FDA substrate-contact migration limits create qualification friction that extends deployment timelines for new ink formulations.
- Automotive Parts:Tier-one suppliers and aftermarket decorators demand chemical resistance and UV stability for interior trim and exterior badging. German industrial hubs around Stuttgart and Munich concentrate specification authority.
- Consumer Goods:Cosmetics, personal care, and promotional product decorators value versioning flexibility over absolute throughput.
- Electronics:Component labeling and device housing personalization respond to India PLI scheme incentives for domestic manufacturing.
Packaging Industry retains volume leadership; Electronics holds the steepest expansion curve.
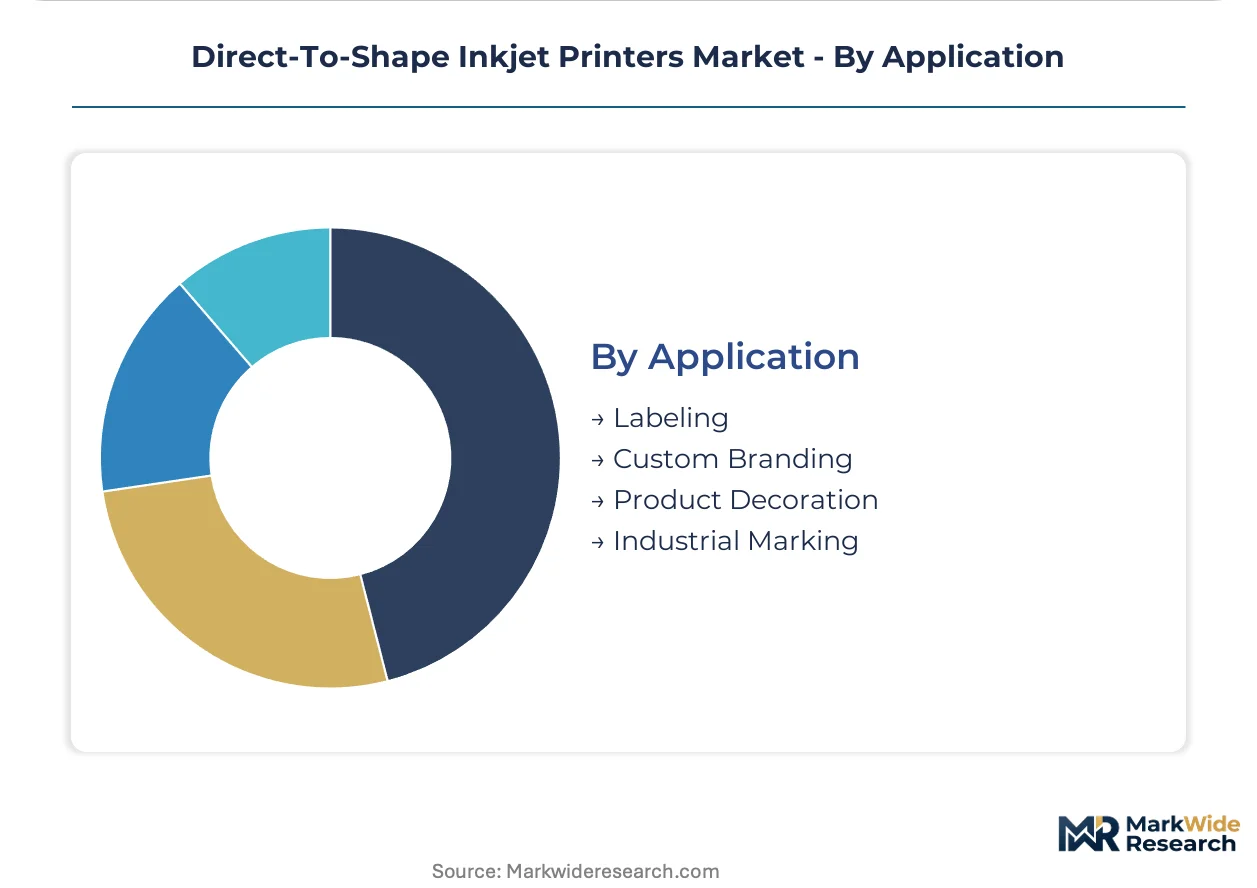
Application:
Margin structure diverges between compliance-driven industrial marking and discretionary customization services.
- Custom Branding:Short-run personalization and versioning commands premium pricing per unit. North American beverage brands eliminate pre-printed label inventories through real-time SKU customization.
- Product Decoration:Premium surface finishing with multi-layer ink deposition and textured effects serves cosmetics and luxury goods. French contract manufacturers adopt these capabilities at replacement cycle pace.
- Labeling:Regulatory compliance and supply chain traceability requirements sustain baseline demand across pharmaceuticals and food packaging.
- Industrial Marking:Permanent part identification for aerospace, medical device, and automotive components faces ISO certification requirements that validate print durability.
Custom Branding retains volume leadership; Product Decoration holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in direct-to-shape inkjet equipment tilt toward net-importing industrial clusters, with Germany and the United States absorbing the highest unit volumes while China and Japan anchor component and printhead export positions.
United States
Beverage co-packers and contract decorators drive equipment procurement to eliminate pre-printed label inventories. FDA substrate-contact migration limits for food-contact packaging extend qualification timelines for new UV ink formulations. California and Illinois industrial corridors concentrate adoption among mid-sized decorators seeking operational expenditure predictability through leasing structures.
Germany
Automotive tier-one suppliers and premium cosmetics contract manufacturers sustain demand for multi-station parallel processing architectures. ECHA REACH Annex XVII restrictions on benzophenone and ITX photoinitiators compel systematic ink chemistry redesign. Stuttgart and Munich industrial hubs concentrate specification authority for interior trim and exterior badging applications.
China
Domestic manufacturing scale and component labeling investments respond to electronics supply chain regionalization. GB standards and MIIT industrial policy shape equipment certification pathways. Yangtze River Delta and Pearl River Delta manufacturing belts concentrate printhead assembly and UV chemistry production for regional export.
Japan
Precision component manufacturers prioritize piezoelectric drop-on-demand systems for textured effects on curved substrates. METI industrial technology roadmaps influence R&D allocation toward multi-layer ink deposition. Kansai and Chubu industrial regions anchor development of variable droplet volume control mechanisms.
India
Electronics component labeling and device housing personalization accelerate under PLI scheme incentives for domestic manufacturing. BIS certification requirements and DGFT import regulations shape equipment sourcing decisions. Maharashtra and Karnataka industrial corridors concentrate contract manufacturer investments where direct-to-shape personalization replaces imported pre-printed housings.
Direct-To-Shape Inkjet Printers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in printhead and ink chemistry supply. Market structure tilts toward consolidated equipment-ink integration among top-tier suppliers, with mid-cap decorators accessing technology through leasing and managed service contracts. Two strategic archetypes dominate: integrated platform vendors with captive chemistry capabilities, and specialized component houses supplying drop-on-demand mechanisms to third-party assemblers. Competitive moves concentrate on backward integration into photoinitiator supply and geographic expansion through local assembly partnerships.
Within the integrated platform tier, Xerox Corporation and Roland DG Corporation exemplify divergent capital deployment strategies. Japanese precision engineering houses, represented by Mimaki Engineering Co., Ltd., occupy positions emphasizing multi-layer deposition R&D for textured surface finishing. These three anchors illustrate how equipment financing arms, compact system specialization, and intensive materials science investment respectively define competitive positioning without requiring uniform scale or scope.
| Leading Market Players |
|---|
| Xerox Corporation |
| Roland DG Corporation |
| Mimaki Engineering Co., Ltd. |
| Xaar plc |
| Durst Group |
| EFI |
| Canon Inc. |
| Seiko Epson Corporation |
| Koenig & Bauer AG |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's container rate volatility feeds directly into landed equipment costs for UV inkjet systems, amplifying price spreads between German-engineered multi-station architectures and Asian-assembled compact units while forcing decorators to choose between premium captive-ink bundles and third-party chemistry sourcing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with multi-station parallel processing systems commanding substantial premiums over single-station alternatives. Price differentiation stems from ISO print quality certification tiers and after-sales service bundling, with certified 1200 dpi resolution systems carrying material premiums. Cost compression in the economy tier is intensifying because photoinitiator supply bottlenecks are squeezing standalone ink houses. Mid-sized contract decorators exhibit the highest price sensitivity, while automotive tier-one suppliers prioritize operational expenditure predictability over capital ownership.
Supply Chain Analysis
Photoinitiator feedstock production clusters in Germany and China, with specialty acrylate monomer synthesis concentrated along the Yangtze River Delta and the Rhine-Ruhr chemical belt. Printhead manufacturing draws from Japanese precision component houses and German automation specialists, while UV LED curing module assembly rests on Taiwanese semiconductor foundries. Single-source vulnerability in benzophenone derivatives exposes formulators to input cost volatility. Distribution runs through equipment financiers and third-party technical service networks that have displaced OEM maintenance monopolies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational fluid dynamics expertise for drop behavior simulation on curved substrates remains scarce across traditional screen-printing workforces, creating a persistent capability gap that equipment suppliers and contract manufacturers must close through targeted hiring or acquisition.
For Market Incumbents: Harden supply chain resilience by securing captive photoinitiator production or locked long-term offtake agreements with German and Chinese specialty chemical producers. Accelerate backward integration into multi-layer ink deposition R&D to defend margin pools against emerging platform integrators. Prioritize certification investment for FDA substrate-contact compliance to extend qualification timelines as a competitive moat.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka industrial corridors present underpenetrated demand for electronics component labeling equipment serving PLI scheme beneficiaries. Target portable printer formats for retail customization activations where capital thresholds exclude incumbent multi-station systems. Pursue a print-as-a-service go-to-market angle to bypass direct hardware sales cycles and capture recurring revenue streams.
For Investors and Strategic Acquirers: ECHA REACH Annex XVII enforcement milestones reshape the acquisition landscape by forcing consolidation among standalone ink houses lacking reformulation scale. Five-to-ten year viability favors integrated equipment-chemistry platforms with demonstrated regulatory navigation capabilities. Monitor benzophenone derivative supply disruptions as an early signal of margin compression among non-integrated decorators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Captive chemistry production insulates margins from ECHA reformulation mandates and German supply concentration. |
| AI-Driven Print Optimization Partnership | Machine vision convergence enables real-time defect correction for Stuttgart automotive trim suppliers. |
| Leasing Structure Expansion | Operational expenditure models unlock mid-sized North American beverage co-packer procurement previously excluded by capex thresholds. |
| India Local Assembly Partnership | DGFT import regulations and PLI scheme incentives favor domestic manufacturing footprint for electronics labeling. |
| Multi-Layer Deposition R&D Scale-Up | Textured effects capability captures premium cosmetics contract manufacturing demand in French industrial hubs. |
Methodological Framework
Cross-validation between primary interviews with equipment R&D directors, plant engineers at automotive tier-one suppliers, beverage co-packer operations managers, and UV ink formulation chemists anchors the qualitative findings, while secondary validation draws from ECHA substance restriction databases, FDA substrate-contact guidance documents, SEC equipment manufacturer filings, and customs trade flow records. Bottom-up installation base modeling triangulates against top-down market size estimates derived from capital expenditure disclosures across the analysis window.
Calibration against historical equipment shipment data and ink chemistry volume trends informs the projection framework across hardware architecture, ink technology, end-use intensity, and geographic regulatory cluster segmentation. CAGRs were derived from fitted growth curves incorporating technology substitution rates and compliance-driven replacement cycles. Forecast inputs include photoinitiator supply elasticity and India PLI scheme beneficiary expansion trajectories.
Practitioners should monitor ECHA substance restriction amendments, FDA migration limit revisions, and photoinitiator supply disruptions for early signals of forecast deviation. Cross-checking against IHS Markit industrial equipment shipment benchmarks and Cefic specialty chemical production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
NCR Printers Market
Printers
Dot Matrix Printer Market
Printers
Global Printer Market
Printers
Refurbished Printers Market
Printers
Retail Printers and Consumables Market
Printers
Aerosol Printing and Graphics Market
Printers
Inkjet Printing Market
Printers
Global Ticket Printers Production Market
Printers
Mobile Printer Market
Printers
Laser Printer Market
Printers
Printer Ribbons Market
Printers
Production Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
India Inkjet Printer Market
Printers
Portable Printer Market
Printers
Multi-Functional Printer Market