
 Refurbished Printers Market | 2026-2036
Refurbished Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Printers Market Outlook
Modular component bundling is consolidating buyer choice around upgradeable print engines and swappable toner systems rather than all-in-one new purchases. HP Inc. leverages its captive supply of replacement parts to dominate refurbishment workflows. Epson anchors its position through proprietary ink-tank architectures that extend hardware lifecycles. Brother Industries competes on geographic proximity, sustaining dense service networks across North American and European repair corridors.
Refurbished printers are previously owned printing devices restored to functional condition through component replacement, firmware updates, and print-quality calibration to meet original performance specifications such as ISO/IEC 24734 page-per-minute standards. These units serve commercial and institutional buyers seeking document output capability without new-equipment capital expenditure. Laser units occupy the largest installed base among product types due to enterprise durability and higher residual value after initial use cycles. Small businesses within the customer type dimension represent the fastest-growing procurement pool as operating-cost sensitivity intensifies. Network-enabled technology configurations command margin premiums over USB-only counterparts by supporting multi-device office integration.
The EPA administers e-waste handling standards that shape refurbishment facility certification requirements across the United States. REACH compliance in Europe restricts certain substances in replacement plastics and circuit boards, elevating material sourcing costs for remanufacturers. India's E-Waste Management Rules impose extended producer responsibility obligations that OEMs must address through authorized refurbishment partnerships. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven margin erosion in cross-border resale channels.
Market Dynamics
Extended producer responsibility mandates across the European Union and India are forcing printer manufacturers to formalize refurbishment partnerships, transforming aftermarket channels from gray-market arbitrage into regulated, OEM-sanctioned supply streams.
Growth Catalysts
- REACH compliance in Europe:Substance restrictions on replacement plastics and circuit boards are compelling remanufacturers to professionalize material sourcing, raising entry barriers for informal operators and consolidating volume with certified facilities.
- Educational institutions:Budget compression across public school districts and universities in the United States, Germany, and India is redirecting capital expenditure toward refurbished laser units that meet ISO/IEC 24734 performance standards at reduced acquisition cost.
- Modular ink-tank architectures:Proprietary refillable systems are extending hardware lifecycles beyond traditional cartridge-based obsolescence curves, creating residual value pools that feed refurbishment pipelines.
Market Restraints
- Replacement component scarcity:Captive supply of print engines and formatter boards by original equipment manufacturers concentrates upstream control, limiting independent remanufacturer access to critical subassemblies.
- Firmware authentication protocols:Chip-level security updates in newer printer generations are rendering third-party refurbishment technically infeasible without OEM authorization, compressing addressable hardware vintages.
- Cross-border regulatory divergence:India's E-Waste Management Rules impose documentation requirements incompatible with European WEEE traceability standards, fragmenting resale channels and elevating compliance overhead.
Strategic Opportunities
- Small business segment expansion:Operating-cost sensitivity among sub-50-employee firms in the United States is creating demand for network-enabled refurbished units with managed print service bundling.
- EU Green Deal circularity incentives:Public procurement guidelines favoring remanufactured electronics are opening institutional tender channels previously reserved for new-equipment vendors.
- Cloud-based fleet management convergence:Integration of refurbished hardware with subscription-based print analytics platforms is expanding into commercial real estate and coworking verticals.
Industry Challenges
- Technician certification bottlenecks:Print-quality calibration and firmware-level repair require specialized training that outpaces vocational program output in key refurbishment corridors.
- Legacy network security integration:Older refurbished units lack embedded encryption standards required by HIPAA and GDPR-mandated data handling environments, limiting addressable healthcare and legal verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Printers Market |
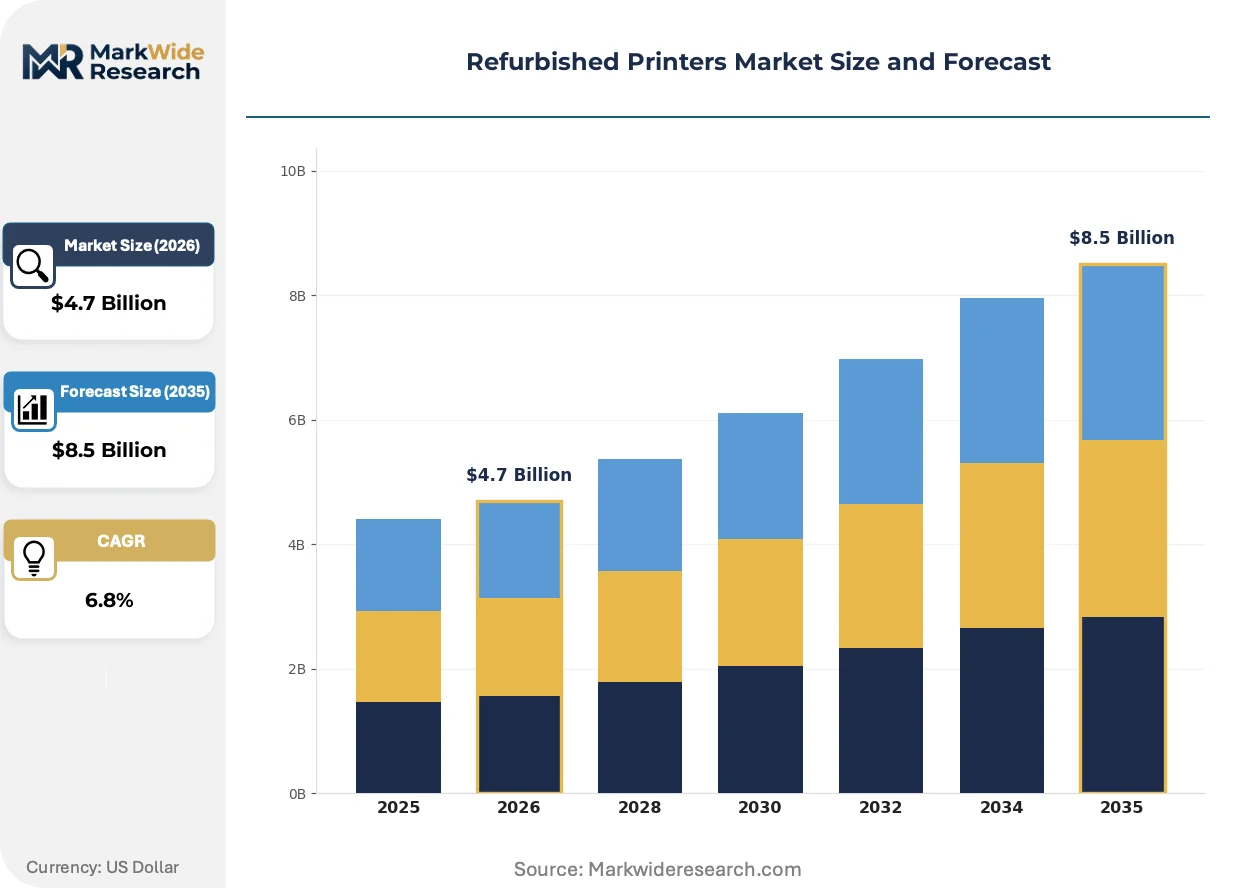
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser, Inkjet, Dot Matrix, Thermal Technology: Wi-Fi, USB, Network, Bluetooth Customer Type: Small Businesses, Enterprises, Educational Institutions, Home Offices Distribution Channel: Online Retailers, Direct Sales, Resellers, Auction Platforms |
| Companies Covered | Epson, Brother Industries, HP Inc., Konica Minolta, Ricoh Company, Ltd., Xerox Corporation, Lexmark International, Kyocera Document Solutions, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Printers Market Strategic Shifts
Refurbishment workflows are converging with predictive diagnostics and circular supply chain orchestration, compressing restoration cycle times while expanding the economically recoverable hardware pool.
Cloud-connected print fleet analytics is expanding into refurbishment operations. Embedded sensors in laser engines now transmit page-count, toner density, and fuser temperature data to centralized platforms. Remanufacturers in Germany and the United States are adopting these feeds to triage incoming hardware and pre-position replacement components. This telemetry-driven triage is expanding into warranty-backed refurbishment tiers that command margin premiums over as-is resale.
India's E-Waste Management Rules are mandating authorized collection center networks for electronics producers. Printer OEMs must now document end-of-life handling through certified refurbishment partners or face extended producer responsibility penalties. This regulatory scaffolding is compressing informal recycler market share and consolidating volume with facilities capable of generating mandatory audit trails. Compliance infrastructure investments are elevating per-unit restoration costs.
Subscription-based procurement models are displacing outright purchase in North American small business segments. Managed print service providers bundle refurbished hardware with per-page billing and remote monitoring, unbundling capital expenditure from operational budgets. Educational institutions and municipal governments in the United States are piloting these arrangements to circumvent biennial appropriation cycles. Channel intermediaries capturing these contracts are backward-integrating into refurbishment capacity to secure hardware supply.
Refurbished Printers Market Segmentation
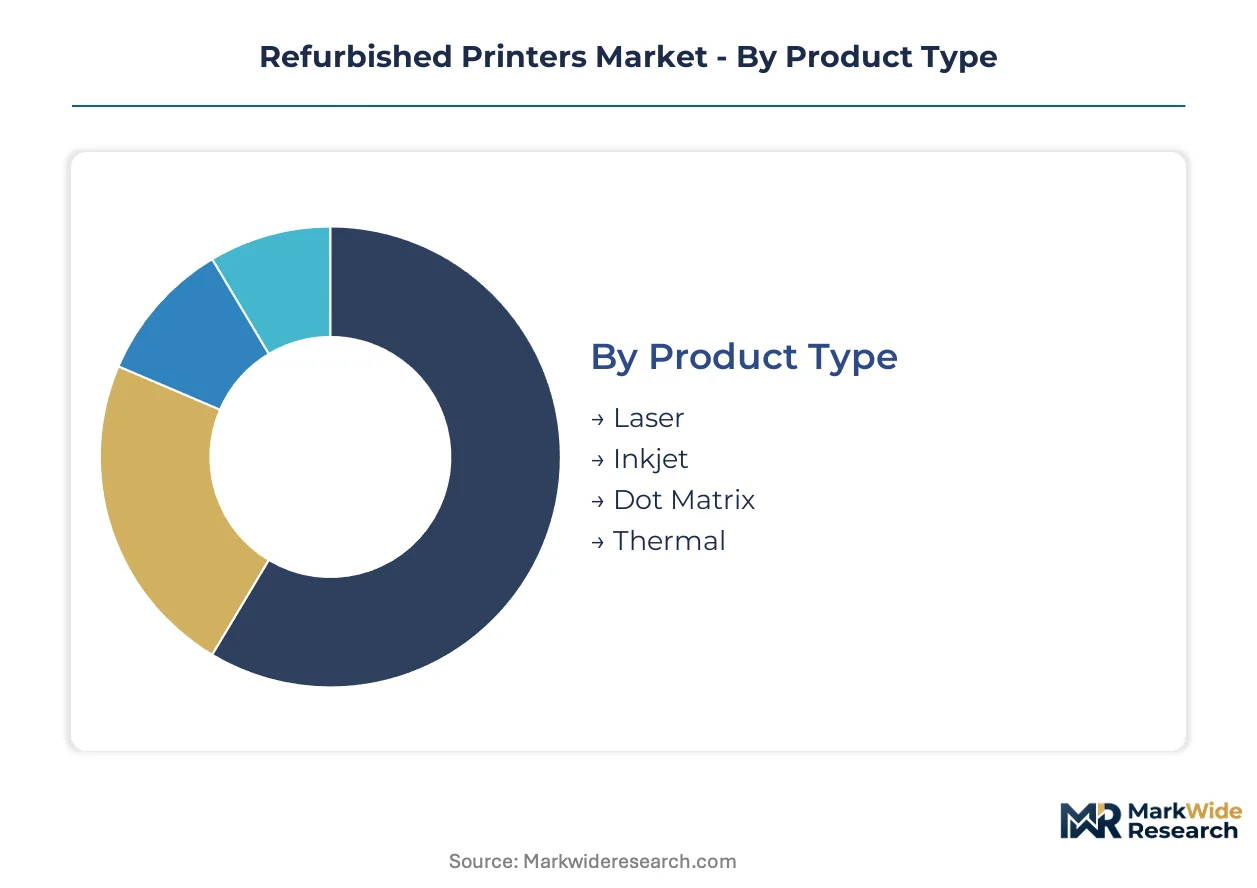
Segmentation in refurbished printers reveals how residual value concentrates in durable hardware architectures and which procurement channels capture price-sensitive demand. Understanding these splits enables vendors to align refurbishment intensity with buyer willingness to pay for performance certification.
Product Type:
Laser units command volume leadership while inkjet systems trade at premium recoveries where proprietary tank architectures extend serviceable life.
- Laser:Enterprise-grade toner engines with fuser assemblies rated for high page volumes dominate refurbishment pipelines. Demand concentrates among United States school districts and German municipal offices seeking ISO/IEC 24734 certified output without capital expenditure.
- Inkjet:Proprietary refillable tank systems from Epson and HP extend hardware lifecycles beyond traditional cartridge obsolescence curves. Recovery economics in India favor these units where OEM-authorized refurbishment partnerships satisfy E-Waste Management Rules documentation requirements.
- Dot Matrix:Impact printing mechanisms serve legacy industrial applications requiring multi-part form output.
- Thermal:Receipt and label printing hardware with limited component interchangeability occupies niche refurbishment channels.
Mature deployment sits with Laser. Newer deployment is concentrated in Inkjet.
Technology:
Connectivity specifications determine addressable buyer segments and margin capture potential across commercial versus consumer resale channels.
- Network:Ethernet-enabled configurations supporting multi-device office integration command recovery premiums over isolated peripherals. Small businesses in the United States increasingly specify these units for managed print service bundling.
- Wi-Fi:Wireless infrastructure compatibility expands placement flexibility in coworking and commercial real estate verticals where cabling constraints limit hardware positioning.
- USB:Direct-connect interfaces serve cost-minimized home office and individual workstation deployments.
- Bluetooth:Short-range pairing capabilities address mobile-first printing requirements in field service and retail environments.
Volume concentration favors Network. Steepest expansion trajectory belongs to Wi-Fi.
Customer Type:
Procurement scale and budget cycle structure create divergent refurbishment service requirements across institutional and commercial accounts.
- Small Businesses:Sub-50-employee firms exhibit acute operating-cost sensitivity and preference for subscription-based procurement that unbundles capital expenditure. United States channel intermediaries are backward-integrating into refurbishment capacity to secure hardware supply for these contracts.
- Educational Institutions:Public school districts and universities in Germany and India redirect constrained capital budgets toward certified refurbished laser units. REACH compliance and extended producer responsibility mandates elevate sourcing requirements for these institutional buyers.
- Enterprises:Fleet refresh cycles generate consistent return material flows and demand for warranty-backed refurbishment tiers.
- Home Offices:Individual procurement decisions prioritize acquisition cost minimization over performance certification.
Enterprise accounts anchor refurbishment volume. Educational Institutions are gaining share fastest.
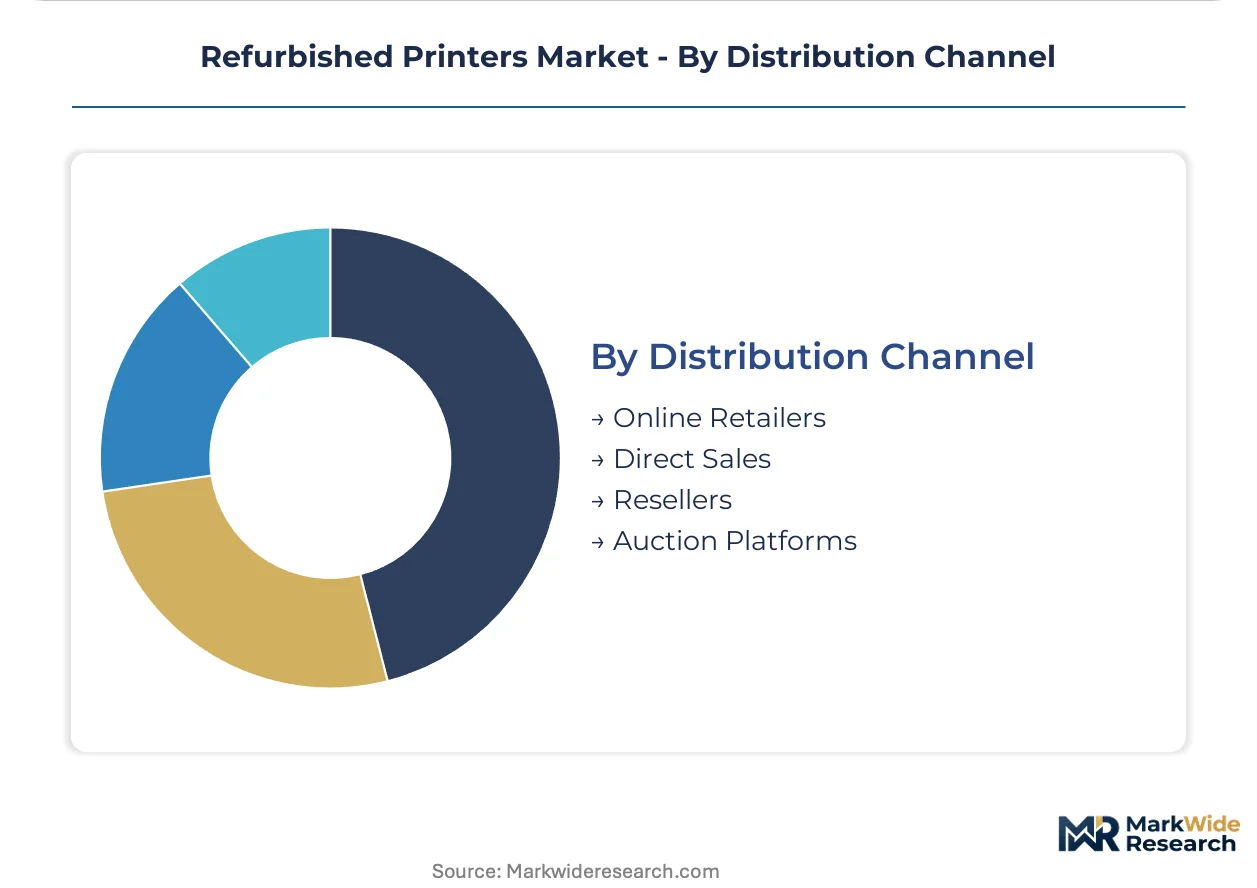
Distribution Channel:
Channel selection determines traceability compliance capabilities and buyer access to technical support infrastructure.
- Direct Sales:OEM-authorized refurbishment programs provide mandatory audit trails for India's E-Waste Management Rules and European WEEE traceability standards. HP Inc. leverages captive parts supply to dominate this channel.
- Resellers:Geographic proximity networks sustain dense service coverage across North American and European repair corridors where Brother Industries competes on technician availability.
- Online Retailers:Platform aggregation expands price discovery but fragments warranty accountability.
- Auction Platforms:As-is disposition channels capture hardware unsuitable for certified refurbishment tiers.
Direct Sales commands premium pricing. Resellers capture volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Shenzhen concentrate refurbishment capacity through tax-advantaged electronics processing clusters. These zones attract OEM-authorized facilities seeking cost-efficient restoration workflows for laser and inkjet units.
United States
School districts in Texas and California redirect capital budgets toward ISO/IEC 24734 certified refurbished laser printers as operating-cost sensitivity intensifies. EPA e-waste handling standards shape facility certification requirements across refurbishment corridors. Channel intermediaries in the Chicago and Dallas metropolitan areas backward-integrate into restoration capacity to secure hardware supply for managed print service contracts.
Germany
REACH compliance obligations elevate material sourcing costs for remanufacturers replacing plastics and circuit boards in restored units. Municipal offices in Bavaria and North Rhine-Westphalia specify refurbished equipment in public procurement tenders aligned with EU Green Deal circularity incentives. Telemetry-driven triage platforms in the Stuttgart industrial cluster compress restoration cycle times through predictive component positioning.
India
E-Waste Management Rules impose extended producer responsibility documentation requirements that OEMs address through authorized refurbishment partnerships. Educational institutions in Maharashtra and Karnataka redirect constrained budgets toward certified restored hardware. Compliance infrastructure investments in the Delhi-NCR electronics corridor consolidate volume with facilities capable of generating mandatory audit trails.
Japan
METI circular economy guidelines encourage manufacturer-led refurbishment programs for enterprise laser fleets reaching end-of-lease cycles. Corporate customers in the Kanto and Kansai regions specify warranty-backed restoration tiers for network-enabled hardware. Component recovery specialists in the Nagoya manufacturing belt extract residual value from formatter boards and print engines.
United Kingdom
WEEE traceability standards fragment cross-border resale channels with incompatible documentation requirements. Small businesses in Greater London and the Midlands subscribe to per-page billing arrangements bundling refurbished hardware with remote monitoring. Reseller networks in the Manchester logistics corridor compete on technician availability and geographic proximity to commercial accounts.
Refurbished Printers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base concentrates around original equipment manufacturers controlling captive parts supply and independent remanufacturers competing on geographic service density. Three strategic archetypes dominate: OEM-authorized refurbishment programs, independent restoration specialists, and managed print service providers backward-integrating into hardware supply. Competitive moves center on formalizing authorized partnerships to satisfy extended producer responsibility mandates and deploying telemetry-driven triage platforms to compress restoration cycle times.
Within the OEM-authorized tier, HP Inc., Epson, and Brother Industries anchor distinct competitive positions. HP Inc. leverages captive supply of replacement components to dominate direct sales channels requiring mandatory audit trails. Epson exemplifies proprietary architecture strategies through refillable tank systems extending hardware lifecycles beyond traditional obsolescence curves. Brother Industries occupies a position emphasizing geographic proximity and dense service network coverage across North American and European repair corridors.
| Leading Market Players |
|---|
| Epson |
| Brother Industries |
| HP Inc. |
| Konica Minolta |
| Ricoh Company, Ltd. |
| Xerox Corporation |
| Lexmark International |
| Kyocera Document Solutions |
| Canon Inc. |
| Others |
Value Chain & Pricing Dynamics
Educational procurement programs in the United States, Germany, and India anchor demand toward subscription-based pricing that unbundles capital expenditure from per-page operational costs. This buyer concentration shapes tiered pricing structures where network-enabled refurbished units with warranty-backed certification command recovery premiums over as-is USB-only counterparts.
Pricing Analysis
Short lead-time availability drives premium capture in the refurbished printer market, with educational institutions and small businesses paying markups for immediate ISO/IEC 24734 certified delivery versus accepting discounts for spot inventory with extended fulfillment windows. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because informal remanufacturers face rising REACH compliance and E-Waste Management Rules documentation costs. Small businesses exhibit the highest price sensitivity, while enterprise fleet managers prioritize performance certification over acquisition cost minimization.
Supply Chain Analysis
Print engine and formatter board supply rests on captive OEM distribution networks concentrated in China, Mexico, and the United States, where HP Inc., Epson, and Brother Industries control upstream component flows through authorized refurbishment partnerships. Critical inputs include toner cartridge assemblies, fuser mechanisms, and proprietary ink-tank architectures. Single-source vulnerability concentrates around chip-level firmware authentication protocols that render third-party refurbishment technically infeasible without manufacturer authorization. Distribution runs through OEM-direct channels for compliance-heavy institutional sales and geographic proximity reseller networks for small business volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refurbished printer market sits in a technology-transition phase where cloud-connected fleet analytics and predictive diagnostics displace legacy break-fix restoration workflows. Telemetry-driven triage platforms now compress cycle times while expanding economically recoverable hardware pools.
For Market Incumbents: Cement control over authorized refurbishment channels by deepening captive parts supply advantages and formalizing partnerships that satisfy India's E-Waste Management Rules and European WEEE traceability mandates. Invest in technician certification infrastructure to address calibration bottlenecks that constrain warranty-backed tier expansion. Firmware authentication protocols serve as the primary defensive moat against independent remanufacturer encroachment.
For New Entrants and Emerging Players: Cloud-based print fleet management integration offers a technology-first wedge into the small business segment, where subscription procurement models displace outright purchase. Target United States coworking and commercial real estate verticals with per-page billing arrangements bundling refurbished hardware with remote monitoring. Pursue backward integration into refurbishment capacity to secure hardware supply for managed print service contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor independent restoration specialists with dense service networks in North American and European repair corridors, where technician availability creates localized competitive moats. Long-term viability hinges on compliance infrastructure investments that capture volume consolidation as informal recycler market share compresses under extended producer responsibility mandates. Watch telemetry adoption rates among German and United States remanufacturers as the inflection indicator for margin expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Authorized Refurbishment Partnership Formalization | HP Inc. leverages captive parts supply to dominate direct sales channels requiring mandatory audit trails. |
| Telemetry-Driven Triage Platform Deployment | German remanufacturers compress restoration cycle times through predictive component positioning. |
| Technician Certification Infrastructure Investment | REACH compliance elevates sourcing requirements that certified facilities capture from informal operators. |
| Subscription-Based Procurement Model Expansion | United States channel intermediaries backward-integrate into refurbishment capacity for small business contracts. |
| Cloud Fleet Management Integration | Integration with print analytics platforms expands addressable commercial real estate and coworking verticals. |
Study Parameters
Trade association filings, customs and trade databases, and SEC regulatory disclosures formed the secondary backbone of this analysis. Primary interviews with refurbishment facility operators, OEM aftermarket executives, educational procurement officers, and managed print service providers combined with secondary validation to triangulate market sizing. Bottom-up unit volume estimates across laser, inkjet, dot matrix, and thermal product categories reconciled with top-down value projections derived from pricing tier analysis.
Historical trendline analysis of installed base depreciation curves and residual value recovery rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, connectivity technology, customer scale tier, and distribution channel structure. CAGRs were derived from regression analysis of replacement cycle compression and circular economy policy adoption trajectories. Forecast inputs incorporated E-Waste Management Rules compliance cost trajectories and REACH substance restriction implementation timelines.
Several conditions sit outside the modeled scope, including potential firmware lockout expansions that could render additional hardware vintages unrecoverable, and unforeseen tariff disruptions affecting cross-border component flows. Forecasts reflect assumptions about regulatory stability and OEM partnership continuity that external shocks could revise. A small set of named triggers warrants ongoing watch: chip-level security protocol evolution, extended producer responsibility mandate expansion, and cloud fleet management platform consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Global Printer Market
Printers
Dot Matrix Printer Market
Printers
Single Function Printer Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Production Printer Market
Printers
Laser Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
NCR Printers Market
Printers
Thermal Printer Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Mobile Printer Market
Printers
India Inkjet Printer Market
Printers
Mobile Photo Printer Market
Printers
Multi-Functional Printer Market
Printers
Global Ticket Printers Production Market
Printers
Continuous Inkjet Printers Market