
 Thermal and Inkjet Disc Printers Market | 2026-2036
Thermal and Inkjet Disc Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal and Inkjet Disc Printers Market Analytics
Germany is tilting toward advanced disc printer assembly capacity as industrial automation suppliers deepen local production ecosystems. Epson leverages its precision micro-piezo inkjet heritage to dominate photographic lab segments with archival-grade output systems. Primera Technology specializes in compact thermal transfer units for on-demand retail fulfillment, while Rimage Corporation anchors enterprise-scale publishing workflows through integrated robotics and direct-to-disc replication.
Thermal and inkjet disc printers are electro-mechanical devices that apply pigment or dye-based coatings onto optical media surfaces at resolutions typically ranging from 4800 dpi for inkjet systems to 300 dpi for thermal transfer, serving primary functions in product identification, archival documentation, and branded media distribution. Thermal printers occupy the highest-margin tier in manufacturing traceability applications where solvent-resistant labels withstand harsh automotive assembly environments. Inkjet printers represent the fastest-growing connectivity class as wireless-enabled models displace USB-tethered units in distributed photographic lab networks.
EPA chemical emission guidelines in the United States restrict volatile organic compounds in inkjet formulations, while REACH in Europe governs heavy metal content in thermal ribbon substrates, collectively elevating compliance costs for cross-border suppliers. FDA 21 CFR Part 11 requirements shape disc labeling validation protocols in pharmaceutical serialization chains. Stakeholders must monitor evolving GB standards from China's SAMR as domestic optical media archiving regulations tighten certification thresholds for imported printing equipment.
Market Dynamics
REACH chemical restrictions in Europe are forcing thermal ribbon and UV-curable inkjet ink reformulations, compressing supplier margins while photographic labs accelerate on-demand disc labeling adoption.
Growth Catalysts
- On-demand photographic lab adoption:Photographic labs are expanding disc labeling systems to replace pre-printed media inventories, reducing waste and enabling personalized batch runs.
- REACH chemical compliance:European ECHA mandates are driving manufacturers toward reformulated thermal ribbons and UV-curable inkjet inks, creating upgrade cycles for compliant equipment.
- Precision manufacturing clusters:Germany's industrial automation ecosystems sustain specialized printer procurement for traceability and archival documentation workflows.
Market Restraints
- Pigment input cost volatility:Specialty dye and pigment feedstocks face price instability due to concentrated chemical supplier bases in Asia.
- Optical media substitution:Cloud storage and solid-state archival systems are displacing physical disc distribution in enterprise documentation chains.
- EPA emission compliance friction:United States EPA volatile organic compound guidelines restrict inkjet formulation chemistries, elevating cross-border certification burdens.
Strategic Opportunities
- Pharmaceutical serialization mandates:FDA 21 CFR Part 11 validation protocols for disc labeling create certified equipment demand in drug distribution chains.
- UV-curable ink convergence:Hybrid thermal-inkjet systems combining instant curing with archival stability open medical imaging and legal discovery applications.
- Wireless connectivity expansion:Wi-Fi-enabled models are penetrating distributed photographic lab networks previously tethered to USB infrastructure.
Industry Challenges
- Micro-piezo nozzle calibration expertise:Precision inkjet maintenance requires specialized technicians scarce in secondary metropolitan markets.
- GB standards certification timelines:China's SAMR optical media archiving regulations impose extended equipment validation periods for imported printing systems.
- Legacy thermal ribbon inventory reconciliation:REACH-mandated formulation changes strand existing ribbon stocks, forcing write-downs during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal and Inkjet Disc Printers Market |
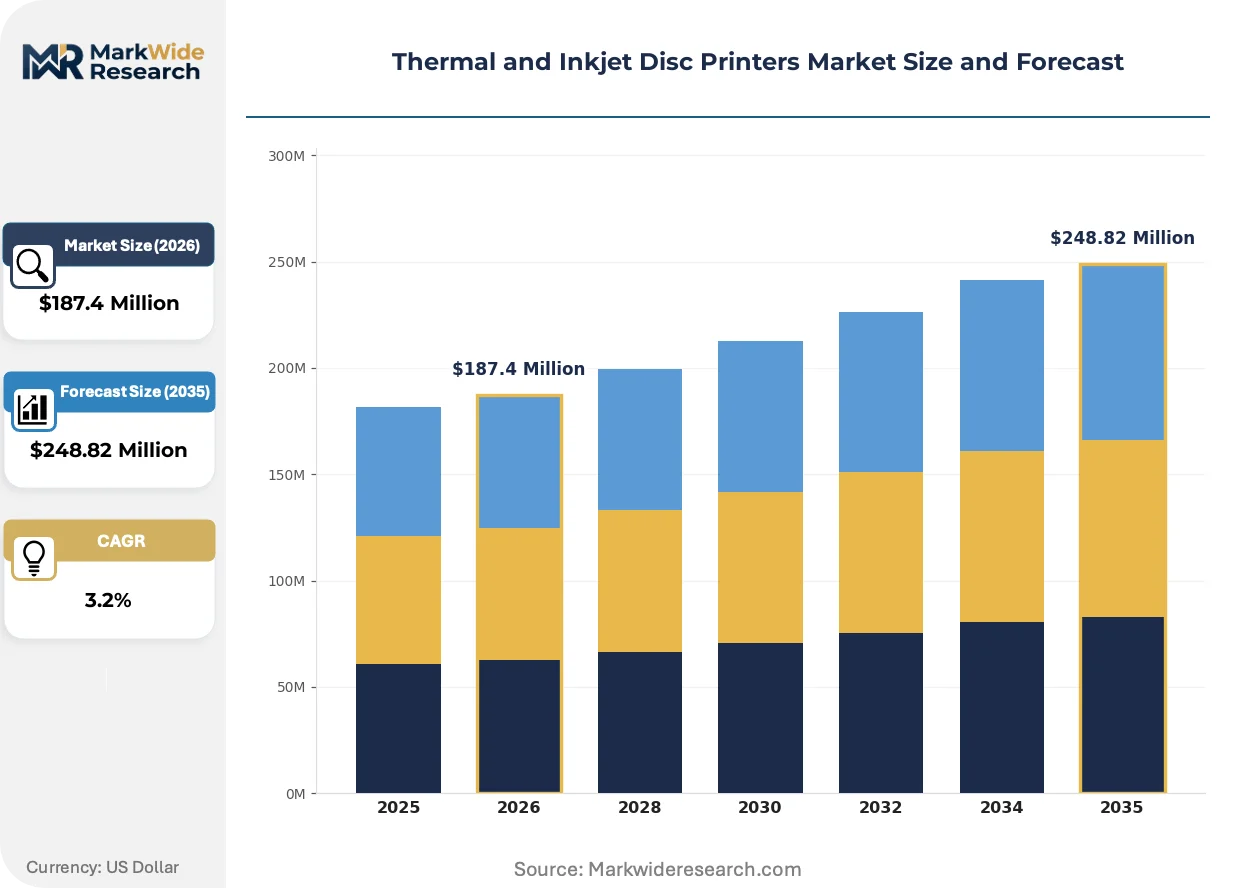
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $248.82 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Printers, Inkjet Printers, Multi-Function Printers, Label Printers End User: Retailers, Photographic Labs, Manufacturing Units, Automotive Industry Connectivity: USB, Ethernet, Wireless, Bluetooth Supply Chain: Direct Sales, Distributors, E-commerce, Retail Outlets |
| Companies Covered | Primera Technology, Rimage Corporation, Epson, Microboards Technology, Vinpower Digital, Formats Unlimited, MF Digital, Canon, HP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal and Inkjet Disc Printers Market Evolving Landscape
Disc printer architectures are pivoting toward connectivity flexibility and chemical compliance, with wireless deployment and reformulated consumables dominating supplier roadmaps.
UV-curable inkjet chemistry is virtualizing archival-grade output durability. Photographic labs in Germany and Japan are adopting these systems for 50-year fade-resistant documentation. The technology is virtualizing traditional silver-halide darkroom workflows by matching permanence standards without chemical processing infrastructure.
REACH Annex XVII restrictions on heavy metal content are reshaping thermal ribbon substrate specifications. ECHA enforcement is eliminating cadmium and lead-based compounds from transfer layers. Automotive traceability applications in Stuttgart and Wolfsburg manufacturing corridors face the steepest reformulation deadlines.
Photographic lab procurement is consolidating around equipment-as-service models. Rental and maintenance-inclusive contracts are displacing capital purchase agreements in mid-sized European studios. France and Benelux markets exhibit the fastest contract penetration, driven by cash-flow-sensitive independent operators.
Thermal and Inkjet Disc Printers Market Segmentation
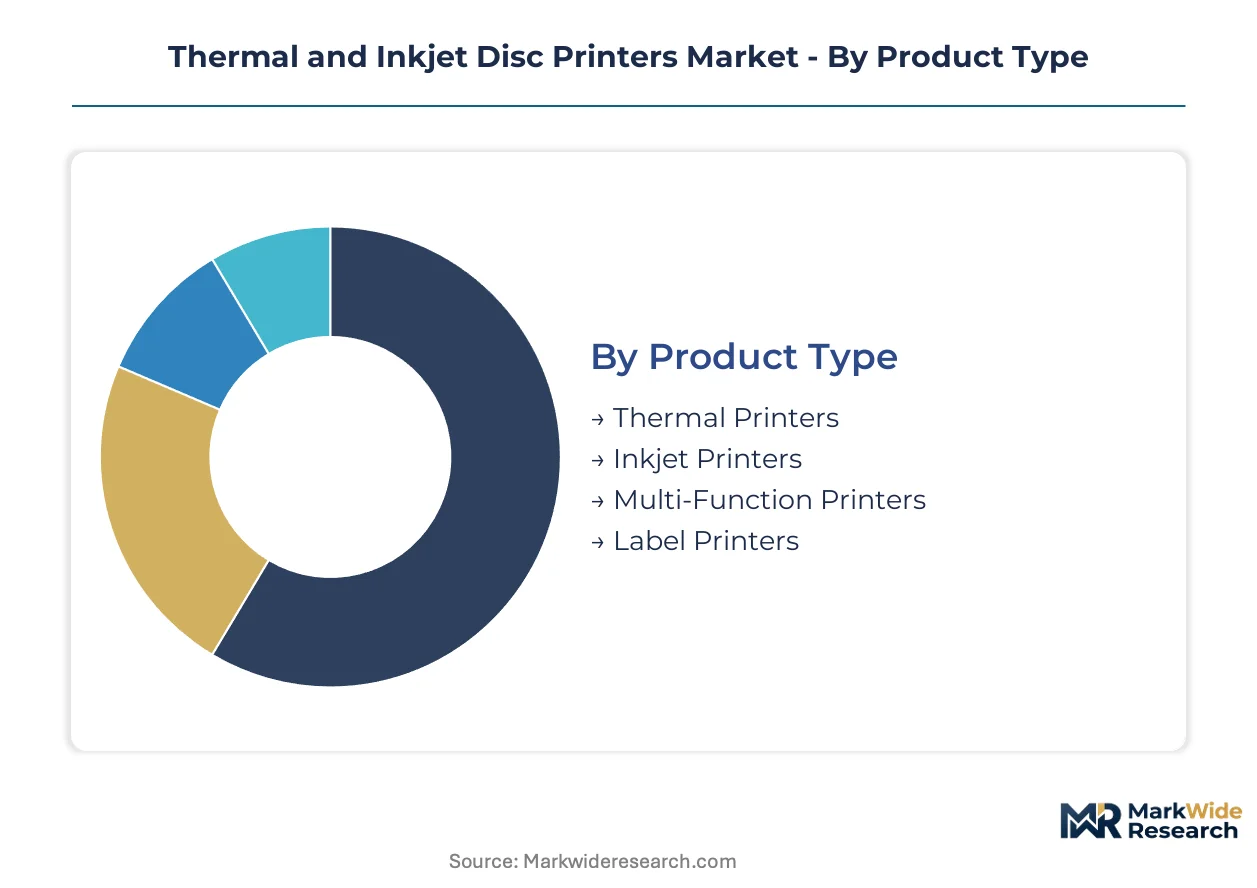
Thermal and inkjet disc printer procurement cycles vary dramatically by segment—photographic labs refresh equipment every 3-4 years while manufacturing traceability systems operate on 7-10 year horizons. Understanding these replacement rhythms shapes inventory planning and service revenue forecasting for suppliers.
Product Type:
Thermal printers turn over slowest due to ribbon standardization and mechanical durability, while inkjet systems face accelerated replacement from nozzle wear and formulation compliance mandates.
- Inkjet Printers:Micro-piezo and thermal inkjet architectures deposit aqueous or UV-curable pigments at resolutions up to 4800 dpi. Photographic labs in Germany and Japan are standardizing on these systems for archival-grade output matching silver-halide permanence standards.
- Thermal Printers:Thermal transfer and direct thermal mechanisms apply wax-resin or resin-only ribbons at 300 dpi, excelling in solvent-resistant automotive traceability applications. Stuttgart manufacturing corridors sustain demand despite REACH-mandated ribbon reformulation costs.
- Multi-Function Printers:Hybrid architectures combining disc printing with document scanning and replication serve centralized media production facilities.
- Label Printers:Narrow-format thermal units adapted for disc hub labeling address cost-sensitive retail fulfillment workflows.
Thermal printers dominate installed base in manufacturing traceability. Inkjet printers are where expansion concentrates in photographic lab networks.
End User:
Cost tiers separate capital-intensive manufacturing procurement from cash-flow-sensitive service bureau acquisitions.
- Photographic Labs:Specialized service bureaus producing personalized optical media for event photography and professional portfolios. France and Benelux markets are consolidating around equipment-as-service contracts to preserve working capital.
- Manufacturing Units:Industrial facilities embedding disc printers into quality documentation and process traceability chains. Automotive assembly plants in Wolfsburg face the steepest REACH compliance deadlines for heavy-metal-free ribbon substrates.
- Retailers:Consumer-facing storefronts offering on-demand disc duplication and labeling for memory preservation services.
- Automotive Industry:Tier-1 and OEM facilities requiring solvent-resistant archival documentation for regulatory audit trails.
Manufacturing units anchor premium pricing tiers. Photographic labs represent the fastest volume expansion as on-demand personalization displaces pre-printed inventory.
Connectivity:
Volume concentration follows infrastructure modernization cycles, with wireless deployment accelerating in distributed lab networks previously constrained by USB cabling.
- Wireless:Wi-Fi-enabled architectures supporting centralized job queue management across multi-station lab environments. Photographic networks in Germany are displacing legacy USB tethering to enable flexible floor layouts.
- Ethernet:Wired LAN connectivity serving enterprise publishing workflows requiring deterministic throughput and security hardening.
- USB:Direct host connectivity dominating entry-level installations and legacy system retrofits.
- Bluetooth:Short-range wireless for mobile-triggered printing in event photography field deployments.
Ethernet dominates enterprise installed base. Wireless connectivity is climbing the fastest as distributed lab networks modernize infrastructure.
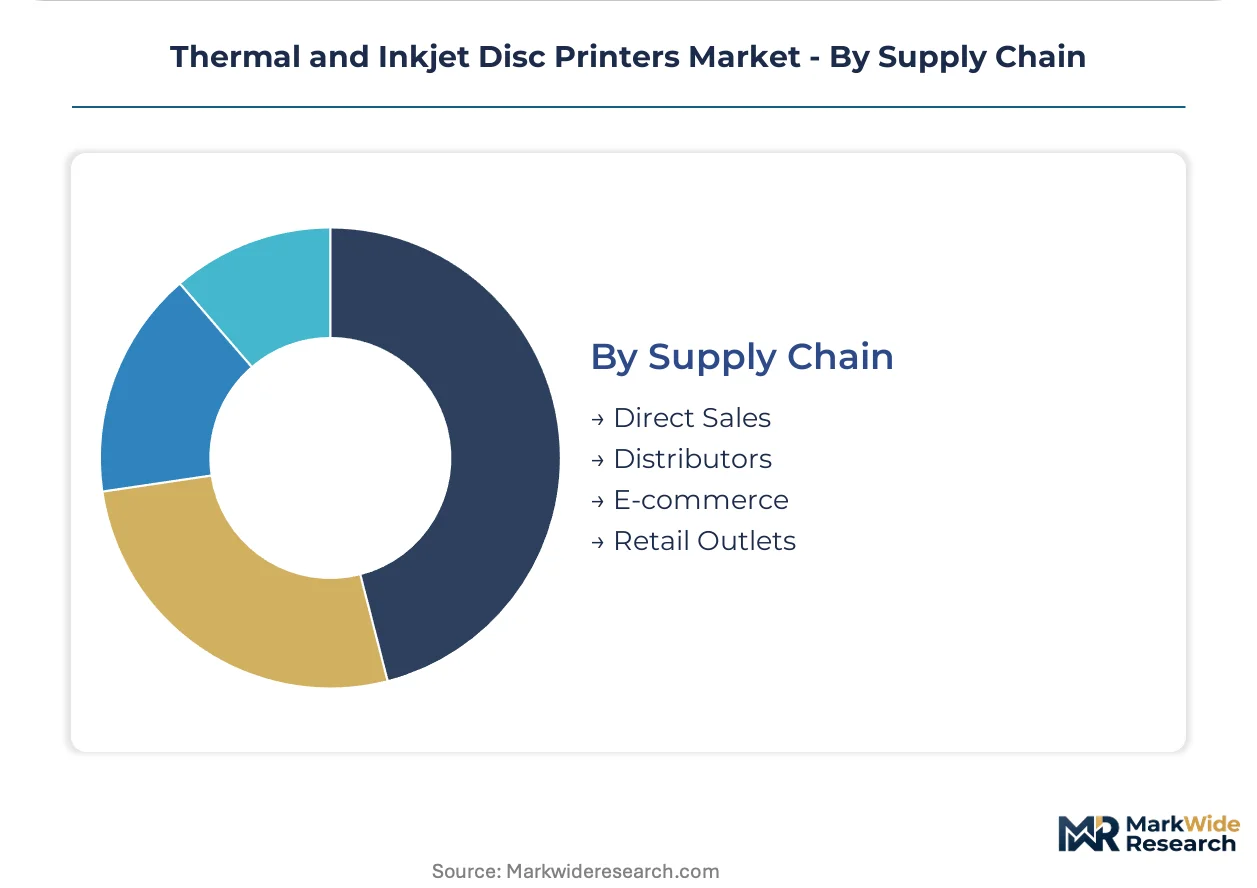
Supply Chain:
Margin structures diverge sharply by channel—direct sales capture service attachment revenue while e-commerce concentrates price-transparent consumables replenishment.
- Direct Sales:Manufacturer-led account management for enterprise publishing and pharmaceutical serialization deployments. FDA 21 CFR Part 11 validation protocols favor this channel for certified equipment procurement.
- Distributors:Regional stocking intermediaries serving mid-market photographic labs with localized technical support and spare parts availability.
- E-commerce:Online platforms concentrating price-sensitive consumables procurement and entry-level hardware transactions.
- Retail Outlets:Physical storefronts addressing immediate replacement needs and hands-on equipment evaluation for independent operators.
Direct sales command premium margins through service integration. E-commerce is gaining share fastest in consumables replenishment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH enforcement is reshaping procurement patterns across Germany's precision manufacturing corridors, while photographic lab networks in France and Japan accelerate equipment refresh cycles driven by archival compliance mandates.
Germany
Automotive traceability systems in Stuttgart and Wolfsburg manufacturing clusters sustain thermal printer demand despite REACH-mandated ribbon reformulation costs. ECHA Annex XVII restrictions on heavy metal content are eliminating cadmium and lead-based compounds from transfer layers by enforced deadlines. Precision equipment suppliers in Baden-Württemberg are deepening local assembly capacity to serve Tier-1 OEM documentation requirements.
United States
EPA volatile organic compound guidelines are restricting inkjet formulation chemistries for photographic lab networks in California and New York. FDA 21 CFR Part 11 validation protocols are driving certified equipment demand in pharmaceutical serialization chains across the Northeast corridor. Enterprise publishing workflows in Illinois and Texas maintain Ethernet-connected installed bases for deterministic throughput requirements.
Japan
METI archival permanence standards are accelerating UV-curable inkjet adoption in Tokyo and Osaka photographic service bureaus. JIS certification requirements for optical media archiving equipment are tightening import thresholds for European and American suppliers. Silver-halide darkroom displacement is concentrating demand in Kanto region labs seeking 50-year fade-resistant documentation systems.
France
Photographic lab operators in Paris and Lyon are consolidating around equipment-as-service contracts to preserve working capital against REACH compliance upgrade costs. ANSM pharmaceutical serialization mandates are creating certified disc labeling demand in drug distribution chains. Benelux-bordering studios in Hauts-de-France exhibit the fastest contract penetration among independent operators.
China
SAMR GB standards for optical media archiving equipment are imposing extended validation periods on imported printing systems entering Shanghai and Beijing markets. MIIT industrial documentation requirements sustain manufacturing traceability demand in Yangtze River Delta clusters. Domestic photographic lab networks in Guangdong are adopting wireless-enabled models to displace legacy USB infrastructure.
Thermal and Inkjet Disc Printers Market Competitive Landscape
Capability concentration sits with precision micro-piezo specialists; scale advantage sits with diversified electronics conglomerates. The vendor base organizes into three functional tiers: imaging heritage players leveraging archival-grade output expertise, compact thermal transfer specialists serving on-demand retail fulfillment, and enterprise-scale integrators anchoring automated publishing workflows. Dominant competitive moves include strategic partnerships between consumables suppliers and equipment manufacturers, plus geographic expansion into REACH-compliant European assembly capacity.
Among precision imaging specialists, Epson represents the micro-piezo heritage archetype with Japanese manufacturing roots. Primera Technology and Rimage Corporation occupy complementary positions in the compact thermal and enterprise automation segments respectively. These three anchors exemplify how vendor positioning diverges between photographic lab service models and industrial traceability applications.
| Leading Market Players |
|---|
| Primera Technology |
| Rimage Corporation |
| Epson |
| Microboards Technology |
| Vinpower Digital |
| Formats Unlimited |
| MF Digital |
| Canon |
| HP Inc. |
| Others |
Value Network & Pricing Analysis
REACH-mandated ribbon reformulation costs in Germany determine both three-tier pricing spreads across premium archival, standard manufacturing, and economy retail tiers and the geographic distribution of compliant assembly capacity toward Baden-Württemberg precision clusters.
Pricing Analysis
German procurement premiums for REACH-compliant thermal ribbons run 15-25% above Asian-sourced equivalents, while Japanese UV-curable inkjet systems command top-tier positioning against Chinese wireless-enabled economy models. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because of concentrated pigment feedstock suppliers in Guangdong. Photographic labs in France exhibit highest price sensitivity; pharmaceutical serialization chains in the Northeast United States show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for thermal ribbon substrate imports. Manufacturing concentrates in China, Japan, and Germany. Specialty dye feedstocks, micro-piezo printhead components, and UV-curable resin formulations anchor raw material dependencies. Single-source vulnerability sits with Japanese precision nozzle suppliers. Distribution runs through regional stocking distributors serving mid-market European labs alongside direct manufacturer channels for enterprise pharmaceutical deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumables-as-service contracts are expanding faster than hardware unit sales, particularly in French and Benelux photographic lab networks where working capital preservation drives procurement preference.
For Market Incumbents: Harden compliance documentation systems against ECHA Annex XVII enforcement deadlines to defend automotive traceability accounts in Stuttgart and Wolfsburg. Deepen backward integration into UV-curable resin formulation to capture margin stranded by REACH-mandated ribbon transitions. Certification investment in FDA 21 CFR Part 11 validation protocols anchors pharmaceutical serialization retention.
For New Entrants and Emerging Players: Establish a beachhead in equipment-as-service contracts for cash-flow-sensitive independent photographic labs in Hauts-de-France and Benelux border regions. Wireless-enabled compact inkjet systems for event photography field deployments represent the most penetrable white space. Channel partnership with regional consumables distributors accelerates spare parts availability credibility.
For Investors and Strategic Acquirers: Precision consumables formulators with captive REACH-compliant chemistry expertise represent the highest-conviction acquisition archetype. Long-term viability hinges on archival permanence standards displacing silver-halide darkroom infrastructure in Japan and Germany. Watch UV-curable ink adoption rates in Tokyo and Osaka service bureaus as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Consumables-as-Service Contract Expansion | Equipment-as-service models in France and Benelux preserve working capital for independent photographic lab operators. |
| REACH-Compliant Chemistry Backward Integration | In-house UV-curable resin production captures margin compression from ECHA-mandated ribbon substrate reformulations. |
| Wireless Connectivity Product Launch | Wi-Fi-enabled architectures displace USB tethering in German distributed lab networks seeking flexible floor layouts. |
| FDA 21 CFR Part 11 Certification Investment | Validation protocol compliance opens pharmaceutical serialization demand in Northeast United States drug distribution chains. |
| Regional Distributor Partnership | Localized technical support and spare parts availability penetration in mid-market European photographic service bureaus. |
Research Methodology
Cross-validation between primary interviews with consumables procurement managers at photographic labs, aftermarket service heads at industrial traceability facilities, and regulatory affairs leads at precision equipment manufacturers anchors the qualitative findings. Secondary validation draws from ECHA enforcement documentation, EPA volatile organic compound guideline releases, FDA 21 CFR Part 11 validation records, and customs trade data for thermal ribbon substrate flows. Bottom-up equipment shipment analysis and top-down consumables revenue triangulation calibrate market sizing.
Calibration against historical replacement cycle patterns across photographic lab and manufacturing traceability segments shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use application, connectivity protocol, and regional regulatory cluster. CAGRs derive from weighted average equipment refresh intervals and consumables attach rate trajectories. Micro-piezo nozzle wear rates and REACH compliance deadline schedules constitute industry-specific forecast inputs.
Stress conditions across pigment feedstock price volatility, ECHA enforcement intensity, and cloud storage substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory timeline shifts or archival permanence standard adoptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Photocopiers Market
Printers
Refurbished Printers Market
Printers
Mobile Photo Printer Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Single Function Printer Market
Printers
Printer Ribbons Market
Printers
Dot Matrix Printer Market
Printers
Global UV LED Printers Market
Printers
India Inkjet Printer Market
Printers
Nanographic Printing Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Production Printer Market
Printers
Multi-Functional Printer Market
Printers
Copier, MFP and Printer Market
Printers
Portable Printer Market
Printers
Global Printer Market