
 NCR Printers Market | 2026-2036
NCR Printers Market Size, Share, and Industry Trends Forecast 2026-2036
NCR Printers Market Foresight
Multi-source procurement for print mechanisms is broadening as retailers reduce dependency on captive hardware ecosystems. NCR Corporation leverages its installed base of POS terminals to sustain aftermarket printer revenue streams. Zebra Technologies competes through ruggedized mobile printing solutions that extend into warehouse and field service environments. Epson America anchors the inkjet segment with precision micro-piezo heads that serve high-resolution ticket and label applications.
NCR printers encompass thermal, impact, inkjet, and laser technologies purpose-built for receipt generation, transaction logging, and customer-facing documentation in high-frequency commercial environments, typically operating at 200-300 mm/s print speed with 203 dpi resolution for thermal variants. Thermal printers dominate transaction volume in quick-service restaurants and self-service kiosks where silent operation and minimal maintenance anchor total cost of ownership advantages. Impact printers retain structural demand in banking and hospitality segments requiring multi-part form duplication through carbon-copy ribbon striking. Ethernet connectivity leads wired installations, though Bluetooth and Wi-Fi configurations are gaining traction in pop-up retail and mobile POS architectures where cable routing proves impractical.
FDA guidelines for healthcare record traceability shape printer selection in pharmacy and clinical settings where timestamped hard copies support audit requirements. The EPA's energy efficiency directives influence thermal printer standby power specifications, while FCC Part 15 emissions standards govern wireless connectivity modules integrated into Bluetooth and Wi-Fi printer models. Stakeholders must weigh ribbon versus thermal total cost models against emerging digital receipt mandates that could compress hardware replacement cycles in regulated jurisdictions.
Market Dynamics
PCI-DSS compliance tightening for payment peripherals is forcing retail chains toward integrated printer-terminal bundles that bundle security certification costs into hardware procurement cycles.
Growth Catalysts
- Quick-Service Restaurant Thermal Refresh:Chains in the United States are replacing aging receipt printers to meet faster service-level agreements and reduce downtime at drive-thru lanes.
- EPA Energy Efficiency Directives:Standby power specifications for thermal printers are tightening, creating replacement demand for pre-2020 installed units that fail new consumption thresholds.
- Self-Checkout Kiosk Density:Grocery operators are expanding unmanned lane deployments, each requiring dedicated silent-operation thermal printers with minimal maintenance windows.
Market Restraints
- Digital Receipt Mandates:Jurisdictions in California and the European Union are advancing paper-reduction frameworks that threaten to compress hardware replacement cycles for physical printers.
- Thermal Paper Cost Volatility:Bisphenol-A coating regulations and pulp input price swings are squeezing consumables margins for operators running high-volume transaction environments.
- Captive Hardware Ecosystems:Legacy POS terminal vendors lock printer compatibility through proprietary firmware, limiting third-party mechanism substitution and extending incumbent replacement timelines.
Strategic Opportunities
- Mobile POS Architectures:Pop-up retail and field service segments are adopting Bluetooth and Wi-Fi printer configurations where cable routing proves impractical, opening wireless module attach-rate expansion.
- Warehouse Label Convergence:E-commerce fulfillment centers are integrating receipt and shipping label generation into unified thermal stations, extending printer utility beyond traditional transaction endpoints.
- Healthcare Traceability Requirements:FDA guidelines for timestamped hard copies in pharmacy settings are creating specification-driven procurement for audit-compliant printing infrastructure.
Industry Challenges
- FCC Part 15 Certification Timelines:Wireless printer models face extended approval cycles for emissions compliance, delaying product launches and compressing effective sales windows.
- Multi-Part Form Expertise Scarcity:Impact printer maintenance requires specialized ribbon-path calibration skills that are aging out of the technical workforce, constraining service coverage in banking and hospitality segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NCR Printers Market |
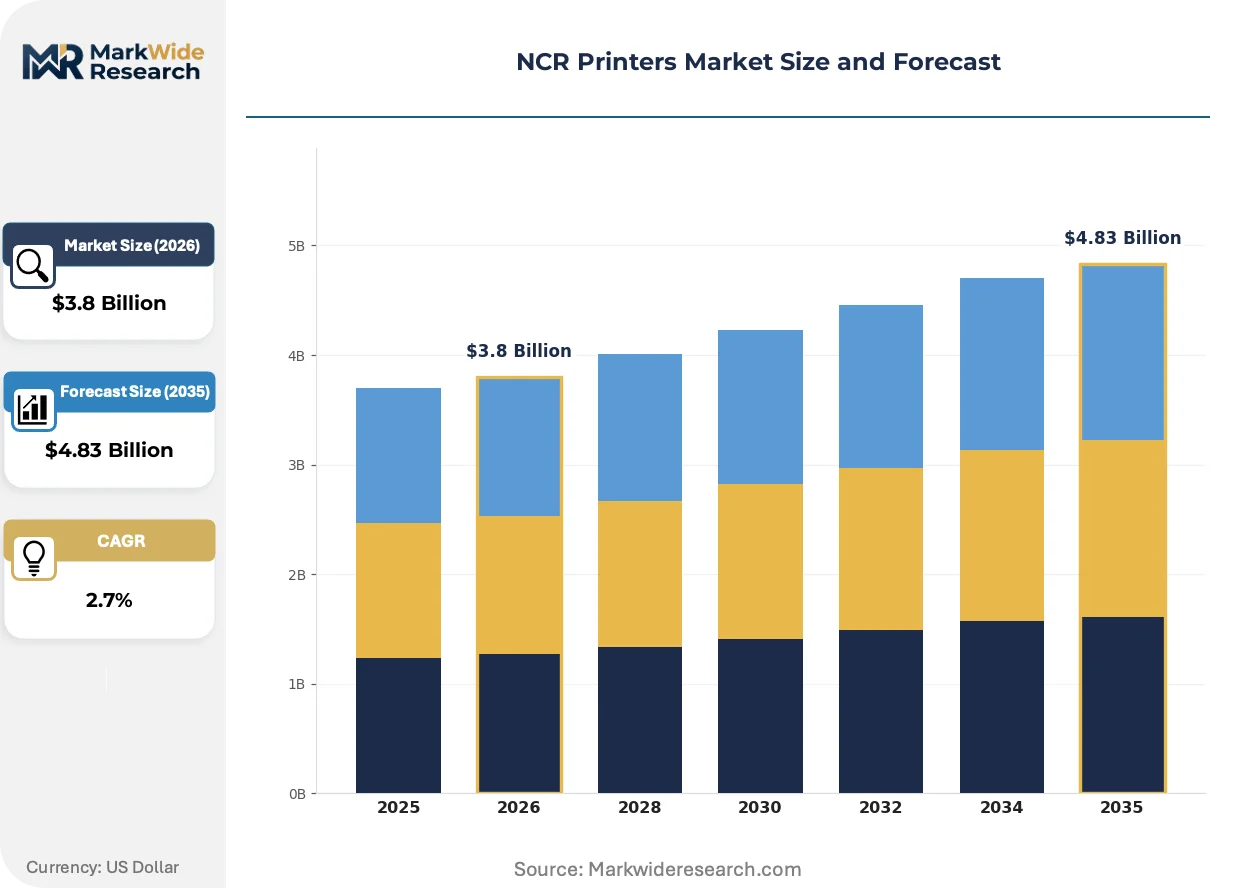
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Printers, Impact Printers, Inkjet Printers, Laser Printers End User: Retail Stores, Banks, Hospitality, Healthcare Connectivity: USB, Ethernet, Bluetooth, Wi-Fi Application: POS Systems, Self-Service Kiosks, Ticket Printing, Receipt Printing |
| Companies Covered | Epson America, Zebra Technologies, NCR Corporation, Star Micronics, Bixolon, Iconex, CDW Corporation, Citizen Systems, Diebold Nixdorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NCR Printers Market Shifts & Advancements
Hardware architectures are fragmenting as buyers demand flexible mounting, connectivity, and firmware options that decouple printer mechanisms from terminal brand loyalty.
Thermal print engines are modularizing into swappable core units that accept multiple interface boards and cutter configurations. Quick-service restaurant chains are specifying these sub-assemblies for rapid field replacement without full unit swap-outs. This architecture is modularizing procurement decisions, letting operators mix mechanism sources with terminal brands and compressing captive ecosystem lock-in.
REACH substance restrictions on thermal paper coatings are reshaping consumables supply chains across European retail and hospitality installations. Bisphenol-A alternatives are undergoing accelerated qualification timelines as distributors face liability exposure for legacy stock. Pharmacy and grocery segments in Germany and France are responding with specification clauses that mandate phenol-free coating certification for new printer deployments.
Buying committees are unbundling after-sales service contracts from hardware procurement, treating maintenance as a separate competitive bid. Large retail banners are pushing this disintermediation to drive hourly labor rate compression and parts markup transparency. This pattern is most visible among United States-based grocery cooperatives with centralized procurement functions and multi-state footprint standardization requirements.
NCR Printers Market Segmentation
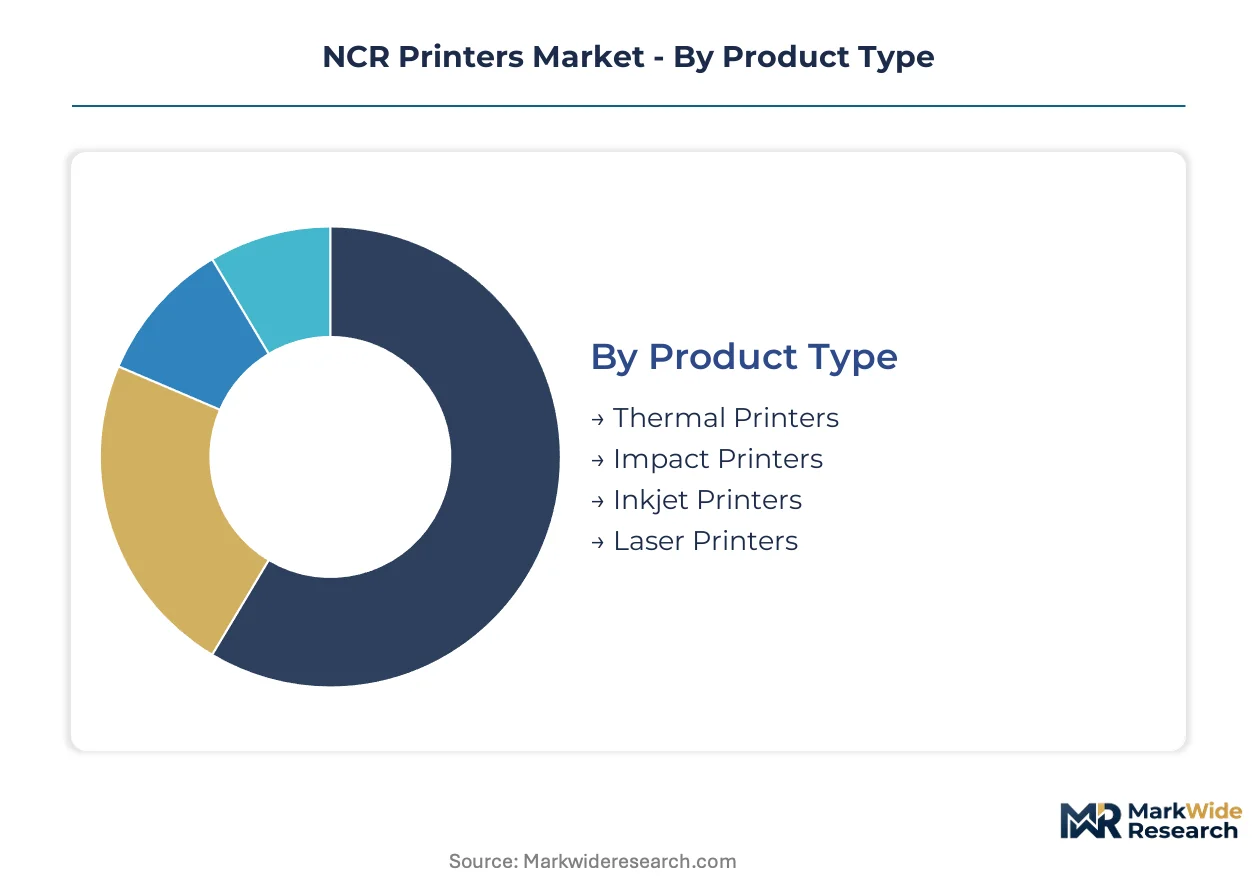
Printer selection across NCR deployments hinges on certification requirements, environmental operating conditions, and total cost models that vary sharply by transaction volume and regulatory exposure. Segmentation reveals how thermal mechanisms dominate quick-service environments while impact technologies retain structural positions in banking compliance workflows.
Product Type:
FCC Part 15 emissions certification burdens concentrate on wireless-enabled thermal variants, while EPA standby power directives apply universally across all electric printing mechanisms.
- Thermal Printers:Solid-state print heads apply heat to chemically treated paper, eliminating ribbon replacement and enabling silent operation at 200-300 mm/s. Quick-service restaurants in the United States specify these for drive-thru lanes where downtime tolerance approaches zero and PCI-DSS compliance for payment peripherals tightens.
- Impact Printers:Dot-matrix mechanisms strike carbon ribbons against paper to produce multi-part forms with physical copies. Banking operations retain these for check truncation workflows and archival requirements where digital signatures lack legal standing.
- Inkjet Printers:Micro-piezo heads deposit pigment droplets for high-resolution tickets and color-coded receipts. Pharmacy chains deploy these for medication instruction printing where legibility standards exceed thermal capabilities.
- Laser Printers:Electrophotographic drums fuse toner to paper for high-volume back-office documentation. Enterprise retail headquarters utilize these for batch report generation from centralized POS data repositories.
Thermal Printers sits at the top of the volume ranking, with Inkjet Printers climbing the fastest.
End User:
Cost tier stratification separates premium-specified healthcare installations from price-sensitive hospitality deployments with shorter replacement cycles.
- Retail Stores:Grocery cooperatives and big-box operators deploy mixed printer fleets across checkout lanes, self-service kiosks, and customer service desks. California digital receipt mandates threaten hardware replacement compression in this segment.
- Banks:Branch networks require impact printers for passbook updates and thermal units for transaction receipts. Multi-part form expertise scarcity constrains maintenance coverage as technician cohorts age out.
- Hospitality:Hotels and restaurants prioritize compact footprint and minimal acoustic signature. Thermal mechanisms dominate front-desk and kitchen printing where space constraints and noise sensitivity overlap.
- Healthcare:FDA guidelines for timestamped hard copies drive specification-driven procurement in pharmacy and clinical settings. Audit trail requirements elevate printer selection to compliance-critical infrastructure decisions.
Retail Stores commands the largest installed base, with Healthcare expanding most quickly on traceability mandates.
Connectivity:
Application architecture determines interface selection, with fixed installations favoring wired reliability and mobile deployments accepting wireless trade-offs.
- USB:Direct host connection delivers deterministic latency for single-terminal POS configurations. Small merchants and franchise operators specify these for simplicity and zero configuration overhead.
- Ethernet:Wired networking supports centralized print queue management across multi-lane retail environments. Grocery chains standardize on Power over Ethernet variants to reduce outlet dependency.
- Bluetooth:Short-range wireless enables tablet-based mobile POS without cable routing. Pop-up retail and field service segments adopt these where infrastructure permanence is absent.
- Wi-Fi:Extended range wireless supports roaming print stations in warehouse and hospitality floor plans. FCC Part 15 certification timelines delay product launches and compress effective sales windows for these models.
Ethernet leads wired deployment share, with Wi-Fi gaining share fastest on mobile architecture adoption.
Application:
Volume concentration and margin structure diverge between high-frequency transaction endpoints and specialized documentation workflows.
- POS Systems:Integrated terminal-printer bundles dominate checkout lane configurations. PCI-DSS compliance bundling forces retail chains toward certified hardware procurement cycles.
- Self-Service Kiosks:Unattended lanes in grocery and quick-service environments require vandal-resistant housings and minimal maintenance windows. Silent thermal operation prevents acoustic intrusion in customer-facing zones.
- Ticket Printing:Transportation and entertainment venues specify high-resolution output for barcode scanning reliability. Epson America anchors this segment with precision micro-piezo heads.
- Receipt Printing:Transaction documentation represents the highest-volume application across all printer technologies. Bisphenol-A coating regulations and pulp price volatility squeeze consumables margins for high-volume operators.
Receipt Printing occupies the peak volume position, with Self-Service Kiosks showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth Metroplex anchors North American NCR printer deployment density, hosting major quick-service restaurant headquarters and regional grocery cooperative procurement centers that drive thermal receipt printer refresh cycles.
United States
Quick-service restaurant chains and grocery operators in Texas, California, and Illinois dominate thermal printer procurement volumes. The EPA's standby power specifications for energy efficiency are forcing replacement of pre-2020 installed units in California and New York retail environments. The Dallas-Fort Worth corridor concentrates self-checkout kiosk deployments among regional grocery banners standardizing on silent-operation thermal mechanisms.
Germany
Pharmacy chains and grocery cooperatives in Bavaria and North Rhine-Westphalia specify phenol-free thermal paper coatings under REACH substance restrictions. The ECHA's accelerated Bisphenol-A alternative qualification timelines are reshaping consumables supply chains for retail installations. The Frankfurt-Rhine-Main cluster anchors specification-driven procurement for audit-compliant printing infrastructure in banking and healthcare settings.
China
E-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta are integrating receipt and shipping label generation into unified thermal stations. The MIIT's GB standards for wireless emissions govern Bluetooth and Wi-Fi printer module certification timelines. Shenzhen-based manufacturing clusters supply modular thermal print engines accepting multiple interface boards for rapid field replacement.
Japan
Convenience store operators and hospitality groups in Tokyo and Osaka prioritize compact footprint thermal mechanisms with minimal acoustic signatures. METI's energy efficiency directives influence standby power specifications for retail installations. The Nagoya manufacturing corridor anchors precision micro-piezo head production for high-resolution ticket applications.
United Kingdom
Banking branch networks in London and the Southeast require impact printers for passbook updates alongside thermal units for transaction receipts. The FCA's operational resilience requirements shape printer selection for audit trail documentation. The Midlands logistics corridor is adopting warehouse label convergence solutions that unify receipt and shipping label generation.
NCR Printers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular mechanism architectures that decouple print engines from terminal brand loyalty. The vendor base stratifies across three maturity tiers: legacy POS terminal vendors with captive hardware ecosystems, specialized print mechanism fabricators, and diversified electronics conglomerates with peripheral divisions. Dominant competitive moves include backward integration into thermal print head manufacturing and strategic partnerships with e-commerce fulfillment platform providers.
Within the diversified electronics tier, Epson America and Zebra Technologies exemplify scale-driven positioning across receipt and label applications. NCR Corporation anchors the legacy terminal-integrated segment, leveraging installed base density to sustain aftermarket revenue streams. These three entities represent distinct strategic archetypes: precision micro-piezo specialization, ruggedized mobility extension, and ecosystem lock-in through firmware compatibility.
| Leading Market Players |
|---|
| Epson America |
| Zebra Technologies |
| NCR Corporation |
| Star Micronics |
| Bixolon |
| Iconex |
| CDW Corporation |
| Citizen Systems |
| Diebold Nixdorf |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between PCI-DSS bundled terminal-printer systems and commodity thermal mechanisms creates parallel supply chains: premium tiers anchor through NCR Corporation and Diebold Nixdorf captive ecosystems with firmware-locked compatibility, while standard tiers fragment across Shenzhen-based modular engine fabricators serving mixed-brand deployments. This bifurcation concentrates margin capture in the certification-heavy segment while squeezing aftermarket parts pricing in the unbundled procurement channel.
Pricing Analysis
Input-cost pass-through from thermal paper coating chemistry and print head ceramic substrates shapes pricing dynamics across all tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant healthcare installations from quick-service restaurant refresh cycles and pop-up retail mobile configurations. Pricing pressure stems from REACH substance restrictions accelerating Bisphenol-A alternative qualification costs. Grocery cooperatives with centralized procurement functions exhibit highest price sensitivity; pharmacy chains facing audit liability show lowest sensitivity.
Supply Chain Analysis
Warehouse-distribution layer concentration in the Dallas-Fort Worth Metroplex, Frankfurt-Rhine-Main cluster, and Shenzhen manufacturing corridor feeds regional printer deployment density. Thermal print head ceramic substrates and micro-piezo precision components draw from Japanese and German precision manufacturing. Single-source vulnerability concentrates in thermal coating chemistry supply. Distribution runs through authorized service dealer networks for captive ecosystems and direct e-commerce fulfillment for modular mechanism substitution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in aftermarket service disintermediation and premium-tier healthcare certification capture, as EPA standby power directives and FDA traceability requirements force replacement cycles with limited price elasticity.
For Market Incumbents: Deepen backward integration into thermal print head manufacturing to reduce ceramic substrate cost exposure and accelerate PCI-DSS certification bundling. Lock channel control through firmware compatibility matrices that extend replacement timelines for legacy terminal installations. Digital receipt mandates in California and the European Union threaten hardware volume; counter through healthcare traceability specification capture. For New Entrants and Emerging Players: Capture warehouse label convergence demand in e-commerce fulfillment centers where receipt and shipping label unification creates specification white space. Mobile POS architectures in pop-up retail and field service segments offer lowest incumbent density. Pursue Bluetooth and Wi-Fi module attach-rate expansion through direct integration with tablet-based payment platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-part form expertise scarcity constrains banking and hospitality service coverage. Five-to-ten-year viability favors modular mechanism fabricators with interface board flexibility decoupled from terminal brand loyalty. Target acquisition archetype: precision micro-piezo head specialists with pharmaceutical segment penetration. Signal to watch: FCC Part 15 certification timeline compression for wireless printer launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Print Head Manufacturing | Ceramic substrate cost control reduces dependency on Japanese precision component suppliers. |
| Healthcare Certification Investment | FDA timestamped hard copy compliance elevates printer selection to infrastructure-critical procurement. |
| Modular Engine Architecture Development | Swappable core units with multiple interface boards compress captive ecosystem lock-in. |
| Wireless Module Certification Acceleration | FCC Part 15 emissions compliance compresses product launch windows for Bluetooth and Wi-Fi configurations. |
| Aftermarket Service Contract Disintermediation | Hourly labor rate transparency drives procurement committee unbundling of maintenance from hardware. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from POS terminal procurement managers at grocery cooperatives, quick-service restaurant IT directors, pharmacy compliance officers, and thermal print head manufacturing engineers. Secondary validation drew from EPA energy efficiency filings, FCC Part 15 equipment authorization databases, FDA guidance documents for healthcare record traceability, and PCI-DSS certified hardware registries. Bottom-up installation tracking and top-down vendor revenue analysis triangulated market sizing.
Comparable-period anchoring linked historical refresh cycle data to forward projection assumptions across the analysis window. Segmentation dimensions modeled include printer technology type, end-user vertical, connectivity interface, and application endpoint. CAGRs derived from unit shipment trajectories and average selling price evolution. Forecast inputs incorporated EPA standby power specification phase-in schedules and REACH substance restriction implementation timelines.
Digital receipt mandate acceleration, thermal paper coating chemistry supply disruption, and PCI-DSS compliance bundling cost inflation are the dominant revision risks. Forecasts reflect documented assumptions on replacement cycle duration and certification timeline elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
India Inkjet Printer Market
Printers
Single Function Printer Market
Printers
Continuous Inkjet Printers Market
Printers
Inkjet Printing Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Global UV LED Printers Market
Printers
Global Ticket Printers Production Market
Printers
Electrophotographic Printing Market
Printers
Thermal Printer Market
Printers
Copier, MFP and Printer Market
Printers
Dot Matrix Printer Market
Printers
Inkjet Printers Market
Printers
Photocopiers Market
Printers
Retail Printers and Consumables Market
Printers
Mobile Photo Printer Market
Printers
Global Printer Market