
 Nanographic Printing Market | 2026-2036
Nanographic Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Nanographic Printing Market Foresight
Asset-light leasing models for nanographic presses is rewriting competitive entry barriers for mid-size converters. Landa Corporation Ltd. leverages its proprietary nano-ink IP to anchor technology leadership in high-speed digital packaging. Komori Corporation sustains manufacturing scale through integrated press-and-ink supply arrangements. Sackel Corporation differentiates through specialized coating formulations that extend substrate compatibility.
Nanographic printing deposits sub-micron pigment particles in aqueous carrier fluids onto standard offset substrates, achieving lithographic resolution at digital economics. Equipment configurations dominate capital allocation, while ink formulations capture recurring margin pools as consumables scale with installed base. Packaging applications lead volume uptake, whereas labeling segments compete on shorter-run personalization requirements. Healthcare end users impose stringent extractables testing that shapes supplier qualification protocols.
EMA chemical safety assessments and REACH substance registrations constrain nano-pigment introductions across European supply chains. Germany's KBA enforces press machinery directives that affect equipment certification timelines. Stakeholders must monitor evolving nano-material toxicity classifications that could trigger reformulation mandates or restrict market access for existing product lines.
Market Dynamics
Water-based nano-ink formulations are displacing solvent-based systems across European packaging supply chains, forcing converters to reconfigure press infrastructure and recalibrate substrate pretreatment protocols under tightening chemical safety frameworks.
Growth Catalysts
- REACH substance registrations:ECHA's streamlined nano-pigment approval pathways accelerate compliant ink commercialization across German and Benelux converter networks.
- Flexible packaging demand:Bavaria's food packaging cluster drives press capacity expansion as brands mandate shorter-run, versioned label production.
- Asset-light leasing:Equipment financing models slash entry capital for mid-size converters, democratizing access to nanographic resolution capabilities.
Market Restraints
- Pigment supply concentration:Specialty nano-pigment synthesis capacity clusters in Swiss and German chemical corridors, creating single-source vulnerability for ink formulators.
- Extractables testing burden:Healthcare end-users impose pharmaceutical-grade validation protocols that extend supplier qualification timelines by 12-18 months.
- Offset lithography substitution:Conventional sheetfed offset retains cost advantage in ultra-long-run folding carton work, capping nanographic penetration in standardized packaging.
Strategic Opportunities
- Pharmaceutical serialization mandates:EU MDR and FDA track-and-trace regulations create demand for high-resolution variable data printing on secondary packaging.
- Recyclable mono-material structures:Water-based nano-inks enable fiber-to-fiber recycling compatibility that solvent systems cannot match, aligning with EU Green Deal circularity targets.
- Print-on-demand fulfillment integration:E-commerce packaging personalization converges with nanographic short-run economics, opening direct-to-consumer channel partnerships.
Industry Challenges
- Color management specialist scarcity:The intersection of inkjet physics, offset substrate behavior, and nano-pigment dispersion requires hybrid skill sets absent from conventional print training pipelines.
- Legacy workflow integration:Prepress RIP architectures designed for offset or toner digital platforms demand costly middleware adaptation to handle nanographic color space and screening algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanographic Printing Market |
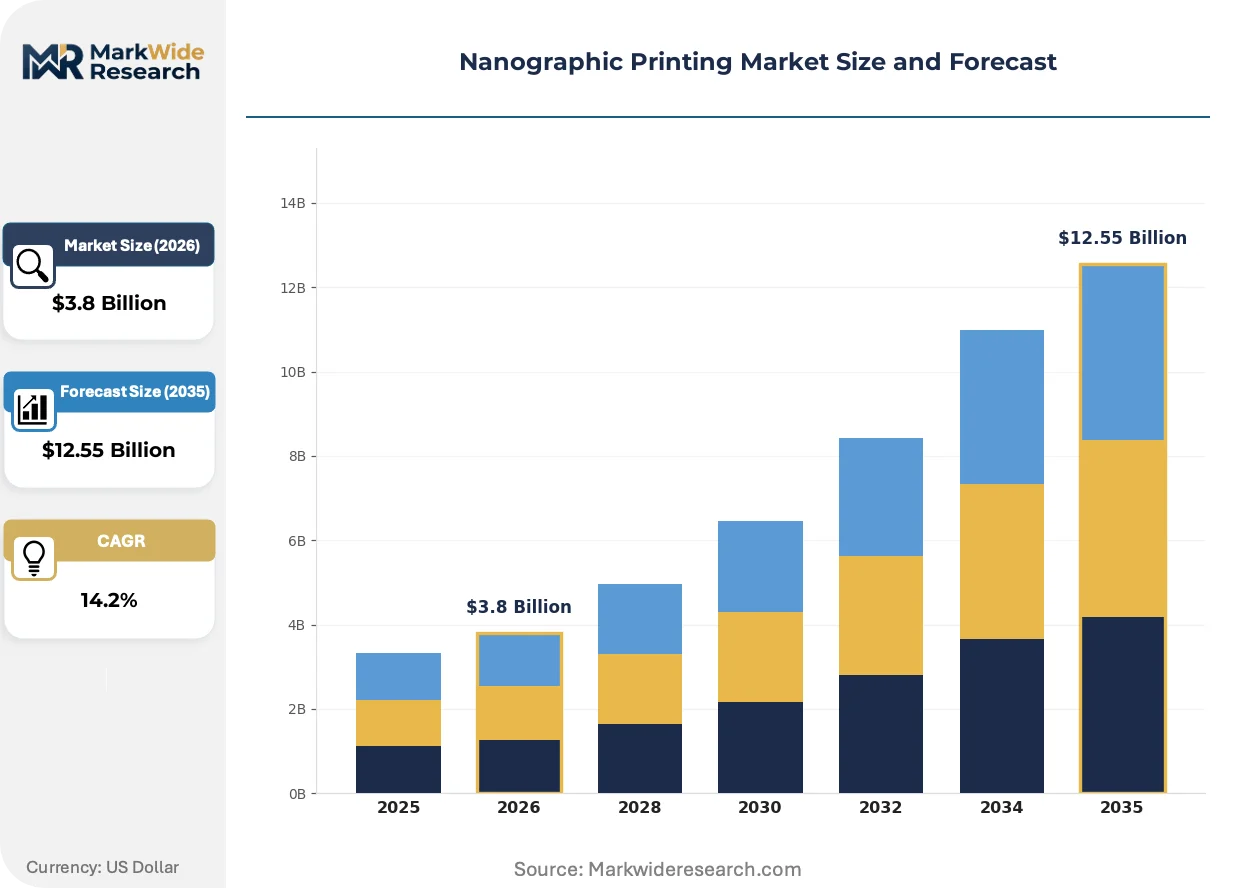
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ink, Substrate, Coating, Equipment Application: Packaging, Labeling, Commercial Printing, Textiles End User: Consumer Goods, Healthcare, Automotive Parts, Electronics Technology: Digital Offset, Flexographic, Inkjet, Screen Printing |
| Companies Covered | Landa Corporation Ltd., Komori Corporation, Sackel Corporation, Quantum Group, Mitchell Press Ltd., Flint Group, Quad, WestRock Company, Edelmann GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanographic Printing Market Shifts & Advancements
Convergence between digital printhead engineering and conventional offset mechanical infrastructure is collapsing the historical trade-off between lithographic quality and digital flexibility, reshaping capital deployment patterns across packaging supply chains.
Nanographic deposition systems is hybridizing aqueous inkjet precision with offset substrate compatibility, enabling 1200 dpi resolution on uncoated stocks previously restricted to gravure or flexo. Pharmaceutical and cosmetics packagers in the Rhine-Main corridor adopt these hybrid configurations fastest, compressing makeready waste from hundreds of sheets to single-digit counts while maintaining brand-color consistency.
ECHA's evolving nano-material toxicity classifications under REACH Annex revisions force ink formulators to pre-register novel pigment chemistries before commercial deployment. The regulatory friction most acutely affects metallic and pearlescent nano-pigments destined for luxury packaging, driving suppliers toward predictive toxicology investments and early regulatory engagement.
Converter procurement behavior is fragmenting across equipment-as-a-service contracts and traditional capital purchase models, with mid-tier packaging firms favoring per-impression pricing that transfers obsolescence risk to OEMs. Germany's Mittelstand converters exhibit this preference most prominently, pressuring vendors to develop residual value guarantees and remote diagnostics capabilities as competitive prerequisites.
Nanographic Printing Market Segmentation
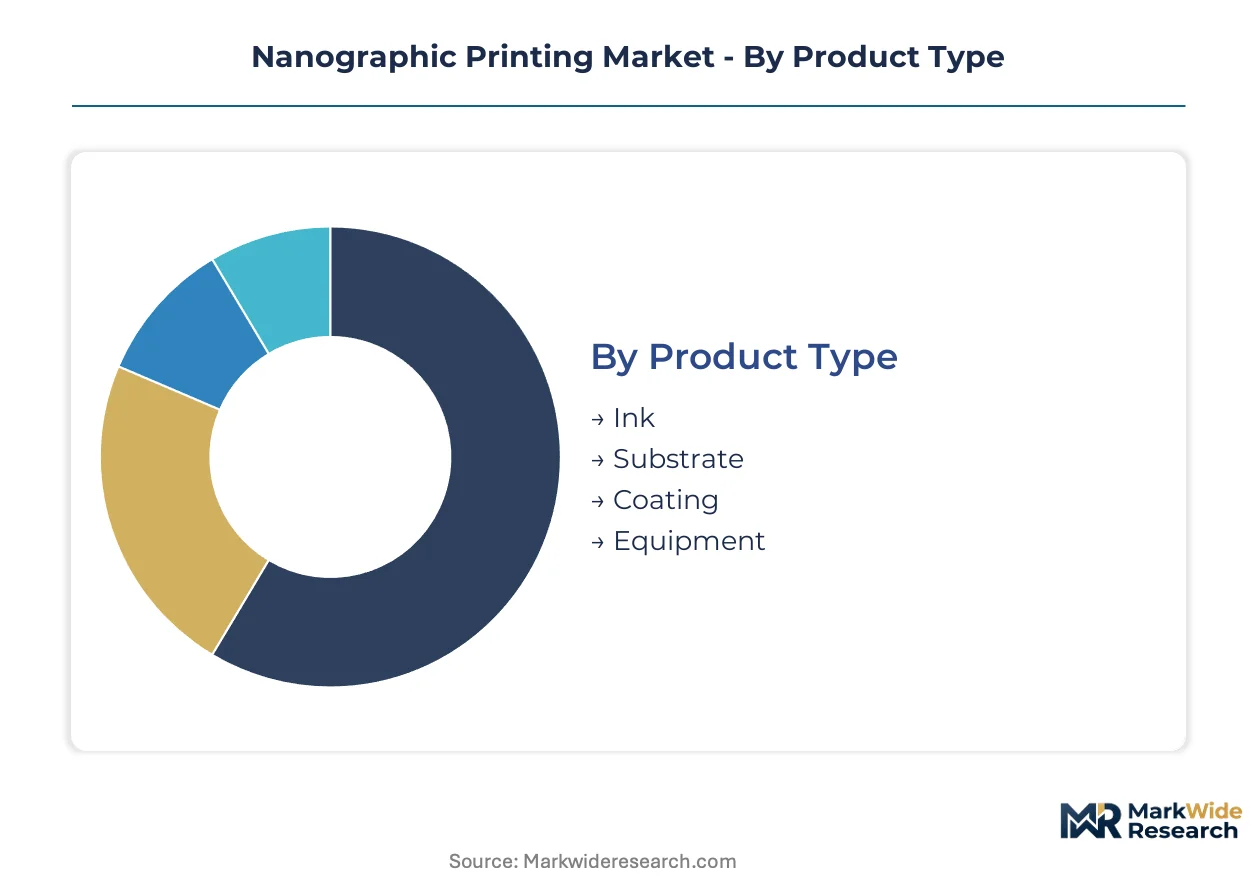
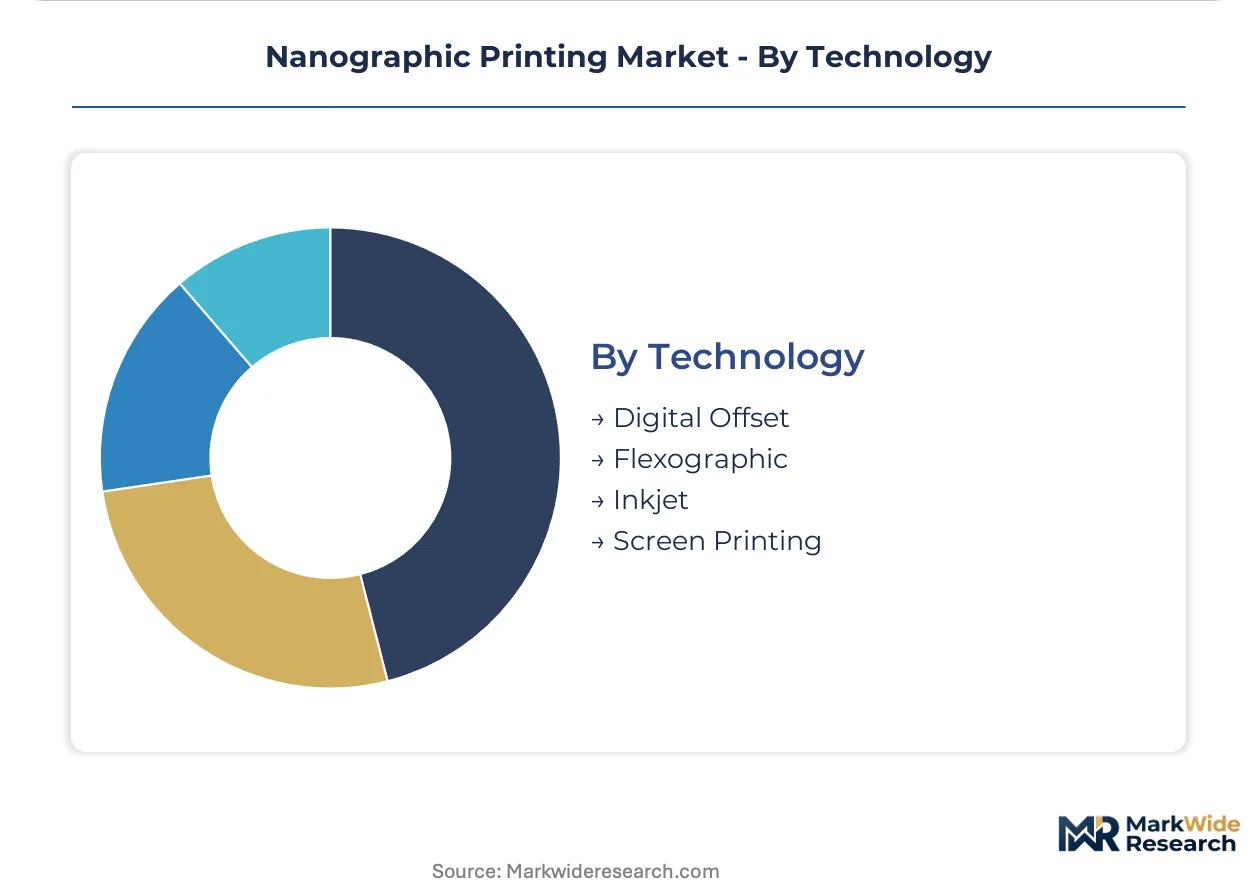
Nanographic printing crosses multiple substrate chemistries, deposition technologies, and end-use compliance regimes. Segmentation clarity enables converters to match capital deployment against specific margin pools and regulatory exposure.
Product Type:
Use-case spectrum spans consumable replenishment cycles through capital equipment depreciation horizons.
- Ink:Water-based nano-pigment suspensions with sub-micron particle distribution determine color gamut and substrate adhesion. Bavaria's flexible packaging cluster drives formulation demand under ECHA substance registration requirements, with REACH compliance timelines constraining new pigment commercialization.
- Equipment:Hybrid press configurations integrating inkjet deposition modules with offset mechanical infrastructure dominate capital allocation. Rhine-Main industrial corridor converters favor configurations with remote diagnostics capabilities and residual value guarantees from OEMs.
- Substrate:Uncoated and lightly coated papers engineered for aqueous ink absorption without pretreatment.
- Coating:Functional topcoats enabling barrier properties or tactile finishes on printed surfaces.
Established volume favors Equipment; emerging adoption favors Ink.
Application:
Cost tier separation runs from mass-customized short runs to pharmaceutical serialization mandates.
- Packaging:Folding cartons, flexible films, and corrugated secondary packs requiring versioned graphics at mid-scale volumes. Germany's food packaging cluster compresses makeready waste through nanographic makeready cycles measured in single-digit sheet counts.
- Labeling:Pressure-sensitive and shrink-sleeve formats demanding variable data integration. EU MDR track-and-trace regulations for pharmaceutical serialization expand addressable demand in the Rhine-Main corridor.
- Commercial Printing:Marketing collateral and publication segments competing with toner digital and sheetfed offset.
- Textiles:Direct-to-fabric deposition for soft signage and apparel prototyping.
Volume concentration sits with Packaging; margin expansion favors Labeling.
End User:
Customer type fragmentation reflects divergent qualification burdens and extractables testing protocols.
- Healthcare:Pharmaceutical and medical device packaging requiring US FDA and EU MDR compliance documentation. Extractables validation protocols extend supplier qualification timelines by 12-18 months, creating defensive moats for qualified ink formulators.
- Consumer Goods:Food, beverage, and personal care brands in Bavaria's packaging cluster. EU Green Deal circularity targets drive preference for water-based systems enabling fiber-to-fiber recyclability.
- Automotive Parts:Under-hood labels and interior trim components with thermal and chemical resistance requirements.
- Electronics:Membrane switches and decorative fascia requiring precise registration on engineered substrates.
Regulatory intensity favors Healthcare; volume scale favors Consumer Goods.
Technology:
Maturity gradient separates proven mechanical platforms from emerging deposition physics.
- Digital Offset:Hybrid architectures combining offset substrate handling with inkjet precision. Landa Corporation's proprietary nano-ink IP anchors this configuration's resolution capabilities on uncoated stocks previously restricted to gravure.
- Inkjet:Piezoelectric drop-on-demand systems adapted for aqueous nano-pigment rheology. Komori Corporation's integrated press-and-ink supply arrangements sustain manufacturing scale for this technology tier.
- Flexographic:Rotary relief printing adapted for nano-pigment transfer in corrugated and flexible film applications.
- Screen Printing:Stencil-based deposition for thick-film and specialty coating requirements.
Technology leadership concentrates in Digital Offset; Inkjet claims steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a net export position in nanographic printing equipment and consumables, while the United States and China remain primary import destinations for high-resolution digital packaging systems. Trade flows concentrate through specialized machinery corridors linking European OEMs to Asian converter networks.
Germany
Bavaria's food packaging cluster and the Rhine-Main industrial corridor drive press capacity expansion for flexible film converters. ECHA's REACH nano-pigment registration requirements constrain ink commercialization timelines, forcing formulators toward early regulatory engagement. Heidelberg and Stuttgart host equipment certification facilities under KBA machinery directives that govern export-ready press configurations.
United States
Pharmaceutical serialization mandates under FDA track-and-trace regulations create demand for high-resolution variable data printing on secondary packaging. The FDA's extractables testing protocols for drug-contact materials extend supplier qualification periods. Chicago and New Jersey packaging converters adopt nanographic systems to serve healthcare and cosmetics brands requiring short-run versioning.
China
E-commerce packaging personalization converges with nanographic short-run economics in the Yangtze River Delta and Pearl River Delta manufacturing belts. MIIT standards for printing machinery safety affect equipment import certification timelines. Shanghai-based converters integrate print-on-demand fulfillment systems for direct-to-consumer brand partnerships.
Japan
Precision electronics packaging in the Kanto and Kansai regions demands sub-micron registration accuracy for membrane switches and decorative fascia. METI's industrial technology roadmaps support nano-material processing innovation. Nagoya-area automotive suppliers adopt nanographic labeling systems for under-hood components requiring thermal resistance.
Switzerland
Specialty nano-pigment synthesis capacity clusters around Basel's chemical corridor, creating critical supply nodes for ink formulators across European converter networks. Swissmedic's pharmaceutical packaging regulations align with EU MDR requirements, enabling cross-border qualification reciprocity. Zurich-area technical institutes advance predictive toxicology for pigment safety assessments.
Nanographic Printing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated press-and-ink supply arrangements and proprietary nano-pigment intellectual property. Three strategic archetypes dominate: technology originators controlling deposition physics, manufacturing-scale OEMs sustaining equipment throughput, and specialized coating formulators extending substrate compatibility. Competitive moves concentrate on strategic partnerships for regulatory pre-qualification and geographic expansion through equipment-as-a-service financing models.
Within the technology-originator tier, Landa Corporation Ltd. anchors proprietary nano-ink capabilities, while Komori Corporation exemplifies manufacturing-scale integration through its press-and-ink supply arrangements. Sackel Corporation occupies a position among specialized formulators focused on coating chemistry that expands substrate addressability. These three entities represent distinct competitive vectors: IP control, production scale, and materials specialization.
| Leading Market Players |
|---|
| Landa Corporation Ltd. |
| Komori Corporation |
| Sackel Corporation |
| Quantum Group |
| Mitchell Press Ltd. |
| Flint Group |
| Quad |
| WestRock Company |
| Edelmann GmbH |
| Others |
Supply & Pricing Matrix
Specialty nano-pigment synthesis capacity clusters in Switzerland and Germany anchor margin capture upstream, while downstream equipment leasing models redistribute pricing power toward converter networks seeking per-impression economics. This structural configuration concentrates value extraction in consumable formulations while press OEMs compete on financing innovation.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in nanographic press procurement. Price differentiation rests on certification grade under KBA machinery directives and remote diagnostics bundling. Cost compression in mid-tier equipment is intensifying because asset-light leasing spreads capital recovery across extended contract terms. Mid-size Mittelstand converters exhibit highest price sensitivity; healthcare-qualified systems command lowest elasticity due to extractables validation requirements.
Supply Chain Analysis
Extended payment terms from Swiss chemical suppliers and supply-chain finance facilities stabilize nano-pigment procurement for ink formulators facing REACH registration delays. Geographic supply concentration centers on Switzerland, Germany, and Japan for deposition module components. Raw material dependencies include aqueous resin systems, piezoelectric printhead ceramics, and barrier-coated substrates. Single-source vulnerability persists in specialty pigment synthesis. Distribution runs through integrated press-and-ink supply arrangements rather than independent channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
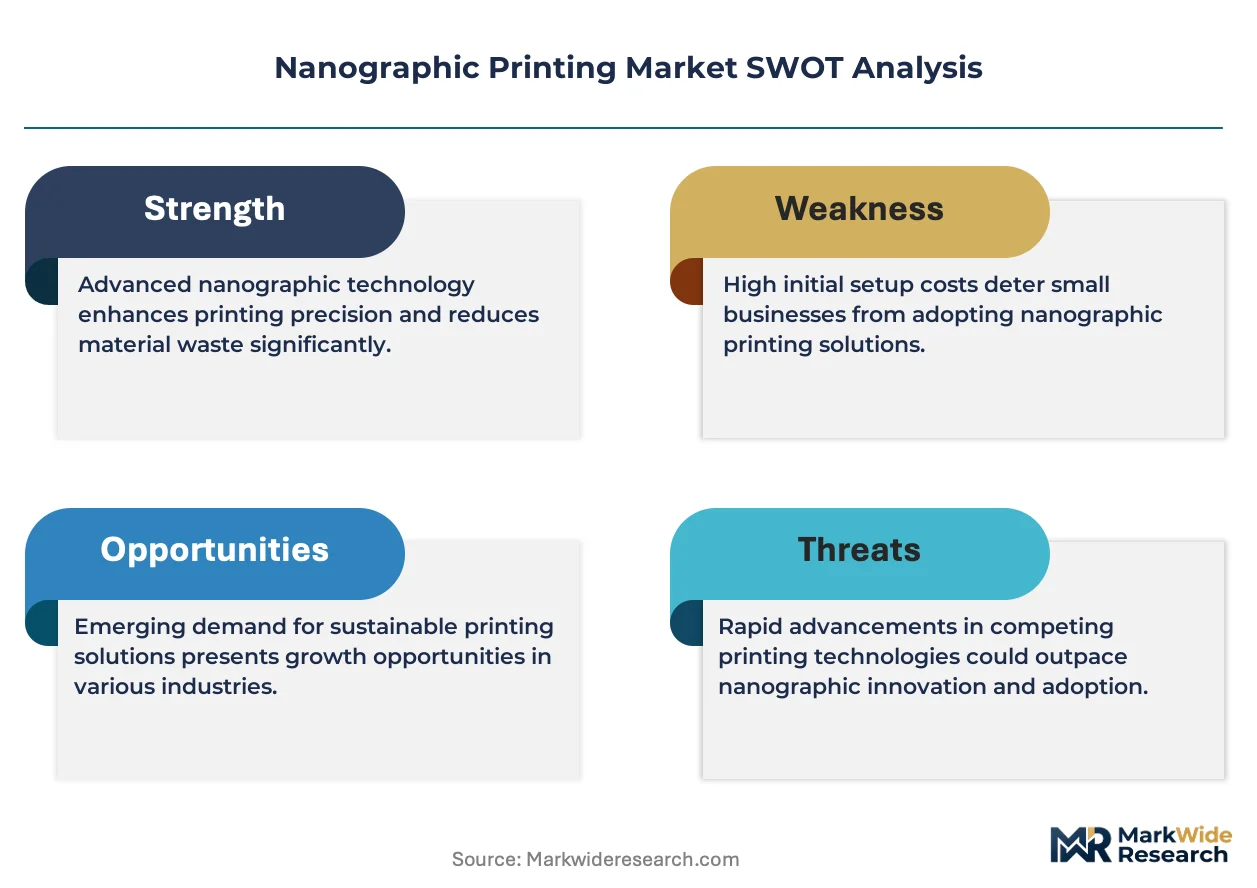
The nanographic printing market functions as a defensive-moat story where regulatory entrenchment in REACH substance registrations creates 12-18 month qualification timelines that protect incumbent ink formulators from rapid competitive displacement.
For Market Incumbents: Build switching-cost moats through early ECHA regulatory engagement and captive nano-pigment synthesis capacity. Komori Corporation's integrated press-and-ink model demonstrates how backward integration into formulation chemistry defends against pure-play equipment entrants. Expand remote diagnostics capabilities to tighten OEM-converter relationships under equipment-as-a-service contracts. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical serialization applications where FDA and EU MDR track-and-trace mandates create demand for qualified variable-data systems. The labeling segment in the Rhine-Main corridor offers lowest penetration barriers versus packaging incumbents. Pursue partnerships with established coating formulators to bypass substrate compatibility development cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed packaging converters that have deployed nanographic capacity under leasing arrangements and now seek exit liquidity. Long-term viability hinges on water-based formulation chemistry remaining compliant under evolving ECHA toxicity classifications. Monitor REACH Annex revision timelines as the critical inflection signal for reformulation risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Qualification Investment | Early ECHA engagement compresses nano-pigment commercialization timelines for compliant formulators. |
| Equipment-as-a-Service Launch | Per-impression pricing transfers obsolescence risk from Mittelstand converters to OEM balance sheets. |
| Coating Chemistry Acquisition | Specialized barrier and tactile formulations extend substrate addressability beyond standard offset stocks. |
| Pharmaceutical Partnership Program | FDA extractables validation protocols create defensive moats through extended supplier qualification cycles. |
| Predictive Toxicology Capability Build | Zurich-area technical institutes advance pigment safety assessment speed under REACH registration pressure. |
Research Methodology
A standing panel of press operations managers, ink formulation chemists, packaging procurement leads, and healthcare regulatory affairs specialists provided ongoing calibration against secondary validation from ECHA registration databases, KBA machinery directive filings, and EU MDR implementation guidance. Customs data on nano-pigment trade flows and SEC disclosures from listed OEMs supplied quantitative anchors. Bottom-up installed base estimates triangulated against top-down addressable packaging spend projections.
Scenario-bracketing around REACH enforcement intensity and leasing penetration rates bounded output ranges across the projection horizon. Segmentation dimensions modeled include product type, application, end-user compliance regime, and technology tier. CAGRs derived from logistic adoption curves fitted to press shipment data and consumable replenishment cycles. Industry-specific inputs incorporated ECHA nano-material classification timelines and FDA pharmaceutical serialization mandate compliance deadlines.
Stress conditions across pigment supply disruption, equipment financing cost spikes, and regulatory reclassification events were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about converter capex recovery rates and ink formulation margin stability. Macroeconomic contraction, unilateral REACH Annex revisions, or breakthrough deposition physics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Retail Printers and Consumables Market
Printers
Multi-Functional Printer Market
Printers
Refurbished Printers Market
Printers
Global Printer Market
Printers
Global Inkjet Coders Market
Printers
Continuous Inkjet Printers Market
Printers
Portable Printer Market
Printers
Global Thermal Printing Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Global UV LED Printers Market
Printers
Global Ticket Printers Production Market
Printers
India Inkjet Printer Market
Printers
Printer Ribbons Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Indonesia Thermal Printer Market