
 Corrugated Wraps Market | 2026-2036
Corrugated Wraps Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Wraps Market Outlook
India is tilting toward expanded containerboard capacity with multiple greenfield mills coming online in Gujarat and Maharashtra. International Paper leverages its integrated pulp-to-box infrastructure to serve export-oriented food producers. WestRock anchors North American supply through extensive recycling collection networks and lightweight flute innovation. DS Smith competes on circular-design credentials, embedding reusable loop systems for European electronics manufacturers.
Corrugated wraps are paper-based protective layers formed from fluted medium sandwiched between linerboards, typically ranging from 80 to 350 grams per square meter in basis weight, engineered to cushion products against compression and impact during transit. Their primary purpose spans unitization, surface protection, and void-fill across manufacturing and distribution chains. Die-cut wraps command premium positioning in electronics packaging where precise fitment reduces material waste and return rates. Recycled fiber dominates volume flows in retail packaging, though virgin kraft retains margin concentration in food-contact applications requiring grease resistance and FDA compliance.
FDA food-contact regulations and EU REACH chemical restrictions shape material selection and coating formulations for cross-border shipments. The EU Green Deal's packaging waste targets and emerging state-level extended producer responsibility laws in California and New York are tightening recyclability thresholds. Stakeholders must monitor how diverging national implementation timelines for recycled content mandates affect sourcing strategies and capital allocation across regional production networks.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery cycles, forcing corrugated wrap specifications toward lighter basis weights and automated handling compatibility without sacrificing compression strength.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates across member states are accelerating demand for fiber-based protective formats that qualify for extended producer responsibility credits.
- Automotive component exports from Germany:Precision die-cut wraps for powertrain and electronics modules are displacing foam-in-place systems in just-in-time supply chains.
- Lightweight flute engineering:Micro-flute and nano-flute constructions below F-grade are enabling source reduction targets while maintaining stacking performance in retail-ready displays.
Market Restraints
- Old corrugated container supply volatility:Recycled fiber costs fluctuate with municipal collection rates and export demand from Asian packaging mills, compressing converter margins.
- Coating chemistry restrictions:EU REACH substance restrictions on fluorinated treatments limit grease-resistant options for direct food contact, forcing reformulation investments.
- Plastic film substitution in moisture-critical lanes:Stretch hood and shrink wrap systems retain cost advantages in cold-chain agricultural exports from California and Florida.
Strategic Opportunities
- Indian food processing expansion:Export-oriented spice and ready-meal producers in Gujarat and Maharashtra require FDA-compliant virgin kraft wraps for US and EU market access.
- Reusable loop integration:European electronics manufacturers are piloting returnable corrugated sleeve systems that embed RFID tracking for circular supply chain verification.
- State-level extended producer responsibility laws:California and New York implementation timelines create first-mover advantages for recyclability-certified suppliers.
Industry Challenges
- Die-cutting precision talent scarcity:Automated rotary and flatbed systems require operators trained in CAD nesting software and quick-change tooling protocols.
- Cross-border compliance latency:Divergent FDA, EU REACH, and emerging state chemical disclosure rules extend product qualification timelines for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Wraps Market |
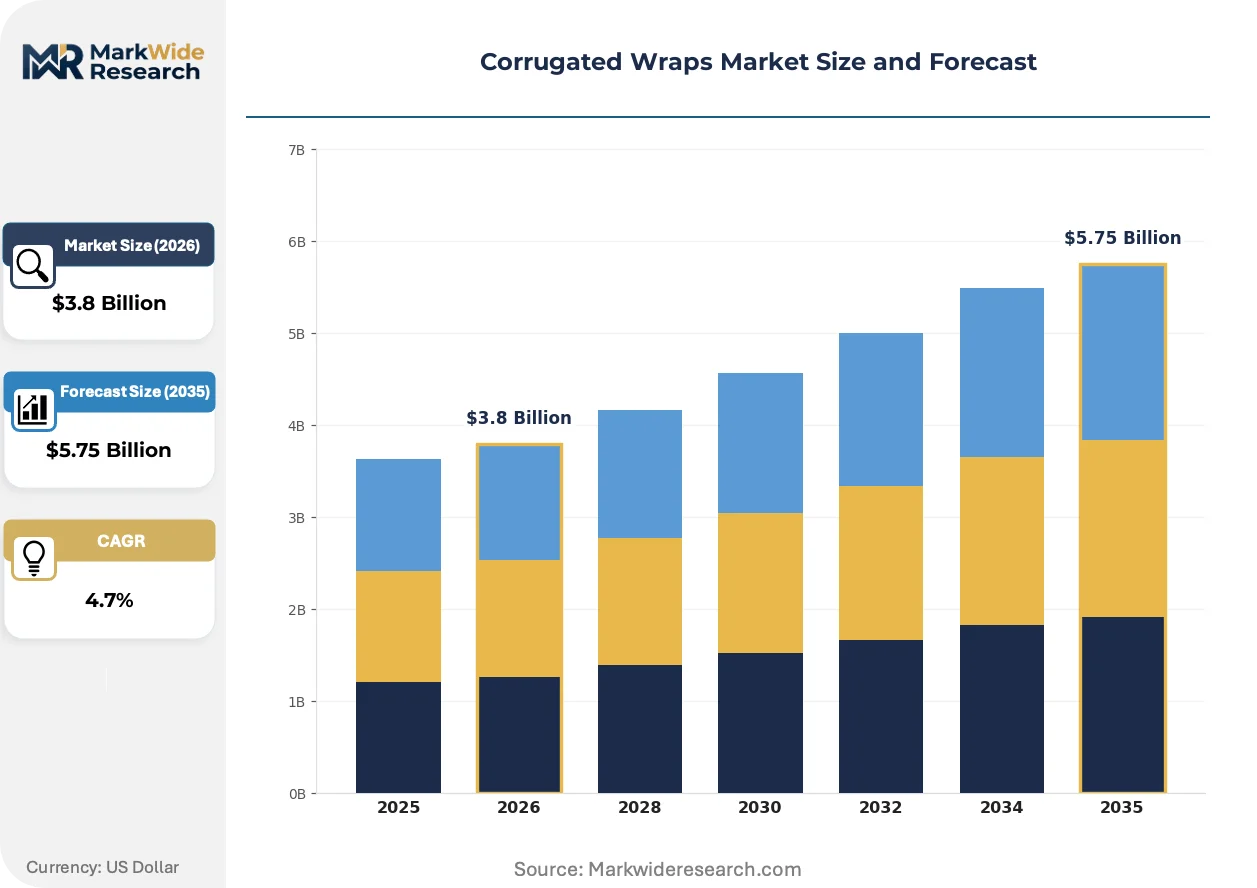
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die-Cut Wraps, Folding Wraps, Flat Wraps, Custom Wraps Material: Recycled Paper, Virgin Fiber, Kraft Paper, Coated Board Application: Food Packaging, Electronics Packaging, Industrial Packaging, Retail Packaging End User: Consumer Goods, Electronics Manufacturers, Food Producers, Automotive Suppliers |
| Companies Covered | International Paper, Mondi Group, WestRock, DS Smith, Smurfit Kappa Group, Amcor, Sealed Air, Packaging Corporation of America, Avery Dennison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Wraps Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine performance specifications across protective packaging tiers. Three developments are actively restructuring competitive positioning.
Water-based barrier coatings are migrating from niche premium applications to mainstream food-contact formats. Bakery and fresh produce exporters in the Pacific Northwest are adopting these treatments at scale to meet California SB 54 compliance deadlines. The shift is compressing demand for legacy polyethylene-laminated wraps in cross-border grocery distribution.
EU Green Deal packaging waste targets are tightening recyclability thresholds for composite structures. Multi-material laminates containing metallized films now face extended producer responsibility penalties in France and Germany. Electronics OEMs are responding by specifying single-fiber corrugated sleeves with printed closure systems rather than adhesive-based formats.
Consolidated buying by third-party logistics providers is compressing supplier rosters. Amazon, Shopify Fulfillment Network, and regional 3PLs in Texas and Pennsylvania are qualifying packaging vendors against unified performance scorecards. This concentration favors converters with integrated testing laboratories and rapid prototyping capabilities over commodity suppliers.
Corrugated Wraps Market Segmentation
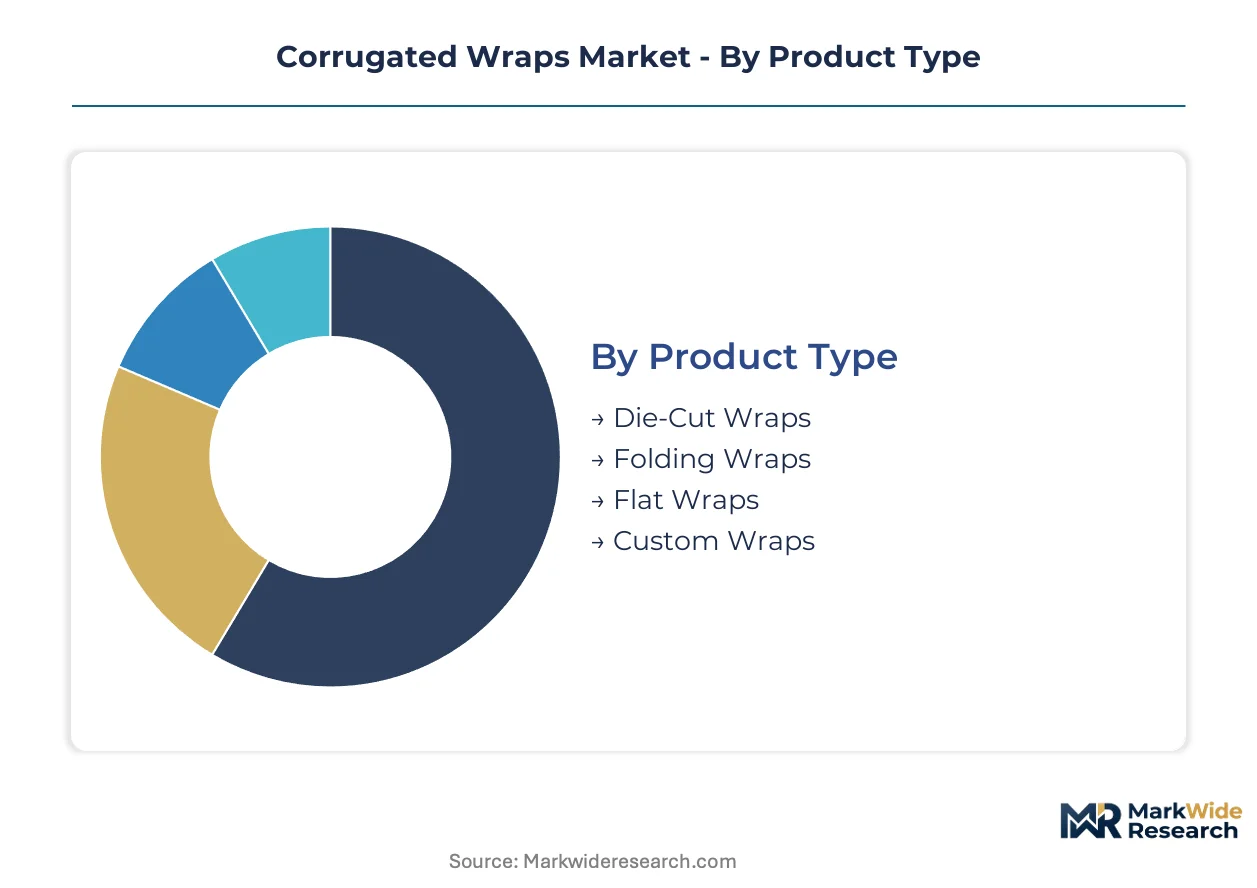
Corrugated wraps serve divergent performance requirements across protective packaging tiers, from precision die-cut formats for automotive supply chains to commodity flat wraps for bulk retail distribution. Segmentation reveals how material specifications, application demands, and end-user compliance obligations fragment supplier strategies and margin structures.
Product Type:
Mature formats dominate volume flows while engineered variants capture specification premiums in high-compliance end uses.
- Die-Cut Wraps:Precision-engineered formats fabricated through rotary or flatbed die-cutting achieve exact dimensional fitment for powertrain modules and consumer electronics. Automotive suppliers in Germany specify these for just-in-time delivery sequences where dimensional tolerance prevents line stoppages.
- Folding Wraps:Pre-scored designs with integrated locking tabs enable rapid manual assembly without adhesive or tape. E-commerce fulfillment centers in Pennsylvania and Texas deploy these for mid-size appliance protection where return rates drive total cost evaluation.
- Flat Wraps:Standard rectangular blanks serve void-fill and surface protection across general merchandise distribution.
- Custom Wraps:Application-specific designs incorporating printing, perforations, or multi-layer constructions address niche requirements.
Flat wraps handle the majority of throughput; die-cut wraps are gaining share fastest on automotive and electronics specification intensity.
Material:
Cost tiers separate commodity recycled grades from certified virgin stocks required for food-contact compliance.
- Recycled Paper:Post-consumer reclaimed fiber processed through OCC pulping systems delivers basis weights from 80 to 200 gsm for non-food retail applications. California SB 54 implementation timelines accelerate procurement of these formats for extended producer responsibility credit qualification.
- Virgin Fiber:Unbleached or semi-bleached kraft pulp provides structural integrity and FDA compliance for direct food contact. Spice exporters in Gujarat and Maharashtra require these specifications for US market access under FDA 21 CFR standards.
- Kraft Paper:Unbleached sulfate pulp delivers tear resistance and printability for branded retail presentations.
- Coated Board:Polymer or water-based barrier treatments enable grease resistance and moisture protection.
Recycled paper commands volume leadership; virgin fiber is expanding most quickly on food-export compliance requirements.
Application:
End-use concentration patterns align with regional industrial clustering and regulatory enforcement intensity.
- Food Packaging:FDA and EU REACH-compliant wraps protect bakery, produce, and ready-meal shipments through cold-chain distribution. Pacific Northwest agricultural exporters adopt water-based barrier coatings to meet California recyclability mandates.
- Electronics Packaging:Anti-static and precision-fit formats safeguard semiconductors, displays, and power supplies during intercontinental air freight. European OEMs pilot returnable sleeve systems with embedded RFID for circular supply chain verification.
- Industrial Packaging:Heavy-duty wraps with reinforced fluting protect machinery components and metal fabrications.
- Retail Packaging:Shelf-ready formats with pre-printed graphics support point-of-sale presentation requirements.
Retail packaging absorbs the largest volume share; food packaging is climbing the fastest on regulatory chemistry constraints.
End User:
Customer type determines specification complexity, with automotive and electronics buyers driving precision requirements.
- Automotive Suppliers:Tier-1 and Tier-2 component manufacturers specify die-cut wraps with exact nesting profiles for powertrain, interior, and electronics modules. German automotive clusters enforce ISO/TS 16949 traceability requirements through packaging documentation.
- Electronics Manufacturers:OEMs and contract assemblers demand ESD-compatible formats with printed circuit identification. Consolidated 3PL qualification programs in Texas and Pennsylvania favor suppliers with integrated testing laboratories.
- Consumer Goods:Brand owners and contract packagers source retail-ready formats for shelf impact and supply chain efficiency.
- Food Producers:Processors and co-packers require FDA and FSSAI compliance for domestic and export market access.
Consumer goods represents the largest addressable base; automotive suppliers are expanding fastest on just-in-time packaging specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation anchors European demand trajectories, while diverging national implementation timelines reshape sourcing strategies across major economies.
Germany
Automotive component exports and precision die-cut specifications drive specification intensity. The EU Green Deal's packaging waste targets enforce recyclability thresholds that favor fiber-based protective formats. Stuttgart and Wolfsburg automotive clusters displace foam-in-place systems with just-in-time corrugated wrap sequences for powertrain modules.
United States
E-commerce fulfillment networks and third-party logistics consolidation compress supplier rosters. California SB 54 and emerging New York extended producer responsibility laws tighten recyclability mandates. Pennsylvania and Texas distribution hubs qualify vendors against unified performance scorecards favoring integrated testing capabilities.
India
Export-oriented food processing and spice trade expansion accelerate virgin kraft demand. FSSAI and FDA 21 CFR compliance requirements structure material selection for US market access. Gujarat and Maharashtra greenfield containerboard mills anchor expanded domestic capacity for ready-meal producers.
China
Domestic e-commerce volume and cross-border agricultural exports sustain protective packaging throughput. GB standards and dual carbon goals influence lightweight flute engineering investments. Yangtze River Delta manufacturing clusters adopt micro-flute constructions for source reduction targets.
Japan
Electronics OEM sourcing and precision packaging specifications sustain premium tier demand. METI circular economy guidelines and JIS standards shape returnable loop pilot programs. Kanto region contract assemblers specify anti-static formats with embedded RFID for supply chain verification.
Corrugated Wraps Market Competitive Environment
Integrated pulp-to-box operators and specialized converters split the market along vertical capability lines. Consolidated buying by Amazon and regional 3PLs compresses supplier rosters toward vendors with rapid prototyping and unified qualification protocols. Three archetypes dominate: integrated fiber producers with captive pulp supply, specialty converters focused on die-cut precision, and diversified packaging conglomerates with multi-material portfolios. Capacity expansion in South Asia and strategic partnerships for circular-design credentials represent the dominant competitive vectors.
Among North American integrated operators, WestRock and Packaging Corporation of America exemplify scale-driven archetypes with extensive recycling collection networks. DS Smith represents European circular-design positioning through reusable loop system development. International Paper anchors the pulp-integration model with cross-border supply capabilities serving export-oriented food producers.
| Leading Market Players |
|---|
| International Paper |
| Mondi Group |
| WestRock |
| DS Smith |
| Smurfit Kappa Group |
| Amcor |
| Sealed Air |
| Packaging Corporation of America |
| Avery Dennison |
| Others |
Value Chain & Pricing Dynamics
Gujarat's greenfield containerboard mills are expanding virgin kraft capacity for export-oriented food producers, compressing regional price premiums while elevating specification intensity for FDA-compliant grades. This upstream capacity injection feeds into downstream pricing power dynamics across Asian and North American distribution networks.
Pricing Analysis
Price spreads between German automotive die-cut specifications and commodity flat wraps for retail distribution reflect three-tier pricing structure across premium, standard, and economy levels. Virgin fiber commands margin concentration on FDA 21 CFR and EU REACH compliance requirements, while recycled grades face compression from OCC supply volatility. Pricing pressure stems from lightweight flute engineering investments as converters absorb R&D costs without full pass-through. Third-party logistics buyers exhibit highest price sensitivity, whereas automotive Tier-1 suppliers prioritize dimensional tolerance over unit cost.
Supply Chain Analysis
Old corrugated container flows from municipal collection systems in the United States, Germany, and India anchor recycled fiber supply. Kraft pulp draws from integrated pulp-to-box operations in the southeastern United States and Scandinavian timber basins. Single-source vulnerability concentrates around Asian packaging mill demand for OCC exports, disrupting converter feedstock planning. Distribution runs through consolidated 3PL qualification programs that compress supplier rosters toward vendors with integrated testing laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Amazon and Shopify Fulfillment Network vendor consolidation, forcing supplier qualification protocols that favor integrated testing capabilities over commodity positioning.
For Market Incumbents: Insulate margin structures through captive pulp supply integration and rapid prototyping investments that meet consolidated 3PL scorecard requirements. Water-based barrier coating R&D addresses California SB 54 compliance deadlines before competitors achieve scale. Die-cutting precision talent scarcity threatens automated rotary system throughput; CAD nesting software training programs defend operational continuity. For New Entrants and Emerging Players: Establish a beachhead in Indian food processing exports where Gujarat and Maharashtra greenfield mills create virgin kraft supply proximity for FDA-compliant ready-meal producers. European reusable loop pilots for electronics manufacturers represent underdeveloped service-layer revenue. Lead with circular-design credentials and RFID-enabled returnable sleeve systems rather than commodity flat wrap competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty die-cut converters with automotive and electronics qualification lock-in. Long-term viability across the analysis window favors integrated pulp-to-box operators with cross-border supply capabilities. Acquisition targets should demonstrate embedded customer switching costs through ISO/TS 16949 traceability documentation. Monitor EU Packaging and Packaging Waste Regulation implementation timelines as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Flute Engineering Investment | Micro-flute and nano-flute constructions enable source reduction targets while maintaining stacking performance for retail-ready displays. |
| Water-Based Barrier Coating Scale-Up | Pacific Northwest agricultural exporters adopt these treatments to meet California SB 54 recyclability compliance deadlines. |
| Reusable Loop System Development | European electronics OEMs pilot returnable corrugated sleeves with embedded RFID for circular supply chain verification. |
| Integrated Testing Laboratory Expansion | Pennsylvania and Texas 3PL hubs qualify vendors against unified performance scorecards favoring rapid prototyping capabilities. |
| Greenfield Virgin Kraft Capacity Addition | Gujarat and Maharashtra mills anchor domestic supply for spice exporters requiring FDA 21 CFR compliance for US market access. |
Study Parameters
Operator-level perspectives from corrugated converter plant managers, Tier-1 automotive procurement leads, 3PL packaging qualification officers, and food processing supply chain directors anchored the qualitative base. Secondary validation drew from USITC trade flow databases, FEFCO industry statistics, EPA municipal solid waste characterization studies, and SEC 10-K filings from integrated packaging producers. Bottom-up volume estimates triangulated against top-down macroeconomic consumption indicators.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled include product type precision tier, material compliance grade, application regulatory intensity, and end-user specification complexity. CAGRs derived from historical growth pattern analysis adjusted for regulatory implementation phasing and capacity expansion announcements. Forecast inputs incorporated OCC price volatility indices and e-commerce fulfillment center buildout trajectories.
Sensitivities concentrate around EU Packaging and Packaging Waste Regulation enforcement intensity, California SB 54 implementation pacing, and Asian OCC export demand fluctuations. Forecasts reflect documented assumptions regarding lightweight flute adoption curves and reusable loop pilot conversion rates. Cross-checking against FEFCO statistical yearbook consumption trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Card Films Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Construction Films Market