
 Sodium Nickel Chloride Battery Market | 2026-2036
Sodium Nickel Chloride Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Nickel Chloride Battery Market Analytics
The EU Battery Regulation is consolidating preference for cobalt-free chemistries in European energy storage procurement. NGK Insulators leverages its ceramic expertise to sustain manufacturing scale in high-temperature sodium nickel chloride cells. FZ Sonick SA anchors European supply through specialized production for stationary grid applications. Altech Batteries competes on advanced hybrid technology development targeting broader temperature operating windows.
Sodium nickel chloride batteries employ a solid-state ceramic electrolyte separating molten sodium and nickel chloride electrodes, typically operating between 270°C and 350°C to achieve ionic conductivity sufficient for grid-scale energy storage and heavy-duty electric vehicle propulsion. Stationary batteries dominate current deployment as utilities prioritize long-duration storage with inherent thermal stability and zero thermal runaway risk. Electric vehicle batteries represent the fastest-expanding segment, particularly for electric buses and commercial fleets where weight tolerance allows the energy density trade-off. Advanced hybrid technology configurations concentrate margin pools where manufacturers integrate thermal management systems to reduce parasitic energy losses.
REACH compliance in Europe, GB standards enforcement under China's SAMR, and NHTSA safety protocols in the United States collectively shape cell certification pathways and cross-border market access conditions. ECHA substance restrictions and EPA hazardous material handling rules further constrain competitor chemistries while validating sodium nickel chloride's environmental positioning. Stakeholders must monitor evolving temperature-performance thresholds as low-temperature technology variants threaten to displace incumbent high-temperature architectures without sacrificing safety credentials.
Market Dynamics
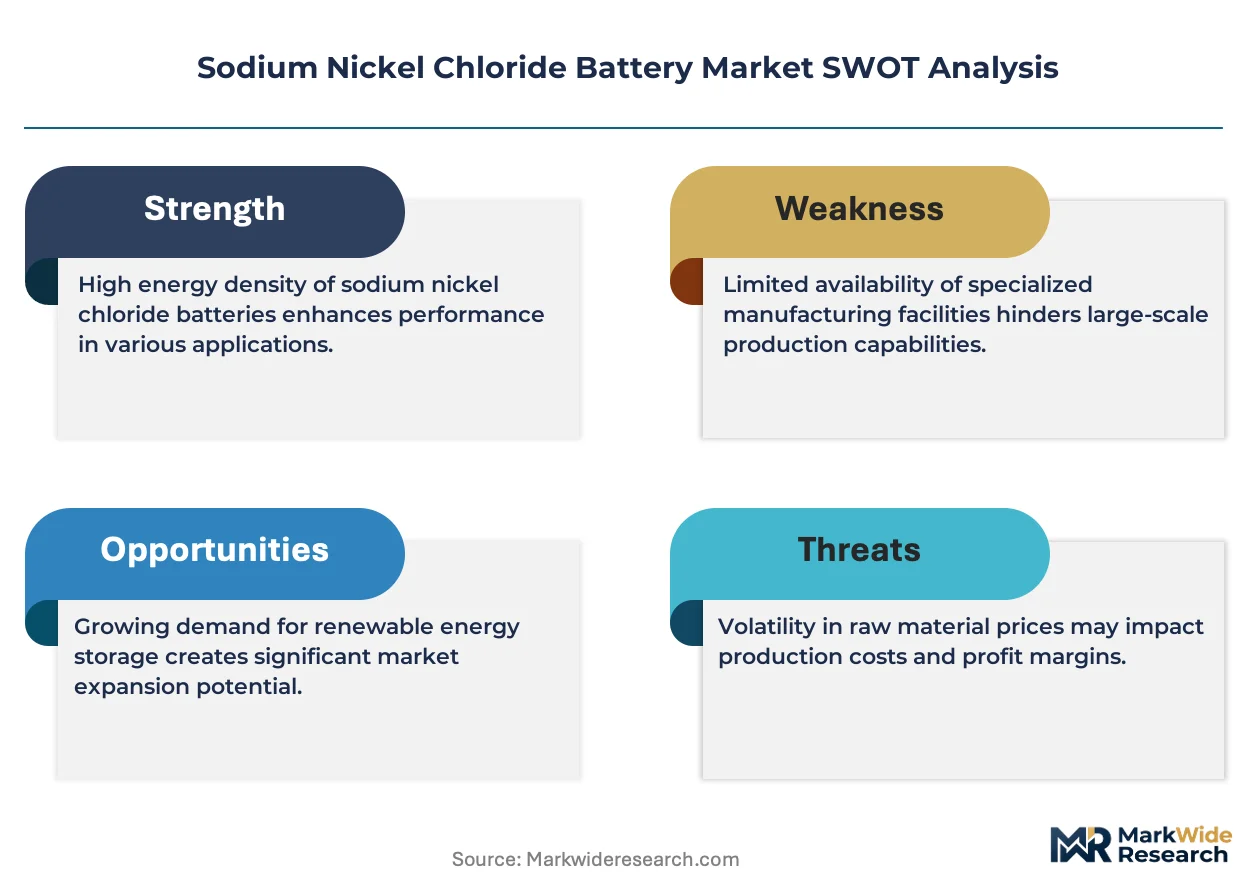
High-temperature sodium nickel chloride architectures face displacement pressure from emerging low-temperature variants that promise equivalent safety credentials without parasitic thermal management losses. Ceramic electrolyte manufacturing concentration in Japan and Germany creates supply vulnerability as demand scales beyond current kiln capacity. The chemistry's cobalt-free profile is accelerating under EU Battery Regulation substance restrictions while stationary grid operators prioritize inherent thermal stability over energy density trade-offs.
Growth Catalysts
- EU Battery Regulation:Cobalt-free chemistry mandates under REACH substance restrictions validate sodium nickel chloride's environmental positioning for European utility procurement.
- Electric transit fleets:Municipal bus operators in Germany and China accept weight penalties for fire safety assurance and extended cycle life in depot charging configurations.
- Grid-scale renewable integration:Long-duration storage requirements for wind and solar intermittency management favor thermal stability over lithium-ion alternatives.
Market Restraints
- Input cost volatility:Nickel price fluctuations and specialized ceramic alumina supply concentration in limited Japanese production facilities compress margin predictability.
- Technical limitation:Operating temperatures between 270°C and 350°C require continuous parasitic heating, degrading round-trip efficiency versus ambient-temperature alternatives.
- Substitution threat:Sodium-ion and solid-state lithium architectures are capturing stationary storage tenders previously reserved for high-temperature molten salt systems.
Strategic Opportunities
- Underpenetrated geography:India's CEA grid storage mandates and PLI scheme incentives for domestic battery manufacturing create first-mover positioning for sodium nickel chloride licensing.
- Technology convergence:Hybrid thermal management integration with phase-change materials is converging with sodium nickel chloride cells to reduce standby energy consumption.
- Regulatory tailwind:China's dual carbon goals and GB standards enforcement under SAMR accelerate certification pathways for fire-safe chemistries in urban energy infrastructure.
Industry Challenges
- Certification timeline compression:UN 38.3 transport testing and IEC 62619 safety validation for grid applications extend product qualification cycles beyond 18 months.
- Capex intensity:Ceramic sintering furnace installation and cleanroom assembly requirements demand upfront investment exceeding comparable lithium-ion gigafactory thresholds.
- Talent scarcity:High-temperature electrochemistry expertise and solid-state ceramic processing skills concentrate in aging Japanese and German engineering workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Nickel Chloride Battery Market |
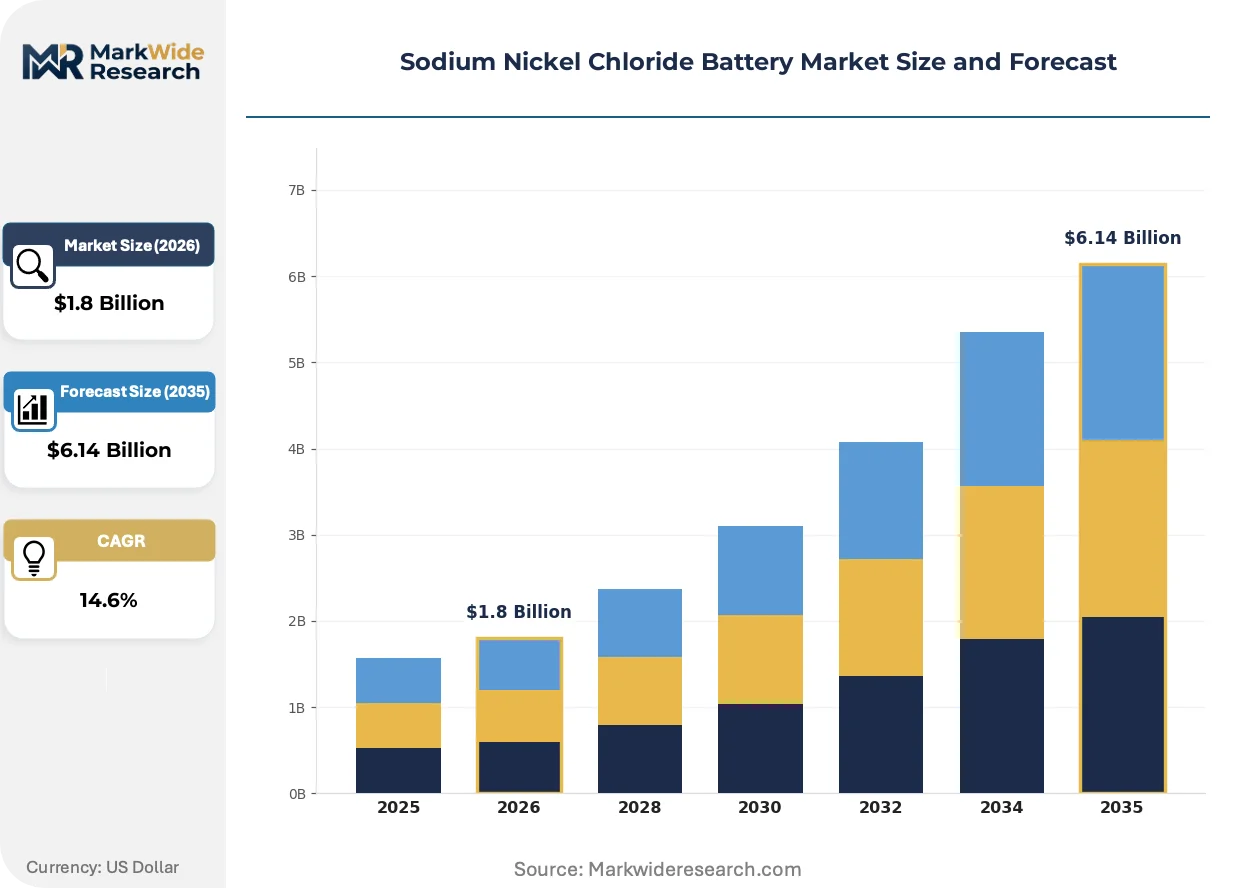
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Batteries, Electric Vehicle Batteries, Portable Batteries, Hybrid Systems Technology: High Temperature, Low Temperature, Advanced Hybrid, Modular Systems End User: Automotive, Renewable Energy, Backup Systems, Industrial Applications Installation: On-grid, Off-grid, Integrated Solutions, Standalone Systems |
| Companies Covered | NGK Insulators, Altech Batteries, FZ Sonick SA, Fiamm Energy Technology, Exide Technologies, Zhejiang AMPower, A123 Systems, HiNa Battery Technology, Saft Groupe SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Nickel Chloride Battery Market Evolving Landscape
Solid-state ceramic electrolyte architectures are converging with advanced thermal management systems to reshape competitive positioning in stationary storage. Regulatory frameworks across multiple jurisdictions are hardening safety requirements that favor inherently non-flammable chemistries. Procurement patterns among utility-scale buyers are compressing supplier qualification cycles while demanding extended performance warranties.
Low-temperature sodium nickel chloride variants operating below 200°C are converging with conventional lithium-ion manufacturing equipment to reduce capital barriers for new entrants. European and Chinese cell developers are piloting these architectures for residential and commercial behind-the-meter applications previously inaccessible to high-temperature molten salt systems. The convergence is compressing the traditional temperature-performance trade-off that has constrained chemistry adoption outside utility-scale deployments.
REACH substance restrictions and RoHS amendments in Europe are eliminating cobalt-containing cathode materials from public procurement tenders. The industrial consequence is a certification advantage for sodium nickel chloride systems in EU-funded grid modernization projects. Stationary storage segments in Germany, France, and the Netherlands are responding with accelerated technical specification updates that explicitly favor cobalt-free chemistries.
Utility procurement departments are consolidating supplier relationships around integrated system providers capable of delivering containerized storage with 20-year service agreements. The traditional component supply model is yielding to performance-contracting structures where cell manufacturers assume operational risk. This behavioral shift is most visible in German and Chinese utility tenders, where guaranteed availability clauses now dominate technical evaluation criteria over upfront capital cost.
Sodium Nickel Chloride Battery Market Segmentation
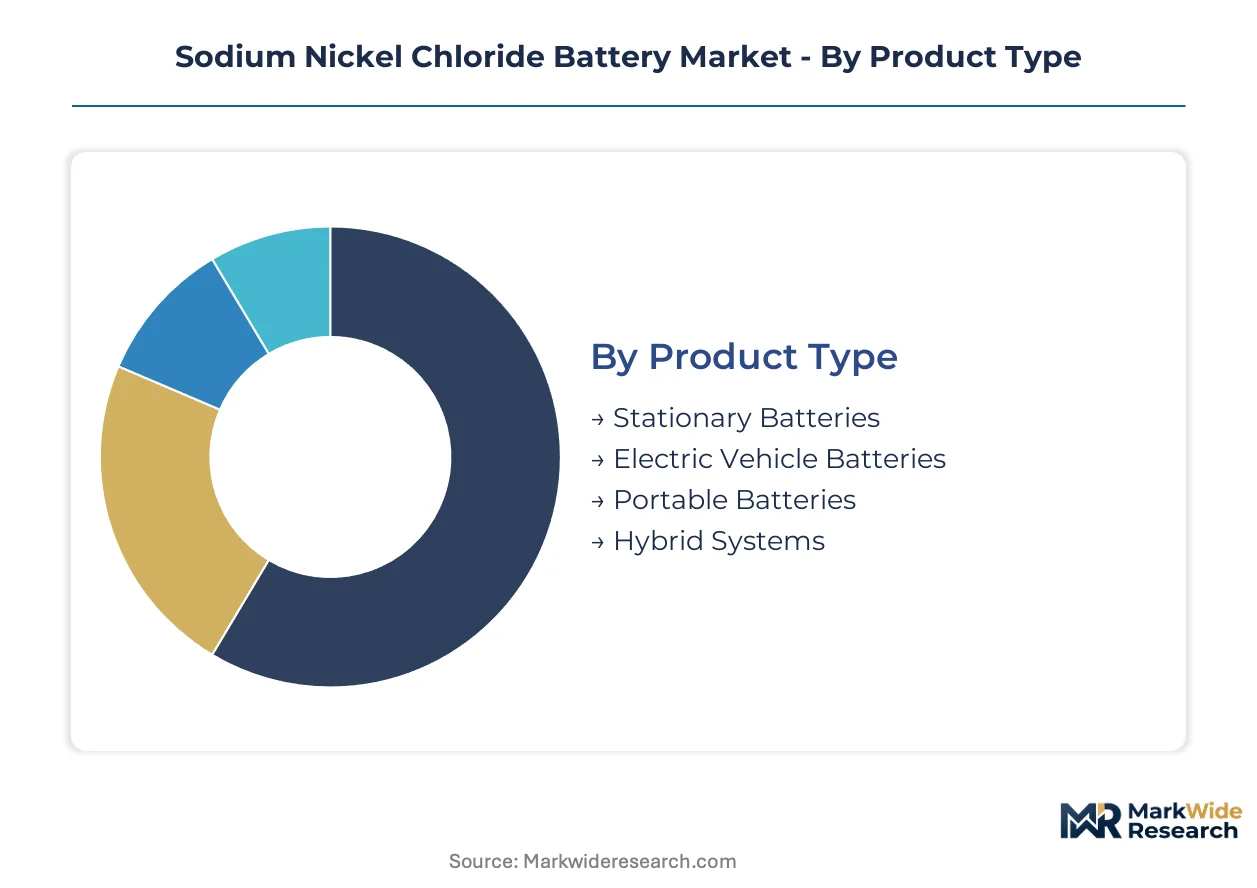
Sodium nickel chloride battery market segmentation reveals how technical specifications, operating temperatures, and deployment configurations create distinct commercial battlegrounds. Each category carries unique supply chain dependencies and regulatory exposure that reshape competitive positioning across utility, mobility, and industrial applications.
Product Type:
Supply concentration in ceramic electrolyte manufacturing tilts competitive advantage toward segments with longest production runs and most standardized cell geometries.
- Stationary Batteries:These systems employ large-format cylindrical cells optimized for multi-hour discharge cycles in grid-scale installations. Demand concentrates in Germany and China where utility procurement mandates favor cobalt-free chemistries with 20-year service warranties under FERC and CEA reliability standards. The segment benefits from established production lines at NGK Insulators and FZ Sonick SA.
- Electric Vehicle Batteries:Heavy-duty transit configurations dominate, particularly electric bus fleets in Chinese megacities and German municipal operators accepting weight penalties for fire safety assurance. SAMR GB standards enforcement and EU Battery Regulation substance restrictions validate this chemistry's thermal stability credentials against lithium-ion alternatives.
- Portable Batteries:Limited deployment due to thermal management mass constraints; niche applications in remote industrial monitoring.
- Hybrid Systems:Emerging configurations integrating phase-change materials to reduce standby energy consumption; pilot programs in Japanese microgrid demonstrations.
Today's leader: Stationary Batteries. Tomorrow's challenger: Electric Vehicle Batteries.
Technology:
Cost tier differentiation separates incumbent high-temperature architectures from capital-efficient low-temperature variants targeting behind-the-meter applications.
- High Temperature:Operating between 270°C and 350°C with beta-alumina ceramic electrolytes, these systems achieve proven cycle life exceeding 4,500 cycles. Production concentrates in Japanese and German kiln facilities with limited expansion capacity.
- Low Temperature:Emerging architectures below 200°C enable lithium-ion manufacturing equipment reuse, reducing capital barriers for new entrants in China and South Korea.
- Advanced Hybrid:Integrated thermal management with phase-change materials is gaining share fastest in European utility tenders demanding reduced parasitic losses.
- Modular Systems:Containerized configurations with standardized 40-foot units; procurement is shifting toward performance-contracting structures with guaranteed availability clauses.
Incumbent advantage rests with High Temperature. Steepest expansion trajectory belongs to Advanced Hybrid.
End User:
Volume concentration among utility-scale buyers creates procurement leverage that compresses supplier margins in the largest segment while protecting niche industrial applications.
- Automotive:Transit bus and commercial fleet operators in Germany, China, and the United States represent the primary demand pool. NHTSA safety protocols and municipal fire codes favor non-flammable chemistries in depot charging configurations.
- Renewable Energy:Wind and solar intermittency management drives long-duration storage procurement; ECHA REACH compliance requirements validate cobalt-free positioning in EU-funded grid modernization.
- Backup Systems:Critical infrastructure applications including telecommunications and data centers; specifications prioritize thermal stability over energy density.
- Industrial Applications:Forklift fleets and port electrification in Chinese manufacturing zones; dual carbon goals accelerate SAMR certification pathways.
Current revenue concentration: Renewable Energy. Emerging volume driver: Automotive.
Installation:
Customer type segmentation distinguishes between centralized utility procurement and distributed commercial deployment with diverging technical requirements.
- On-grid:Utility-scale installations connecting directly to transmission infrastructure; German TSOs and Chinese grid operators specify containerized systems with integrated inverters.
- Off-grid:Remote mining operations and island microgrids; Australian and Canadian resource projects specify wide temperature operating windows.
- Integrated Solutions:Combined solar-plus-storage or wind-plus-storage configurations; procurement departments demand single-source performance accountability.
- Standalone Systems:Retrofit installations replacing lead-acid or diesel backup; Indian CEA mandates create first-mover positioning for sodium nickel chloride licensing.
Procurement dominance: On-grid. Fastest policy tailwind: Standalone Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ceramic processing talent concentrates in Japanese and German engineering workforces, anchoring production capacity for high-temperature sodium nickel chloride architectures while Chinese manufacturers scale low-temperature alternatives.
Germany
Utility-scale storage procurement from transmission system operators drives demand concentration in North Rhine-Westphalia. EU Battery Regulation REACH substance restrictions validate cobalt-free chemistry positioning for grid modernization tenders. The Eindhoven-adjacent cluster across the Dutch border supplies thermal management components to German system integrators.
China
Municipal electric bus fleets in Beijing and Shenzhen accept weight penalties for fire safety assurance in depot charging configurations. SAMR GB standards enforcement accelerates certification pathways for high-temperature molten salt systems in urban energy infrastructure. Yangtze River Delta manufacturers pilot low-temperature variants below 200°C using repurposed lithium-ion equipment.
United States
FERC reliability standards shape utility procurement specifications for multi-hour discharge systems in Texas and California grid interconnections. NHTSA safety protocols favor non-flammable chemistries in commercial fleet depot configurations. Pacific Northwest aluminum smelter retirements create stranded transmission capacity for utility-scale battery installations.
India
CEA grid storage mandates and PLI scheme incentives for domestic battery manufacturing create first-mover positioning for sodium nickel chloride licensing agreements. The country's national power sector regulator prioritizes long-duration storage for renewable integration targets. Gujarat and Maharashtra industrial corridors attract pilot manufacturing investments for stationary grid applications.
Japan
Microgrid demonstration programs in Kyushu and Hokkaido test hybrid thermal management integration with phase-change materials. METI technology roadmaps support solid-state ceramic electrolyte development for export competitiveness. Nagoya-area kiln facilities face capacity constraints as global demand scales beyond current sintering throughput.
Sodium Nickel Chloride Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where ceramic sintering furnace ownership separates integrated manufacturers from technology licensors. The vendor base concentrates around three strategic archetypes: integrated ceramic specialists controlling electrolyte production, hybrid system integrators combining thermal management with cell supply, and low-temperature challengers repurposing lithium-ion manufacturing equipment. Dominant competitive moves include capacity expansion in Japanese and German kiln facilities and technology licensing partnerships targeting Indian and Chinese manufacturing scale-up.
Among Japanese ceramic specialists, NGK Insulators anchors the integrated production archetype through captive beta-alumina electrolyte supply. FZ Sonick SA exemplifies the European system integrator position with specialized stationary grid focus. Altech Batteries occupies the hybrid technology development tier targeting expanded temperature operating windows. These three company structures illustrate how geographic concentration in ceramic processing talent shapes competitive positioning across high-temperature and emerging low-temperature architectures.
| Leading Market Players |
|---|
| NGK Insulators |
| Altech Batteries |
| FZ Sonick SA |
| Fiamm Energy Technology |
| Exide Technologies |
| Zhejiang AMPower |
| A123 Systems |
| HiNa Battery Technology |
| Saft Groupe SAS |
| Others |
Value Network & Pricing Analysis
Sovereign-backed ceramic producers in Japan and Germany anchor supply-side discipline through captive beta-alumina electrolyte production, translating upstream kiln capacity constraints into tiered pricing power across stationary storage contracts. This ownership pattern insulates incumbent cell manufacturers from commodity volatility while compressing margins for asset-light system integrators dependent on spot ceramic supply.
Pricing Analysis
Bundled long-term service agreements dominate utility procurement, separating premium 20-year availability contracts from unbundled cell-only transactions. Price differentiation rests on certification tier (IEC 62619 validation status) and thermal management integration depth. Cost compression in standard-grade stationary systems is intensifying because Chinese low-temperature variants enable lithium-ion equipment reuse. Municipal transit operators exhibit highest price sensitivity; German transmission system operators accept premium positioning for guaranteed performance clauses.
Supply Chain Analysis
Beta-alumina ceramic electrolyte supply rests on specialized sintering kilns concentrated in Japan, Germany, and select Yangtze River Delta facilities. Raw material dependencies include high-purity alumina, nickel cathode feedstock, and sodium metal anodes. Single-source vulnerability in Japanese kiln capacity creates bottleneck risk as global demand scales. Distribution runs through containerized system integrators delivering turnkey grid installations to utility procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sodium nickel chloride battery market functions as a stable compounder where regulatory tailwinds for cobalt-free chemistries generate predictable procurement volume expansion across European and Asian grid modernization programs.
For Market Incumbents: Anchor manufacturing scale through captive ceramic electrolyte expansion in existing Nagoya-area kiln clusters, defending against low-temperature sodium-ion substitution by accelerating hybrid thermal management R&D. Prioritize IEC 62619 certification maintenance as procurement departments consolidate supplier relationships around validated system providers with 20-year performance accountability.
For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer lowest-friction market access for containerized storage configurations targeting Indian CEA-mandated standalone installations. White-space concentration sits in low-temperature residential behind-the-meter applications using repurposed lithium-ion manufacturing equipment. License hybrid thermal management IP from established Japanese developers to compress qualification timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light system integrators lacking captive ceramic supply but holding utility procurement relationships. Long-term viability centers on technology licensing models rather than capital-heavy manufacturing scale. Watch low-temperature variant cycle-life validation data as the inflection signal for displacement risk against incumbent high-temperature architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Electrolyte Capacity Expansion | Japanese kiln additions under METI roadmaps secure supply for German utility tenders. |
| Hybrid Thermal Management Integration | Phase-change material convergence reduces parasitic losses in European grid deployments. |
| Low-Temperature Technology Licensing | Chinese equipment reuse agreements accelerate Indian manufacturing scale-up under PLI incentives. |
| Long-Term Service Contracting | Performance-accountability structures shift procurement criteria from capital cost to availability guarantees. |
| REACH Compliance Certification | Cobalt-free chemistry validation secures preferential positioning in EU-funded grid modernization tenders. |
Research Methodology
Direct dialogue with utility procurement officers, ceramic processing engineers, grid-scale EPC contractors, and regulatory affairs specialists at battery system integrators grounded qualitative assessment. Secondary validation drew from ECHA substance restriction filings, SAMR GB standards documentation, FERC reliability standard updates, and customs trade data for beta-alumina ceramic imports. Bottom-up cell production estimates and top-down grid storage deployment forecasts were triangulated against disclosed utility tender awards.
Segment-level projections across product type, technology tier, end-use application, and installation configuration were generated through the forecast period. CAGRs were derived from regression analysis of historical procurement volumes against regulatory milestone timing and manufacturing capacity expansion schedules. Key model inputs included ceramic sintering furnace utilization rates, nickel price volatility bands, and electric transit fleet electrification targets in Germany and China.
The model assumes a particular technology adoption path favoring high-temperature architectures through the projection horizon; accelerated low-temperature variant commercialization would alter the outlook. Forecasts reflect assumptions about REACH enforcement consistency, SAMR certification timeline stability, and ceramic supply expansion rates. A small set of triggers—low-temperature cycle-life breakthroughs, nickel supply disruption, or kiln capacity bottlenecks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Primary Battery Market
Batteries
South Africa Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Industrial Battery Charger Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
Portable Battery Market
Batteries
Wireless Power Bank Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Battery Wash System Market
Batteries
Thin Film and Printed Battery Market
Batteries
Power-Sports Batteries Market
Batteries
Forklift Battery Rental Market
Batteries
Carbon Foam Battery Market
Batteries
Micro Battery Market
Batteries
Battery Light Towers Market