
 Sweden Rechargeable Battery Market | 2026-2036
Sweden Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Rechargeable Battery Market Insights
Battery-as-a-service subscription models for commercial vehicle fleets is repositioning how Swedish buyers acquire energy storage assets. Panasonic Corporation leverages its cylindrical cell expertise to sustain supply relationships with European automakers. Novo Energy AB anchors domestic production ambitions through its planned gigafactory in northern Sweden. Samsung SDI Co. Ltd. competes on high-nickel chemistry platforms tailored to Nordic cold-climate performance requirements.
Sweden rechargeable batteries are electrochemical energy storage devices designed for repeated charge-discharge cycling, typically employing lithium-ion chemistries with nickel-manganese-cobalt or lithium-iron-phosphate cathodes paired with graphite or silicon-blend anodes, and are manufactured through electrode coating, calendering, electrolyte filling, and formation cycling processes to serve electric mobility and stationary power applications. Lithium-ion cells dominate installed capacity due to energy density advantages, while flow batteries occupy emerging grid-scale deployments where duration exceeds four hours. Energy Storage Systems represent the fastest-growing end user segment as Swedish wind and solar penetration drives utility-scale buffering needs.
The EU Battery Regulation mandates carbon footprint labeling and minimum recycled content thresholds that Swedish market participants must integrate into product design. Sweden's Chemicals Agency enforces REACH compliance for hazardous substance restrictions across battery supply chains. The Swedish Energy Agency's electrification subsidies shape demand patterns for industrial and transport applications. Stakeholders must monitor how forthcoming EU critical raw material act requirements alter sourcing strategies for cobalt, lithium, and nickel.
Market Dynamics
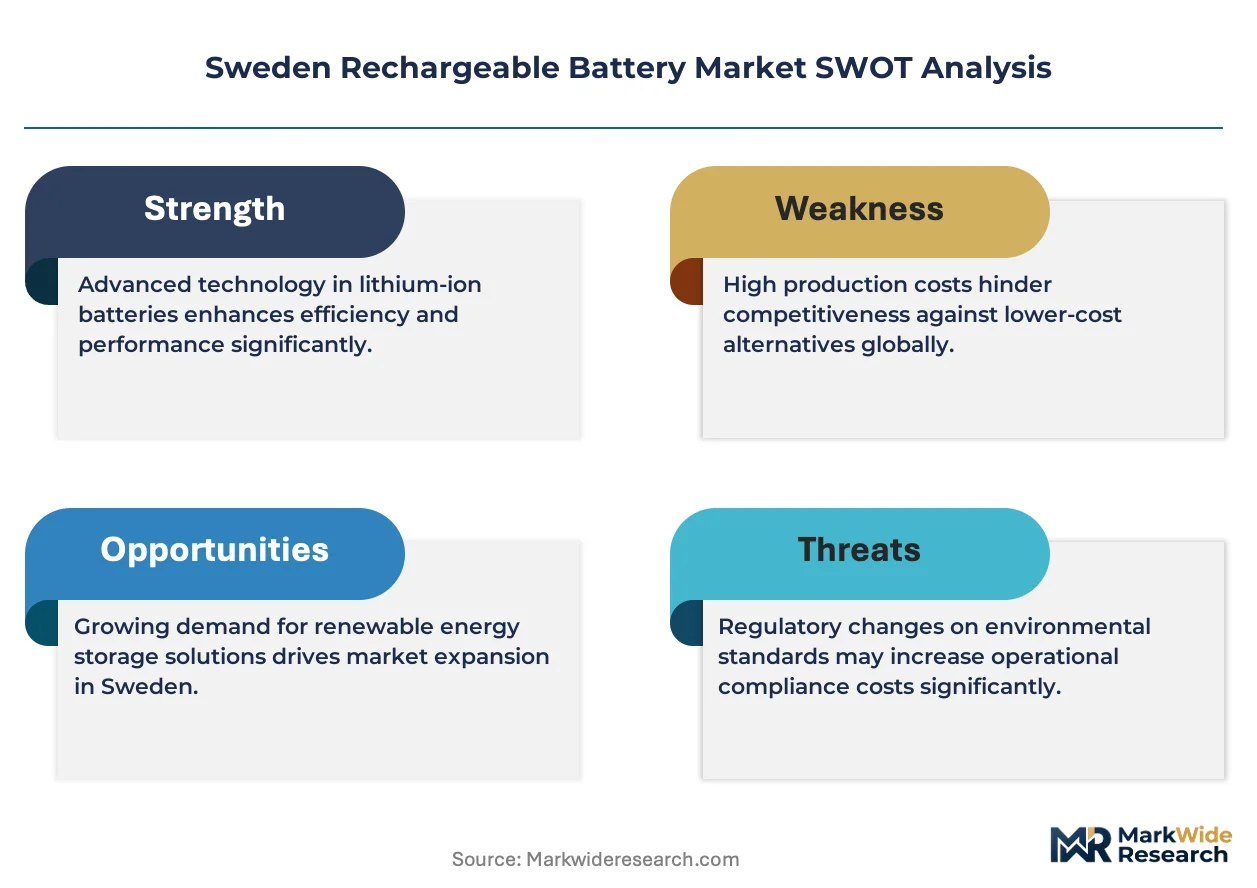
The EU Battery Regulation's carbon footprint declarations and recycled content mandates are forcing Swedish suppliers to reconfigure supply chains and product design architectures. This regulatory pressure intersects with Nordic cold-climate performance requirements to create a distinct technical specification layer that shapes procurement decisions.
Growth Catalysts
- Electrification Subsidies:The Swedish Energy Agency's industrial and transport electrification funding programs anchor volume commitments from energy storage developers and commercial fleet operators.
- Gothenburg and Stockholm Bus Fleets:Municipal procurement of high-capacity lithium-ion packs for electric bus networks generates predictable demand anchors for domestic cell suppliers.
- Nickel-Manganese-Cobalt Chemistry Advances:Energy density improvements in NMC cathode formulations enable extended range performance for Nordic winter operating conditions.
Market Restraints
- Lithium and Cobalt Sourcing Concentration:Dependence on concentrated upstream extraction geographies creates price volatility exposure and supply security vulnerabilities for Swedish cathode material procurement.
- Silicon-Blend Anode Technical Limitations:Volume expansion during cycling degrades cell longevity, constraining silicon adoption rates in automotive-grade packs despite theoretical capacity advantages.
- REACH Compliance Friction:The Swedish Chemicals Agency's hazardous substance restrictions add certification timelines and reformulation costs across electrolyte and separator supply tiers.
Strategic Opportunities
- Grid-Scale Flow Battery Deployments:Four-hour-plus duration energy storage applications in Swedish wind and solar buffering represent underpenetrated territory beyond lithium-ion dominance.
- Battery-as-a-Service Models:Subscription-based commercial vehicle fleet acquisition channels decouple capital expenditure from energy storage ownership, unlocking price-sensitive buyer segments.
- EU Critical Raw Material Act Alignment:Strategic stockpiling and domestic processing incentives for lithium, nickel, and cobalt reshape sourcing economics for compliant Swedish producers.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:Specialized electrochemistry expertise for low-temperature performance optimization remains concentrated among limited research institutions and incumbent suppliers.
- Gigafactory Capex Intensity:Novo Energy AB's planned northern Sweden production facility demands multi-billion-krona electrode coating, calendering, and formation cycling infrastructure commitments.
- CE Marking and Carbon Footprint Certification Timelines:Extended documentation requirements under the EU Battery Regulation compress product launch windows for new cell architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Rechargeable Battery Market |
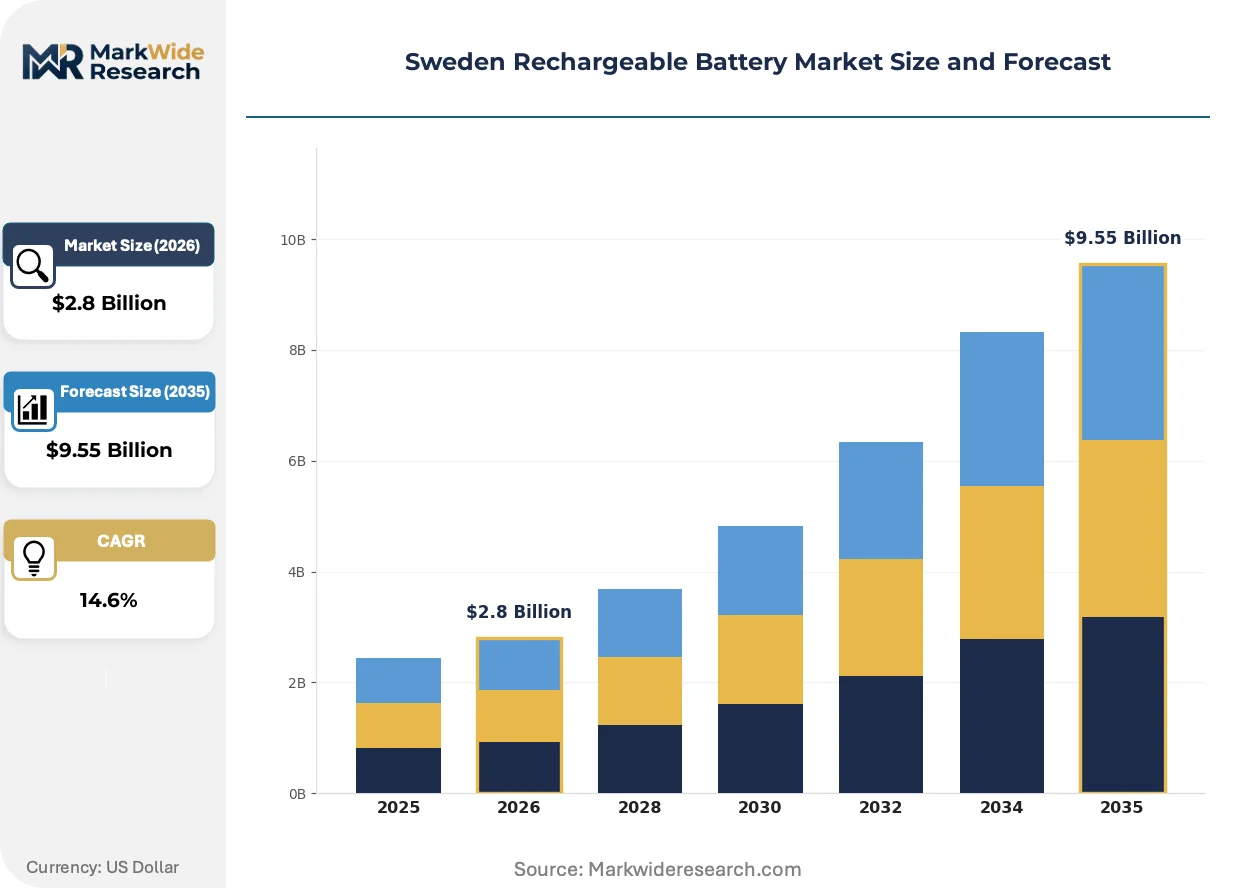
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead-acid, Flow Batteries End User: Consumer Electronics, Automotive, Industrial Equipment, Energy Storage Systems Technology: Fast Charging, Wireless Charging, Smart Batteries, Solar Rechargeable Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | BYD Co. Ltd., Contemporary Amperex Technology Co. Ltd., Panasonic Corporation, Lyten, Novo Energy AB, GS Yuasa Corporation, Exide Industries, Samsung SDI Co. Ltd., LG Chem Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Rechargeable Battery Market Trends and Innovations
Swedian battery markets are experiencing convergent pressures from chemistry evolution, regulatory stringency, and procurement model disruption. These forces collectively determine competitive positioning and investment allocation across the value chain.
Solid-state electrolyte architectures are rewriting performance benchmarks for energy density and thermal stability. Automotive OEMs active in Nordic markets are accelerating pilot programs for sulfide and oxide-based solid-state cells. This transition is compressing the competitive window for conventional liquid electrolyte suppliers to demonstrate cost parity.
The EU Battery Regulation's recycled content thresholds and due diligence obligations are reshaping supplier qualification protocols. Swedish pack assemblers must now document supply chain provenance and end-of-life collection infrastructure. Energy storage system integrators face the steepest compliance burden as utility-scale projects scale procurement volumes.
Fleet operators are unbundling energy storage ownership from vehicle acquisition through third-party battery service contracts. Commercial vehicle lessors in Stockholm and Gothenburg are displacing traditional capital purchase models with per-kilometer usage agreements. This pattern concentrates most visibly in municipal bus networks where total cost of ownership transparency drives contract structures.
Sweden Rechargeable Battery Market Segmentation
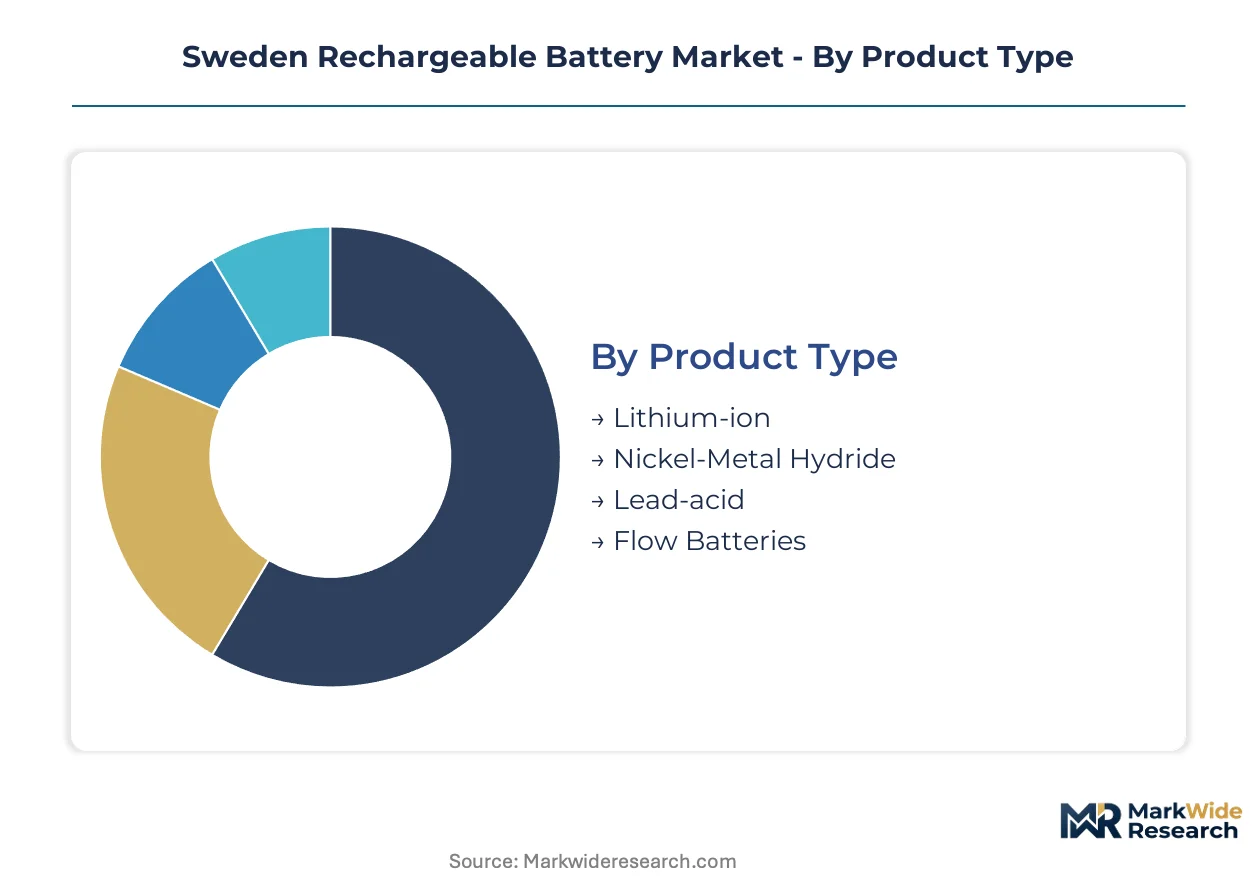
Sweden's rechargeable battery market segments along chemistry platforms, application intensity, and performance tiers. Procurement patterns diverge sharply between automotive volume contracts and specialized industrial deployments. Understanding these splits clarifies where cell suppliers concentrate R&D investment versus manufacturing scale.
Product Type:
Volume concentration favors established chemistries with proven Nordic cold-climate reliability, while premium positioning attaches to emerging architectures with superior energy density or duration characteristics.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathode formulations paired with graphite or silicon-blend anodes deliver the energy density thresholds required for Stockholm and Gothenburg electric bus fleets. Demand concentrates heavily within automotive OEM supply agreements where domestic pack assemblers anchor procurement commitments.
- Flow Batteries:Vanadium redox and zinc-bromine systems employ liquid electrolyte tanks separated by ion-selective membranes, enabling independent scaling of power and energy capacity. Deployments cluster in northern Sweden wind buffering projects where discharge duration exceeds four hours and lithium-ion cost economics degrade.
- Nickel-Metal Hydride:Rare-earth alloy anodes paired with nickel hydroxide cathodes occupy legacy hybrid vehicle applications and industrial backup power where capital constraints limit lithium-ion adoption.
- Lead-acid:Mature flooded and absorbed glass mat designs serve stationary backup and motive power segments with minimal energy density requirements.
Mature deployment sits with Lead-acid in industrial backup configurations. Newer deployment is concentrated in Flow Batteries for utility-scale duration applications.
End User:
Application intensity separates high-volume automotive contracts from specialized industrial equipment procurement with diverging performance specifications and qualification timelines.
- Automotive:Passenger EV platforms and commercial vehicle fleets demand cylindrical and prismatic cell formats with thermal management systems engineered for sub-zero startup performance. The Swedish Energy Agency's electrification subsidies channel volume through domestic OEM partnerships.
- Energy Storage Systems:Utility-scale and behind-the-meter installations integrate containerized battery racks with power conversion systems for grid stabilization services. Wind and solar penetration in northern Sweden drives the steepest expansion trajectory for this segment.
- Consumer Electronics:Pouch and cylindrical formats power portable devices with priority on volumetric energy density and cycle stability under shallow discharge patterns.
- Industrial Equipment:Forklift fleets, mining machinery, and automated guided vehicles require ruggedized pack architectures with rapid opportunity charging capability.
Contract scale differentiates Automotive megawatt-hour commitments from Industrial Equipment's fragmented procurement. Energy Storage Systems command the longest project development cycles due to grid interconnection protocols.
Technology:
Charging architecture and intelligence layers segment the market between speed-optimized, convenience-focused, and autonomy-enabled product configurations.
- Fast Charging:Silicon carbide power electronics and advanced thermal management enable 10-80% state-of-charge replenishment in under 20 minutes for commercial vehicle fleets. Gothenburg bus operators specify these systems to minimize route downtime.
- Smart Batteries:Integrated battery management systems with predictive algorithms and cellular connectivity enable remote diagnostics and optimized cycling strategies. Industrial Equipment and Energy Storage Systems applications prioritize these capabilities for asset utilization maximization.
- Wireless Charging:Inductive power transfer coils embedded in roadways and parking surfaces eliminate connector wear in automated logistics environments.
- Solar Rechargeable:Photovoltaic-integrated packs with maximum power point tracking serve off-grid and remote monitoring applications with intermittent insolation profiles.
Feature integration runs deepest in Smart Batteries where software margins supplement hardware economics. Wireless Charging remains experimental outside controlled demonstration corridors.
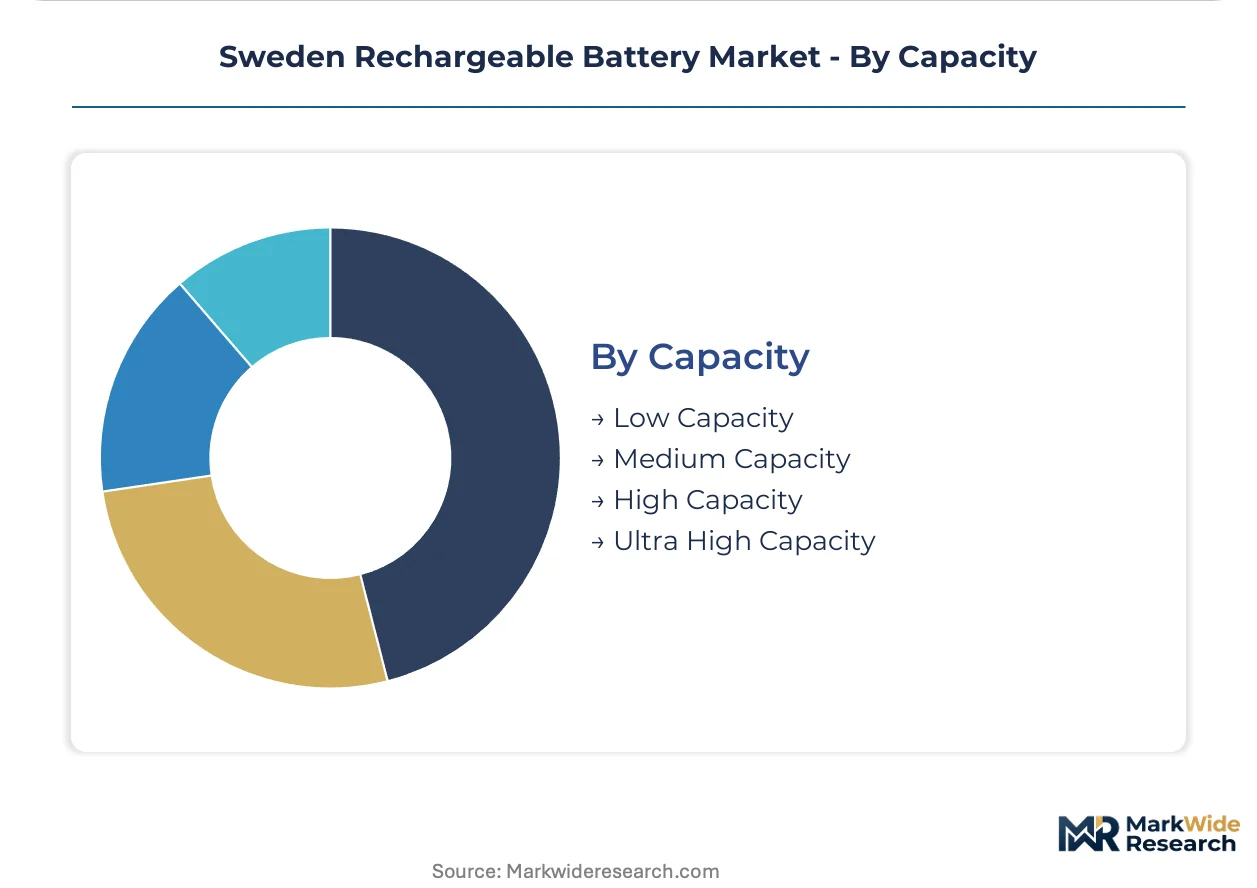
Capacity:
Energy content tiers align with physical footprint constraints and discharge duration requirements across mobility and stationary applications.
- High Capacity:Packs exceeding 50 kWh enable 300+ kilometer electric range in passenger vehicles and multi-hour industrial shift operations. Swedish automotive OEMs concentrate procurement here for premium platform differentiation.
- Ultra High Capacity:Systems above 100 kWh serve long-haul trucking prototypes and grid-scale four-hour duration storage with cell-to-pack architectures eliminating module overhead.
- Medium Capacity:10-50 kWh configurations power compact urban delivery vehicles and residential energy storage with wall-mounted form factors.
- Low Capacity:Sub-10 kWh designs occupy power tools, e-bikes, and portable electronics where mass and volume constraints dominate energy requirements.
Unit economics favor High Capacity production scales where electrode coating and formation cycling infrastructure achieves maximum utilization. Ultra High Capacity commands project-specific engineering with elongated delivery schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish cell production capacity lags behind Nordic consumption growth, creating import dependency on Asian and European suppliers. Domestic gigafactory investments in Västerbotten and Norrbotten aim to rebalance this asymmetry by the early 2030s.
Stockholm
Greater Stockholm hosts Sweden's densest concentration of energy storage system integrators and electric bus fleet operators. The Swedish Energy Agency's electrification subsidies channel procurement through municipal transit authorities. Northvolt's R&D presence in Kista anchors pilot production programs for next-generation cell architectures.
Västerbotten
Northern Sweden's Västerbotten county hosts Novo Energy AB's planned gigafactory near Skellefteå, leveraging abundant hydropower for carbon-neutral electrode coating operations. The EU Critical Raw Material Act's domestic processing incentives support lithium refining partnerships with Finnish suppliers. Arctic climate conditions drive specialized low-temperature electrolyte formulation requirements for regional automotive OEMs.
Gothenburg
Sweden's second-largest metropolitan area anchors commercial vehicle electrification through Volvo Group's heavy-duty truck platforms and municipal bus procurement. The Swedish Chemicals Agency enforces REACH compliance for hazardous substance restrictions across pack assembly operations. Lindholmen Science Park concentrates battery management system software development for Nordic cold-climate optimization.
Norrbotten
Europe's largest iron ore mining district in Norrbotten drives demand for ruggedized industrial battery packs in underground electric vehicle applications. The Swedish Work Environment Authority mandates explosion-proof certification for subterranean energy storage deployments. LKAB's fossil-free steel initiative creates adjacent demand for high-capacity stationary storage at hydrogen reduction pilot plants.
Malmö
Southern Sweden's logistics corridor through Malmö connects continental European cell supply chains with Nordic distribution networks. The Øresund Bridge freight corridor enables just-in-time delivery of cylindrical and prismatic formats to Danish and Norwegian pack assemblers. Malmö's port infrastructure handles bulk lithium carbonate imports from South American extraction sites.
Sweden Rechargeable Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for positioning across Sweden's rechargeable battery value chain. Integrated cell manufacturers with electrode coating and formation cycling assets command premium supply relationships with automotive OEMs. Three archetypes dominate: Asian conglomerates with cylindrical cell expertise, European specialists in prismatic automotive formats, and domestic developers of solid-state architectures. Competitive moves concentrate on capacity expansion in Nordic production zones and strategic partnerships for raw material offtake agreements.
Among Asian conglomerates, Panasonic Corporation and Samsung SDI Co. Ltd. exemplify the scale-driven tier, leveraging established cylindrical and high-nickel chemistry platforms to sustain European automaker relationships. Novo Energy AB represents the domestic production archetype, anchoring Sweden's gigafactory ambitions through planned northern Sweden facilities. Contemporary Amperex Technology Co. Ltd. occupies a position as a volume supplier with documented European expansion intent. These three illustrate how geographic origin and corporate structure map onto distinct competitive postures within Swedish procurement channels.
| Leading Market Players |
|---|
| BYD Co. Ltd. |
| Contemporary Amperex Technology Co. Ltd. |
| Panasonic Corporation |
| Lyten |
| Novo Energy AB |
| GS Yuasa Corporation |
| Exide Industries |
| Samsung SDI Co. Ltd. |
| LG Chem Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive electrode coating and formation cycling infrastructure anchors both supply security and pricing leverage for Swedish cell producers navigating EU Battery Regulation compliance. Novo Energy AB's northern Sweden gigafactory investment exemplifies how backward integration into cathode material processing insulates procurement costs from lithium carbonate spot volatility while satisfying carbon footprint declaration requirements.
Pricing Analysis
Cost-down pressure on automotive-grade lithium-ion packs accelerates because nickel-manganese-cobalt cathode formulations face raw material volatility from concentrated DRC and Indonesian supply. Three-tier pricing structure across premium solid-state pilot programs, standard NMC automotive contracts, and economy LFP stationary storage reflects certification grade differentiation under REACH and EU Battery Regulation tiers. Municipal bus fleet operators in Stockholm and Gothenburg exhibit highest price sensitivity through battery-as-a-service subscription structures, while premium passenger EV platforms absorb cell cost premiums for cold-climate performance specifications.
Supply Chain Analysis
EU Critical Raw Material Act domestic processing incentives are reshaping Swedish sourcing strategies toward Finnish lithium refining partnerships and Nordic cobalt hydroxide preprocessing. Upstream concentration in Chilean and Australian lithium extraction, Chinese cathode active material production, and South Korean separator manufacturing creates tariff exposure vulnerability through EU-Asia trade corridors. Silicon-blend anode precursor and electrolyte salt dependencies rest on Japanese and Chinese specialty chemical suppliers. Distribution runs through Malmö port infrastructure connecting continental European cell logistics with Nordic pack assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's rechargeable battery market is a vertical-integration race where captive cathode material processing and formation cycling infrastructure determine cost position against Asian imports.
For Market Incumbents: Acquire Finnish lithium refining offtake agreements and electrode coating capacity in Västerbotten to secure supply position against Samsung SDI and Panasonic's cylindrical cell cost advantages. Defend automotive OEM relationships through CE marking pre-certification investments that compress EU Battery Regulation compliance timelines for new cell architectures.
For New Entrants and Emerging Players: Battery-as-a-Service digital platforms for commercial vehicle fleets offer the most penetrable channel to bypass capital-intensive gigafactory commitments. Target Gothenburg municipal bus procurement through per-kilometer usage agreements that decouple energy storage ownership from vehicle acquisition. Partner with energy storage system integrators for grid-scale flow battery deployments where lithium-ion cost economics degrade beyond four-hour duration.
For Investors and Strategic Acquirers: Exit pathways concentrate in domestic solid-state electrolyte specialists and battery management system software developers with Nordic cold-climate optimization IP. Long-term viability hinges on EU Critical Raw Material Act alignment for strategic stockpiling and domestic processing incentives. Watch electrolyte formulation talent migration from incumbent Asian suppliers to Swedish research institutions as the inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Finnish lithium refining partnerships reduce DRC cobalt exposure under EU due diligence rules. |
| Battery-as-a-Service Platform Launch | Per-kilometer pricing unlocks municipal bus fleet procurement in Stockholm and Gothenburg. |
| Solid-State Electrolyte Pilot Scale-Up | Sulfide-based cell architectures bypass liquid electrolyte REACH compliance friction. |
| Grid-Scale Flow Battery Deployment | Vanadium redox systems capture northern Sweden wind buffering beyond lithium-ion duration limits. |
| CE Marking Pre-Certification Investment | Accelerated carbon footprint documentation compresses product launch windows under EU Battery Regulation. |
Research Methodology
Independent corroboration across cell manufacturer procurement directors, energy storage system integrators, and Swedish Energy Agency program officers underwrites the qualitative findings. Primary fieldwork with electrode coating equipment suppliers, electrolyte formulators, and automotive OEM platform engineers combined with secondary validation from EU Battery Regulation implementation guidance, Swedish Chemicals Agency REACH enforcement records, and Nordic customs trade data. Bottom-up cell production capacity estimates and top-down electrification subsidy allocation analysis triangulate volume projections.
Rate-of-change decomposition across chemistry platform evolution, regulatory compliance burden escalation, and procurement model disruption shapes the analytical framework. Segmentation dimensions span lithium-ion versus flow battery technology, automotive versus energy storage end-use, and high versus ultra-high capacity tiers. CAGRs derive from installed base replacement cycles, fleet electrification timelines, and grid interconnection queue analysis. Forecast inputs incorporate EU Critical Raw Material Act implementation pace and Nordic hydropower availability for carbon-neutral production.
The model holds under sustained EU Battery Regulation enforcement and lithium carbonate price band stability; deviation in raw material export restrictions or solid-state technology breakthroughs would shift competitive positioning. Forecasts reflect documented assumptions about cathode chemistry transition rates and municipal procurement acceleration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
South Korea Rechargeable Battery Market
Batteries
East Asia Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Battery Binders Market
Batteries
Marine Powerboat Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Europe Industrial Battery Market
Batteries
America SLI Battery Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Europe Consumer Battery Market
Batteries
Seawater Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market