
 Kuwait Poultry Meat Market | 2026-2036
Kuwait Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Poultry Meat Market Insights
Halal-certified premium-grade poultry is bifurcating the Kuwait market into value-tier and specification-tier supply lanes. Kuwait United Poultry Company (KUPCO) anchors domestic production through integrated breeding-to-retail operations across Al-Jahra and Al-Wafra. Almarai Food Company leverages its Gulf-wide cold-chain network to sustain consistent chilled-distribution coverage into Kuwaiti retail channels. BRF S.A. competes via specialized halal-processing capabilities calibrated to Middle Eastern import protocols.
Kuwait poultry meat encompasses avian muscle tissue harvested from broiler chickens, turkeys, and waterfowl, processed to moisture-content specifications typically between 65% and 75% for fresh retail sale and blast-frozen at minus 18 degrees Celsius for extended shelf stability; its primary commercial purpose is to supply protein for household consumption, institutional catering, and quick-service restaurant chains. Chicken dominates volume throughput across Kuwaiti distribution channels, though marinated and value-added processed segments are expanding fastest as time-constrained consumers trade up from raw whole-bird purchases. Fresh processing retains margin concentration in supermarket and wholesale channels where cold-chain integrity commands price premiums, while frozen product occupies volume leadership through local market and bulk institutional procurement.
Kuwait's Public Authority for Food and Nutrition enforces halal-slaughter compliance and residue-testing protocols that shape import eligibility and domestic plant licensing, while the Environment Public Authority regulates wastewater and emissions from processing facilities, constraining capacity expansion at older industrial zones. The General Administration of Customs applies GCC-wide tariff structures that influence regional sourcing decisions for frozen and chilled imports. Stakeholders must monitor evolving shelf-life labeling requirements and carbon-footprint disclosure pressures that could reshape procurement criteria and supplier qualification standards.
Market Dynamics
Halal certification mandates from Kuwait's Public Authority for Food and Nutrition are tightening import eligibility and domestic processing standards, forcing supply chain reconfiguration toward specification-tier procurement lanes.
Growth Catalysts
- Protein-rich dietary shift:Kuwaiti consumers in urban governorates are prioritizing poultry as a lean protein source, expanding household consumption and foodservice procurement volumes.
- Public Authority for Food and Nutrition halal mandates:Certification requirements are filtering out non-compliant imports, creating protected market space for qualified domestic and regional suppliers.
- Chilled distribution infrastructure:Cold-chain investments across Kuwait City retail corridors are enabling fresh-product margin capture previously concentrated in frozen bulk channels.
Market Restraints
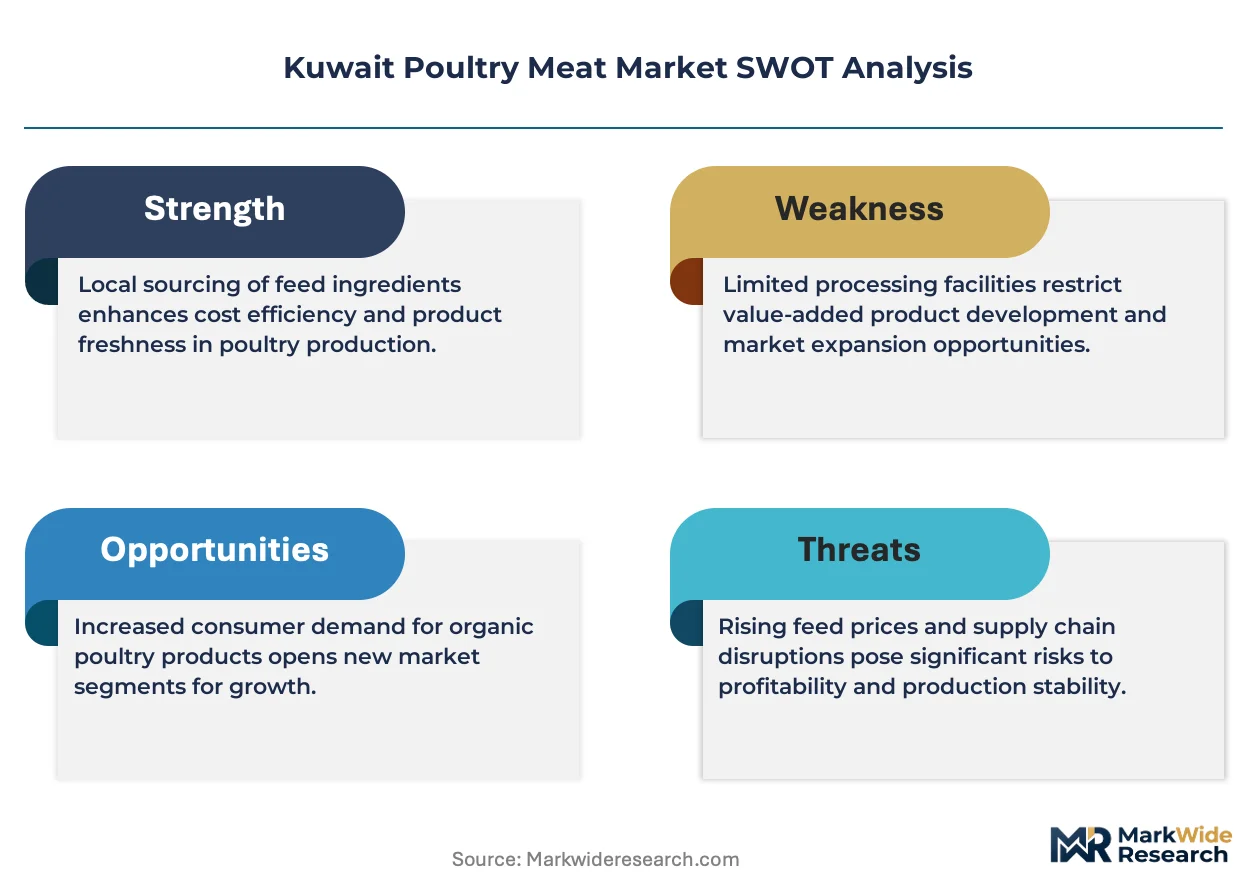
- Feed input cost volatility:Global grain price fluctuations transmit directly into domestic broiler production economics, compressing processor margins during supply shocks.
- Import concentration risk:Frozen poultry sourcing remains concentrated through GCC tariff-advantaged regional suppliers, limiting diversification options during trade disruptions.
- Wastewater compliance constraints:Environment Public Authority emissions regulations restrict capacity expansion at older industrial zones in Al-Jahra.
Strategic Opportunities
- Al-Wafra production cluster:Integrated breeding-to-processing facilities in southern Kuwait offer land and water access for domestic capacity expansion.
- Value-added marinated segments:Time-constrained consumers are trading up from raw whole-bird purchases, creating white space for prepared-product innovation.
- Carbon-footprint disclosure readiness:Early alignment with emerging supply-chain transparency requirements positions qualified suppliers for future procurement criteria.
Industry Challenges
- Halal-slaughter certification timelines:Extended approval processes for import eligibility and plant licensing delay market entry for new suppliers.
- Cold-chain integrity maintenance:Temperature-controlled logistics requirements across Kuwait's summer heat stress equipment reliability and operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Poultry Meat Market |
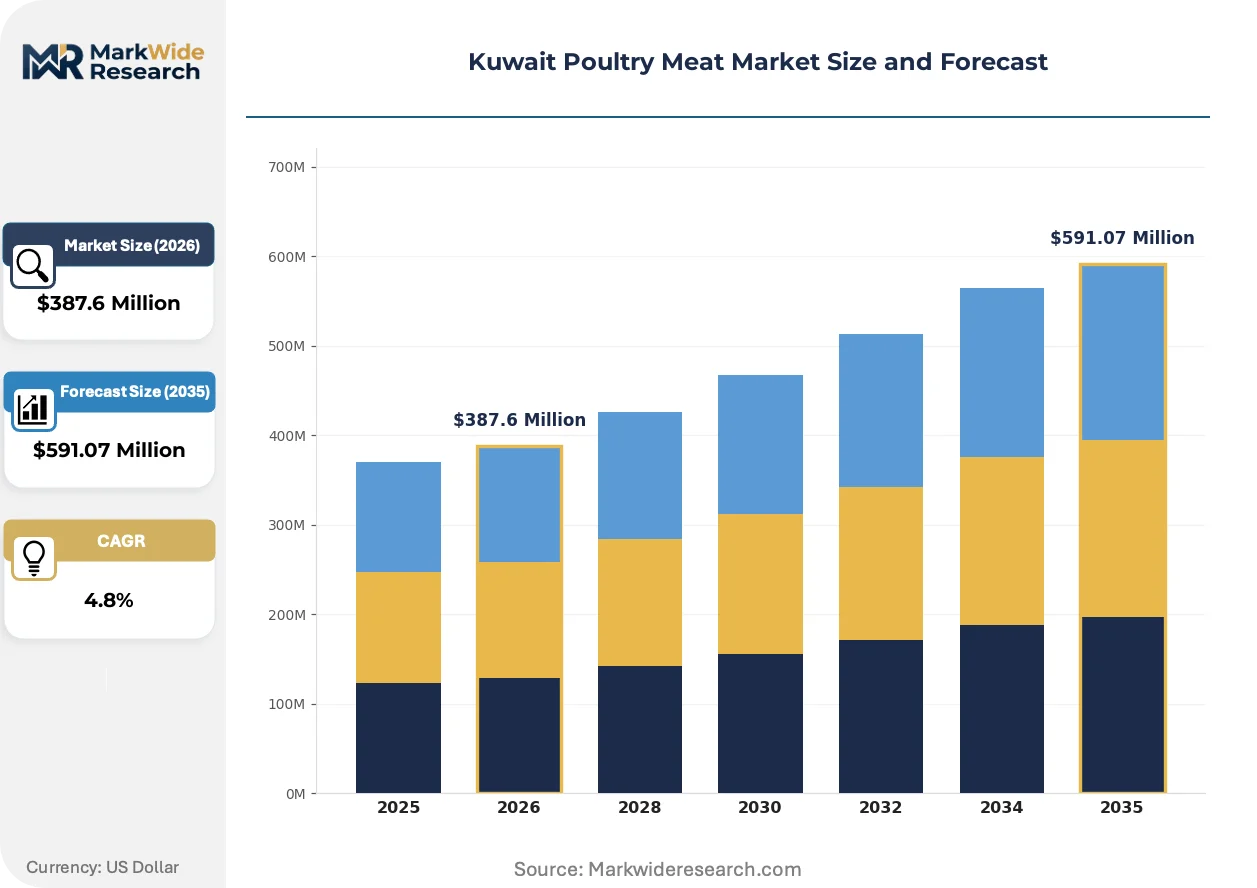
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Turkey, Duck, Quail Processing Method: Fresh, Frozen, Processed, Marinated Distribution Channel: Supermarkets, Local Markets, Online, Wholesale Packaging Type: Tray, Vacuum Sealed, Bulk, Retail Packs |
| Companies Covered | BRF S.A., Sunbulah Group, Kuwait United Poultry Company (KUPCO), Lulu International Group, Al-Watania Poultry Company, Almarai Food Company, The Savola Group, JBS SA, Americana Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Poultry Meat Market Trends and Innovations
Processing technology and certification standards are restructuring competitive advantage in Kuwait's poultry supply base, with automation and traceability systems separating specification-tier suppliers from commodity competitors.
Automated halal-slaughter and evisceration systems are displacing manual processing lines in Kuwaiti facilities capable of capital investment. Foodservice operators and supermarket chains are prioritizing suppliers with mechanized consistency for volume contracts. This technology compression is marginalizing smaller processors dependent on labor-intensive methods.
Kuwait's Public Authority for Food and Nutrition residue-testing protocols are extending detection requirements for antibiotics and growth promoters. Import shipments face enhanced laboratory screening at port of entry, lengthening clearance timelines. Domestic processors with in-house testing capabilities are capturing preference from buyers seeking supply predictability.
Quick-service restaurant chains are consolidating procurement through direct supplier relationships, bypassing traditional wholesale intermediaries. This channel compression concentrates volume with integrated breeding-to-retail operators. The shift is most visible in Kuwait City and Hawalli Governorate, where franchise density supports dedicated distribution routes.
Kuwait Poultry Meat Market Segmentation
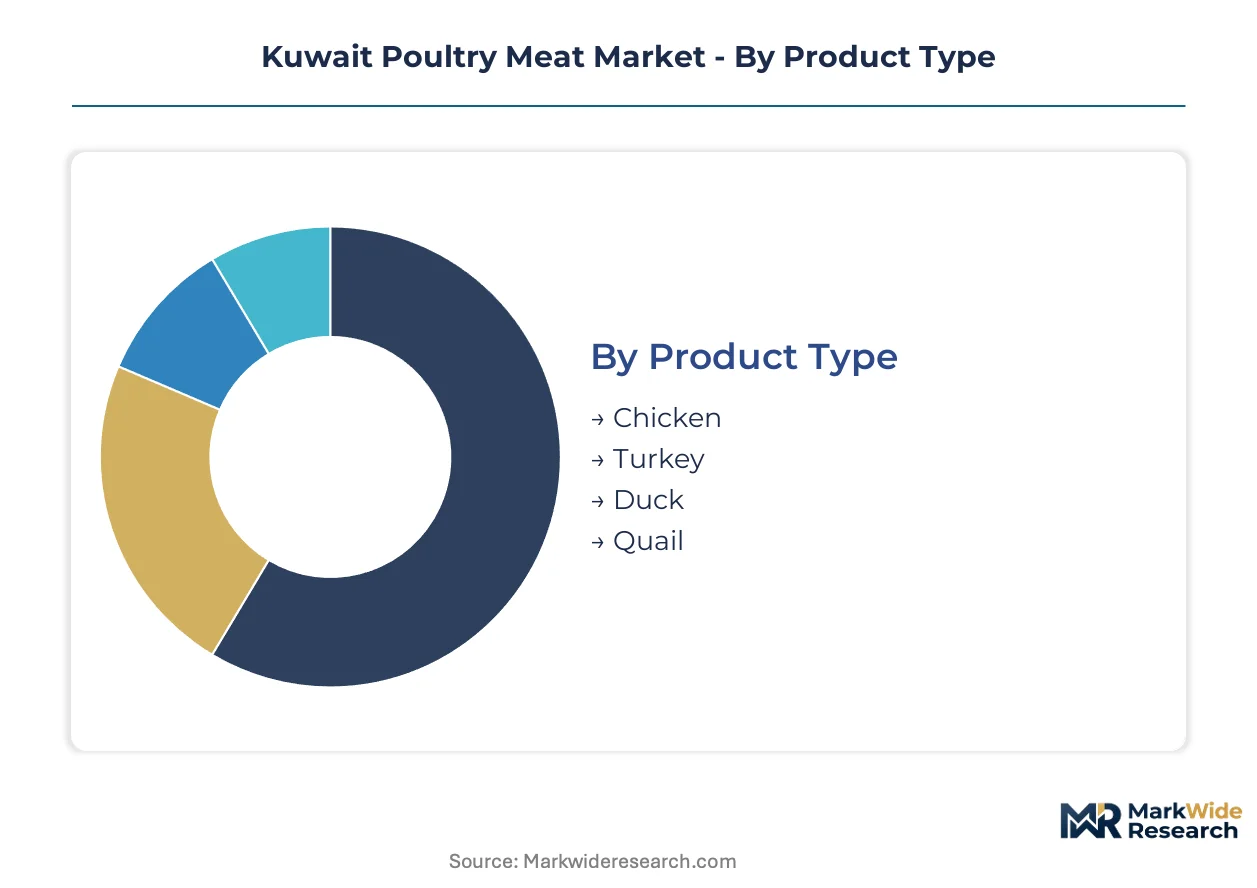
Kuwait's poultry meat segmentation reflects divergent margin structures across temperature states and channel formats. Each dimension carries distinct regulatory exposure and capital intensity requirements that reshape supplier economics.
Product Type:
Substitution pressure from red meat alternatives and plant-based proteins varies sharply by avian species, with smaller birds facing intensified cross-category competition.
- Chicken:Broiler muscle tissue harvested at 35-42 days dominates protein throughput across Kuwaiti retail and foodservice channels. Demand concentrates in Kuwait City and Hawalli Governorate quick-service restaurant chains where franchise operators prioritize consistent portion weights and halal certification documentation.
- Turkey:Heavier carcass weights and longer grow-out periods position this segment for institutional catering and holiday-season retail surges. Procurement from Saudi and Brazilian suppliers fills domestic production gaps, with chilled whole-bird shipments commanding premium positioning in supermarket deli counters.
- Duck:Niche positioning in Asian-cuisine restaurant segments with limited household penetration.
- Quail:Specialty game-bird category serving traditional medicine and high-end dining applications with restricted volume scale.
Chicken anchors the volume base while turkey gains share at the steepest rate among alternative species.
Processing Method:
Cost tier stratification separates capital-intensive chilled infrastructure from commodity frozen handling, with processed segments capturing disproportionate margin expansion.
- Fresh:Blast-chilled carcasses and primal cuts distributed at 0-4 degrees Celsius retain highest per-kilogram valuations. Cold-chain investments across Kuwait City retail corridors enable supermarket premium positioning where temperature integrity justifies price markups over frozen alternatives.
- Frozen:Blast-frozen at minus 18 degrees Celsius for extended shelf stability, this segment occupies volume leadership through local market bulk procurement and institutional tender awards. GCC tariff-advantaged regional suppliers dominate import flows.
- Processed:Mechanically separated and formed products including nuggets and patties serve quick-service restaurant specifications with standardized portion control.
- Marinated:Value-added preparations with spice blends and tenderizing agents target time-constrained household segments in Salmiya and Fahaheel retail zones.
Frozen processing commands absolute tonnage while marinated formulations climb the fastest on consumer convenience premiums.
Distribution Channel:
Customer type concentration is restructuring procurement relationships, with institutional buyers consolidating volume through direct supplier contracts that disintermediate traditional wholesale layers.
- Supermarkets:Chilled display cases and private-label programs in The Avenues and 360 Mall retail clusters capture premium household spending. Cold-chain integrity requirements filter supplier qualification toward integrated operators with captive distribution assets.
- Local Markets:Traditional souk formats in Farwaniya and Jahra governorates handle frozen bulk breaking for price-sensitive segments and small restaurant accounts.
- Online:Delivery-platform partnerships with quick-commerce operators expand refrigerated last-mile coverage into residential compounds.
- Wholesale:Institutional catering and restaurant supply through central kitchen contracts concentrates volume with breeding-to-retail integrated processors.
Supermarkets anchor the value base while online channels gain penetration at the steepest rate among emerging formats.
Packaging Type:
Supply concentration in modified-atmosphere technologies is separating specification-tier suppliers from commodity competitors on shelf-life extension capabilities.
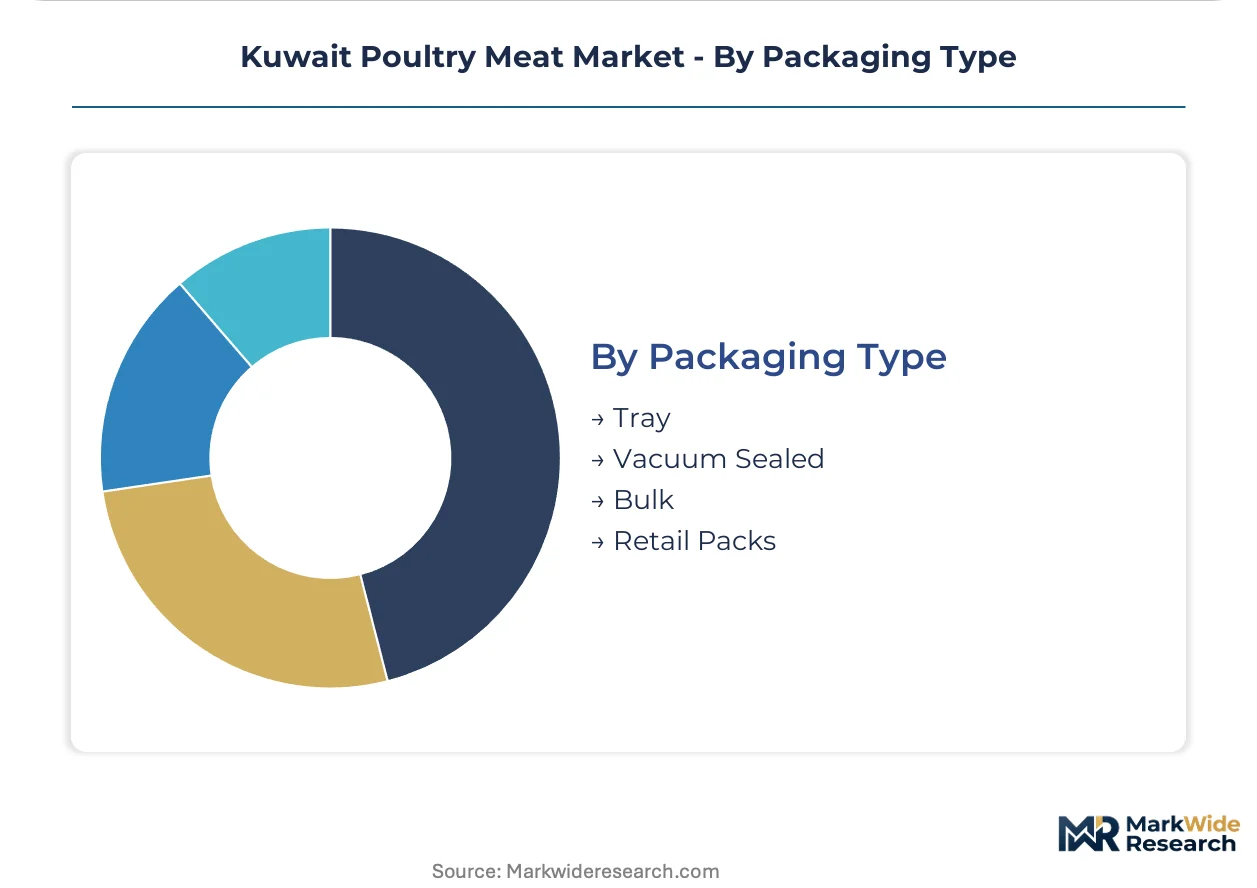
- Tray:Expanded polystyrene or PET containers with absorbent pads dominate fresh retail presentation in supermarket meat counters. Kuwait City retail corridors prioritize leak-resistant designs for display aesthetics and food safety compliance.
- Vacuum Sealed:Barrier-film evacuation extends chilled shelf life from days to weeks, enabling central kitchen pre-portioning and export-grade handling standards.
- Bulk:10-20 kilogram corrugated containers serve foodservice and industrial processing accounts with minimal unit packaging cost.
- Retail Packs:Pre-weighed 500 gram to 2 kilogram formats with printed halal certification and traceability coding satisfy modern trade barcode requirements.
Tray packaging anchors the volume base while vacuum-sealed formats gain adoption at the steepest rate on shelf-life extension premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait's poultry trade flows reflect a structural deficit between domestic broiler output and per-capita consumption, with frozen imports from Brazil and Saudi Arabia filling volume gaps while chilled premium product enters through UAE re-export channels.
Kuwait City
Supermarket chains and quick-service restaurant clusters in The Avenues and 360 Mall corridors drive chilled poultry demand. The Public Authority for Food and Nutrition enforces halal-slaughter documentation at all retail entry points. Cold-chain logistics providers concentrate distribution assets in Shuwaikh Industrial Area to serve high-frequency replenishment cycles.
Hawalli Governorate
Franchise density from global QSR brands creates dedicated procurement routes for portion-controlled products. The Environment Public Authority regulates wastewater discharge from processing facilities in older industrial zones. Salmiya retail corridors host the highest concentration of marinated and value-added poultry SKUs targeting time-constrained households.
Al-Jahra Governorate
Industrial-scale breeding and slaughtering operations anchor domestic supply contribution. Kuwait United Poultry Company maintains integrated facilities subject to Environment Public Authority emissions compliance. Capacity expansion faces land and water access constraints relative to southern Kuwait alternatives.
Al-Wafra
Southern Kuwait's agricultural cluster offers land availability for integrated breeding-to-processing investments. Groundwater access and proximity to Saudi border logistics support regional supply chain positioning. New entrant facilities here bypass older industrial zone regulatory burdens affecting northern governorates.
Al-Farwaniyah Governorate
Traditional souk formats handle frozen bulk breaking for price-sensitive segments and small restaurant accounts. The General Administration of Customs processes GCC tariff-advantaged regional imports through this corridor. Wholesale intermediaries here face margin compression from direct supplier relationships consolidating at foodservice chain level.
Kuwait Poultry Meat Market Competitive Landscape
Listed leaders compete with private specialists across certification and distribution capabilities, creating a tiered structure where scale advantages separate integrated operators from commodity traders. The vendor base clusters around three strategic archetypes: Gulf-wide agribusiness conglomerates with captive cold-chain assets, domestic integrated producers controlling breeding through retail, and import-specialized traders leveraging GCC tariff structures. Competitive moves concentrate on direct procurement relationships with QSR chains and backward integration into feed and breeding operations.
Within the domestic integrated tier, Kuwait United Poultry Company and Al-Watania Poultry Company exemplify breeding-to-retail operators with captive distribution into Kuwaiti channels. Among Gulf-wide conglomerates, Almarai Food Company and BRF S.A. occupy positions shaped by chilled logistics networks and halal-processing specialization respectively. These three anchors represent distinct competitive vectors: domestic land and water access, regional cold-chain density, and international halal-certification scale.
| Leading Market Players |
|---|
| BRF S.A. |
| Sunbulah Group |
| Kuwait United Poultry Company (KUPCO) |
| Lulu International Group |
| Al-Watania Poultry Company |
| Almarai Food Company |
| The Savola Group |
| JBS SA |
| Americana Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Kuwaiti foodservice chains and integrated poultry processors lock in chilled product access while stabilizing price visibility against feed grain volatility. These arrangements concentrate procurement leverage with breeding-to-retail operators who can guarantee halal certification documentation and temperature-controlled delivery cadences.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures across institutional catering and quick-service restaurant procurement lanes. Three-tier pricing structure across premium chilled, standard frozen, and economy bulk tiers separates suppliers by cold-chain investment depth and certification grade. Cost compression in the frozen tier is intensifying because Brazilian and Saudi import volumes compete on GCC tariff advantages. Small restaurant accounts in Farwaniya souks exhibit highest price sensitivity, while supermarket chains in The Avenues corridor prioritize supply predictability over unit cost.
Supply Chain Analysis
Brazil and Saudi Arabia anchor frozen poultry export volumes into Kuwait, while domestic Al-Jahra and Al-Wafra facilities supply chilled fresh product. Feed grain draws from Black Sea and North American origins, with soybean meal and corn anchoring broiler production economics. Single-source vulnerability concentrates in GCC-advantaged regional imports during trade route disruptions. Distribution runs through Shuwaikh Industrial Area cold-chain hubs for retail replenishment and direct-to-kitchen drops for consolidated foodservice accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's poultry market sits in early-cycle expansion as protein-rich dietary shifts penetrate household consumption beyond traditional red meat baselines. Halal certification mandates and chilled infrastructure investments create protected runway for qualified suppliers.
For Market Incumbents: Shield margin position by deepening backward integration into Al-Wafra breeding facilities and securing Environment Public Authority pre-approvals for capacity expansion. Plant-based protein entrants from European suppliers threaten conventional poultry's health-positioning narrative, making residue-testing certification investment the priority defensive lever. For New Entrants and Emerging Players: Differentiate on marinated and value-added convenience segments where time-constrained Salmiya households trade up from raw whole-bird purchases. Al-Wafra's land and water access offers the most penetrable geography for greenfield integrated facilities. A direct procurement pitch to quick-service restaurant chains bypassing wholesale intermediaries provides the clearest go-to-market angle. For Investors and Strategic Acquirers: Domestic integrated operators with captive cold-chain assets and halal certification scale represent the most viable acquisition archetype for medium-term consolidation plays. Long-term viability hinges on carbon-footprint disclosure readiness positioning suppliers for emerging procurement criteria. Watch for Public Authority for Food and Nutrition shelf-life labeling revisions as the inflection signal requiring supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captive grain sourcing insulates KUPCO and Al-Watania from Black Sea price volatility. |
| Halal Certification Scale-Up | BRF S.A.'s dedicated Middle East processing lines accelerate Kuwait import clearance timelines. |
| Chilled Distribution Network Expansion | Almarai's Gulf-wide cold-chain density enables consistent zero-to-four-degree delivery into retail. |
| Value-Added Product Line Launch | Marinated SKUs in Salmiya and Fahaheel corridors capture convenience premiums from working households. |
| Direct QSR Procurement Partnership | Bypassing Farwaniya wholesale layers concentrates volume with integrated breeding-to-retail operators. |
Research Methodology
Initial hypotheses were tested against primary input from poultry processing plant managers, foodservice procurement directors, supermarket category buyers, and cold-chain logistics operators and refined through secondary validation. Trade data from the General Administration of Customs, Public Authority for Food and Nutrition regulatory filings, Environment Public Authority emissions records, and GCC agricultural statistics anchored supply-side quantification. Bottom-up volume triangulation across processing facilities and top-down consumption modeling from household expenditure surveys converged on segment-level estimates.
Variance decomposition across product type, processing temperature state, distribution channel format, and packaging technology dimensions structured the analytical framework. CAGRs were derived from trend extrapolation moderated by regulatory event probabilities and infrastructure investment pipelines. Feed grain price scenarios and halal certification approval timelines served as industry-specific sensitivity inputs throughout the projection horizon.
Material uncertainties — feed input cost spikes, trade route disruptions, and regulatory shelf-life revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about consumer protein substitution patterns and cold-chain penetration rates. Recalibration cycles align with material shifts in Public Authority for Food and Nutrition mandates and Environment Public Authority emissions enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market