
 Floriculture Market | 2026-2036
Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Floriculture Market Intelligence
Specialty grower capacity for organic and sustainably-certified potted plants is expanding in key production zones like Colombia and Kenya. Dümmen Orange specializes in breeding and developing new flower and plant varieties. Ball Horticultural leverages its extensive global distribution network to serve diverse markets. Syngenta Flowers differentiates through its investment in genetic research and seed technology to improve plant resilience.
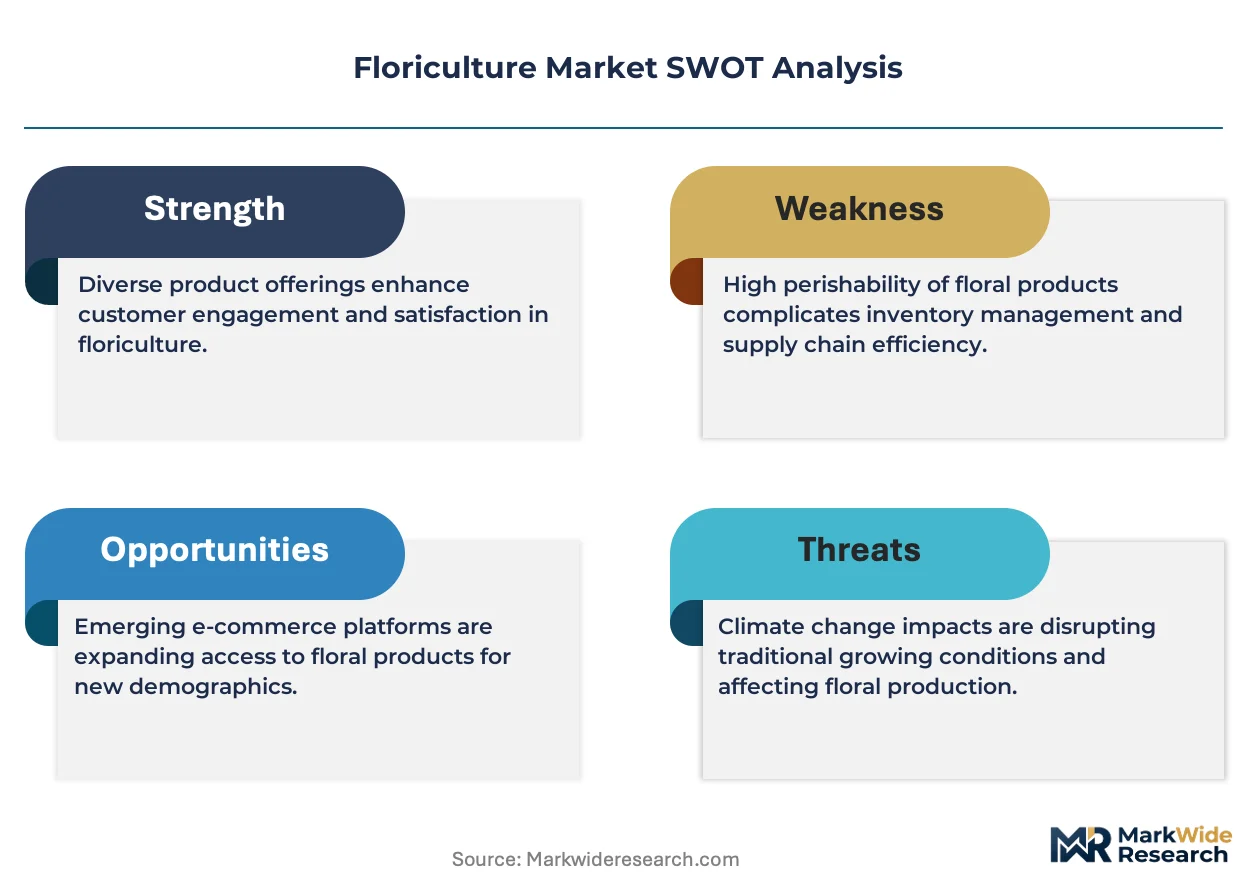
Floriculture encompasses the science and practice of cultivating flowering and ornamental plants, often within controlled-environment agriculture systems to manage light and temperature. Its primary commercial purpose is the production of decorative plants for aesthetic use in homes and landscapes. Cut flowers remain a dominant product type by value, driven by the floral gifts and event decoration applications. Potted plants show significant momentum, supported by sustained interest in home decoration and gardening.
Regulatory frameworks, including the USDA's Animal and Plant Health Inspection Service (APHIS) protocols and the European Union's plant passport system, govern phytosanitary standards. These rules directly impact market access and supply chain costs for exporters. Success for stakeholders hinges on building supply chain resilience against climate and logistical disruptions.
Market Dynamics
The floriculture market's structure is defined by the logistical tension between globally dispersed, climate-dependent production zones and highly concentrated distribution hubs. This dynamic places immense pressure on cold chain efficiency and phytosanitary compliance to connect growers in regions like South America and Africa with consumers in Europe and North America.
Growth Catalysts
- CRISPR Gene Editing:This technology enables the rapid development of novel traits such as unique colors, extended vase life, and enhanced disease resistance, creating new product categories and value opportunities for breeders.
- Event Decoration Sector:The expansion of corporate events, weddings, and hospitality industries provides a consistent, large-scale demand source for high-value cut flowers and ornamental plants, driving volume growth.
- Logistical Hubs:The Netherlands' advanced auction and distribution infrastructure, particularly around Aalsmeer, acts as a critical enabler for global trade, providing liquidity and efficient market access for producers worldwide.
Market Restraints
- Input Cost Volatility:High dependency on air freight creates direct exposure to fuel price volatility, while controlled-environment agriculture is sensitive to fluctuating energy costs, compressing grower margins.
- Phytosanitary Regulations:Strict protocols from bodies like the USDA's APHIS and the EU's plant passport system create significant compliance costs and potential delays, acting as non-tariff barriers for exporters.
- Product Perishability:The extremely short shelf-life of cut flowers results in a high-risk supply chain with significant potential for spoilage and value loss, particularly during logistical disruptions.
Strategic Opportunities
- Durable Potted Plants:Developing low-maintenance, long-lasting indoor plant varieties caters to sustained consumer interest in home wellness and biophilic design, opening a market less dependent on event-driven demand.
- Direct-to-Consumer Channels:Subscription-based services and e-commerce platforms offer a pathway to bypass traditional retail intermediaries, allowing growers to capture more value and build direct customer relationships.
- Sustainable Certification:Expansion of organic and sustainably-certified lines meets consumer demand for ethical sourcing in key import markets, creating price differentiation opportunities for producers in Colombia and Kenya.
Industry Challenges
- Resource Management:Optimizing water and energy use within greenhouses and other controlled-environment agriculture systems remains a persistent operational challenge, impacting both production costs and sustainability credentials.
- Cold Chain Resilience:The necessity for an unbroken cold chain from farm to consumer makes the industry vulnerable to climate-related disruptions, transportation bottlenecks, and geopolitical events that affect freight routes.
- Intellectual Property Protection:Protecting intellectual property for new plant varieties developed via techniques like CRISPR presents a complex legal challenge, particularly across different international jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floriculture Market |
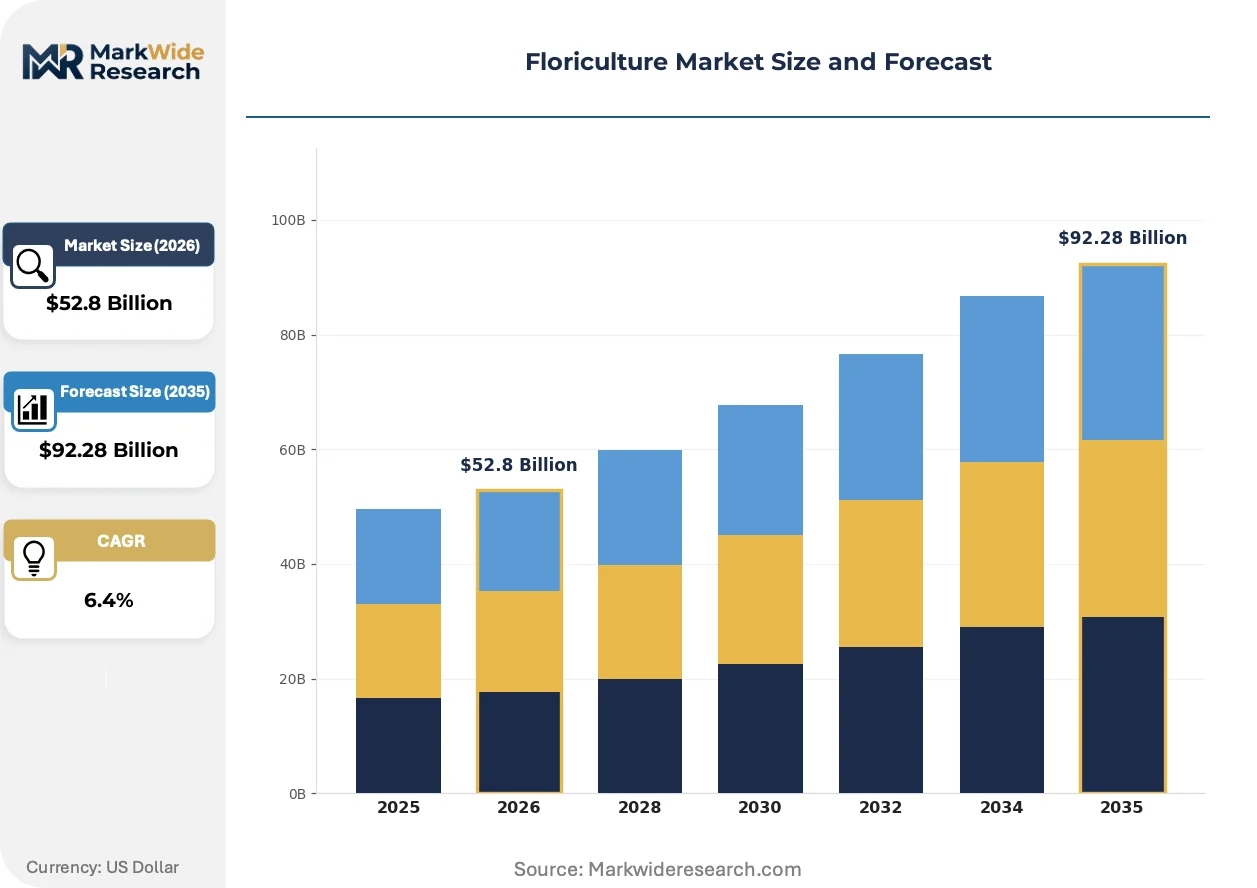
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cut Flowers, Potted Plants, Foliage Plants, Flower Seeds, Bulbs & Tubers Application: Home Decoration, Landscaping, Event Decoration, Floral Gifts, Corporate Gifting End User: Florists, Nurseries, Event Planners, Hospitality Sector, Garden Centers Distribution Channel: Online Retailers, Local Markets, Wholesale Dealers, Exporters, Garden Supply Stores |
| Companies Covered | Ball Horticultural, Costa Farms, Flamingo Horticulture, Green Circle Growers, Beekenkamp Plants, Dümmen Orange, Florensis, Monrovia Nursery Company, Syngenta Flowers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floriculture Market Strategic Shifts & Innovations
The convergence of advanced biotechnology with sustainable agricultural practices is reshaping competitive positioning. Innovations are focused on enhancing plant traits through genetic science while simultaneously addressing regulatory and consumer pressures for greater environmental transparency across the supply chain.
CRISPR gene-editing technology allows for the precise and rapid modification of plant genetics to improve traits like disease resistance, drought tolerance, and vase life. Specialized breeders and large-scale horticultural companies are adopting this tool to shorten development timelines for new commercial varieties. This advanced capability is consolidating market influence with firms that possess significant genetic research expertise and can secure intellectual property rights.
The European Union’s Corporate Sustainability Reporting Directive (CSRD) is creating new benchmarks for environmental and social governance disclosure. This framework compels large growers and distributors exporting to the EU to report detailed data on water usage, pesticide application, and labor conditions. The potted plant segment, with its longer production cycles, is most impacted, driving investment in auditable supply chain tracking systems.
A significant behavioral shift is the rise of subscription-based purchasing models for fresh flowers and potted plants. This approach often bypasses traditional florists and supermarkets, creating space for online-native, direct-to-consumer (DTC) brands that offer curated selections. This trend is most visible in major urban centers across North America and Western Europe, where convenience and personalization are primary purchase drivers.
Floriculture Market Segmentation
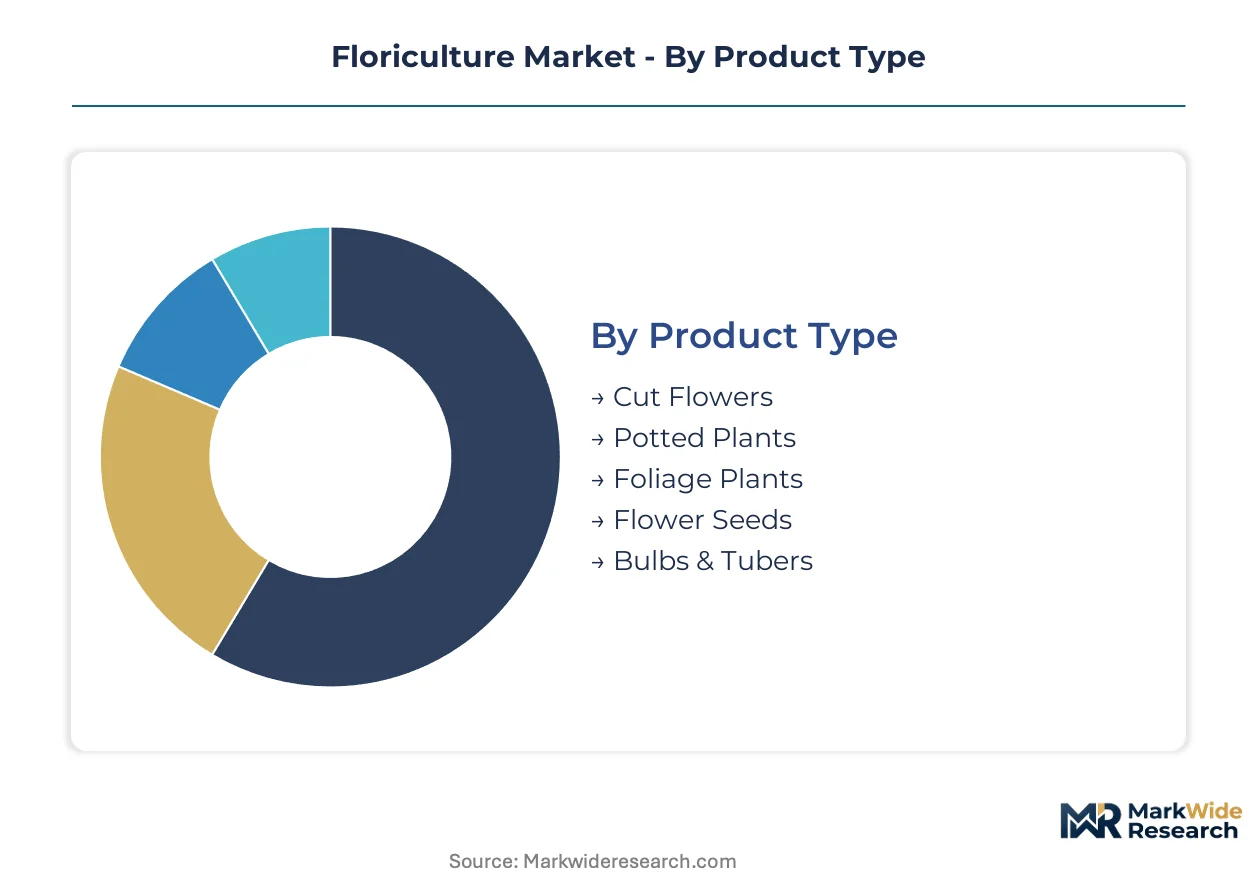
The floriculture market’s structure is defined by distinct product types, applications, end-users, and distribution channels. Understanding these segments is crucial for stakeholders navigating the complex interplay of production, logistics, and consumer preferences. Each segment presents unique growth opportunities and operational challenges for growers and distributors.
Product Type:
Compliance with phytosanitary regulations and specific import permits significantly impacts product type market access. These protocols, such as the USDA's APHIS and the EU's plant passport system, create compliance costs for exporters.
- Cut Flowers:This product type remains dominant by value, driven by floral gifts and event decoration applications. Demand concentrates in key import markets like Europe and North America, necessitating efficient cold chain logistics.
- Potted Plants:This segment shows significant momentum, supported by sustained interest in home decoration and gardening. Production in Colombia and Kenya is expanding for organic and sustainably-certified varieties, catering to ethical consumer demand.
- Foliage Plants:These plants provide long-lasting aesthetic appeal for indoor and outdoor environments, offering a durable alternative to cut flowers.
- Flower Seeds:Flower seeds serve as a fundamental input for growers, enabling new variety development through advanced genetic research.
- Bulbs & Tubers:These specialized planting materials are crucial for the cultivation of seasonal flowering plants, particularly in regions with distinct growing seasons.
Leading the category by volume: Cut Flowers. Growing fastest: Potted Plants.
Application:
The diverse applications of floriculture products reflect varying consumer needs and commercial functions. Each application influences demand patterns and product specifications across the supply chain.
- Event Decoration:This segment provides consistent, large-scale demand for high-value cut flowers and ornamental plants. Corporate events, weddings, and hospitality industries drive significant volume growth in this application.
- Home Decoration:Sustained consumer interest in home wellness and biophilic design supports demand for durable potted plants. This application segment is less dependent on event-driven demand fluctuations, offering stability.
- Landscaping:Ornamental plants are utilized for aesthetic enhancement of outdoor spaces, including public parks and private gardens.
- Floral Gifts:This traditional application for cut flowers is driven by personal celebrations and expressions of sentiment.
- Corporate Gifting:Businesses leverage floral arrangements and plants for client appreciation, employee recognition, and office beautification initiatives.
Consumer preferences for aesthetic enhancement influence demand across these applications.
End User:
Customer types within the floriculture market exhibit distinct procurement patterns and product requirements. Each end-user segment contributes uniquely to market demand and distribution dynamics.
- Florists:These traditional retail channels for cut flowers serve individual consumers for various occasions. Florists often source products from wholesale dealers or local markets, requiring diverse selections.
- Event Planners:Event planners require large volumes of specific cut flowers and ornamental plants for corporate events and weddings. Their purchasing decisions are often driven by budget constraints and thematic requirements.
- Nurseries:Nurseries cultivate and supply young plants, often serving as a primary source for landscapers or other growers.
- Hospitality Sector:Hotels, restaurants, and resorts utilize floral arrangements for ambiance and to enhance the guest experience.
- Garden Centers:These retail outlets specialize in offering potted plants, seeds, and gardening supplies, catering directly to home gardeners.
Distribution channel efficiency is critical for effectively serving these diverse end-user segments.
Distribution Channel:
The efficiency of distribution channels is paramount for connecting globally dispersed production zones with concentrated consumer demand. Cold chain logistics and market access are critical factors.
- Wholesale Dealers:These entities form the backbone of the floriculture supply chain, aggregating products from growers for onward distribution to florists and event planners. They leverage logistical hubs like Aalsmeer.
- Online Retailers:Online platforms offer direct-to-consumer channels, bypassing traditional intermediaries and leveraging subscription-based models. This channel is gaining share fastest in urban centers across North America and Western Europe.
- Local Markets:Local markets provide direct access to fresh produce for consumers and small businesses, fostering regional trade.
- Exporters:Exporters facilitate international trade, particularly from production zones in Colombia and Kenya to major consumption markets.
- Garden Supply Stores:These specialized retailers offer a range of potted plants, seeds, and gardening accessories to home enthusiasts.
Technology adoption and cold chain resilience significantly influence the performance of these distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands, a pivotal logistical hub, anchors global floriculture trade by facilitating efficient distribution from diverse production zones. This market relies on robust cold chain infrastructure and stringent phytosanitary compliance to connect growers with major consumer markets. Demand patterns shift with regional preferences, influencing both product types and distribution channels.
Netherlands
The Netherlands drives global trade volume through its advanced auction system and re-export capabilities. The European Union’s plant passport system ensures phytosanitary compliance for all imports and exports. The Aalsmeer region, with its extensive auction and distribution infrastructure, serves as a critical enabler for worldwide floriculture commerce.
Colombia
Colombia leads in the production of high-quality cut flowers and expanding organic potted plant varieties. Exporters adhere to USDA's Animal and Plant Health Inspection Service (APHIS) protocols for market access to North America. The Bogotá savanna region concentrates numerous large-scale flower farms, specializing in export-oriented cultivation.
Kenya
Kenya is a major producer of cut flowers, primarily targeting European markets with sustainably-certified products. Compliance with the European Union’s Corporate Sustainability Reporting Directive (CSRD) is becoming crucial for Kenyan exporters. The Naivasha area, known for its ideal climate and lake access, hosts a significant cluster of large-scale flower farms.
United States
The United States represents a substantial import market for cut flowers and a growing segment for durable potted plants. Strict USDA's APHIS regulations govern all plant imports, ensuring biosecurity. California, a large consumer market with diverse climates, also supports specialized domestic floriculture production and distribution centers.
Germany
Germany exhibits strong consumer demand for home decoration and sustainably-sourced floral products. The EU plant passport system facilitates intra-European trade, while CSRD influences import standards. The Rhine-Ruhr metropolitan region serves as a major consumption area and a key distribution point for floriculture products across Central Europe.
Floriculture Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-value segments like durable potted plants. The market exhibits a tiered structure, with large-scale breeders and distributors alongside niche cultivators. Strategic archetypes include genetic innovators, logistics-focused distributors, and sustainable specialty growers. Competitive moves involve portfolio diversification and geographic expansion to secure supply chains.
Specialists in plant breeding and genetic innovation include Dümmen Orange, which focuses on developing new flower and plant varieties. Ball Horticultural exemplifies a distribution-centric archetype, leveraging its extensive global network to serve diverse markets. Syngenta Flowers represents firms investing heavily in genetic research and seed technology to improve plant resilience and traits.
| Leading Market Players |
|---|
| Ball Horticultural |
| Costa Farms |
| Flamingo Horticulture |
| Green Circle Growers |
| Beekenkamp Plants |
| Dümmen Orange |
| Florensis |
| Monrovia Nursery Company |
| Syngenta Flowers |
| Others |
Cost & Logistics Intelligence
Outsourced logistics and specialized cold chain management anchor the floriculture market's supply position and influence its pricing power. This market connects globally dispersed production with concentrated consumer demand through sophisticated, time-sensitive networks.
Pricing Analysis
After-sales service bundling, particularly for large event orders, influences the final price for floriculture products. Per-unit transactional pricing dominates for cut flowers, while contract-based long-term offtake agreements are common for bulk potted plant purchases. Price differentiation stems from certification levels, such as sustainably-certified varieties from Kenya, and volume scale for wholesale buyers. Margins are tightening due to input cost volatility, especially fuel prices for air freight. Event planners and large hospitality groups are highly price-sensitive, while individual consumers purchasing floral gifts often prioritize aesthetic value over cost.
Supply Chain Analysis
Wholesale dealers and online retailers form the primary distribution channels, connecting growers to end-users. Geographic supply concentration centers on Colombia and Kenya for production, with the Netherlands serving as a critical re-export hub. The market relies heavily on specific inputs like specialized seeds, fertilizers, and packaging materials. A structural risk involves cold chain disruptions, which can lead to significant product spoilage and value loss due to extreme perishability. Distribution runs through a complex network of air freight and refrigerated transport, ensuring product integrity from farm to market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The floriculture market is currently experiencing a vertical-integration race, with players pursuing upstream control over genetic research and downstream expansion into direct-to-consumer channels.
For Market Incumbents: Extend investment in genetic research, particularly CRISPR technology, to develop novel, resilient plant varieties. This defends against emerging entrants offering niche products and mitigates climate-related production threats. Focus on acquiring specialized logistics firms to enhance cold chain resilience and control distribution costs. Prioritize sustainable certification across global operations to meet evolving regulatory frameworks like the EU's CSRD.
For New Entrants and Emerging Players: Subscription-based e-commerce platforms offer a pathway to bypass traditional wholesale intermediaries and capture direct customer relationships. Target the durable potted plant segment, which is less susceptible to event-driven demand fluctuations and offers higher margins. Emphasize unique plant traits developed through genetic innovation and promote sustainable growing practices as a key go-to-market angle. The North American urban market for home decoration represents a penetrable segment.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized breeding companies with strong intellectual property portfolios or logistics-centric distributors controlling critical cold chain infrastructure. Long-term viability over the next 5-10 years favors firms capable of integrating advanced biotechnology with sustainable supply chain management. Acquisition targets should include companies with proven genetic research capabilities or established direct-to-consumer platforms. The signal to watch is the increasing market share of sustainably-certified and genetically enhanced plant varieties.
| Strategic Initiative | Industry Significance |
| CRISPR Trait Development | Creates proprietary plant varieties with enhanced disease resistance and extended vase life, securing competitive advantage. |
| Sustainable Certification Expansion | Meets growing consumer demand for ethical sourcing and ensures compliance with stringent import regulations in key markets. |
| Direct-to-Consumer Channel Buildout | Bypasses traditional intermediaries, allowing growers to capture more value and build stronger customer relationships. |
| Cold Chain Technology Investment | Mitigates product perishability risks and ensures efficient delivery of high-value cut flowers and plants globally. |
| Logistical Hub Optimization | Enhances efficiency in distribution from production zones to consumption markets, reducing supply chain costs and delays. |
Research Approach
Document review covered USDA's APHIS protocols, EU plant passport system guidelines, and industry association reports, complemented by interviews with floriculture growers, wholesale distributors, plant breeders, and event planners. This approach combined primary insights with secondary validation to construct a comprehensive market view. Bottom-up and top-down triangulation ensured data consistency across various market segments.
The quantitative model produced volume and value forecasts across the analysis window, segmented by product type, application, end-user, distribution channel, and regional phytosanitary compliance. Compound annual growth rates were derived from historical data trends and projected market dynamics. Key forecast inputs included global event sector growth projections and the adoption rate of genetic innovation in new plant varieties.
The model holds under stable climate conditions and predictable logistical operations; deviation in global fuel prices or major geopolitical events affecting freight routes would shift projections. Forecasts reflect assumptions regarding regulatory stability and consumer preference evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Ginseng Market