
 United Kingdom Poultry Meat Market | 2026-2036
United Kingdom Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Poultry Meat Market Insights
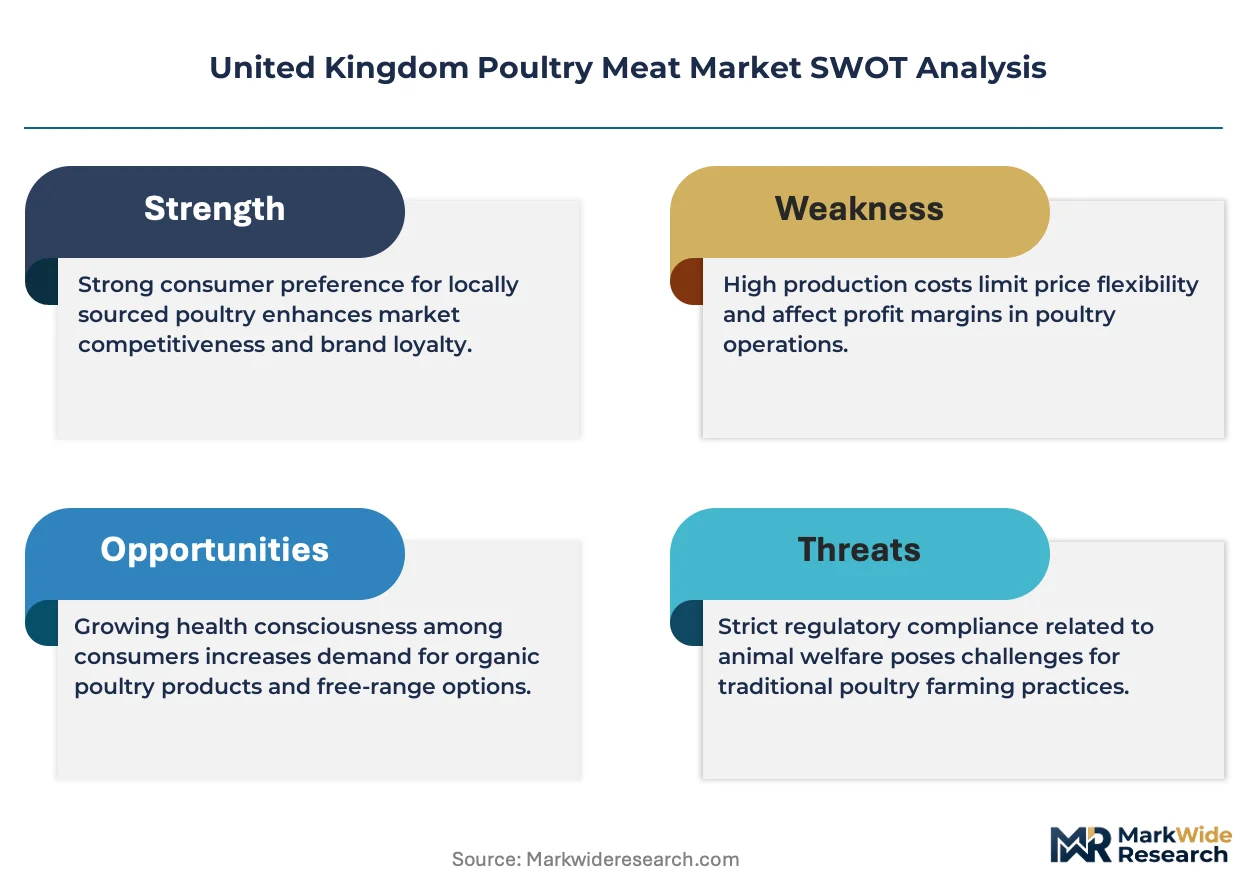
The price spread between premium free-range poultry and commodity broiler lines is hardening as retailers sharpen tiering strategies. Moy Park Ltd leverages its integrated supply chain across Northern Ireland and Great Britain to sustain cost advantages in volume segments. Cranswick plc differentiates through high-welfare and added-value product lines that command shelf space in premium retail channels.
United Kingdom poultry meat encompasses chicken, turkey, duck, and goose species raised for human consumption, with broiler chickens dominating output through intensive shed-rearing systems optimized for feed conversion ratios below 1.7:1. The primary commercial purpose centers on delivering protein-rich, cost-efficient meat to retail and food service channels. Chicken occupies the dominant volume position across supermarkets and wholesalers, while turkey demand concentrates seasonally around festive periods and prepared-meal applications. Frozen packaging formats retain significant share in bulk food service procurement, though vacuum-sealed retail packs are gaining traction in household channels.
The Food Standards Agency enforces hygiene and traceability standards that shape processing plant investments and operational protocols. Defra's welfare codes and the Animal Welfare (Kept Animals) Bill mandate housing specifications and stocking densities that directly affect production costs and farm-gate pricing. Stakeholders must monitor how post-Brexit import tariff adjustments and domestic welfare regulation divergence from EU standards reshape competitive dynamics between UK-sourced and imported poultry supplies.
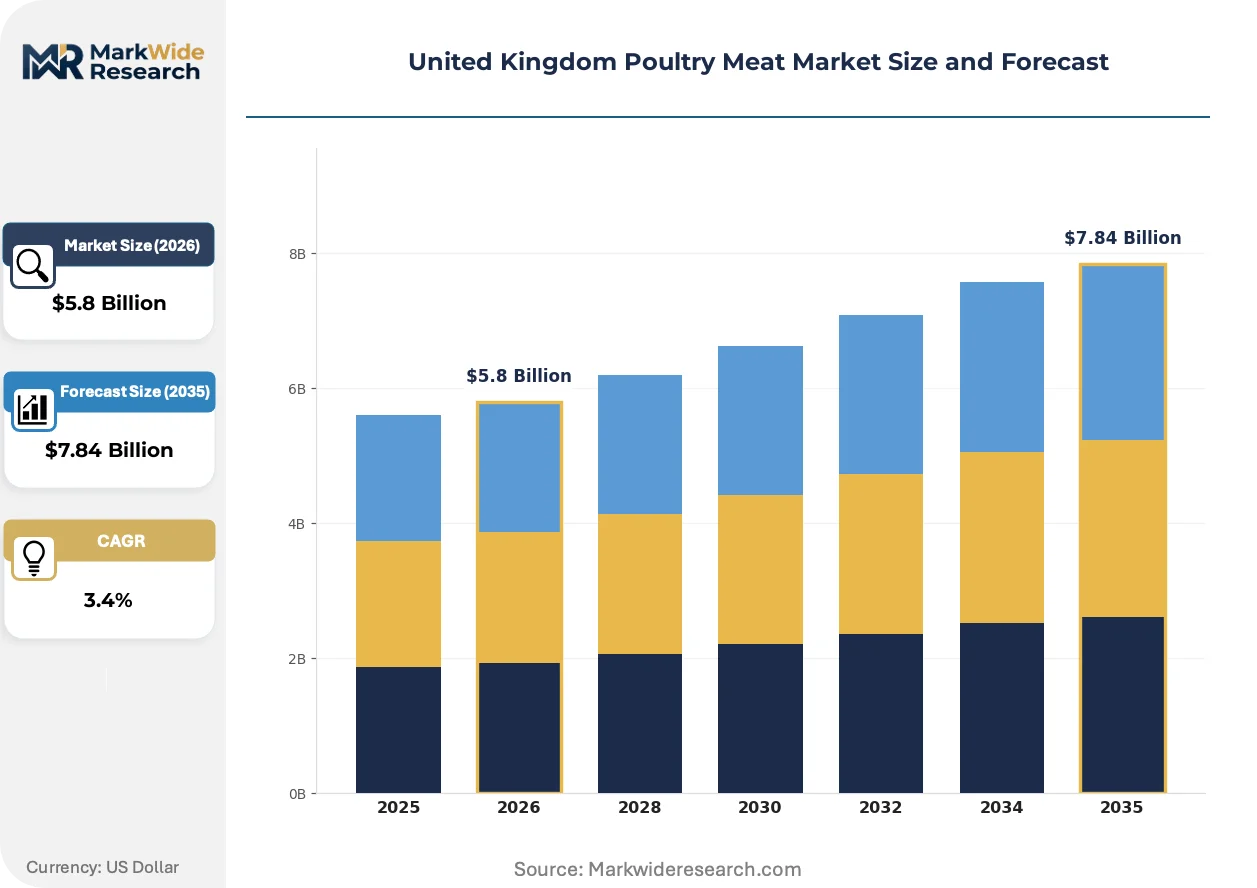
Market Dynamics
The Animal Welfare (Kept Animals) Bill is compressing production margins while food service chains accelerate poultry menu placements to capture consumer migration toward leaner proteins.
Growth Catalysts
- East Anglia Processing Corridor:Concentrated slaughter and processing infrastructure reduces logistics costs for broiler supply to London retail and food service channels.
- Defra Welfare Code Tiering:Premium certification tiers create price stratification that rewards higher-welfare investment with shelf space access in major supermarkets.
- Food Service Menu Expansion:Quick-service restaurants and casual dining chains are replacing red meat items with poultry-based alternatives to meet health-positioning demands.
Market Restraints
- Soybean Meal Import Dependency:UK feed compounders rely on South American and Black Sea soybean shipments, exposing margins to currency volatility and trade friction.
- Slaughterhouse Capacity Concentration:Four integrated processors control over 80% of licensed slaughter capacity, creating bottleneck risk during disease-related supply shocks.
- Lab-Grown Protein Substitution:Cultivated meat startups targeting UK approval by 2028 threaten long-term volume growth in conventional broiler segments.
Strategic Opportunities
- West Midlands Processing Investment:Underutilized cold-chain infrastructure offers expansion headroom for value-added poultry product manufacturing.
- Carbon Labeling Alignment:Defra's emerging environmental reporting standards create first-mover advantage for operations with verified low-emission feed rations.
- Direct-to-Restaurant Distribution:Bypassing wholesale intermediaries through dedicated fleet contracts captures margin currently lost to layered distribution.
Industry Challenges
- Veterinary Surgeon Shortage:Official Veterinarian certification requirements for slaughterhouse supervision outstrip training pipeline output, delaying plant approvals.
- Legacy ERP Integration:Food Standards Agency traceability mandates force expensive middleware development to connect farm management systems with processing plant databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Poultry Meat Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Turkey, Duck, Goose End User: Households, Food Service Chains, Retailers, Butchers Distribution Channel: Online, Direct Sales, Wholesalers, Supermarkets Packaging Type: Vacuum Sealed, Tray Pack, Canned, Frozen |
| Companies Covered | Boparan Holdings Ltd, Moy Park Ltd, Cranswick plc, Avara Foods Ltd, Danish Crown AmbA, Gressingham Foods, 2 Sisters Food Group, Karro Food Group, PHW Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Poultry Meat Market Trends and Innovations
Automation and welfare verification technologies are compressing labor costs while regulatory divergence from EU standards creates compliance complexity for cross-border supply chains.
Computer vision grading systems are automating carcass quality assessment at line speeds exceeding 135 birds per minute. Major processors in Northern England and Scotland are retrofitting existing plants with these systems to reduce manual inspection headcount. This technology is automating the labor-intensive grading decisions that previously required skilled operatives, compressing unit labor costs by standardizing defect detection thresholds.
Defra's post-Brexit divergence from EU welfare standards is creating dual compliance burdens for exporters serving both markets. The UK's proposed lower stocking density mandates exceed current EU requirements, forcing integrated producers to maintain separate housing specifications. Northern Ireland operations face the most acute friction, as they must simultaneously satisfy UK domestic retail contracts and EU export certification under the Windsor Framework.
Retail buyers are consolidating supplier relationships around single-source contracts with integrated processors who control farm-to-shelf traceability. Independent farm cooperatives are losing shelf space as supermarkets prioritize supply security over price competition. This concentration is most visible in England's Southeast, where Tesco and Sainsbury's procurement teams have reduced approved poultry supplier lists by 40% since 2022.
United Kingdom Poultry Meat Market Segmentation
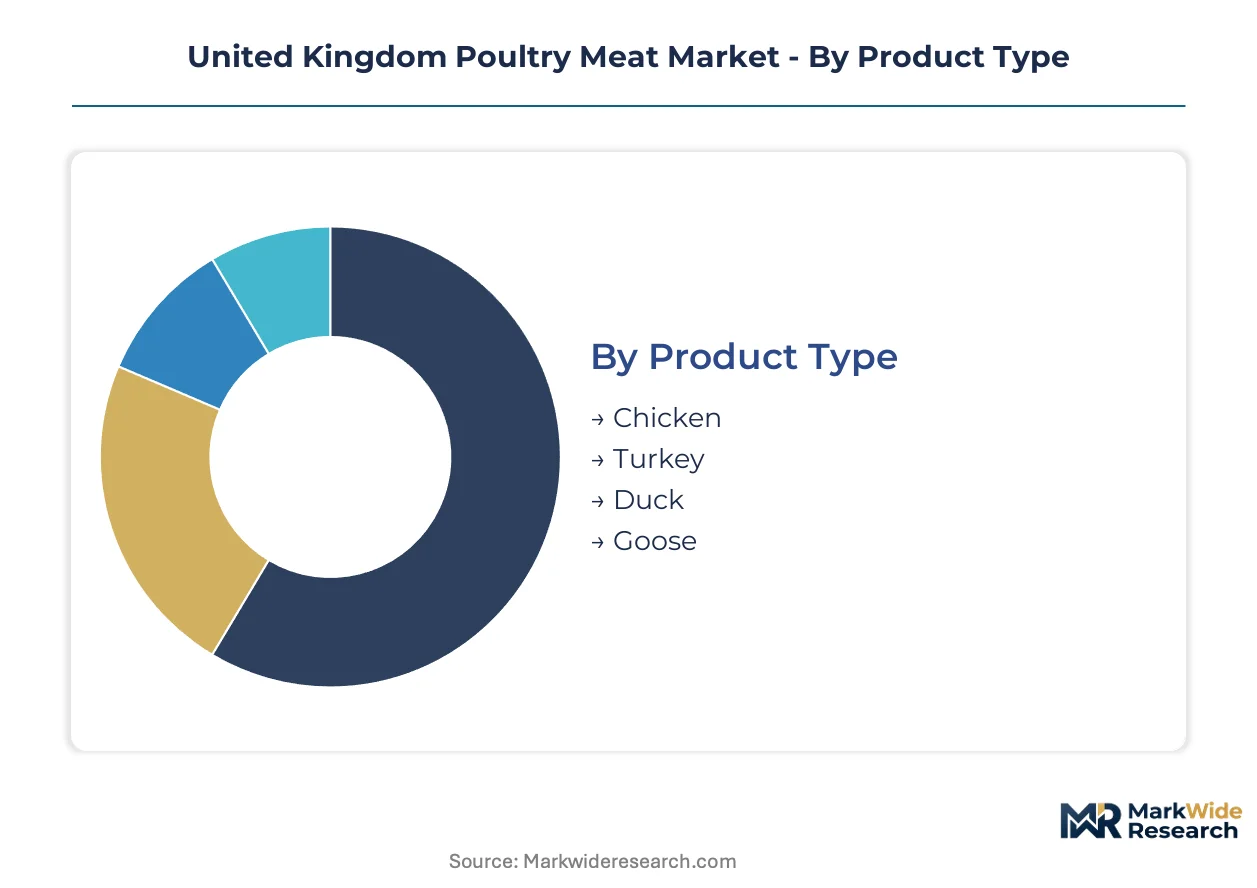
Poultry meat segmentation in the United Kingdom reflects divergent supply chain configurations across species, customer channels, and packaging formats. Each dimension carries distinct margin profiles and regulatory exposure that shape processor investment priorities.
Product Type:
Standardization dominates volume production while specialty species command premium positioning through welfare certification tiers.
- Chicken:Broiler production optimized for feed conversion ratios below 1.7:1 supplies the bulk of supermarket and food service volume. East Anglia processing corridors concentrate slaughter capacity to serve London retail channels with minimal logistics friction.
- Turkey:Seasonal demand peaks around festive periods drive prepared-meal applications and whole-bird retail. Defra welfare code tiering creates price stratification that rewards higher-welfare investment with shelf space access in premium retail channels.
- Duck:Niche positioning in Asian cuisine and fine dining segments supports smaller-scale production with specialized processing requirements.
- Goose:Limited commercial output concentrated in traditional festive markets and specialty butcher channels.
Most installed capacity flows through Chicken. Expansion is steepest in Turkey.
End User:
Customer concentration patterns split between price-sensitive volume procurement and relationship-driven premium contracting.
- Households:Vacuum-sealed retail packs gain traction as consumers prioritize convenience and extended shelf stability over frozen bulk formats.
- Food Service Chains:Quick-service restaurants and casual dining operators are replacing red meat items with poultry-based alternatives to meet health-positioning demands. Direct fleet contracts bypass wholesale intermediaries to capture margin.
- Retailers:Supermarket buyers consolidate supplier relationships around single-source contracts with integrated processors who control farm-to-shelf traceability.
- Butchers:Independent channels retain specialty species and premium welfare-tier products as differentiated offerings against supermarket commoditization.
Procurement concentrates through Food Service Chains. Margin expansion is strongest in Retailers.
Distribution Channel:
Channel selection determines cold-chain investment intensity and traceability system requirements.
- Online:Direct-to-consumer platforms require specialized last-mile temperature control but enable premium pricing for welfare-certified products.
- Direct Sales:Dedicated fleet contracts with restaurant groups eliminate wholesale layering and support just-in-time delivery schedules.
- Wholesalers:Bulk frozen procurement dominates food service supply with established credit terms and consolidated delivery routes.
- Supermarkets:Dominant retail channel with consolidated supplier lists and stringent traceability mandates enforced through Food Standards Agency protocols.
Volume throughput centers on Supermarkets. Digital infrastructure investment is climbing fastest in Online.
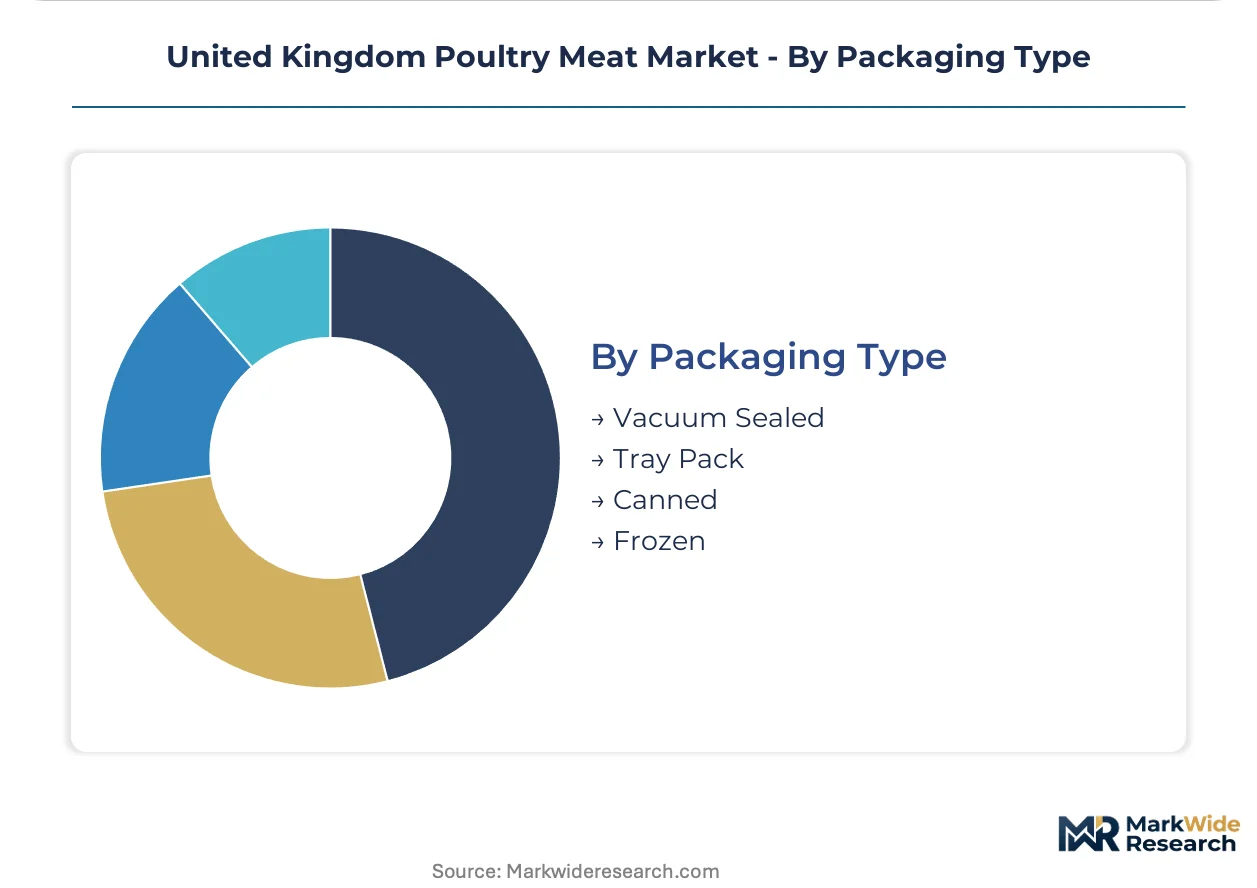
Packaging Type:
Packaging innovation targets shelf-life extension and carbon footprint reduction under emerging Defra environmental reporting standards.
- Vacuum Sealed:Modified atmosphere technology extends retail shelf life while reducing food waste penalties in supermarket supply agreements.
- Tray Pack:Standard format for fresh counter display with overwrap film meeting retailer-specific presentation requirements.
- Canned:Limited application in prepared meal ingredients and emergency food supply channels with stable but declining volume.
- Frozen:Retains significant share in bulk food service procurement and export shipments requiring extended supply chain resilience.
Operational scale favors Frozen. Sustainability-driven conversion is accelerating in Vacuum Sealed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Anglia's veterinary and agricultural workforce concentration anchors UK poultry production capacity, with specialized talent pools supporting both intensive broiler operations and welfare-certified supply chains across England's eastern counties.
East Anglia
East Anglia hosts Britain's densest concentration of broiler housing and slaughter capacity, serving London retail and food service channels through minimized logistics friction. The Animal Welfare (Kept Animals) Bill mandates lower stocking densities than current EU requirements, forcing producers serving dual markets to maintain separate housing specifications. Norfolk and Suffolk processing corridors concentrate automated grading and packaging infrastructure that reduces unit labor costs.
West Midlands
The West Midlands corridor leverages underutilized cold-chain infrastructure for value-added poultry manufacturing expansion. Defra's emerging environmental reporting standards drive investment in verified low-emission feed ration systems across Staffordshire and Shropshire operations. Birmingham's distribution networks connect regional processors to national retail chains through dedicated fleet contracts.
Northern England
Northern England's Yorkshire and Lancashire counties maintain significant turkey and seasonal poultry production capacity. Computer vision grading systems retrofitting existing plants automate carcass quality assessment at line speeds exceeding 135 birds per minute. The region's independent farm cooperatives face shelf space pressure as supermarket buyers consolidate supplier relationships around integrated processors.
Northern Ireland
Northern Ireland operations confront acute regulatory friction under the Windsor Framework, simultaneously satisfying UK domestic retail contracts and EU export certification requirements. Moy Park Ltd leverages integrated supply chain control across the province and Great Britain to sustain cost advantages in volume segments. Dual compliance burdens for stocking density and welfare documentation increase operational complexity for cross-border supply chains.
Scotland
Scotland's poultry sector concentrates in Aberdeenshire and Tayside, with computer vision automation reducing manual inspection headcount in processing plants. The Scottish Government's welfare standards align with but occasionally exceed Defra baseline requirements, creating additional certification tiers for premium retail placement. Edinburgh and Glasgow retail channels drive demand for vacuum-sealed convenience formats with extended shelf stability.
United Kingdom Poultry Meat Market Competitive Landscape
Capital-heavy integrated producers compete with asset-light branded marketers across tiered market positions. Four processors control over 80% of licensed slaughter capacity, creating bottleneck risk during disease-related supply shocks. Strategic archetypes separate into volume-driven integrated chains, premium welfare-certified specialists, and diversified protein conglomerates. Competitive moves concentrate on M&A consolidation of farm-to-shelf traceability capabilities and backward integration into captive feed milling operations.
Within the integrated processor tier, Moy Park Ltd and Cranswick plc occupy distinct positioning vectors. Moy Park exemplifies scale-driven supply chain integration spanning Northern Ireland and Great Britain. Cranswick plc represents premium-tier differentiation through high-welfare and added-value product lines commanding shelf space in major supermarkets. Avara Foods Ltd anchors the mid-market volume segment with processing concentration in England's eastern corridors.
| Leading Market Players |
|---|
| Boparan Holdings Ltd |
| Moy Park Ltd |
| Cranswick plc |
| Avara Foods Ltd |
| Danish Crown AmbA |
| Gressingham Foods |
| 2 Sisters Food Group |
| Karro Food Group |
| PHW Group |
| Others |
Pricing and Supply Chain Analysis
Computer vision automation retrofitted across Northern England and Scottish processing plants compresses unit labor costs while concentrating slaughter capacity among fewer integrated operators capable of capital deployment. This technology shift simultaneously widens margin spreads for scale players and hardens price tiers between welfare-certified premium lines and commodity broiler segments.
Pricing Analysis
Whole-bird and cut-meat pricing separates welfare-tier certification levels from standard intensive production, with Defra code compliance acting as the primary price differentiation driver. Retail buyers extract volume discounts through single-source contracts with integrated processors, while independent farm cooperatives face pricing softness reflecting shelf space consolidation. Food service chains demonstrate highest price sensitivity in frozen bulk procurement, whereas premium retail channels absorb welfare-tier markups with minimal volume elasticity.
Supply Chain Analysis
Dual-sourcing requirements from major supermarket buyers mandate multi-processor qualification, yet four integrated operators control over four-fifths of licensed UK slaughter capacity. Feed compounders draw from South American and Black Sea soybean shipments, exposing margins to currency volatility and trade friction. Single-source vulnerability concentrates in East Anglia processing corridors, where logistics chokepoints threaten supply continuity during disease-related shocks. Distribution runs through dedicated fleet contracts bypassing wholesale intermediaries for food service accounts, while bulk frozen formats retain dominance in institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom poultry meat market functions as a geographic-arbitrage play, with Northern Ireland operations capturing margin advantages from Windsor Framework access to EU export certification alongside UK domestic retail contracts.
For Market Incumbents: To counter lab-grown protein substitution threats, Moy Park Ltd and Cranswick plc should deepen backward integration into captive feed milling operations securing soybean meal supply chains. Capacity addition in the West Midlands corridor leverages underutilized cold-chain infrastructure for value-added manufacturing expansion, while welfare certification investment defends shelf space against retailer consolidation of approved supplier lists. For New Entrants and Emerging Players: Direct-to-restaurant distribution partnerships offer white-space penetration bypassing wholesale layering currently captured by established intermediaries. The West Midlands value-added processing segment presents the most penetrable geography, with carbon labeling alignment enabling premium positioning under emerging Defra environmental reporting standards. A go-to-market angle targeting independent butcher channels with specialty species and welfare-tier differentiation circumvents supermarket supplier list restrictions. For Investors and Strategic Acquirers: Valuations sit cheapest among independent farm cooperatives facing shelf space pressure from retailer consolidation around integrated processors. Long-term viability across the projection horizon hinges on traceability technology ownership and feed ration carbon verification capabilities. The signal to watch is cultivated meat regulatory approval timelines, which would inflect conventional broiler volume growth assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captive soybean meal supply reduces currency exposure and secures Defra carbon labeling compliance. |
| Computer Vision Grading Deployment | Automation at 135+ birds per minute compresses labor costs and standardizes defect detection thresholds. |
| Welfare Certification Tiering Investment | Premium Defra code compliance unlocks shelf space in Tesco and Sainsbury's consolidated supplier lists. |
| West Midlands Cold-Chain Expansion | Underutilized infrastructure supports value-added manufacturing for food service direct fleet contracts. |
| Dual-Market Compliance Architecture | Northern Ireland operations leverage Windsor Framework access to simultaneous UK and EU certification. |
Research Methodology
Bottom-up food service and retail channel modeling reconciled against top-down slaughter capacity and feed input tracking forms the analytical core of this study. Primary interviews with procurement directors at major supermarkets, operations managers at integrated processors, veterinary supervisors at slaughter facilities, and category buyers at quick-service restaurant chains combined with secondary validation from Food Standards Agency hygiene records, Defra agricultural census data, customs trade statistics, and supermarket supplier list disclosures. Triangulation across these sources ensures supply-side installation figures align with demand-side procurement patterns.
Input-output matrices map broiler housing capacity through processing volumes to end-use channel consumption across the projection horizon. Segmentation dimensions modeled include species type, welfare certification tier, packaging format, and regional processing corridor concentration. CAGRs derive from trend extrapolation of feed conversion efficiency gains, automation adoption curves, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate Animal Welfare (Kept Animals) Bill implementation timelines and cultivated meat approval pathway developments.
Revisions become necessary when disease-related supply shocks, abrupt feed commodity price spikes, or regulatory divergence accelerations materialize beyond baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Bee Pollen Market