
 Cage Free Eggs Market | 2026-2036
Cage Free Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Cage Free Eggs Market Analysis
Market Context
The gap between premium pasture-raised supply and conventional commodity egg volumes is expanding as retailers enforce differentiated sourcing tiers. Cal-Maine Foods leverages vertical integration across feed production and distribution to sustain cost discipline at scale. Vital Farms anchors the pasture-raised premium segment through brand strength and channel control in specialty retail. Rose Acre Farms competes via geographic dominance across multiple production regions with standardized barn configurations.
Technical Definition and Segments
Cage-free eggs are laid by hens housed in indoor systems that permit unrestrained access to feed, water, and vertical space without conventional battery confinement, typically yielding shell thickness of 0.30–0.35 mm and Haugh unit scores above 72. Their primary commercial purpose is supplying food manufacturers and retail channels with compliant inventory that satisfies corporate animal welfare pledges and regulatory mandates. Organic product type leads value contribution due to feed certification requirements and price premiums, while liquid formats represent the fastest-growing processing segment driven by industrial bakery and ready-meal demand. Supermarkets dominate distribution channel throughput, though online retailers capture expanding share among subscription-based household buyers seeking direct farm transparency.
Regulatory Frame and Outlook
The USDA oversees voluntary grading standards that influence wholesale pricing and retail labeling credibility, while FDA enforcement of the Egg Safety Rule shapes refrigeration and Salmonella control protocols for cage-free operations. State regulators in California, Massachusetts, and Washington administer confinement statutes that effectively dictate national supply chain restructuring for multi-state distributors. Stakeholders must monitor pending ballot initiatives and legislative sessions across additional states to anticipate capacity investment requirements and avoid stranded conventional assets.
Market Dynamics
State-level confinement statutes are forcing accelerated barn conversions across multi-state supply chains, restructuring capital deployment timelines and procurement compliance requirements for integrated producers and contract growers alike.
Growth Catalysts
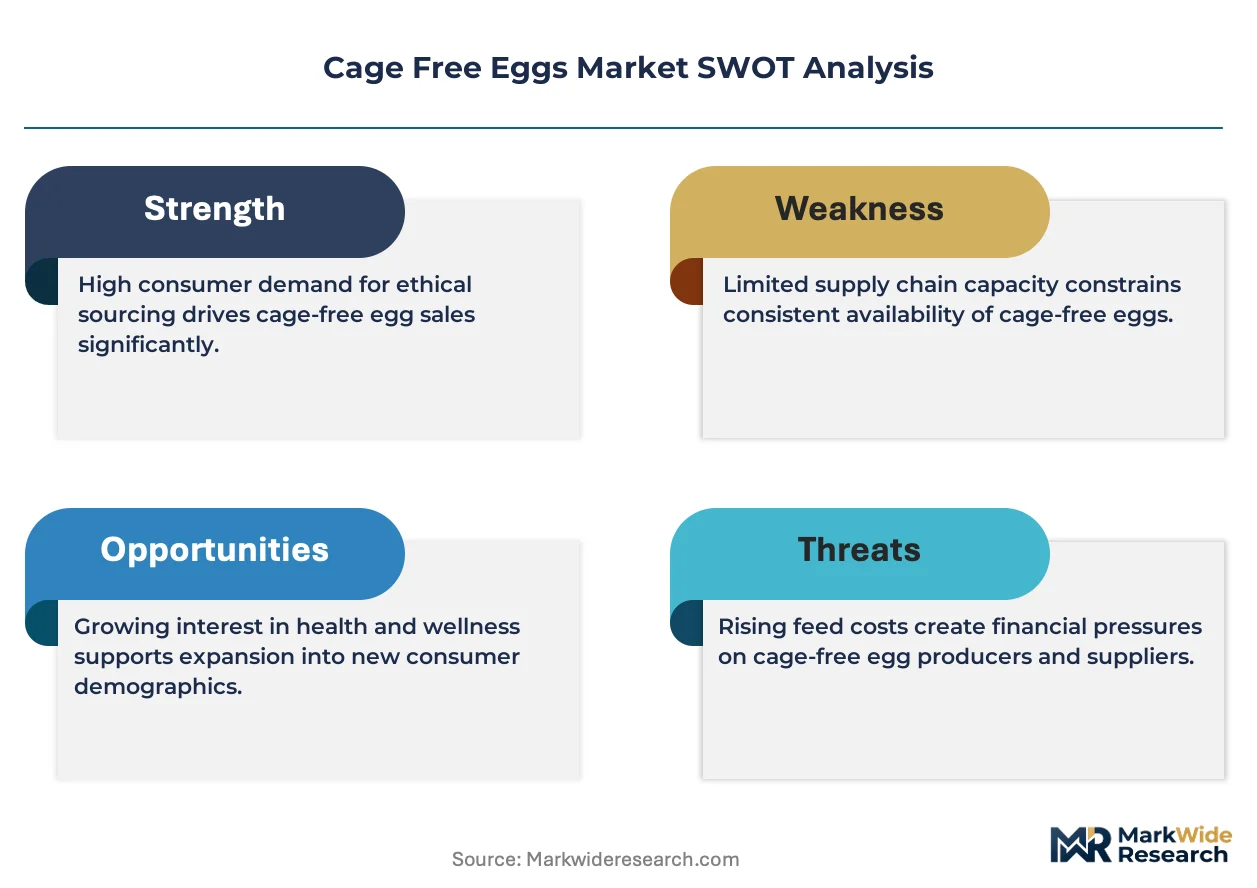
- Proposition 12 Mandates:California's confinement standards are compelling national distributors to reconfigure sourcing networks, creating guaranteed offtake for compliant producers.
- Quick-Service Procurement:Food service chains are enforcing cage-free supply chain pledges, locking in multi-year volume commitments that de-risk producer expansion decisions.
- Germany's Tierhaltungskennzeichnung:The country's animal welfare labeling framework is driving retail shelf-space reallocation toward higher-welfare egg categories.
Market Restraints
- Feed Cost Volatility:Organic soybean and corn price swings compress margin predictability for certified organic cage-free operations.
- Midwest Supply Concentration:Iowa and Indiana house disproportionate conventional capacity, creating logistical friction for coastal distributors seeking compliant supply.
- Conventional Egg Substitution:Price-sensitive institutional buyers retain flexibility to revert to caged supply when premium spreads widen.
Strategic Opportunities
- United Kingdom Retail Premiumization:British supermarkets are expanding dedicated pasture-raised shelf sets, rewarding brand investment with category captaincy.
- Subscription Direct-to-Consumer:Farm-branded monthly egg delivery is bypassing traditional wholesale markup structures.
- Massachusetts Question 3 Expansion:The state's confinement law is creating adjacent demand pull throughout New England distribution corridors.
Industry Challenges
- Avian Health Specialist Scarcity:Cage-free systems demand veterinarians trained in loose-housing pathology, a credential pool concentrated at land-grant universities.
- Multi-Tier Barn Retrofit Complexity:Converting existing facilities to aviary systems requires structural reinforcement and ventilation redesign that extends downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cage Free Eggs Market |
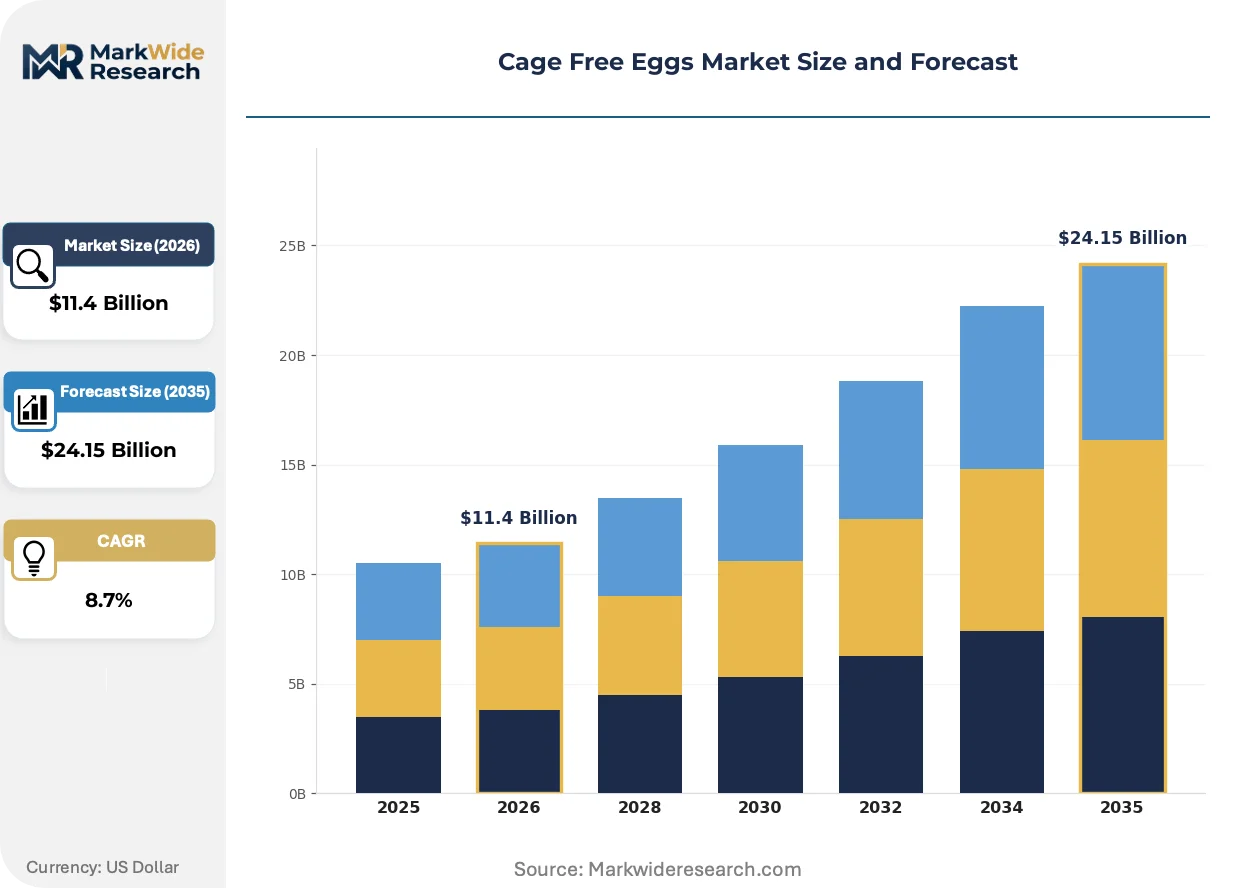
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Processed, Liquid Distribution Channel: Supermarkets, Online Retailers, Farmers Markets, Convenience Stores Packaging Type: Cartons, Trays, Bulk Bags, Retail Packs Consumer Type: Households, Restaurants, Food Services, Bakeries |
| Companies Covered | Cal-Maine Foods, Vital Farms, Rose Acre Farms, Eggland's Best, Rembrandt Enterprises, Herbruck’s Poultry Ranch, Hillandale Farms, Midwest Poultry Services, Stoltzfus Hatchery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cage Free Eggs Market Emerging Trajectories
Automation and data capture are penetrating barn operations, while regulatory layering and consumer transparency demands are reshaping how value is communicated and captured across the supply chain.
Precision feeding systems are unifying individual bird nutrition tracking with flock-level performance optimization. Large integrated producers are deploying these platforms across multi-barn complexes to reduce feed conversion variance. The technology is unifying historically separate grower and processor data streams into shared performance dashboards.
Washington State's confinement statute is extending Proposition 12-style requirements to Pacific Northwest supply chains. Retailers operating across state lines must harmonize procurement standards to the strictest applicable regulation. The policy is forcing distributors to consolidate supplier relationships with operations certified to multiple state standards.
Blockchain-enabled provenance verification is replacing paper-based audit trails for welfare claims. Specialty retail channels are mandating real-time barn access footage as a condition of shelf placement. This transparency expectation is most pronounced in German and British urban markets where direct-farm branding commands price premiums.
Cage Free Eggs Market Segmentation
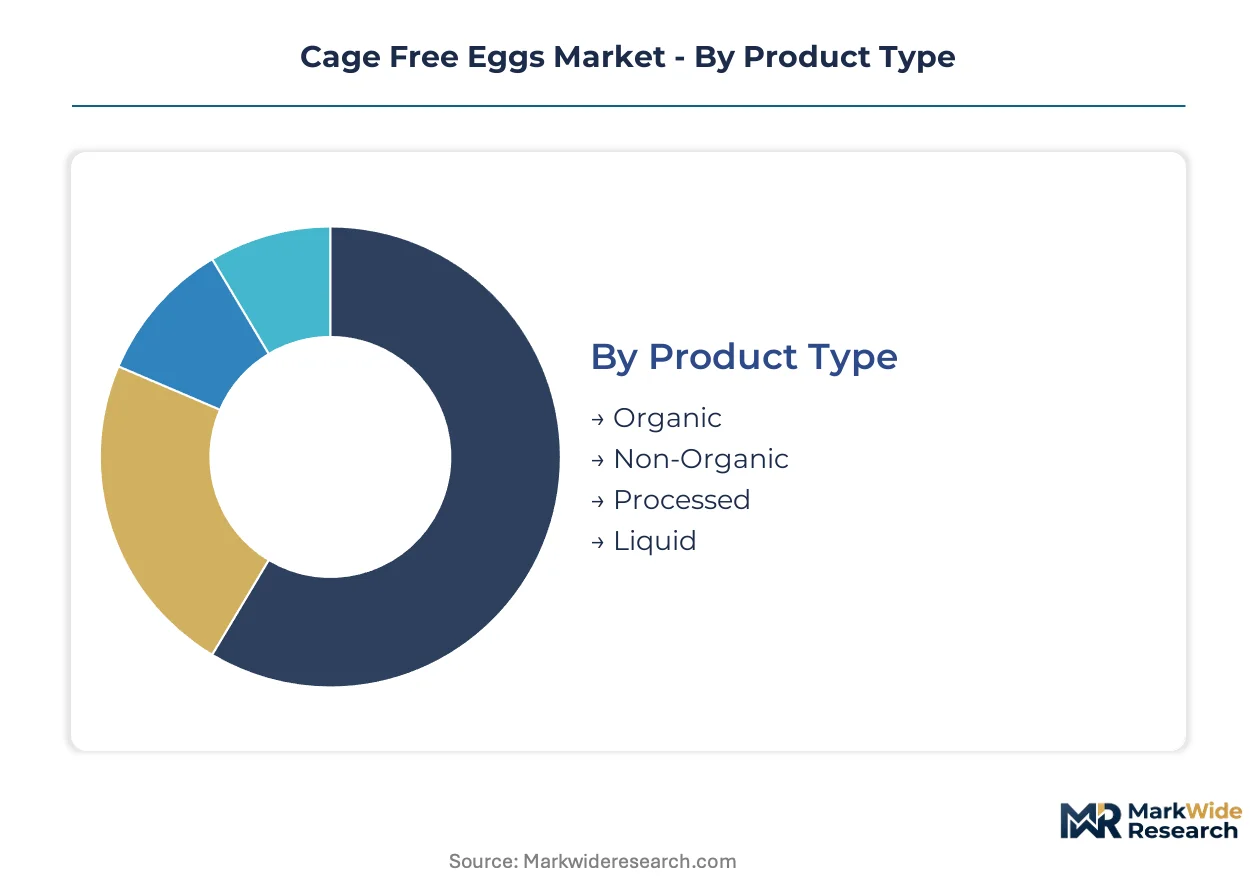
Segmentation in the cage-free eggs market reflects divergent certification standards, channel economics, and end-use specifications that dictate pricing power and procurement compliance. Producers must align barn configurations and processing investments with the precise welfare and format requirements of each buyer category.
Product Type:
Certification grade and feed sourcing protocols define the technical and commercial boundaries between segments, with organic certification imposing the most stringent supply chain controls.
- Organic:Hens receive certified organic feed without synthetic pesticides or GMOs, producing eggs with verified welfare credentials that command shelf price premiums in German and British retail. German supermarkets reallocate shelf space toward this tier under Tierhaltungskennzeichnung labeling requirements.
- Non-Organic:Cage-free housing without organic feed certification offers baseline welfare compliance at accessible price points. Quick-service chains in the United States lock in multi-year volume commitments here to satisfy Proposition 12 mandates without absorbing full organic premiums.
- Processed:Hard-boiled, pickled, or pre-cooked formats target institutional food service with extended shelf stability. Bakeries and ready-meal manufacturers source these for operational efficiency.
- Liquid:Pasteurized whole egg, yolk, or white formats supply industrial bakery and sauce production. This segment is expanding most quickly as manufacturers reformulate for cage-free ingredient compliance.
Mature deployment sits with Non-Organic. Newer deployment is concentrated in Liquid.
Distribution Channel:
Channel selection determines margin capture, with direct and digital formats bypassing traditional wholesale markups that compress producer returns.
- Supermarkets:Dominant throughput channel where category captaincy rewards brand investment with dedicated pasture-raised shelf sets. British retailers are expanding these premium allocations fastest.
- Online Retailers:Subscription-based direct farm delivery is gaining share among households seeking transparency. Real-time barn access footage is becoming a mandatory placement condition in urban German markets.
- Farmers Markets:Hyper-local sourcing with minimal intermediation serves transparency-seeking consumers. Regional producers leverage this channel for price realization above wholesale benchmarks.
- Convenience Stores:Limited SKU counts favor standardized retail packs with extended shelf life. Price-sensitive positioning limits premium tier penetration here.
Volume concentrates in Supermarkets. Margin expansion concentrates in Online Retailers.
Packaging Type:
Packaging configuration aligns with channel requirements and breakage risk tolerance across the supply chain.
- Cartons:Molded pulp or recycled paper containers dominate retail shelf presentation with printable branding surfaces. Consumer familiarity sustains this format's prevalence in household purchase occasions.
- Trays:Plastic or fiber flats optimize logistics for food service and bakery procurement with stackable efficiency. Institutional buyers favor these for volume handling and inventory rotation.
- Bulk Bags:Loose egg containment for industrial processing facilities where immediate shell removal occurs. Liquid egg processors source through this format to minimize packaging waste.
- Retail Packs:Pre-portioned multi-count configurations balance convenience with per-unit pricing transparency. Convenience stores and smaller supermarkets standardize on these counts.
Standardization sits with Cartons. Format innovation concentrates in Retail Packs.
Consumer Type:
End-use specifications vary dramatically across buyer categories, from household transparency demands to industrial formulation requirements.
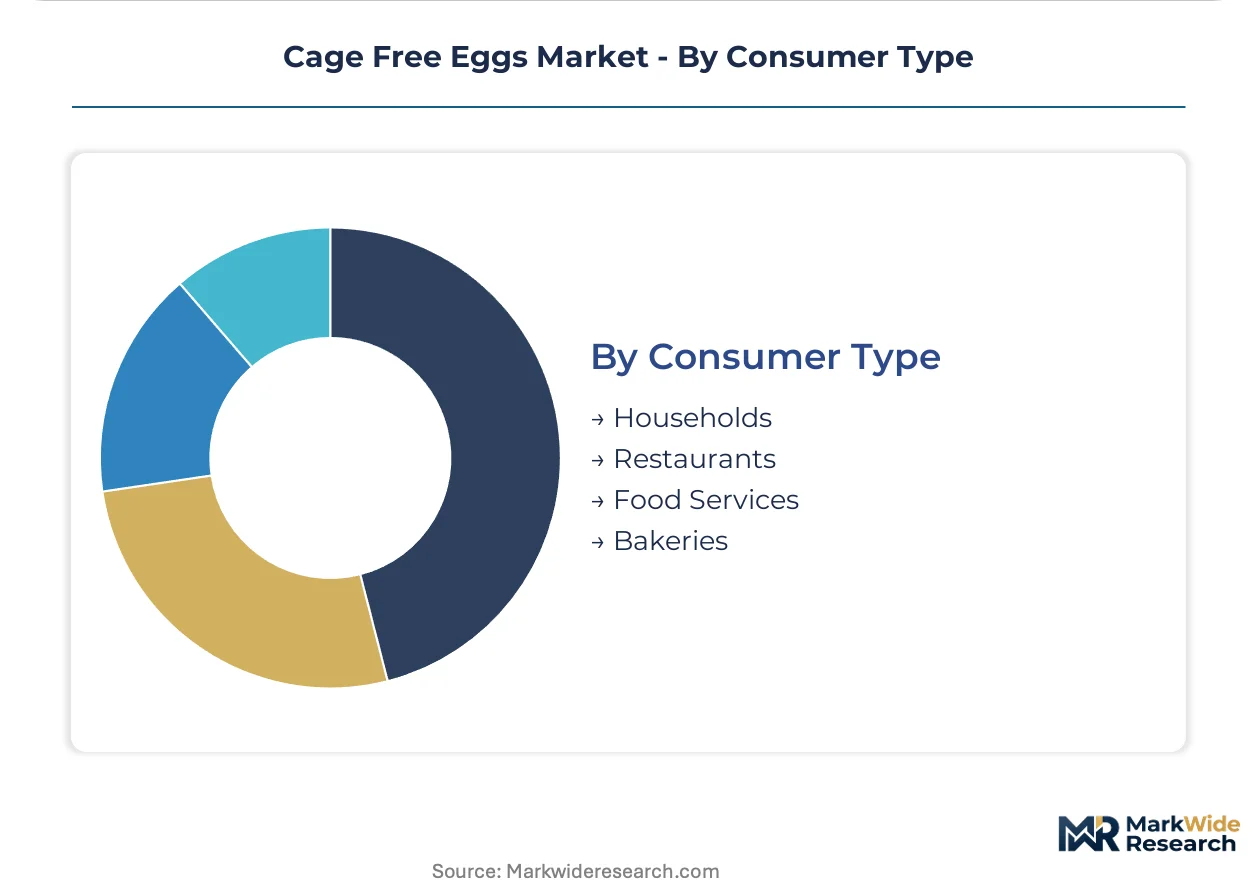
- Households:Individual consumers purchase shell eggs through retail channels with welfare labeling as the primary decision filter. Subscription direct-to-consumer models are bypassing wholesale structures for this segment.
- Restaurants:Full-service operators require consistent shell quality and size grading for plate presentation. Proposition 12 compliance is mandatory for California-serving chains.
- Food Services:Institutional caterers and contract feeders prioritize liquid and processed formats for operational efficiency. Multi-year procurement pledges from major operators de-risk producer expansion decisions.
- Bakeries:Industrial and artisanal bakers demand liquid egg with precise solids content and functional performance. This segment drives the fastest volume growth in liquid format demand.
Procurement scale sits with Food Services. Specification intensity sits with Bakeries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Des Moines anchors North American cage-free production capacity, with processing clusters extending through Iowa's corn belt into Indiana and Ohio distribution corridors.
United States
California's Proposition 12 mandates are restructuring national procurement networks, compelling distributors to source exclusively from compliant operations. The USDA administers voluntary grading standards that influence wholesale pricing credibility across state lines. Iowa and Indiana house the densest conventional-to-cage-free conversion activity, with barn retrofit timelines accelerating through 2025-2026.
Germany
The Tierhaltungskennzeichnung labeling framework is reallocating retail shelf space toward higher-welfare egg categories in Berlin and Hamburg metropolitan markets. EFSA guidelines on animal welfare substantiation shape compliance protocols for imported supply. Bavaria's integrated poultry cooperatives are expanding aviary system investments to capture premium positioning under federal labeling tiers.
United Kingdom
British supermarkets are expanding dedicated pasture-raised shelf sets in London and Southeast England, rewarding brand investment with category captaincy. The Department for Environment, Food and Rural Affairs oversees welfare labeling enforcement that exceeds baseline EU requirements. Midlands-based processors are consolidating supplier relationships to meet multi-retailer compliance standards.
Canada
Ontario's retail chains are adopting cage-free procurement pledges that mirror US state-level mandates, creating demand pull across Great Lakes distribution networks. Health Canada administers food safety protocols that align with FDA Egg Safety Rule refrigeration standards. Quebec's integrated egg cooperatives are investing in multi-tier barn conversions to supply Toronto and Montreal metropolitan markets.
Australia
New South Wales and Victoria supermarkets are expanding free-range and cage-free SKU allocations in Sydney and Melbourne urban centers. The country's national agricultural regulator oversees welfare labeling claims that increasingly influence consumer purchase decisions. Queensland producers are developing barn capacity to supply eastern seaboard retail consolidation.
Cage Free Eggs Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with organic and pasture-raised specialists capturing shelf price premiums while non-organic cage-free operators satisfy volume mandates. The competitive structure consolidates around three strategic archetypes: vertically integrated majors controlling feed-to-retail supply chains, premium brand specialists leveraging channel control in specialty retail, and regional scale players optimizing geographic density across multiple production zones. Dominant competitive moves include barn conversion capacity expansion to meet state compliance deadlines and strategic partnerships locking in multi-year offtake agreements with quick-service chains.
Among US-based integrated producers, Cal-Maine Foods, Vital Farms, and Rose Acre Farms occupy distinct positioning archetypes. Cal-Maine exemplifies scale-driven vertical integration across feed production and distribution infrastructure. Vital Farms anchors the pasture-raised premium segment through brand strength and specialty retail channel control. Rose Acre represents geographic diversification strategy, with standardized barn configurations spread across multiple production regions to service dispersed retail and food service accounts.
| Leading Market Players |
|---|
| Cal-Maine Foods |
| Vital Farms |
| Rose Acre Farms |
| Eggland's Best |
| Rembrandt Enterprises |
| Herbruck's Poultry Ranch |
| Hillandale Farms |
| Midwest Poultry Services |
| Stoltzfus Hatchery |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap producers across Iowa and Indiana anchor conventional capacity, creating fragmented ownership patterns that resist coordinated pricing discipline while California's Proposition 12 forces coastal distributors to absorb premium spreads for compliant supply.
Pricing Analysis
Certification-grade pricing anchors value capture, with organic tiers commanding shelf premiums in German and British retail under Tierhaltungskennzeichnung and Department for Environment, Food and Rural Affairs enforcement. Three-tier pricing structure across organic, non-organic cage-free, and conventional levels stratifies buyer access, with quick-service chains locking contract-based long-term offtake to de-risk volume commitments. Pricing pressure stems from organic soybean and corn feed cost volatility compressing margin predictability. Food service operators demonstrate lowest price sensitivity due to corporate welfare pledge compliance requirements, while convenience store channels remain most exposed to conventional egg substitution.
Supply Chain Analysis
Direct-to-retail supermarket channels handle volume throughput for household and restaurant demand, while liquid egg processors source through bulk bag formats for industrial bakery integration. Production concentrates in the United States, Germany, and the United Kingdom, with Iowa and Indiana housing densest conventional-to-cage-free conversion activity. Feed sourcing draws from organic corn and soybean certification networks, with barn retrofit materials and aviary system components creating secondary dependencies. Single-source vulnerability runs through Midwest supply concentration for coastal distributors. Distribution runs through multi-state procurement networks harmonized to strictest applicable state confinement statutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where California's Proposition 12 creates a barrier-to-entry moat that strands non-compliant conventional assets and rewards early barn conversion investments.
For Market Incumbents: Anticipate feed cost volatility compressing organic tier margins by securing backward integration into certified organic grain sourcing or captive supply agreements with Midwest cooperatives. Reinforce geographic diversification across multiple production regions to reduce single-state regulatory exposure. Channel control through quick-service chain partnerships locks multi-year offtake that de-risks expansion capital deployment against conventional egg substitution threats. For New Entrants and Emerging Players: Subscription direct-to-consumer platforms offer the most penetrable route for farm-branded monthly egg delivery bypassing traditional wholesale markups. Target Massachusetts Question 3 expansion corridors throughout New England where adjacent demand pull outpaces established supply. White-space sits in pasture-raised transparency segments requiring real-time barn access footage as mandatory placement conditions in urban German markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated specialists with feed-to-retail control in Iowa and Indiana conversion zones where conventional asset stranding accelerates. Long-term viability hinges on 5-10 year regulatory layering across additional state ballot initiatives. The signal to watch is pending legislative sessions creating capacity investment requirements that consolidate supplier relationships with multi-state certified operations.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Tier Barn Retrofit Program | Structural reinforcement and ventilation redesign extends downtime but satisfies Proposition 12 compliance deadlines. |
| Organic Feed Supply Agreement | Certified organic corn and soybean sourcing locks margin predictability against commodity price swings. |
| Quick-Service Chain Partnership | Multi-year volume commitments from food service operators de-risk producer expansion decisions. |
| Blockchain Provenance Verification | Real-time barn access footage replaces paper audit trails for welfare claims in German urban retail. |
| Pasture-Raised Brand Extension | Category captaincy in British supermarket dedicated shelf sets captures premium price realization. |
Methodological Framework
Document review covered USDA grading standards, FDA Egg Safety Rule enforcement records, and state-level confinement statute filings, complemented by interviews with integrated producer operations managers, quick-service chain procurement directors, and specialty retail category buyers. Secondary validation drew from agricultural trade association reports, customs records for organic feed imports, and SEC filings for publicly traded egg producers. Bottom-up capacity modeling triangulated against top-down consumption estimates across the analysis window.
Cross-referencing historical barn conversion timelines with producer panel input on capital deployment intentions shaped the analytical framework. Segmentation dimensions modeled included certification grade, product format, distribution channel, and regional regulatory cluster. CAGRs were derived from supply-demand balance projections incorporating state mandate compliance deadlines and quick-service procurement pledge fulfillment curves. Feed cost volatility indices and avian health specialist credential pool constraints provided industry-specific forecast inputs.
The model holds under stable regulatory layering assumptions; deviation in ballot initiative timing or feed commodity spikes would shift capacity investment trajectories. Forecasts reflect documented assumptions regarding state-level mandate adoption rates and corporate welfare pledge enforcement. Periodic stress-testing of base assumptions is recommended given pending legislative sessions across additional states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Tanzania Cashew Market
Agriculture and Agri Products
Global Industrial Hemp Market