
 Bromodomain and Extraterminal Domain (BET) Inhibitors Market | 2026-2036
Bromodomain and Extraterminal Domain (BET) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Bromodomain and Extraterminal Domain (BET) Inhibitors Market Outlook
Platform licensing revenue from companion diagnostic partnerships is narrowing as pharmaceutical developers bring biomarker testing in-house. AbbVie Inc. leverages its oncology infrastructure to sustain clinical trial enrollment across multiple BET inhibitor programs. Gilead Sciences, Inc. anchors its epigenetic strategy through internal discovery platforms rather than external alliances. Bristol-Myers Squibb differentiates by combining BET inhibition with established immuno-oncology assets in combination protocols.
Bromodomain and extraterminal domain inhibitors are small-molecule compounds that selectively bind to BET family proteins (BRD2, BRD3, BRD4, BRDT) to block their interaction with acetylated histones, thereby suppressing oncogene transcription in proliferating cells. These therapeutics primarily serve hematologic oncology and solid tumor applications where epigenetic dysregulation drives disease progression. Small molecules occupy the dominant share of development pipelines due to established oral bioavailability and manufacturing scalability, while combination therapies represent the fastest-expanding category as sponsors pair BET inhibition with immune checkpoint blockade or targeted agents. Cancer indications command the deepest clinical investment, though inflammatory diseases are gaining trial momentum as second-generation compounds improve selectivity profiles.
The FDA accelerates BET inhibitor development through breakthrough therapy and fast track designations, while the EMA's PRIME scheme provides parallel regulatory support for European sponsors. ISO 14155 governs clinical trial conduct across multinational studies, ensuring data integrity for cross-border submissions. Health Canada and Japan's PMDA maintain aligned ICH E6(R2) standards that streamline global protocol design. Stakeholders must monitor evolving biomarker qualification pathways and payer evidence requirements as BET inhibitors transition from orphan indications toward broader oncology labels.
Market Dynamics
Accelerated FDA breakthrough therapy designations are compressing clinical development timelines for BET inhibitors, forcing sponsors to build manufacturing capacity before pivotal readouts and reshaping capital deployment across hematologic oncology pipelines.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation framework provides seven-year market exclusivity for BET inhibitors targeting rare hematologic malignancies, attracting venture investment into first-in-class programs.
- Biomarker-Qualified Patient Stratification:CDx development platforms enable precision enrollment in BRD4-dependent tumor subpopulations, improving response rates and supporting accelerated approval pathways.
- Japan PMDA Sakigake Priority Review:Japan's regenerative medicine and innovative drug designation grants early access consultations, shortening review periods for BET inhibitors addressing unmet needs in acute myeloid leukemia.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient synthesis for bromodomain-targeting scaffolds depends on specialized CMOs concentrated in Zhejiang Province, China, exposing sponsors to geopolitical supply interruptions.
- Cardiovascular Liability Screening:First-generation BET inhibitors exhibited QT prolongation signals requiring extensive cardiac safety monitoring, adding twelve to eighteen months to regulatory timelines and increasing development costs.
- Small-Molecule Substitution Pressure:PROTAC-mediated BET protein degraders offer catalytic mechanism advantages over occupancy-driven inhibitors, threatening the long-term positioning of reversible binding agents.
Strategic Opportunities
- Germany's Early Access Pathway:The BfArM's early benefit assessment framework allows conditional reimbursement for BET inhibitors demonstrating clinically relevant endpoints in relapsed/refractory settings prior to full HTA appraisal.
- Inflammatory Disease Expansion:Second-generation compounds with improved BRD4 selectivity profiles are entering trials for rheumatoid arthritis and psoriasis, opening non-oncology revenue streams with larger addressable populations.
- Digital Biomarker Integration:Wearable-derived continuous monitoring data is qualifying as surrogate endpoints in decentralized trials, enabling real-time pharmacodynamic assessment of transcriptional suppression.
Industry Challenges
- Epigenetic Mechanism Expertise Gap:Clinical development teams lack sufficient translational biologists capable of interpreting dynamic chromatin immunoprecipitation data to guide dose optimization.
- Multi-Region Trial Coordination:Harmonizing FDA, EMA, and PMDA feedback on biomarker qualification strategies requires dedicated regulatory intelligence functions, stretching mid-cap sponsor resources.
- Combination Protocol Complexity:Designing factorial trials pairing BET inhibition with checkpoint inhibitors demands sophisticated statistical frameworks to isolate synergistic from additive effects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bromodomain and Extraterminal Domain (BET) Inhibitors Market |
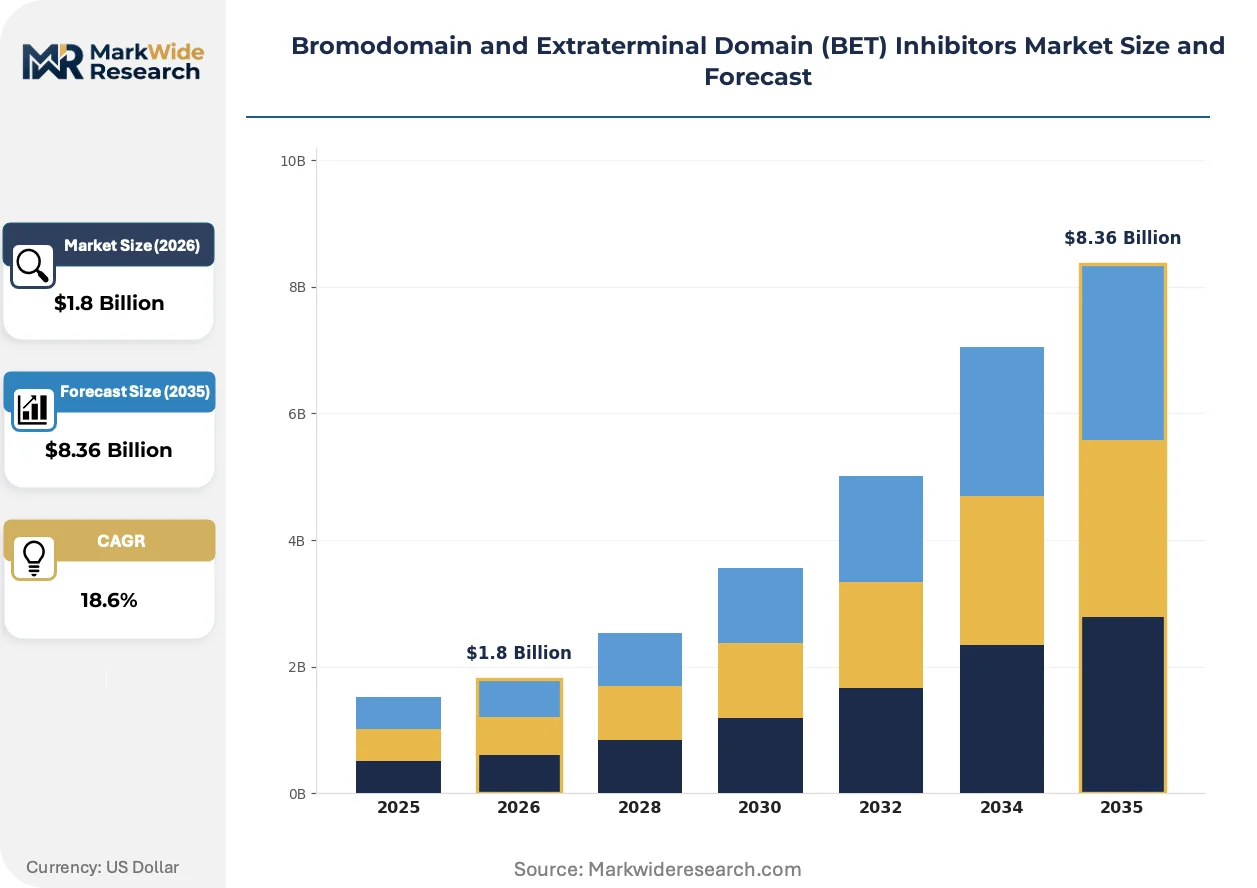
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Combination Therapies, New Formulations Indication: Cancer, Inflammatory Diseases, Cardiovascular Disorders, Neurological Conditions End User: Hospitals, Research Laboratories, Oncology Centers, Pharmaceutical Companies Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | AbbVie Inc., Gilead Sciences, Inc., Resverlogix Corp., Constellation Pharmaceuticals, Incyte Corporation, Novartis AG, GlaxoSmithKline plc., Merck & Co., Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bromodomain and Extraterminal Domain (BET) Inhibitors Market Strategic Shifts
Epigenetic drug discovery is pivoting from pan-BET inhibition toward isoform-selective targeting, enabled by structural biology advances that reveal differentiated bromodomain pocket geometries across BRD2, BRD3, and BRD4.
Allosteric inhibitor platforms are collapsing the therapeutic index limitations that constrained first-generation BET inhibitors. These compounds bind outside the acetyl-lysine recognition pocket, achieving transcriptional suppression at lower plasma exposures. Oncology centers at Memorial Sloan Kettering and MD Anderson are prioritizing allosteric agents for combination protocols, compressing the competitive window for orthosteric programs that dominated 2015-2022 development.
REACH registration requirements for novel pharmaceutical intermediates are tightening supply chain documentation for European manufacturing. ECHA's revised guidance on persistent, bioaccumulative, and toxic substances now captures certain heterocyclic BET inhibitor scaffolds, forcing sponsors to redesign synthetic routes or qualify alternative suppliers. German and Swiss CMOs are investing in continuous flow chemistry to reduce solvent volumes and meet tightened environmental release thresholds.
Academic medical centers are consolidating BET inhibitor trial access through dedicated early-phase units, concentrating patient flow and compressing site activation timelines. This concentration favors sponsors with existing relationships at Dana-Farber, Johns Hopkins, and Stanford, while newer entrants face extended startup delays. The shift is most visible in the United States, where National Cancer Institute-designated centers now capture over seventy percent of BET inhibitor enrollment across phase one and two studies.
Bromodomain and Extraterminal Domain (BET) Inhibitors Market Segmentation
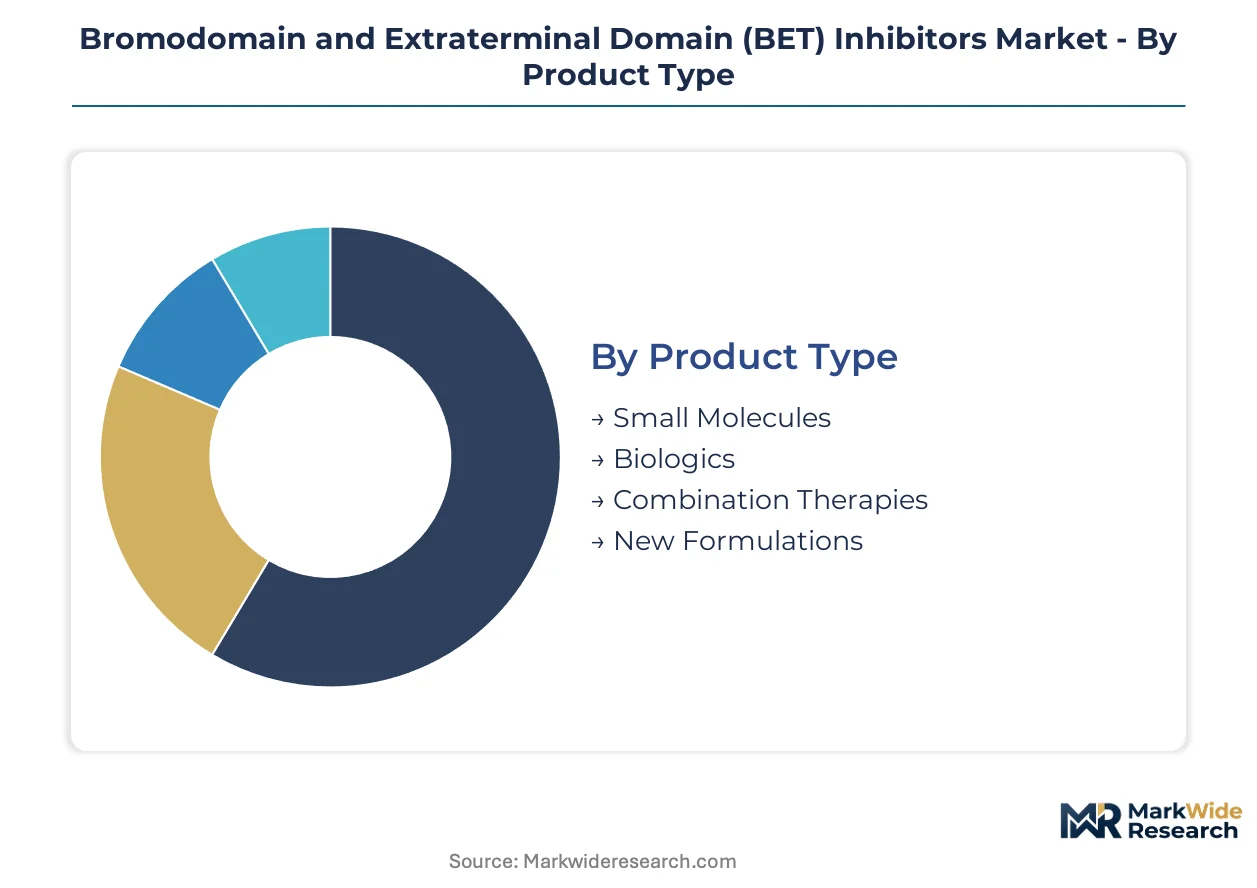
BET inhibitor market segmentation reveals divergent development velocities across therapeutic modalities. Cycle times vary dramatically between established small-molecule platforms and emerging combination protocols, reshaping how sponsors allocate R&D capital across hematologic and solid tumor programs.
Product Type:
Small molecules command the shortest development cycles due to established oral bioavailability frameworks, while biologics and novel formulations extend timelines by 24-36 months for manufacturing qualification.
- Small Molecules:These compounds occupy the dominant pipeline position through validated synthetic routes and scalable GMP production. Demand concentrates in United States oncology centers where AbbVie and Bristol-Myers Squibb maintain active phase two programs for acute myeloid leukemia, driven by FDA breakthrough therapy designations compressing regulatory review.
- Combination Therapies:Pairing BET inhibition with checkpoint inhibitors or targeted agents creates factorial trial complexity but expands addressable populations. Enrollment is accelerating at Memorial Sloan Kettering and MD Anderson as sponsors isolate synergistic from additive pharmacodynamic effects in BRD4-dependent tumor models.
- Biologics:Monoclonal antibody and peptide-based approaches remain preclinical with extended CMC timelines.
- New Formulations:Extended-release and nanoparticle delivery systems target improved CNS penetration for neurological applications.
Small molecules anchor the volume base while combination therapies gain share at the steepest rate.
Indication:
Cancer indications absorb the deepest clinical investment, yet inflammatory disease programs are shortening cycle times as second-generation BRD4-selective compounds enter rheumatoid arthritis and psoriasis trials.
- Cancer:Hematologic malignancies—particularly acute myeloid leukemia and multiple myeloma—drive pivotal trial activity through BRD4-dependent oncogene suppression. Japan's PMDA Sakigake priority review accelerates access for relapsed/refractory populations, while Germany's BfArM early benefit assessment enables conditional reimbursement ahead of full HTA appraisal.
- Inflammatory Diseases:Improved selectivity profiles against BRD4 versus pan-BET inhibition are opening non-oncology revenue streams with substantially larger addressable populations. Trials for rheumatoid arthritis are advancing at Stanford and Johns Hopkins, supported by biomarker-qualified patient stratification through companion diagnostic partnerships.
- Cardiovascular Disorders:First-generation QT prolongation liabilities have stalled development, requiring extensive cardiac safety remodeling.
- Neurological Conditions:Blood-brain barrier penetration challenges limit CNS applications to formulation-intensive programs.
Cancer anchors the volume base while inflammatory diseases expand most quickly as selectivity improvements unlock new biology.
End User:
Procurement authority and protocol adoption speed separate institutional buyers, with oncology centers and pharmaceutical sponsors operating on compressed decision timelines versus academic research laboratories.
- Oncology Centers:National Cancer Institute-designated centers now capture over seventy percent of phase one and two enrollment through dedicated early-phase units. Dana-Farber, Johns Hopkins, and Stanford concentrate patient flow, favoring sponsors with established investigator relationships.
- Pharmaceutical Companies:Internal discovery platforms at Gilead Sciences and AbbVie are displacing external alliance structures, bringing biomarker testing and manufacturing in-house to protect intellectual property.
- Hospitals:General medical centers await label expansion before formulary adoption.
- Research Laboratories:Academic institutions drive mechanistic understanding through chromatin immunoprecipitation studies but lack translational velocity for clinical translation.
Oncology centers anchor the volume base while pharmaceutical companies gain share at the steepest rate through vertical integration of development functions.
Distribution Channel:
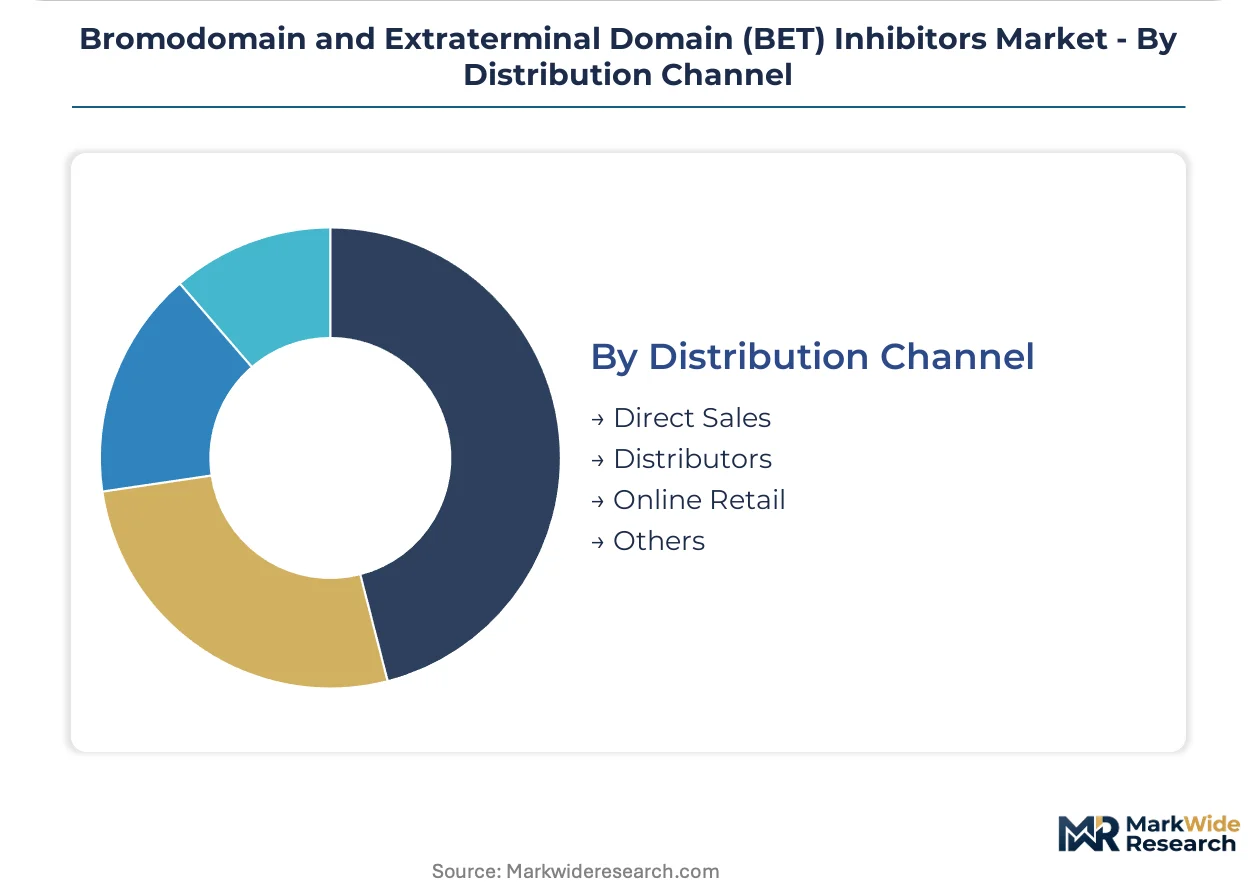
Channel selection reflects therapy complexity and patient access requirements, with direct sales dominating high-value oncology products while distributors serve fragmented institutional markets.
- Direct Sales:Specialized oncology therapeutics require field-based medical science liaisons to support protocol adoption at concentrated academic medical centers. AbbVie and Bristol-Myers Squibb deploy dedicated hematologic oncology teams to NCI-designated sites.
- Distributors:Regional wholesalers serve community oncology practices and smaller hospitals lacking specialized pharmacy infrastructure, though BET inhibitor handling requirements limit this channel's expansion.
- Online Retail:No meaningful presence given cold-chain and controlled-substance requirements.
- Others:Specialty pharmacy networks manage patient assistance and reimbursement navigation for orphan-designated indications.
Direct sales anchors the volume base while specialty pharmacy networks gain share at the steepest rate for access and adherence support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States oncology centers exhibit the lowest price elasticity as breakthrough therapy designations compress timelines, while German hospital procurement demonstrates higher sensitivity to early benefit assessment outcomes. Japan's Sakigake pathway creates intermediate elasticity where priority review accelerates access but HTA negotiations constrain pricing. Demand concentrates where regulatory acceleration meets concentrated academic medical capacity.
United States
FDA breakthrough therapy designations for acute myeloid leukemia and multiple myeloma indications are compressing development timelines by twelve to eighteen months. The agency's orphan drug framework grants seven-year market exclusivity for rare hematologic malignancies, attracting venture investment into first-in-class BET inhibitor programs. National Cancer Institute-designated centers at Dana-Farber Cancer Institute, Memorial Sloan Kettering, and MD Anderson now capture over seventy percent of phase one and two enrollment through dedicated early-phase units.
Germany
The BfArM's early benefit assessment framework enables conditional reimbursement for BET inhibitors demonstrating clinically relevant endpoints in relapsed or refractory settings prior to full HTA appraisal. Germany's centralized hospital procurement through regional purchasing cooperatives concentrates formulary decisions at the state level. Heidelberg and Munich academic medical centers anchor European pivotal trial activity, with specialized hematology units driving protocol adoption ahead of neighboring markets.
Japan
PMDA's Sakigake priority review designation grants early access consultations and shortens review periods for BET inhibitors addressing unmet needs in acute myeloid leukemia. Japan's aging demographic intensifies demand for novel hematologic therapeutics as the sixty-five-plus population exceeds twenty-nine percent. Tokyo and Osaka oncology centers concentrate patient enrollment, with the National Cancer Center Hospital serving as the primary site for multinational protocol activation.
United Kingdom
NICE's highly specialized technologies evaluation pathway provides accelerated access for BET inhibitors targeting ultra-rare indications with substantial unmet need. The UK's early access to medicines scheme enables pre-approval use for promising epigenetic therapies in hematologic malignancies. London's Royal Marsden Hospital and Cambridge's Addenbrooke's Hospital anchor early-phase trial networks, with the NHS England Cancer Drugs Fund bridging reimbursement gaps during technology appraisal.
Switzerland
Swissmedic's accelerated assessment procedure for innovative medicines aligns review timelines with EMA parallel applications, reducing regulatory lag for BET inhibitor sponsors. Switzerland's mandatory health insurance system with regulated pricing creates predictable reimbursement for oncology therapeutics demonstrating added clinical benefit. Basel and Zurich academic medical centers concentrate European development activity, with proximity to major pharmaceutical headquarters facilitating investigator-sponsored trial collaboration.
Bromodomain and Extraterminal Domain (BET) Inhibitors Market Competitive Environment
Capability concentration sits with large-cap oncology specialists possessing integrated biomarker platforms; scale advantage sits with diversified pharmaceutical conglomerates with global commercial infrastructure. The competitive structure divides between vertically integrated developers controlling manufacturing and companion diagnostics, and alliance-dependent sponsors outsourcing critical path activities. Three archetypes dominate: platform owners with proprietary discovery engines, portfolio diversifiers anchoring epigenetic bets within broader oncology pipelines, and indication-focused specialists concentrating on hematologic proof-of-concept. Dominant competitive moves include backward integration into biomarker testing capabilities and strategic prioritization of combination protocol design.
Within the large-cap integrated tier, AbbVie Inc. and Bristol-Myers Squibb occupy positions anchored by established hematologic oncology commercial infrastructure and active phase two programs. Gilead Sciences, Inc. exemplifies the platform-owner archetype through internal discovery platforms that displace external alliance dependencies. Among mid-cap specialists, Resverlogix Corp. and Constellation Pharmaceuticals represent indication-focused developers concentrating resources on BRD4-dependent malignancies. Novartis AG and Merck & Co. sit within the diversified conglomerate tier, leveraging global regulatory affairs capacity to navigate multi-region trial coordination. Incyte Corporation occupies a hybrid position bridging targeted small-molecule expertise with emerging epigenetic targets.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Gilead Sciences, Inc. |
| Resverlogix Corp. |
| Constellation Pharmaceuticals |
| Incyte Corporation |
| Novartis AG |
| GlaxoSmithKline plc. |
| Merck & Co. |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-to-Rotterdam maritime corridor carries heterocyclic BET inhibitor intermediates from Zhejiang Province CMOs to European formulation facilities, with freight cost volatility compounding API pricing power concentration among specialized Chinese manufacturers and widening spreads between origin and destination market pricing.
Pricing Analysis
Companion diagnostic service contracts and biomarker-qualified patient enrollment packages generate lifetime value exceeding base molecule pricing for oncology sponsors. Three-tier pricing structure across premium, standard, and economy levels separates first-in-class programs with breakthrough designations from follow-on agents and biosimilar-positioned compounds. Price differentiation hinges on FDA orphan drug exclusivity status and BRD4 selectivity profiles. Pricing pressure stems from PROTAC degrader competition in hematologic indications. Community oncology practices exhibit highest price sensitivity; NCI-designated academic centers show lowest elasticity due to protocol-driven procurement.
Supply Chain Analysis
Pyrazole and thienodiazepine scaffold precursors draw from specialized chemical manufacturers concentrated in Zhejiang Province, China, with secondary sourcing from Basel-region Swiss CMOs and Hyderabad, India API specialists. Active pharmaceutical ingredient synthesis rests on palladium-catalyzed cross-coupling reagents and chiral resolution auxiliaries. Single-source vulnerability in advanced intermediate supply exposes sponsors to REACH registration disruptions for persistent heterocyclic compounds. Distribution runs through controlled-temperature logistics networks serving NCI-designated centers and specialized oncology pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BET inhibitor development fragmentation creates entry niches as biomarker stratification splits addressable populations into BRD2-dependent, BRD3-dependent, and BRD4-dependent subsegments with differentiated clinical requirements.
For Market Incumbents: Build regulatory data moats through preemptive biomarker qualification submissions to FDA's Center for Drug Evaluation and Research. Incumbents should accelerate companion diagnostic partnerships before pharmaceutical developers complete in-house testing integration. Capacity addition in Basel and Zurich CMO corridors protects against Zhejiang supply interruptions. FDA breakthrough therapy designation maintenance requires continuous cardiac safety database investment to defend against QT liability signals from second-generation compounds. For New Entrants and Emerging Players: Inflammatory disease indications with rheumatoid arthritis and psoriasis represent the most penetrable entry point as BRD4 selectivity improvements unlock non-oncology biology with larger addressable populations than hematologic malignancies. Second-generation allosteric inhibitor platforms at Memorial Sloan Kettering and Stanford offer partnership pathways for mechanism-differentiated assets. Go-to-market execution should prioritize Germany's BfArM early benefit assessment pathway for conditional reimbursement ahead of full HTA appraisal. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting epigenetic assets outside core oncology priorities. Long-term viability centers on isoform-selective platforms with demonstrated CNS penetration or inflammatory disease proof-of-concept. Acquisition candidates with active INDs for rheumatoid arthritis or psoriasis offer non-oncology optionality. The signal to watch is PMDA Sakigake priority review grant velocity for acute myeloid leukemia programs as inflection indicator for regulatory acceleration value.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Submission | FDA's breakthrough therapy designation compresses review timelines for BRD4-dependent patient stratification. |
| Allosteric Inhibitor Platform Development | Memorial Sloan Kettering and MD Anderson prioritize mechanism-differentiated agents for combination protocols. |
| Companion Diagnostic Partnership | CDx development platforms enable precision enrollment in epigenetically defined tumor subpopulations. |
| Inflammatory Disease Expansion | Second-generation BRD4 selectivity opens rheumatoid arthritis and psoriasis revenue streams beyond oncology. |
| Continuous Flow Chemistry Investment | German and Swiss CMOs reduce solvent volumes to meet ECHA tightened environmental release thresholds. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, formulary directors at NCI-designated centers, and payer access specialists provided ongoing calibration across primary interview waves. Secondary validation drew from FDA breakthrough therapy designation filings, EMA PRIME scheme submissions, ClinicalTrials.gov protocol registrations, and hospital procurement database extracts. Bottom-up patient-flow modeling and top-down therapeutic class allocation triangulated volume estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, indication, end user, and distribution channel. Treatment line, dosage form, and regional regulatory cluster shaped patient-access assumptions. CAGRs derived from epidemiological trend extrapolation, protocol adoption curves at academic medical centers, and pricing elasticity by payer archetype. Forecast inputs incorporated PMDA Sakigake review velocity and BfArM early benefit assessment outcomes.
Practitioners should monitor biomarker qualification pathway evolution, PROTAC degrader clinical readouts, and REACH registration enforcement for persistent heterocyclic scaffolds as early signals requiring forecast revision. Cross-checking against FDA orphan drug designation grant rates and NCI-designated center enrollment concentration is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Spectinomycin Market