
 Global Bruton Tyrosine Kinase (BTK) Inhibitors Market | 2026-2036
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market Foresight
Combination therapy packs bundling BTK inhibitors with anti-CD20 antibodies or BCL-2 antagonists is rebalancing how hematology-oncology clinics procure and administer treatment. BeiGene leverages its global clinical trial infrastructure to compete across both covalent and non-covalent inhibitor classes. AbbVie anchors its position through sustained investment in combination regimen development, while AstraZeneca differentiates via broad oncology portfolio integration.
Bruton Tyrosine Kinase inhibitors are small-molecule pharmaceuticals that selectively bind the BTK enzyme in the B-cell receptor signaling cascade, with covalent variants forming irreversible cysteine bonds at Cys481 and non-covalent variants enabling reversible allosteric inhibition. Their primary purpose is to disrupt malignant B-cell proliferation and survival in hematologic cancers and autoimmune conditions. Irreversible inhibitors occupy the largest revenue pool due to entrenched clinical validation in chronic lymphocytic leukemia, though non-covalent inhibitors represent the fastest-expanding segment as resistance mutations drive demand for C481S-sparing alternatives. Oral tablets dominate delivery mode selection, while cancer treatment centers capture the deepest patient volume concentration among end-user channels.
FDA breakthrough therapy designation and EMA PRIME eligibility compress regulatory review timelines for novel BTK inhibitors, directly shaping manufacturer R&D prioritization and payer negotiation leverage. China's NMPA oncology innovation pathways and Japan's PMDA sakigake designation add further complexity to multi-regional launch sequencing. Stakeholders must monitor evolving resistance mutation epidemiology and corresponding shifts in NCCN, ESMO, and CSCO guideline positioning to anticipate which product configuration—covalent, non-covalent, or combination—will command preferential reimbursement and clinical adoption in the next therapeutic cycle.
Market Dynamics
Resistance mutation epidemiology, particularly C481S substitutions in chronic lymphocytic leukemia patients, is fragmenting prescriber loyalty toward first-generation covalent inhibitors and forcing rapid portfolio diversification across oncology manufacturers.
Growth Catalysts
- FDA Breakthrough Therapy designation:Compressed review timelines for novel BTK inhibitors accelerate patient access and reshape manufacturer R&D prioritization toward hematologic malignancies.
- Combination therapy protocols:Bundling BTK inhibitors with anti-CD20 antibodies or BCL-2 antagonists in United States oncology centers expands addressable patient populations beyond monotherapy constraints.
- Medicare reimbursement alignment:NCCN guideline incorporation drives first-line adoption of next-generation inhibitors across United States hematology-oncology clinics.
Market Restraints
- Active pharmaceutical ingredient concentration:Specialized kinase inhibitor synthesis capabilities cluster among contract manufacturers in China and India, creating supply vulnerability for Western sponsors.
- Cardiovascular toxicity profiling:Atrial fibrillation and hypertension monitoring requirements impose substantial post-market surveillance burdens on treatment centers.
- Biosimilar development timelines:Complex small-molecule patent thickets around Cys481-binding scaffolds delay generic entry and sustain originator pricing power.
Strategic Opportunities
- Autoimmune expansion:Multiple sclerosis and rheumatoid arthritis applications represent underpenetrated indications beyond oncology for reversible non-covalent inhibitors.
- Japan PMDA sakigake designation:Priority review vouchers for breakthrough oncology therapies enable accelerated commercialization timelines in the Asia-Pacific's second-largest pharmaceutical market.
- Real-world evidence platforms:Integration of electronic health record networks with pharmaceutical sponsors creates novel post-approval differentiation channels for safety profiling.
Industry Challenges
- Resistance surveillance infrastructure:Molecular diagnostic testing capacity lags behind mutation emergence rates in community oncology practices across Germany and Japan.
- Combination trial complexity:Multi-arm studies involving BTK inhibitors, venetoclax, and obinutuzumab strain investigator bandwidth and site activation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bruton Tyrosine Kinase (BTK) Inhibitors Market |
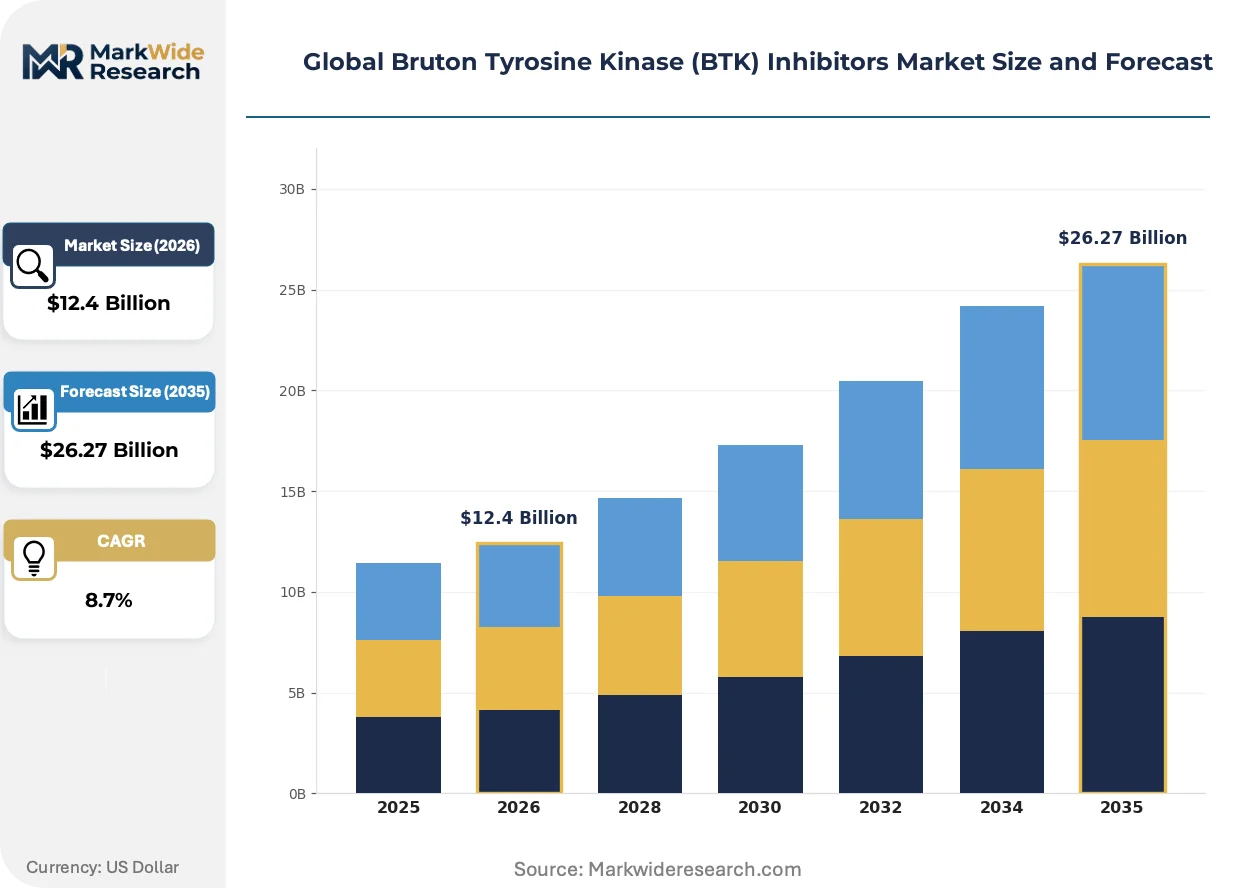
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Irreversible Inhibitors, Reversible Inhibitors, Covalent Inhibitors, Non-Covalent Inhibitors Application: Chronic Lymphocytic Leukemia, Mantle Cell Lymphoma, Waldenström's Macroglobulinemia, Rheumatoid Arthritis End User: Specialty Clinics, Research Laboratories, Cancer Treatment Centers, Biotechnology Firms Delivery Mode: Oral Tablets, Injectable Formulations, Extended-Release Capsules, Combination Therapy Packs |
| Companies Covered | BeiGene, F. Hoffmann-La Roche Ltd, Johnson & Johnson, InnoCare Pharma, Novartis, AbbVie, Eli Lilly and Company, Sanofi, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market Shifts & Advancements
Next-generation inhibitor architectures are compressing development cycles and reconfiguring how hematology clinics sequence therapy lines across resistant patient populations.
Non-covalent allosteric BTK inhibitors are modularizing prescriber decision frameworks by enabling C481S-mutant patient treatment without cross-resistance to prior covalent exposure. Academic medical centers in the United States and Germany are adopting these agents as second-line standards. This architecture is modularizing how manufacturers structure pivotal trial designs and companion diagnostic requirements.
EMA PRIME eligibility and FDA breakthrough pathway convergence are compressing regulatory review timelines for novel hematologic therapies. Sponsors now prioritize simultaneous EMA and FDA submission strategies to capture accelerated access incentives. Oncology manufacturers with existing CLL portfolios benefit most from this harmonization, while new entrants face steeper evidence generation thresholds.
Hematology-oncology clinics are unbundling infusion services from oral therapy management, creating distinct procurement streams for BTK inhibitor tablets versus monoclonal antibody administration. United States cancer centers are consolidating oral oncology dispensing under specialty pharmacy partnerships. This reconfiguration is most visible in Medicare Advantage networks where risk-bearing entities optimize site-of-care economics.
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market Segmentation
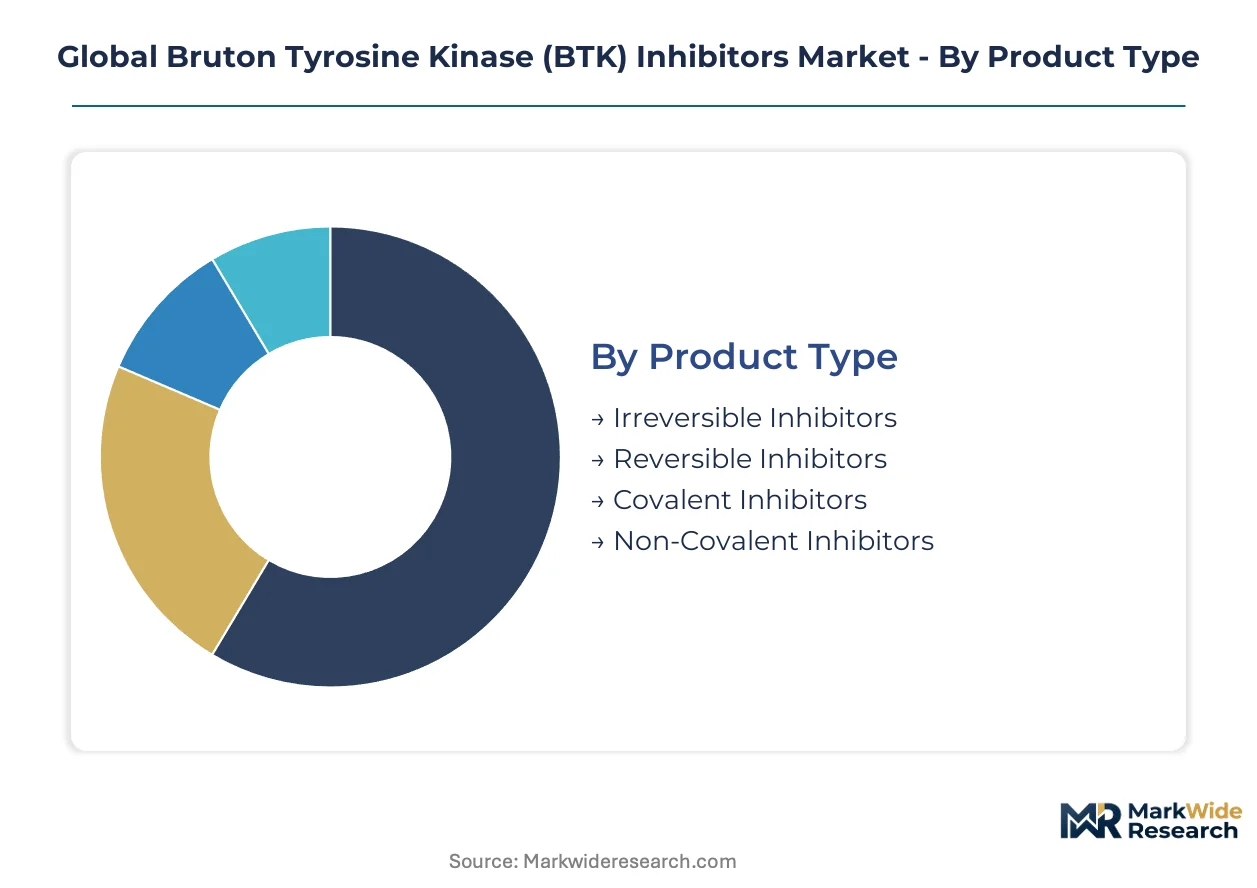
BTK inhibitor procurement patterns diverge sharply across product architectures, therapeutic settings, and administration formats. Manufacturers must align formulation development with site-of-care economics and resistance mutation surveillance infrastructure.
Product Type:
Specialized kinase inhibitor synthesis capabilities concentrate among contract manufacturers in China and India, creating geographic supply dependencies for Western sponsors.
- Irreversible Inhibitors:These small molecules form permanent cysteine bonds at the Cys481 binding site. United States hematology-oncology clinics in Medicare Advantage networks drive demand for these entrenched first-line standards in chronic lymphocytic leukemia.
- Reversible Inhibitors:Allosteric binding enables dissociation from the BTK enzyme, preserving activity against C481S mutations. Academic medical centers in Germany and Japan are adopting these agents fastest as resistance surveillance expands.
- Covalent Inhibitors:Electrophilic warheads create durable enzyme occupancy. FDA breakthrough therapy designations have accelerated approval timelines for this established scaffold class.
- Non-Covalent Inhibitors:Competitive ATP-site binding without covalent attachment. EMA PRIME eligibility is compressing review timelines for these next-generation architectures.
Irreversible inhibitors absorb the bulk of installed capacity; non-covalent inhibitors are expanding most quickly.
Application:
Prescriber decision frameworks stratify sharply between hematologic malignancies and autoimmune indications, with reimbursement pathways determining commercial prioritization.
- Chronic Lymphocytic Leukemia:The dominant indication by patient volume, with NCCN guideline incorporation driving Medicare reimbursement alignment across United States oncology centers.
- Mantle Cell Lymphoma:Aggressive B-cell neoplasm with defined BTK dependency. Japan's PMDA sakigake designation has accelerated commercialization timelines for therapies targeting this indication.
- Waldenström's Macroglobulinemia:Rare lymphoplasmacytic disorder with MYD88 mutation prevalence. ESMO guidelines influence adoption patterns in European hematology clinics.
- Rheumatoid Arthritis:Autoimmune expansion opportunity beyond oncology. Rheumatology practices in Germany represent early adopters for non-covalent inhibitors in this setting.
Chronic lymphocytic leukemia commands the deepest prescriber familiarity; rheumatoid arthritis presents the steepest expansion trajectory.
End User:
Procurement authority is fragmenting between institutional purchasers and specialty pharmacy intermediaries as oral oncology dispensing consolidates.
- Specialty Clinics:Community-based hematology practices with direct patient management. These sites prioritize oral tablet convenience and resistance monitoring protocols.
- Research Laboratories:Academic and commercial entities conducting biomarker discovery. Molecular diagnostic testing capacity lags behind mutation emergence rates in these settings.
- Cancer Treatment Centers:High-volume institutions with integrated pharmacy services. United States cancer centers are unbundling infusion services from oral therapy management.
- Biotechnology Firms:Drug developers sourcing reference compounds and active pharmaceutical ingredients. These buyers concentrate demand for specialized kinase inhibitor synthesis capabilities.
Cancer treatment centers capture the largest patient volume concentration; specialty clinics are gaining procurement autonomy fastest.
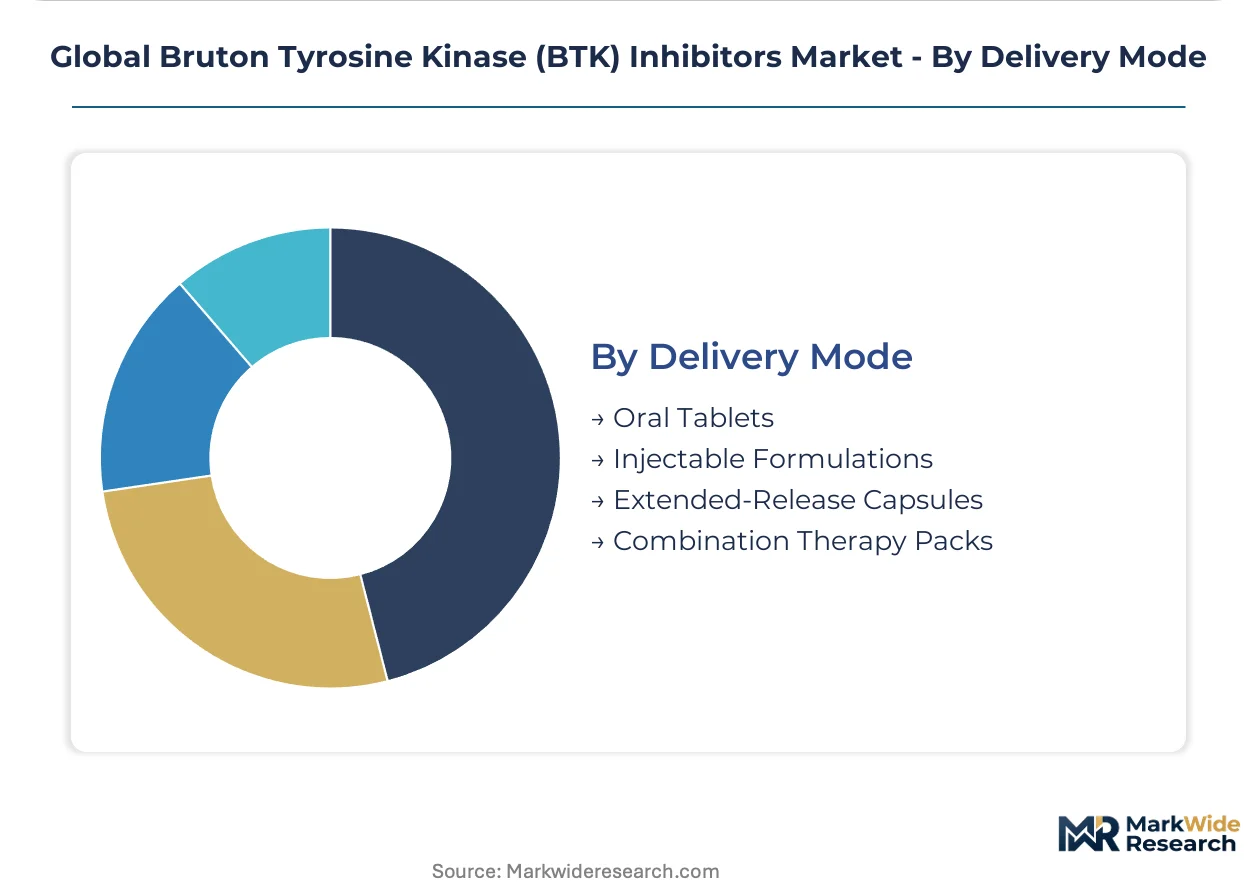
Delivery Mode:
Site-of-care economics and patient adherence requirements are reconfiguring formulation preferences across risk-bearing entities.
- Oral Tablets:Dominant format for BTK inhibitor administration. Medicare Advantage networks optimize around this delivery mode for chronic lymphocytic leukemia maintenance therapy.
- Injectable Formulations:Parenteral delivery for combination regimens or hospital-based initiation. These formats align with monoclonal antibody co-administration protocols.
- Extended-Release Capsules:Modified-release architectures for dosing convenience. Development programs in Japan emphasize patient adherence benefits of reduced dosing frequency.
- Combination Therapy Packs:Bundled BTK inhibitors with anti-CD20 antibodies or BCL-2 antagonists. United States oncology centers are consolidating procurement under specialty pharmacy partnerships for these packs.
Oral tablets retain the largest installed base; combination therapy packs are climbing the fastest as bundling protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized kinase inhibitor synthesis capabilities concentrate among contract manufacturers in China and India, while consumption clusters in United States oncology centers and European hematology clinics. This production-consumption divide shapes regulatory submission strategies and multi-regional launch sequencing for BTK inhibitor sponsors.
United States
Medicare reimbursement policies and NCCN guideline incorporation drive first-line adoption of next-generation covalent and non-covalent inhibitors across hematology-oncology clinics. FDA breakthrough therapy designation compresses review timelines for novel agents targeting C481S-resistant chronic lymphocytic leukemia. The Greater Boston biotech corridor anchors clinical trial infrastructure for combination therapy development.
Germany
Academic medical centers in Munich and Heidelberg adopt reversible non-covalent inhibitors fastest as resistance surveillance expands. EMA PRIME eligibility accelerates regulatory pathways for hematologic malignancy therapies. The Rhine-Main pharmaceutical manufacturing cluster supplies active pharmaceutical ingredients to Western sponsors.
Japan
PMDA sakigake designation enables accelerated commercialization timelines for mantle cell lymphoma therapies in the Asia-Pacific's second-largest pharmaceutical market. Tokyo and Osaka cancer treatment centers unbundle infusion services from oral BTK inhibitor management. Post-market cardiovascular toxicity surveillance requirements shape prescriber training protocols.
China
NMPA oncology innovation pathways add complexity to multi-regional launch sequencing for domestic and multinational sponsors. Contract manufacturers in Jiangsu and Zhejiang provinces dominate specialized kinase inhibitor synthesis. BeiGene leverages global clinical trial infrastructure to compete across both covalent and non-covalent inhibitor classes.
Switzerland
Swissmedic regulatory frameworks support early access programs for breakthrough hematologic therapies. Basel and Zurich anchor pharmaceutical R&D concentration for combination regimen development. The country's precision medicine infrastructure enables molecular diagnostic testing for resistance mutation surveillance.
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the BTK inhibitor landscape, creating a tiered structure where portfolio breadth intersects with indication depth. Large-cap pharmaceutical companies anchor positions through sustained investment in combination regimen development, while emerging biotech firms concentrate on next-generation architectures addressing resistance mutations. Three archetypes dominate: oncology portfolio integrators, hematology-focused developers, and autoimmune expansion specialists. Competitive moves center on clinical trial infrastructure expansion and companion diagnostic partnerships.
Among oncology portfolio integrators, AbbVie and AstraZeneca exemplify the diversified approach, with the former anchoring combination therapy development and the latter integrating BTK inhibitors across broad oncology portfolios. BeiGene occupies a distinctive position as a China-founded sponsor with global clinical trial reach, competing across both covalent and non-covalent inhibitor classes.
| Leading Market Players |
|---|
| BeiGene |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| InnoCare Pharma |
| Novartis |
| AbbVie |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Covalent-to-non-covalent tier divergence separates entrenched first-line standards from premium resistance-sparing alternatives, with this bifurcation manifesting in both patent-protected pricing corridors and geographically concentrated API manufacturing footprints. Contract manufacturers in Jiangsu and Zhejiang provinces anchor the supply base for Western sponsors, while Medicare reimbursement alignment in the United States preserves pricing power for guideline-preferred inhibitors.
Pricing Analysis
Margin tightening in irreversible inhibitor tiers reflects biosimilar development delays around Cys481-binding scaffolds and sustained originator pricing power. Value-based contracting dominates oncology procurement, with NCCN guideline tier and FDA breakthrough designation status driving price differentiation between premium next-generation agents and standard-of-care alternatives. Cost-down pressure accelerates in Medicare Advantage networks as risk-bearing entities optimize site-of-care economics for oral tablet maintenance therapy.
Supply Chain Analysis
Single-source vulnerability sits with specialized kinase inhibitor synthesis capabilities concentrated in China and India, creating geographic dependencies for Western pharmaceutical sponsors. Active pharmaceutical ingredient production draws from contract manufacturers in Jiangsu, Zhejiang, and Hyderabad, with pyrrolopyrimidine and pyrazolopyrimidine scaffolds representing critical raw material inputs. Tariff exposure on Chinese-sourced intermediates strains cost structures, while distribution runs through specialty pharmacy partnerships consolidating oral oncology dispensing in United States cancer centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
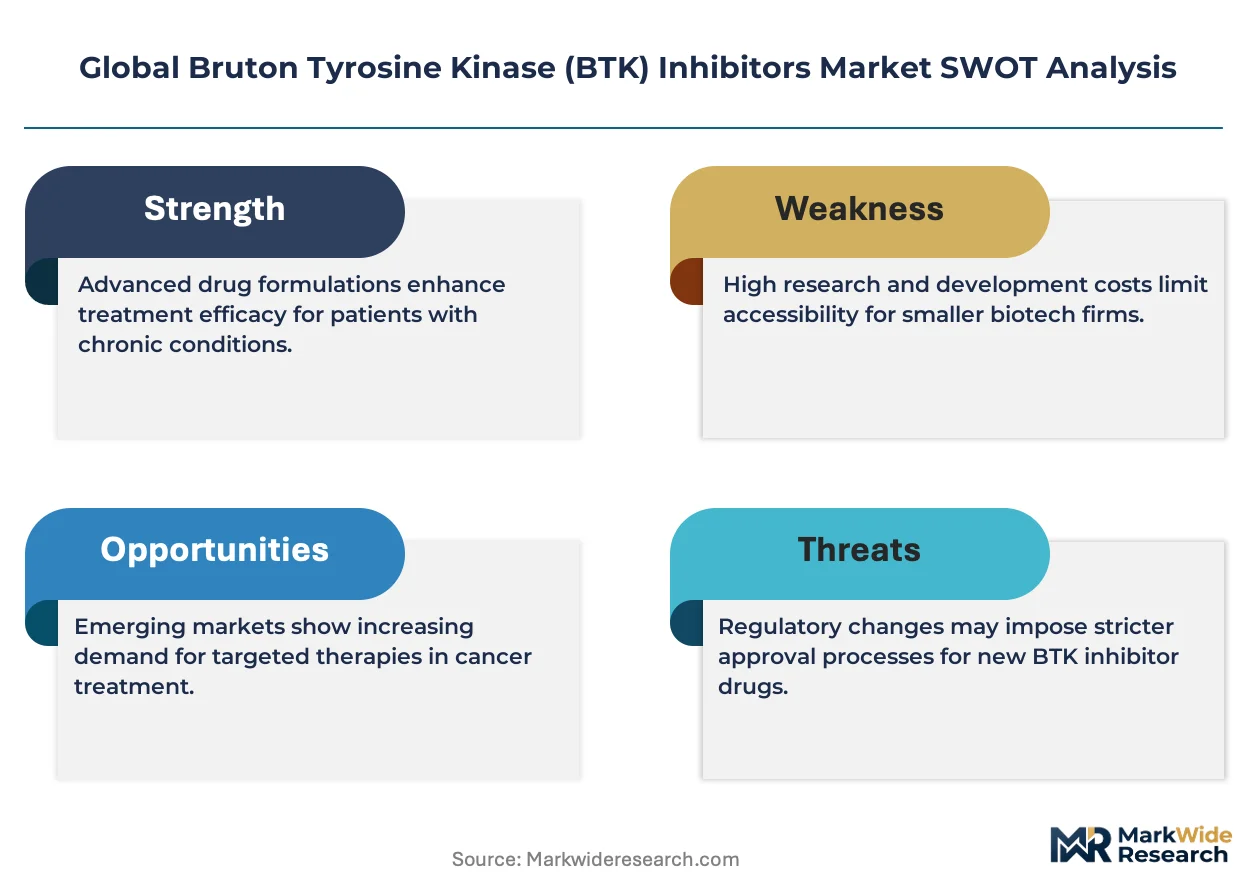
Specialized synthesis capacity constraints prop pricing power for originator BTK inhibitors, as API manufacturing expertise clusters among a limited set of contract manufacturers serving global oncology sponsors.
For Market Incumbents: Lock in backward integration into pyrrolopyrimidine intermediate production to secure supply continuity against Chinese tariff exposure. Prioritize companion diagnostic partnerships for C481S mutation detection to defend formulary positioning against non-covalent entrant pressure. Capacity addition in the Rhine-Main pharmaceutical cluster reduces geographic concentration risk for European supply security. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for accelerated patient access and compressed development timelines for C481S-sparing architectures. Target autoimmune expansion indications—multiple sclerosis and rheumatoid arthritis—as the most penetrable white space beyond oncology saturation. Pursue rheumatology practice partnerships in Germany as the lead go-to-market angle for reversible inhibitor differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with hematology-focused developers possessing global clinical trial infrastructure given EMA-FDA regulatory pathway convergence. Long-term viability hinges on portfolio breadth spanning both covalent and non-covalent inhibitor classes to capture sequential therapy-line economics. Monitor resistance mutation surveillance infrastructure buildout in community oncology practices as the inflection indicator for non-covalent inhibitor adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough designation compresses review timelines for C481S-resistant CLL therapies. |
| Clinical Trial Advancement | Multi-arm combination studies with venetoclax strain investigator bandwidth across United States academic centers. |
| Manufacturing Scale-Up | Specialized kinase inhibitor synthesis expansion in India diversifies supply beyond Chinese concentration. |
| Licensing Agreement | Companion diagnostic partnerships for resistance mutation detection secure formulary positioning. |
| Pipeline Diversification | Autoimmune indication expansion into multiple sclerosis opens reimbursement pathways outside oncology. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database audits and CMS Medicare reimbursement records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated secondary findings. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the projection horizon.
Bottom-up treatment-line segmentation and top-down oncology therapeutic class analysis converged in the analytical framework. Modeled dimensions spanned inhibitor architecture, indication, delivery mode, and regional regulatory cluster. CAGRs derived from patient population epidemiology, therapy-line sequencing patterns, and reimbursement trajectory assumptions. Resistance mutation surveillance expansion rates and combination protocol adoption curves informed forecast inputs.
Caveats apply where cardiovascular toxicity profiling requirements or biosimilar patent challenges could materially shift the outlook. Forecasts reflect assumptions around NCCN guideline positioning, EMA PRIME eligibility timelines, and Medicare Advantage network consolidation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Spectinomycin Market