
 Trauma Products Market | 2026-2036
Trauma Products Market Size, Share, and Industry Trends Forecast 2026-2036
Trauma Products Market Intelligence
Emergency care is consolidating its share of trauma product consumption as hospital networks centralize acute trauma services into dedicated Level I centers. Stryker Corporation leverages its integrated trauma platform to anchor supply relationships with these consolidated buyers. Zimmer Biomet competes through specialized extremity fixation systems that occupy niche procedural segments. Smith & Nephew plc differentiates its trauma portfolio via advanced wound closure technologies that extend into post-operative care pathways.
Trauma products encompass internal and external fixation devices, bone cement, surgical staples, and wound management materials engineered from titanium alloys, stainless steel, or bioresorbable polymers to stabilize fractures and soft-tissue injuries. These devices restore anatomical alignment under physiological load conditions, enabling osseous union and functional recovery. The surgical intervention application leads volume due to operative fracture management protocols, while rehabilitation generates expanding recurring revenue through brace and immobilizer replacement cycles. Hospitals dominate end-user demand through centralized procurement of implant systems, though direct sales channels capture premium pricing from ambulatory surgery centers seeking specialized inventory.
The US FDA regulates trauma implants through the 510(k) premarket notification pathway, while the EU MDR imposes strengthened clinical evidence requirements for Class III orthopedic devices. China's NMPA accelerates market access for innovative trauma fixation through its priority review channel for clinically urgent devices. Stakeholders must monitor evolving biocompatibility testing standards and reimbursement shifts toward outpatient fracture management as care settings fragment beyond traditional hospital environments.
Market Dynamics
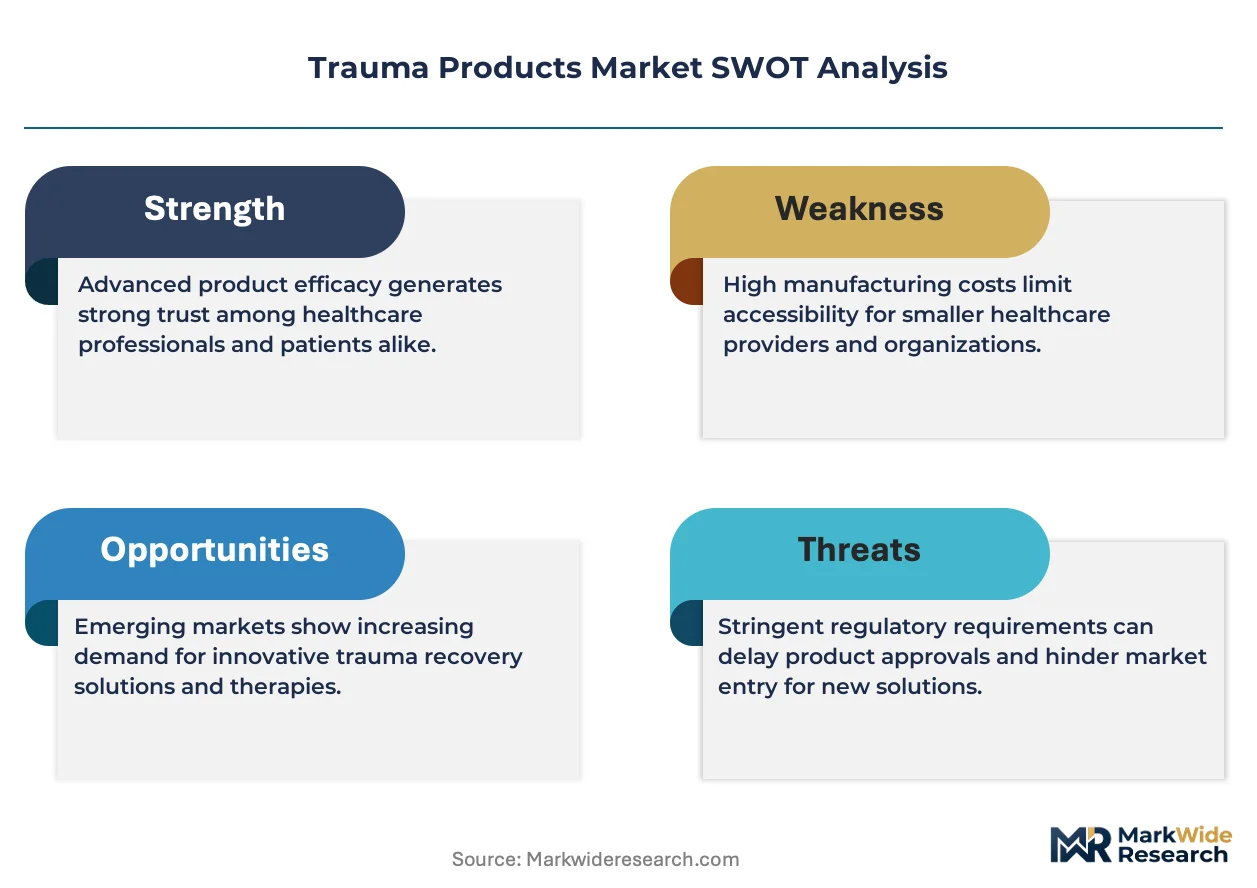
Orthopedic trauma centers are consolidating procurement around integrated fixation platforms, compressing vendor relationships while elevating clinical evidence requirements for implant selection. This structural concentration forces manufacturers to bundle hardware, software, and service capabilities into unified supply contracts.
Growth Catalysts
- Bioresorbable polymer innovation:Advanced magnesium alloys and polylactic acid composites enable gradual implant dissolution, eliminating secondary removal surgeries. The US FDA's streamlined 510(k) pathway accelerates material validation timelines for these next-generation fixation devices.
- Emergency care centralization:Hospital networks are merging acute trauma services into dedicated Level I centers, creating concentrated demand nodes for premium implant systems. Germany's specialized trauma hospitals exemplify this procurement consolidation pattern.
- EU MDR clinical evidence standards:Strengthened post-market surveillance requirements for Class III orthopedic devices are elevating product quality thresholds industry-wide. Manufacturers investing in robust clinical data packages capture preferential positioning with risk-averse procurement committees.
Market Restraints
- Titanium alloy supply concentration:Primary sponge production clusters in China and Russia create raw material vulnerability for Western implant manufacturers. Geopolitical friction threatens feedstock security for precision-machined trauma hardware.
- Biocompatibility testing cost escalation:Extended cytotoxicity and sensitization protocols for novel resorbable materials inflate R&D expenditure. Small and mid-sized manufacturers face disproportionate capital barriers to regulatory compliance.
- External fixation substitution:Minimally invasive percutaneous plating techniques are displacing traditional external fixators in limb reconstruction. This modality shift compresses addressable volume for ring and hybrid external fixation systems.
Strategic Opportunities
- Ambulatory surgery center channel expansion:Outpatient fracture management protocols create direct sales opportunities bypassing hospital procurement hierarchies. Specialized inventory arrangements for ASCs command premium pricing through convenience and speed.
- China NMPA priority review channel:Clinically urgent trauma fixation devices receive accelerated market access through this regulatory fast-track. Domestic and multinational manufacturers leveraging this pathway capture first-mover advantage in high-volume surgical markets.
- Digital surgical planning convergence:Integration of patient-specific 3D modeling with conventional implant systems enables personalized fixation strategies. Trauma centers adopting this workflow differentiation attract complex reconstructive case referrals.
Industry Challenges
- Orthopedic trauma surgeon training pipeline:Fellowship program capacity constraints limit specialist availability for advanced fixation technique adoption. Manufacturers must invest directly in surgeon education infrastructure to expand addressable procedural volume.
- Legacy hospital information system integration:Implant tracking and inventory management platforms require costly customization to interface with entrenched electronic health record architectures. Implementation timelines frequently exceed contracted deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trauma Products Market |
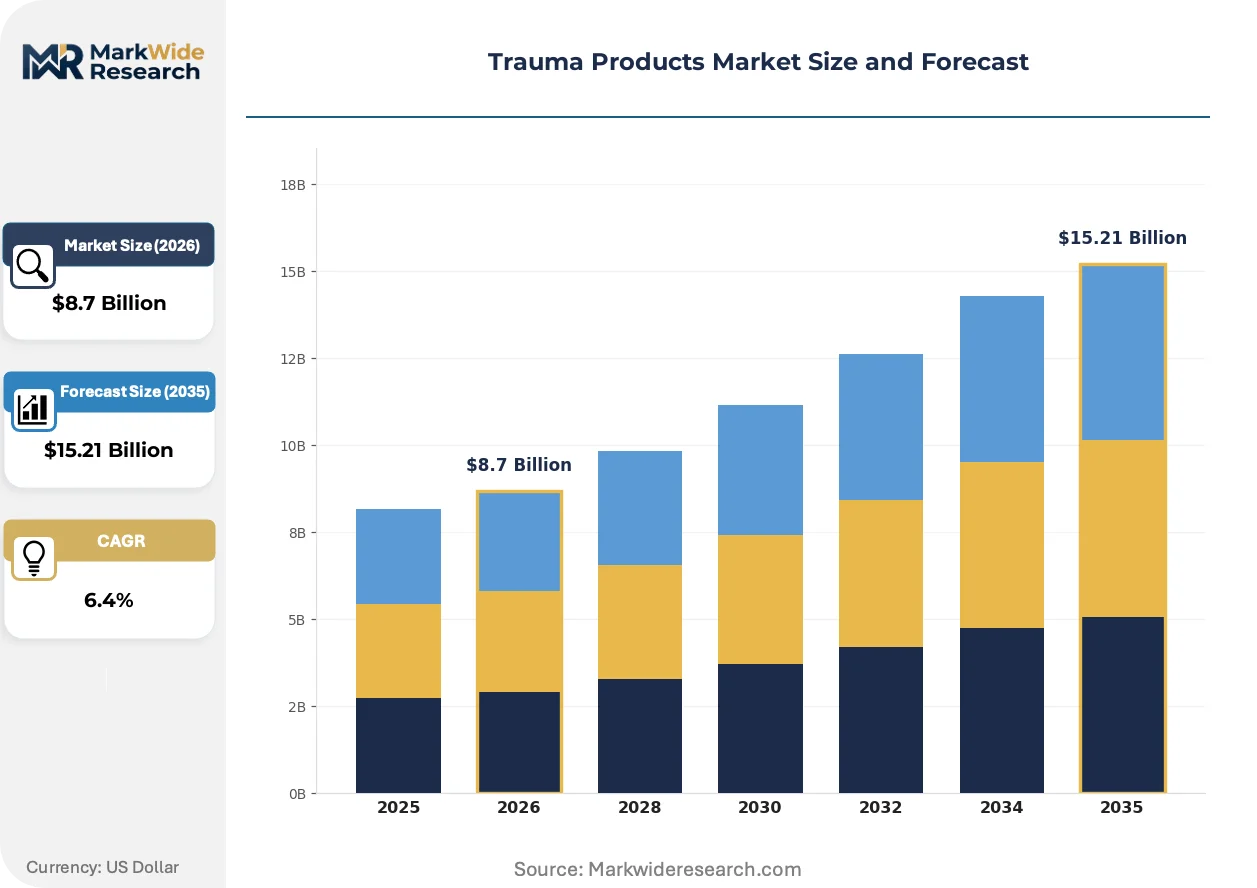
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bandages, Splints, Braces, Immobilizers Application: Emergency Care, Surgical Intervention, Rehabilitation, Home Care End User: Hospitals, Rehabilitation Centers, Clinics, Home Users Distribution Channel: Online, Direct Sales, Pharmacies, Medical Supply Stores |
| Companies Covered | Stryker Corporation, DePuy Synthes, Zimmer Biomet, Smith & Nephew plc, Johnson & Johnson, Orthofix Medical Inc., Acumed LLC, Arthrex Inc., B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trauma Products Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory pathway evolution are compressing product development cycles while elevating clinical performance benchmarks across trauma fixation. Three interconnected developments are restructuring competitive advantage formation.
Patient-specific 3D-printed titanium implants are electrifying complex pelvic and acetabular reconstruction workflows. Academic medical centers with dedicated additive manufacturing facilities are adopting these custom geometries within 48-hour production windows. This capability is compressing revision surgery rates while displacing standard off-the-shelf plates in high-energy fracture patterns.
The EU MDR's strengthened clinical evidence requirements for Class III orthopedic devices are extending technical documentation preparation timelines. Manufacturers must generate prospective clinical data or equivalent real-world evidence for legacy product recertification. Trauma fixation portfolios with limited post-market surveillance histories face disproportionate compliance burden and potential portfolio rationalization.
Hospital procurement committees are consolidating vendor relationships around full-service trauma platform providers. Integrated contracts spanning implants, power tools, and disposable consumables are displacing fragmented multi-supplier arrangements. This concentration is most visible in US health system centralization initiatives, where standardized protocols reduce inventory complexity and streamline surgeon training requirements.
Trauma Products Market Segmentation
Trauma product procurement varies sharply by care setting and patient acuity. Upgrade cycles differ materially across hardware versus consumable categories, with implant systems requiring surgical technique certification while disposables turn on inventory velocity.
Product Type:
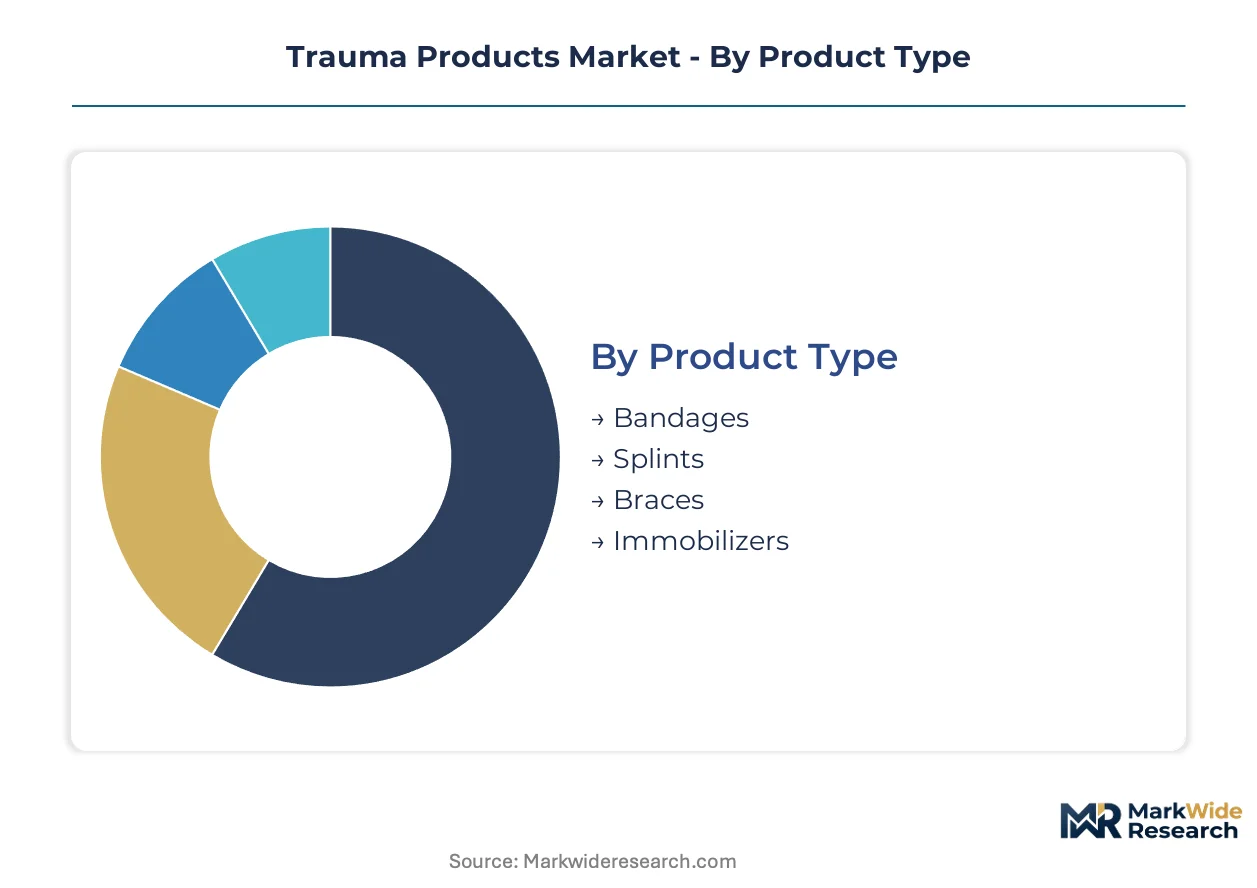
Replacement intensity separates consumables from capital hardware, with adhesive bandages and casting materials cycling through weekly restocking while splint systems persist across multi-year depreciation schedules.
- Bandages:Adhesive and cohesive variants engineered from elastic fibers or hydrocolloid substrates manage exudate and protect wound beds. Demand clusters in emergency departments across Germany and the United States where high patient throughput mandates continuous restocking. Raw material volatility in cotton and synthetic adhesives pressures margin structures for contract manufacturers.
- Splints:Rigid and semi-rigid stabilization devices fabricated from fiberglass, aluminum, or thermoplastic materials immobilize acute fractures prior to definitive fixation. Orthopedic trauma centers in specialized German hospitals drive premium uptake of moldable and waterproof variants that accelerate casting workflow efficiency.
- Braces:Hinged and static designs provide post-operative joint protection and ligament support during rehabilitation phases.
- Immobilizers:Foam and fabric constructs with rigid stays limit range of motion for soft-tissue injuries and post-surgical recovery.
Volume placements concentrate in bandages; the faster expansion belongs to splints.
Application:
Clinical setting determines reimbursement pathway and product specification intensity, with inpatient surgical sites commanding sterilized implant-grade hardware while outpatient channels absorb basic stabilization supplies.
- Emergency Care:Acute trauma bays require rapid-deployment fixation and wound management supplies compatible with hemodynamic instability protocols. Level I trauma centers in the United States consolidate procurement around integrated platforms that bundle implants with power instrumentation and disposable consumables.
- Surgical Intervention:Operative fracture management employs internal fixation plates, screws, and intramedullary nails machined from titanium alloys or stainless steel. Germany's specialized trauma hospitals anchor European demand for anatomically contoured locking plate systems that reduce revision rates in complex periarticular injuries.
- Rehabilitation:Post-acute recovery protocols generate recurring revenue through brace replacement and progressive mobilization devices.
- Home Care:Patient-directed wound care and immobilization supplies bypass institutional procurement hierarchies.
Revenue gravity sits with surgical intervention; rehabilitation claims the steepest expansion trajectory.
End User:
Capital availability and procurement sophistication stratify across institutional buyers, with integrated delivery networks extracting volume discounts while independent clinics absorb distributor markups.
- Hospitals:Centralized materials management departments negotiate multi-year supply agreements spanning trauma implants, power tools, and sterile disposables. US health system consolidation is compressing vendor rosters to single-source platform providers that standardize surgeon training and reduce SKU complexity.
- Rehabilitation Centers:Outpatient physical therapy facilities purchase durable medical equipment and replacement brace inventory through group purchasing organizations.
- Clinics:Ambulatory surgery centers seek specialized trauma fixation inventory through direct manufacturer relationships that bypass hospital procurement delays.
- Home Users:Direct-to-patient channels capture premium pricing for convenience-driven wound care and immobilization supplies.
Procurement volume aggregates at hospitals; ambulatory surgery centers are gaining share fastest.
Distribution Channel:
Channel selection reflects urgency requirements and product complexity, with sterile implants demanding cold-chain logistics while basic supplies tolerate parcel post.
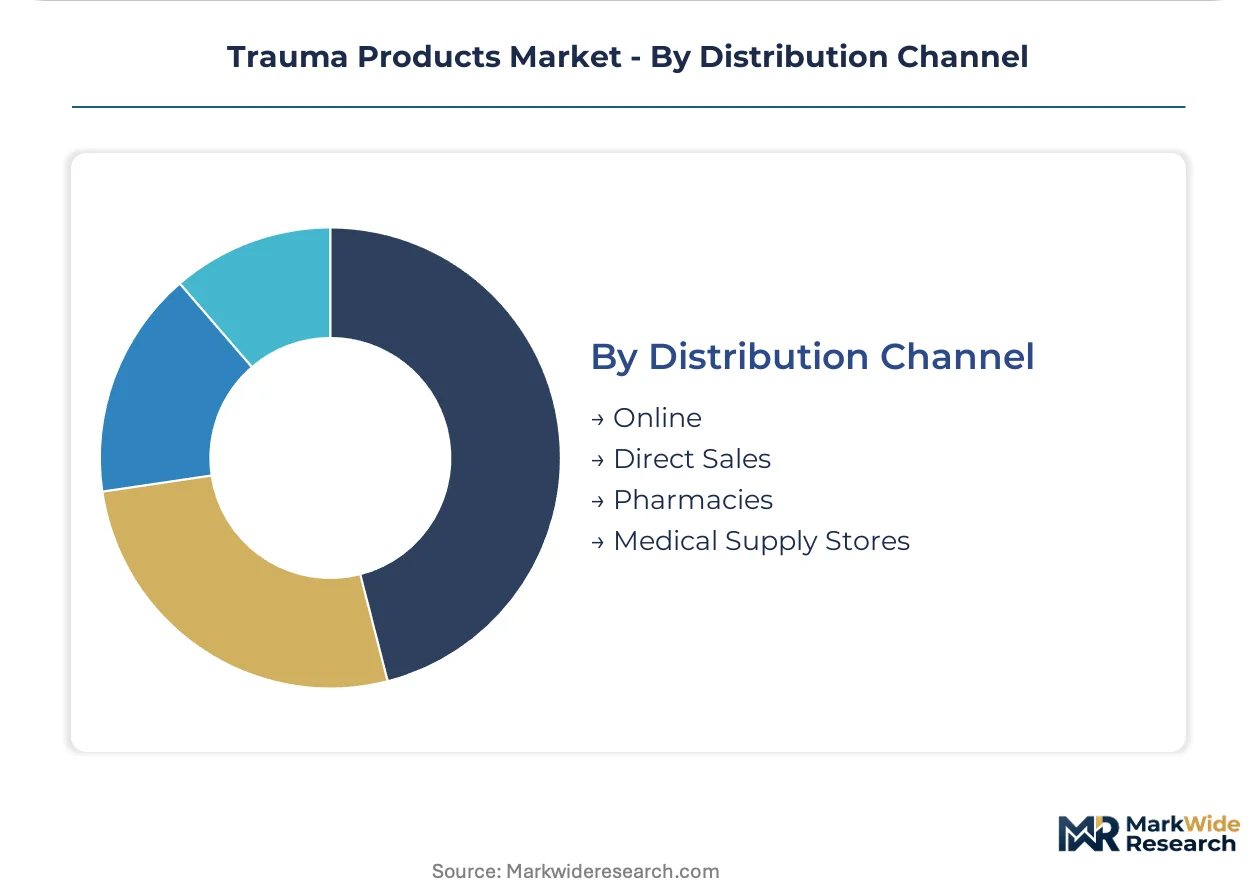
- Online:E-commerce platforms aggregate consumable demand from small clinics and home users seeking transparent pricing and rapid replenishment. Specialized orthopedic distributors maintain digital storefronts with surgeon-specific catalog permissions that restrict implant purchases to credentialed professionals.
- Direct Sales:Manufacturer representatives cultivate long-term supply relationships with high-volume trauma centers. Stryker Corporation deploys dedicated account managers to anchor integrated contracts across US health system consolidation initiatives.
- Pharmacies:Retail and hospital outpatient dispensaries stock basic wound care and immobilization supplies for patient self-care.
- Medical Supply Stores:Durable medical equipment dealers serve post-acute and home care segments with brace and mobility device rentals.
Transaction volume flows through direct sales; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes trauma fixation systems at volumes that outstrip domestic production capacity, while China manufactures titanium alloy feedstock that Western implant fabricators depend upon. This production-consumption asymmetry shapes procurement risk profiles across major surgical markets.
United States
Level I trauma centers in Texas and California drive demand for integrated fixation platforms that bundle implants with power instrumentation. The FDA's streamlined 510(k) pathway for bioresorbable devices accelerates material innovation timelines. Stryker Corporation anchors supply relationships with consolidated health systems in the Midwest and Southeast.
Germany
Specialized trauma hospitals in Bavaria and North Rhine-Westphalia anchor European demand for anatomically contoured locking plate systems. The EU MDR imposes strengthened clinical evidence requirements for Class III orthopedic devices. Berlin-Brandenburg hosts regulatory consulting clusters that guide manufacturers through post-market surveillance compliance.
China
Domestic trauma fixation manufacturers capture volume in tier-two and tier-three city hospitals as surgical capacity expands. The NMPA operates a priority review channel for clinically urgent devices that reduces time-to-market for innovative implants. Yangtze River Delta production clusters machine precision trauma hardware for domestic and export markets.
Japan
Aging demographics elevate fracture incidence rates and sustain procedural volume for osteosynthesis systems. The PMDA maintains rigorous biocompatibility testing standards that extend validation timelines for novel resorbable materials. Kanto region academic medical centers adopt patient-specific 3D-printed implants for complex pelvic reconstructions.
India
Trauma care infrastructure expansion in Maharashtra and Karnataka creates demand for cost-optimized fixation devices. The CDSCO regulates orthopedic implants through a risk-based classification system that stratifies clinical evidence requirements. Delhi-NCR hospital networks centralize procurement for premium trauma platforms serving medical tourism segments.
Trauma Products Market Key Industry Players
Top-tier vendors anchor integrated trauma platform supply, while mid-sized specialists occupy niche fixation segments and regional distributors capture ambulatory surgery center volume. Market structure concentrates around manufacturers with full-service capabilities spanning implants, power tools, and disposable consumables. Three archetypes dominate: diversified orthopedic conglomerates with trauma divisions, pure-play trauma fixation specialists, and regional contract manufacturers serving price-sensitive markets. Competitive moves center on health system consolidation capture and ambulatory channel expansion.
Within the diversified orthopedic tier, Stryker Corporation and Zimmer Biomet occupy positions that exemplify platform-level supply relationships. Stryker leverages its integrated trauma portfolio to anchor multi-year contracts with consolidated US health systems. Zimmer Biomet represents specialized extremity fixation capabilities that penetrate niche procedural segments. Smith & Nephew plc sits within the wound-care-trauma convergence archetype, differentiating through post-operative care pathway extension.
| Leading Market Players |
|---|
| Stryker Corporation |
| DePuy Synthes |
| Zimmer Biomet |
| Smith & Nephew plc |
| Johnson & Johnson |
| Orthofix Medical Inc. |
| Acumed LLC |
| Arthrex Inc. |
| B. Braun Melsungen AG |
| Others |
Cost & Logistics Intelligence
Bioresorbable polymer manufacturing transitions from batch synthesis to continuous processing, compressing unit economics while concentrating production capability among capital-rich specialists with dedicated cleanroom infrastructure. This process shift simultaneously elevates quality consistency thresholds and locks out contract manufacturers lacking validated continuous lines, reshaping procurement leverage across implant tiers.
Pricing Analysis
Lead-time premiums command 15-30% markups for patient-specific 3D-printed implants delivered within 48-hour windows, while spot inventory of standard titanium plates trades at discounts to long-term contract pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by anatomical complexity and regulatory certification tier. Cost compression in economy-grade external fixation runs through distributor consolidation and Chinese titanium sponge oversupply. Ambulatory surgery centers exhibit highest price sensitivity due to constrained capital budgets, while Level I trauma centers absorb premium pricing for integrated platform contracts.
Supply Chain Analysis
Regional distribution centers in Memphis, Rotterdam, and Singapore anchor hub-and-spoke patterns that position sterile implant inventory within four-hour ground transport of major surgical clusters. Titanium alloy feedstock concentrates in China and Russia, with magnesium alloy precursor production clustering in Israel and Germany. Raw material dependencies span surgical-grade titanium sponge, bioresorbable polylactic acid resin, and cobalt-chrome powder for additive manufacturing. Single-source vulnerability in Chinese sponge exports threatens Western implant fabricators amid geopolitical friction. Distribution runs through manufacturer-direct sales forces for high-value implants and orthopedic specialty distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's clinical evidence requirements erect a cost-of-compliance moat that favors incumbents with existing post-market surveillance infrastructure and capital reserves for legacy product recertification.
For Market Incumbents: Hedge titanium supply exposure through captive offtake agreements with non-Chinese sponge producers or backward integration into scrap recycling. Consolidate procurement relationships around full-service trauma platforms that bundle implants, power tools, and disposable consumables into multi-year contracts. Threat substitution from patient-specific 3D-printed implants demands R&D investment in digital surgical planning integration. For New Entrants and Emerging Players: Enter via ambulatory surgery center direct sales channels that bypass hospital procurement hierarchies and command premium pricing for specialized inventory. Target cost-optimized trauma fixation in India and Southeast Asia where surgical capacity expansion outstrips domestic supply. White-space opportunity concentrates in bioresorbable magnesium alloy fixation for pediatric applications. Go-to-market leverage rests on NMPA priority review channel navigation for accelerated China access. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-level acquisitions by diversified orthopedic conglomerates seeking trauma division scale. Long-term viability frames around EU MDR compliance infrastructure as a scarce, non-replicable asset. Acquisition target archetype: mid-cap trauma specialists with robust clinical data packages and ASC channel penetration. Signal to watch: health system consolidation velocity in US Midwest and Southeast markets.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Legacy product recertification secures continued market access for Class III orthopedic portfolios. |
| Patient-Specific 3D Printing Capability Buildout | Academic medical center partnerships in Kanto and Bavaria anchor complex pelvic reconstruction workflows. |
| Bioresorbable Material FDA 510(k) Submission | Streamlined pathway accelerates magnesium alloy fixation validation timelines versus premarket approval. |
| Ambulatory Surgery Center Direct Sales Expansion | Specialized inventory arrangements bypass hospital procurement delays and capture premium pricing. |
| Titanium Sponge Supply Agreement Diversification | Non-Chinese feedstock sourcing mitigates geopolitical risk for Western precision-machined hardware fabricators. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with orthopedic trauma surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EU MDR technical documentation registries, NMPA priority review announcements, and hospital procurement databases furnished validation sources. Bottom-up implant volume modeling triangulated against top-down health system expenditure estimates.
Granularity-level framing applied country-specific regulatory pathway assumptions, product-type replacement intensity curves, and end-user procurement sophistication tiers across the analysis window. Segmentation dimensions spanned hardware versus consumable categories, inpatient versus outpatient care settings, and direct sales versus distributor channel structures. CAGRs derived from surgical procedure volume forecasts, implant penetration rates, and pricing trajectory assumptions. Industry-specific inputs incorporated bioresorbable material adoption curves and health system consolidation velocity indices.
Revisions become necessary when EU MDR enforcement intensity shifts, biocompatibility testing standards evolve, or titanium supply disruptions materialize. Forecasts reflect documented assumptions regarding surgical technique adoption rates and reimbursement pathway stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Casting and Splints Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Urine Meter Trays Market