
 Automatic Laser Welding Machine Market | 2026-2036
Automatic Laser Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Laser Welding Machine Market Insights
Aftermarket service revenue is rewriting profit allocation across the Automatic Laser Welding Machine competitive landscape. TRUMPF leverages its captive service network across European automotive hubs to capture recurring revenue streams. IPG Photonics Corporation anchors its position through vertical control of fiber laser source production. Han's Laser Technology Industry Group Co., Ltd dominates domestic aftermarket channels within China's precision manufacturing corridor.
An automatic laser welding machine employs a concentrated coherent light beam to fuse metallic substrates with minimal heat-affected zones, typically operating at power densities exceeding 10^6 W/cm² for precision joints in dissimilar materials. Fiber laser welding machines lead unit shipments due to superior wall-plug efficiency and beam quality at industrial power levels. Pulsed laser technology occupies the medical instrument and jewelry production segments where thermal distortion must stay below 50 micrometers. Aerospace fabrication applications sustain premium pricing through stringent Nadcap accreditation requirements and nickel-alloy processing complexity.
FDA device manufacturing regulations and the EU Machinery Directive enforce traceable weld documentation for medical instrument and heavy machinery fabrication end users. China's SAMR administers GB standards that mandate laser safety interlocks and operator certification for industrial fiber systems. Stakeholders must monitor evolving dual carbon goals in Beijing and Brussels that tie capital equipment procurement to energy efficiency benchmarks and carbon disclosure thresholds.
Market Dynamics
Automotive battery pack manufacturing is compressing weld cycle times below 200 milliseconds, forcing equipment suppliers to redesign optical delivery architectures around multi-kilowatt fiber sources.
Growth Catalysts
- EU Machinery Directive:Mandates traceable weld documentation for heavy machinery fabrication, compelling manufacturers to upgrade legacy systems with integrated quality monitoring.
- Automotive belt concentration:Germany's automotive corridor drives fiber laser adoption as EV battery welding specifications tighten joint penetration tolerances.
- Dual carbon goals:Beijing's energy efficiency benchmarks tie capital equipment procurement to carbon disclosure thresholds, accelerating replacement of gas-shielded arc systems.
Market Restraints
- Fiber laser source concentration:Supply bottlenecks in high-purity ytterbium-doped fiber create vulnerability in upstream component availability.
- Technical limitation:Aluminum-copper dissimilar metal welding remains constrained by brittle intermetallic formation at joint interfaces.
- Substitution threat:Advanced resistance welding with adaptive current control captures cost-sensitive automotive body-in-white applications.
Strategic Opportunities
- Medical instrument segment:Pulsed laser systems for titanium implant welding remain underpenetrated relative to orthopedic device manufacturing growth.
- EU Green Deal:Carbon border adjustment mechanisms create competitive advantage for laser welding's reduced energy intensity versus conventional joining.
- Remote laser scanning:Galvanometer-based beam steering converges with machine vision to enable non-contact seam tracking for complex geometries.
Industry Challenges
- Nadcap accreditation timelines:Aerospace suppliers face 18-24 month certification cycles for nickel-alloy welding procedure qualifications.
- Optics technician scarcity:Specialized skills in beam alignment and resonator maintenance outpace vocational training program output.
- Legacy integration friction:Retrofitting fiber lasers into existing robotic cells requires custom cable routing and safety interlock reprogramming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Laser Welding Machine Market |
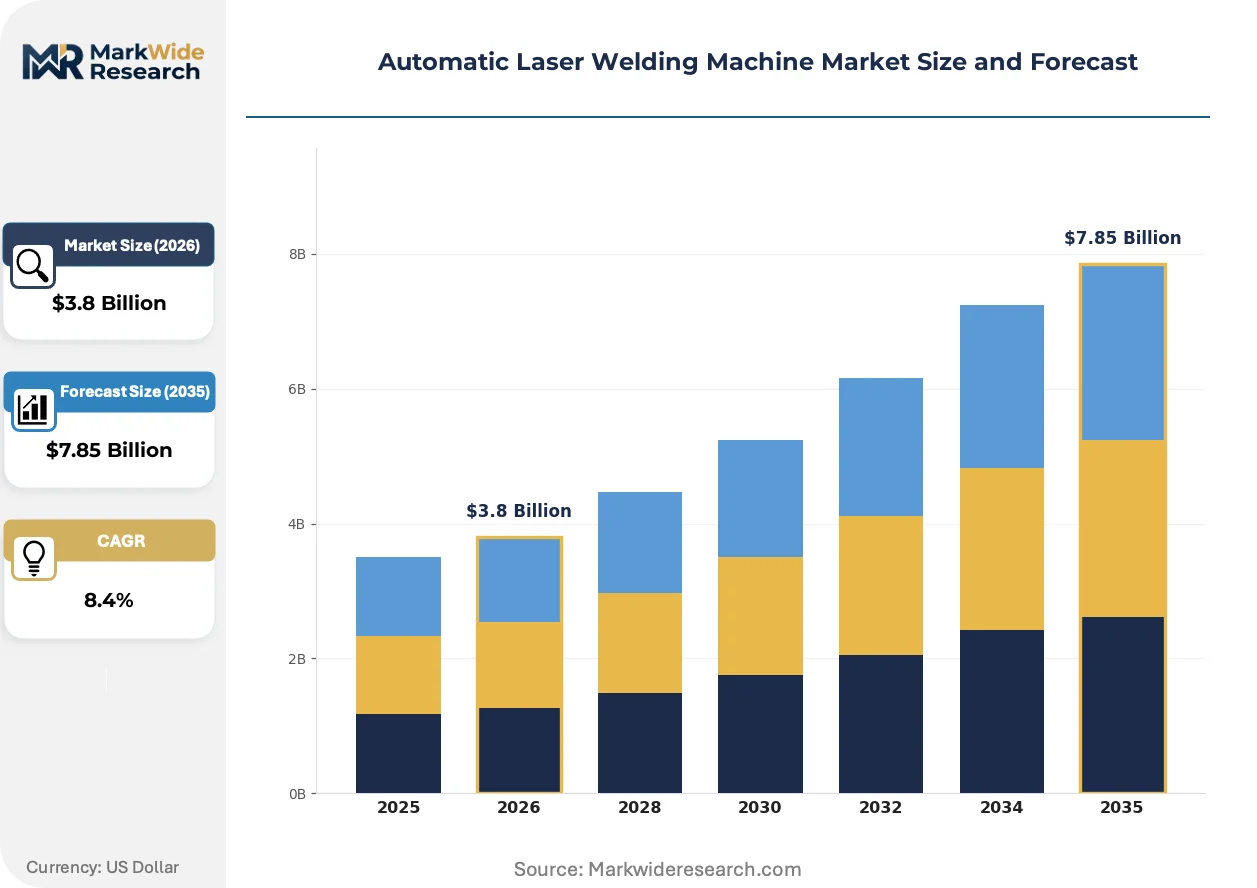
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser Welding Machine, Fiber Laser Welding Machine, Diode Laser Welding Machine, Nd:YAG Laser Welding Machine, Disk Laser Welding Machine Technology: Continuous Wave Laser, Pulsed Laser, Hybrid Laser, Laser Hybrid Arc Welding, Solid State Laser Application: Aerospace Components, Electronic Devices, Jewelry Production, Medical Instruments, Heavy Machinery Fabrication End User Industry: Electronics Manufacturing, Jewelry Crafting, Medical Device Production, Aerospace Fabrication, Shipbuilding |
| Companies Covered | IPG Photonics Corporation, Han’s Laser Technology Industry Group Co., Ltd, TRUMPF, Coherent Inc., Wuhan HGLaser Engineering Co., Ltd, Amada Miyachi Co., Ltd., KEYENCE CORPORATION, Penta Laser (Zhejiang) Co., Ltd, SENFENG Laser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Laser Welding Machine Market Trends and Innovations
Beam delivery architectures are virtualizing control functions that previously demanded dedicated hardware, collapsing the boundary between optical engineering and software-defined manufacturing.
Artificial intelligence is virtualizing weld parameter optimization through real-time melt-pool monitoring and predictive penetration depth modeling. Tier-one automotive suppliers deploy these systems across high-volume battery tab welding lines. The technology is virtualizing quality assurance labor while compressing defect detection latency from offline inspection to in-process intervention.
China's GB standards administered by SAMR now mandate laser safety interlocks and operator certification for industrial fiber systems above 1 kilowatt output. Heavy machinery fabricators in the Yangtze River Delta manufacturing corridor face compliance deadlines requiring controller firmware updates and protective housing retrofits. Medical instrument manufacturers exporting to China must document weld traceability through revised quality management system audits.
Aftermarket service contracts are unbundling from initial equipment sales as buyers demand predictive maintenance tied to uptime guarantees rather than fixed-schedule technician visits. German automotive OEMs now specify outcome-based service level agreements with penalty clauses for unplanned downtime exceeding four hours. This restructuring concentrates service revenue with suppliers maintaining captive spare parts inventories near Stuttgart and Wolfsburg production clusters.
Automatic Laser Welding Machine Market Segmentation
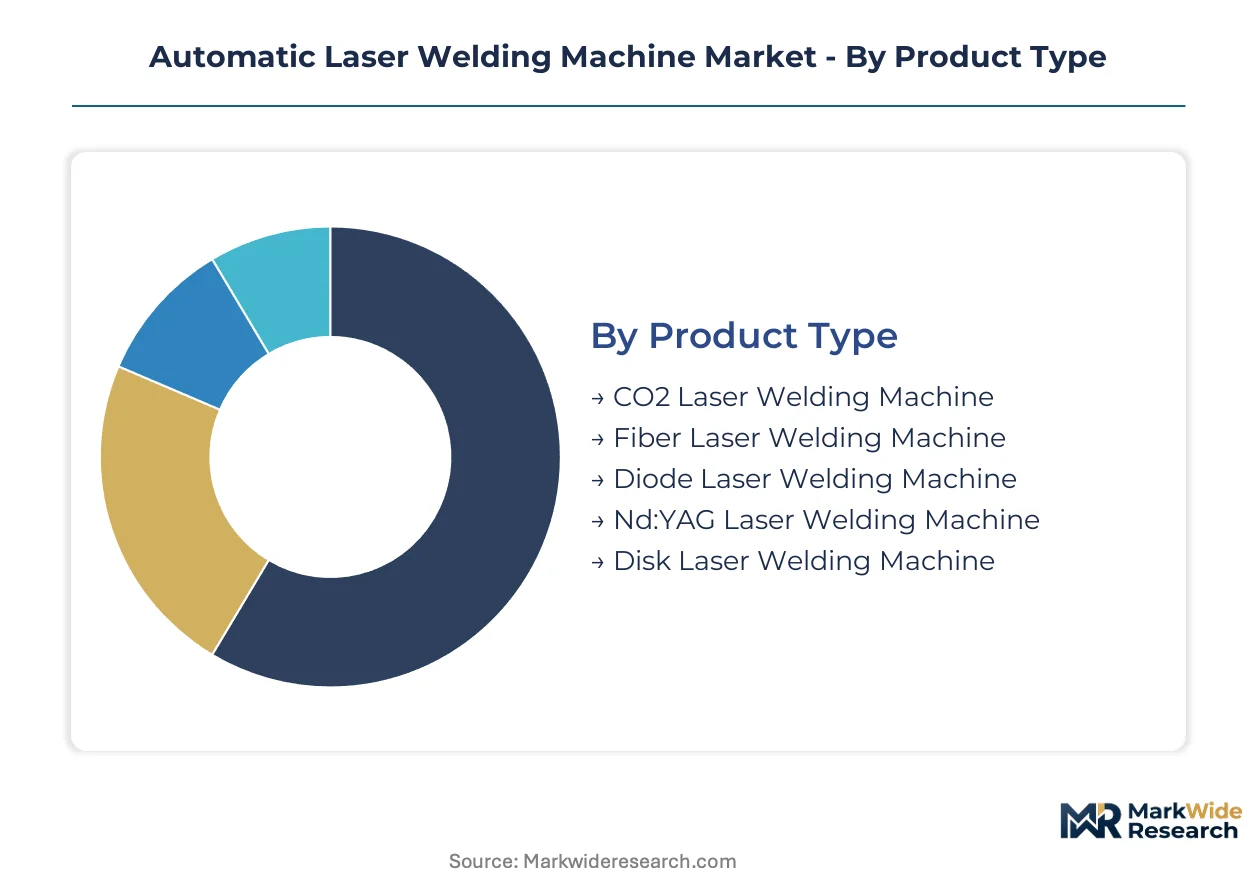
Segmentation in the automatic laser welding machine market reveals how technology choices map to performance requirements and regulatory constraints. Buyers select systems based on material thickness, joint geometry, and certification demands rather than price alone.
Product Type:
Cost tier determines access to beam quality, wall-plug efficiency, and maintenance intervals across industrial laser architectures.
- Fiber Laser Welding Machine:Ytterbium-doped fiber gain media deliver power densities exceeding 10^6 W/cm² with electrical-to-optical conversion above 30%. Automotive battery pack manufacturers in Germany's Stuttgart corridor specify multi-kilowatt fiber systems for tab-to-busbar welding cycles below 200 milliseconds.
- CO2 Laser Welding Machine:Gas discharge excitation produces 10.6-micrometer wavelength output optimal for thick-section steel processing. Shipyards along China's Yangtze River Delta retain CO2 installations for hull plate joining where penetration depth exceeds 12 millimeters.
- Diode Laser Welding Machine:Direct-emitting semiconductor arrays enable compact form factors for plastic welding and brazing applications.
- Nd:YAG Laser Welding Machine:Neodymium-doped yttrium aluminum garnet rods provide 1.064-micrometer output with legacy installed base in jewelry production.
- Disk Laser Welding Machine:Thin-disk geometry combines fiber-like beam quality with power scalability for aerospace nickel-alloy processing.
Fiber laser systems hold installed capacity. Disk laser configurations are rotating up the share rankings.
Technology:
Application requirements for heat input control and penetration depth determine selection between continuous and modulated energy delivery modes.
- Continuous Wave Laser:Uninterrupted emission sustains stable keyhole formation for deep-penetration welds in structural steel. Heavy machinery fabricators under EU Machinery Directive compliance mandates deploy continuous wave systems with integrated seam tracking for traceable documentation.
- Pulsed Laser:Millisecond-duration energy bursts limit heat-affected zones to sub-50-micrometer dimensions. Medical instrument manufacturers producing titanium orthopedic implants specify pulsed Nd:YAG or fiber sources to meet FDA device manufacturing regulations for thermal distortion control.
- Hybrid Laser:Simultaneous laser and arc processes bridge gap tolerance in thick-section applications.
- Laser Hybrid Arc Welding:Tandem heat sources combine penetration precision with gap-bridging capability for shipbuilding.
- Solid State Laser:Crystal-based gain media provide wavelength diversity for specialized material interactions.
Continuous wave systems dominate heavy fabrication installed base. Pulsed configurations are climbing the fastest in medical and electronics segments.
Application:
End-use specifications for joint integrity, surface finish, and documentation rigidity fragment demand across industrial sectors.
- Medical Instruments:Titanium and cobalt-chrome implant welding demands vacuum-tight joints with surface roughness below Ra 0.8 micrometers. China's SAMR-administered GB standards now mandate laser safety interlocks and operator certification for industrial fiber systems serving orthopedic device exporters.
- Aerospace Components:Nickel-based superalloys and titanium alloys require Nadcap-accredited welding procedure specifications. Suppliers face 18-24 month qualification timelines for gas turbine component repairs.
- Electronic Devices:Hermetic sealing of sensor housings and battery enclosures drives demand for precision micro-welding.
- Jewelry Production:Pulsed laser spot welding enables repair work on precious metal assemblies without removal of heat-sensitive gemstones.
- Heavy Machinery Fabrication:Structural weldments for construction and mining equipment prioritize deposition rate over cosmetic finish.
Heavy machinery retains volume leadership. Medical instruments are gaining share fastest on regulatory tailwinds.
End User Industry:
Customer procurement patterns separate capital-intensive volume producers from job-shop flexibility seekers.
- Electronics Manufacturing:High-mix, high-volume production lines for consumer devices and automotive electronics require rapid changeover between aluminum, copper, and steel alloys. Contract manufacturers specify fiber laser cells with automated fixture recognition.
- Aerospace Fabrication:Long-lead production contracts for airframe structures and engine components sustain premium pricing through stringent quality system requirements. OEMs specify outcome-based service level agreements with uptime guarantees.
- Medical Device Production:Regulatory filing requirements lock welding procedures to specific equipment configurations.
- Shipbuilding:Thick-plate hull construction and outfitting welding favor high-deposition processes with manual operator override.
- Jewelry Crafting:Artisan-scale workshops prioritize compact footprint and low capital outlay over production throughput.
Electronics manufacturing holds installed capacity. Aerospace fabrication is rotating up the share rankings on Nadcap accreditation premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta deploys fiber laser systems for high-speed battery tab welding, while Germany's automotive belt prioritizes precision disk lasers for aerospace-grade joints. The United States concentrates demand in medical device clusters requiring FDA-compliant pulsed systems. Japan maintains specialized capacity for electronics micro-welding. South Korea's EV supply chain is compressing cycle times below 200 milliseconds.
China
SAMR-administered GB standards mandate laser safety interlocks and operator certification for industrial fiber systems above 1 kilowatt output. The Yangtze River Delta manufacturing corridor faces compliance deadlines requiring controller firmware updates and protective housing retrofits. Medical instrument manufacturers exporting to China must document weld traceability through revised quality management system audits.
Germany
The EU Machinery Directive enforces traceable weld documentation for heavy machinery fabrication, compelling manufacturers to upgrade legacy systems with integrated quality monitoring. Stuttgart and Wolfsburg production clusters drive fiber laser adoption as EV battery welding specifications tighten joint penetration tolerances. German automotive OEMs now specify outcome-based service level agreements with penalty clauses for unplanned downtime exceeding four hours.
United States
FDA device manufacturing regulations enforce traceable weld documentation for medical instrument end users. The Boston-Cambridge medical device corridor sustains demand for pulsed laser systems capable of sub-50-micrometer heat-affected zones in titanium orthopedic implants. Aerospace suppliers in the Pacific Northwest face 18-24 month Nadcap accreditation timelines for nickel-alloy welding procedure qualifications.
Japan
METI industrial standards emphasize energy efficiency benchmarks that accelerate replacement of gas-shielded arc systems with fiber laser alternatives. The Nagoya automotive and electronics manufacturing belt requires rapid changeover between aluminum, copper, and steel alloys. Contract manufacturers specify fiber laser cells with automated fixture recognition for high-mix production lines.
South Korea
The Seoul Capital Area EV battery manufacturing cluster compresses weld cycle times below 200 milliseconds, forcing equipment suppliers to redesign optical delivery architectures around multi-kilowatt fiber sources. MFDS medical device regulations align with international traceability standards for implant welding. Busan-Ulsan shipyards evaluate hybrid laser-arc systems for thick-section hull construction.
Automatic Laser Welding Machine Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct tiers: vertically integrated laser source manufacturers, regional system integrators with captive service networks, and specialized niche players focused on single applications. Strategic moves concentrate on backward integration into fiber gain media production and geographic expansion through distribution partnerships in high-growth manufacturing corridors.
Among German and Chinese fabricators, TRUMPF, Han's Laser Technology Industry Group Co., Ltd, and IPG Photonics Corporation occupy positions across the capability-scale spectrum. TRUMPF represents the integrated-system archetype with European automotive hub proximity. Han's Laser exemplifies domestic aftermarket channel dominance within China's precision manufacturing corridor. IPG Photonics anchors the upstream-control tier through in-house production of fiber laser sources. These three entities illustrate how competitive positioning fragments across technology ownership, geographic density, and service model differentiation.
| Leading Market Players |
|---|
| IPG Photonics Corporation |
| Han's Laser Technology Industry Group Co., Ltd |
| TRUMPF |
| Coherent Inc. |
| Wuhan HGLaser Engineering Co., Ltd |
| Amada Miyachi Co., Ltd. |
| KEYENCE CORPORATION |
| Penta Laser (Zhejiang) Co., Ltd |
| SENFENG Laser |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's fiber laser source manufacturing corridor is compressing margins for mid-tier system integrators while concentrating pricing power with ytterbium-doped fiber producers. This utilization imbalance forces equipment suppliers to bundle predictive maintenance contracts with hardware sales, transforming transactional revenue into recurring service streams.
Pricing Analysis
Long-term offtake agreements dominate procurement between German automotive OEMs and European system integrators, locking in multi-year pricing with uptime guarantee clauses. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-accredited aerospace configurations from automotive battery welding cells and entry-level job-shop systems. Cost compression in standard-tier fiber laser cells is intensifying because Chinese domestic suppliers are expanding export capacity. Contract manufacturers in the Yangtze River Delta exhibit highest price sensitivity, while aerospace fabricators in Germany's Stuttgart corridor prioritize certification-grade equipment over unit cost.
Supply Chain Analysis
High-purity ytterbium-doped fiber feedstock concentrates in the United States, Germany, and China, with IPG Photonics and TRUMPF maintaining captive production of gain media. German precision optics, Japanese galvanometer scanners, and Chinese machined housings constitute critical component inputs. Single-source vulnerability in rare-earth fiber doping creates exposure to export licensing restrictions. Distribution runs through direct OEM relationships for high-volume automotive contracts, while regional integrators serve fragmented job-shop demand across Europe and Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automatic laser welding equipment faces substitution pressure from adaptive resistance welding in cost-sensitive automotive body-in-white applications, compelling incumbents to defend fiber laser positioning through performance differentiation and service bundling.
For Market Incumbents: Build captive service network moats by locating spare parts inventories within four-hour response zones of Stuttgart and Wolfsburg production clusters. Backward integration into fiber gain media production insulates against ytterbium supply bottlenecks while capturing upstream margin. Counter adaptive resistance welding threats by embedding AI-driven seam tracking as standard configuration rather than premium upgrade.
For New Entrants and Emerging Players: Pursue pulsed laser system penetration in medical instrument manufacturing, where FDA device regulations and sub-50-micrometer heat-affected zone requirements create specialist barriers. Target orthopedic implant welding applications in the Boston-Cambridge corridor as the most penetrable white-space segment. Establish go-to-market presence through outcome-based service contracts that guarantee uptime rather than competing on equipment price alone.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-kilowatt fiber laser architectures as automotive battery welding specifications demand redesigned optical delivery systems. Five-to-ten year viability favors suppliers with in-house source production and captive service infrastructure over pure-play system integrators. Acquire regional aftermarket specialists with established technician training programs and installed base relationships. Monitor Nadcap accreditation backlog duration as inflection indicator for aerospace segment pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Gain Media | Captive ytterbium-doped fiber production insulates against supply bottlenecks and captures upstream margin. |
| AI-Driven Seam Tracking Integration | Real-time melt-pool monitoring virtualizes quality assurance labor and differentiates against resistance welding. |
| Outcome-Based Service Contract Expansion | Uptime guarantees with penalty clauses lock in recurring revenue from German automotive OEM procurement. |
| Nadcap Accreditation Investment | Eighteen-to-twenty-four month qualification timelines create specialist barriers in aerospace nickel-alloy processing. |
| Regional Spare Parts Inventory Positioning | Four-hour response zones near Stuttgart and Wolfsburg defend service revenue against third-party competitors. |
Research Methodology
Desk research of customs trade data, SEC filings from laser source manufacturers, and EU Machinery Directive compliance documentation preceded structured interviews with plant engineers at German automotive OEMs, aftermarket service heads at Chinese system integrators, procurement managers at Yangtze River Delta contract manufacturers, and biomedical engineers at US medical device firms. Bottom-up triangulation across equipment shipment data and top-down validation through end-use industry capex surveys anchored market sizing.
Assumptions around EU Green Deal carbon border adjustment enforcement and China's dual carbon goal implementation timelines were held fixed, while automotive battery chemistry transitions and aerospace production rates were varied across sensitivity scenarios. Segmentation modeling spanned product architecture, technology mode, application requirements, and end-user procurement patterns. CAGRs derived from equipment replacement cycles, regulatory compliance deadlines, and technology substitution curves. Forecast inputs included fiber laser source production capacity utilization and Nadcap accreditation pipeline duration.
Macroeconomic conditions sit as an overlay; deviation in automotive capital expenditure cycles or rare-earth export licensing regimes would shift the trajectory. Cross-checking against IHS Markit vehicle production databases and SAMR GB standards implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Pneumatic Strippers Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market