
 Grading and Batching Systems Market | 2026-2036
Grading and Batching Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Grading and Batching Systems Market Analytics
Germany's precision manufacturing belt is tilting toward higher-capacity grading and batching assembly lines. Bühler Group leverages its Swiss-German engineering heritage to dominate high-throughput food sorting installations. STEINERT GmbH anchors its position in magnetic sensor-based batching for recycling and mining applications. TOMRA Systems ASA competes through AI-driven optical grading platforms deployed across Nordic and Central European processing plants.
Grading and batching systems sort, weigh, and group materials by physical properties using load cells, optical sensors, and programmable logic controllers with throughput rates exceeding 20 tons per hour in industrial configurations. Their primary purpose is to standardize output quality and optimize downstream process efficiency in high-volume production environments. Automated graders now capture the dominant margin pool as labor costs rise across European food processing, while electronic control technology is displacing legacy electromechanical architectures in new installations. Weight metric systems remain mature with slower replacement cycles, though calibration service contracts generate recurring revenue streams that offset hardware commoditization.
The EU Green Deal and REACH compliance frameworks mandate energy-efficient designs and recyclable component materials in new equipment placements. Germany's KBA and France's ANSM enforce divergent certification pathways for batching systems deployed in automotive-adjacent versus pharmaceutical-adjacent applications. Stakeholders must monitor how the EU AI Act's risk classification rules will reshape algorithmic grading software deployment timelines and validation requirements.
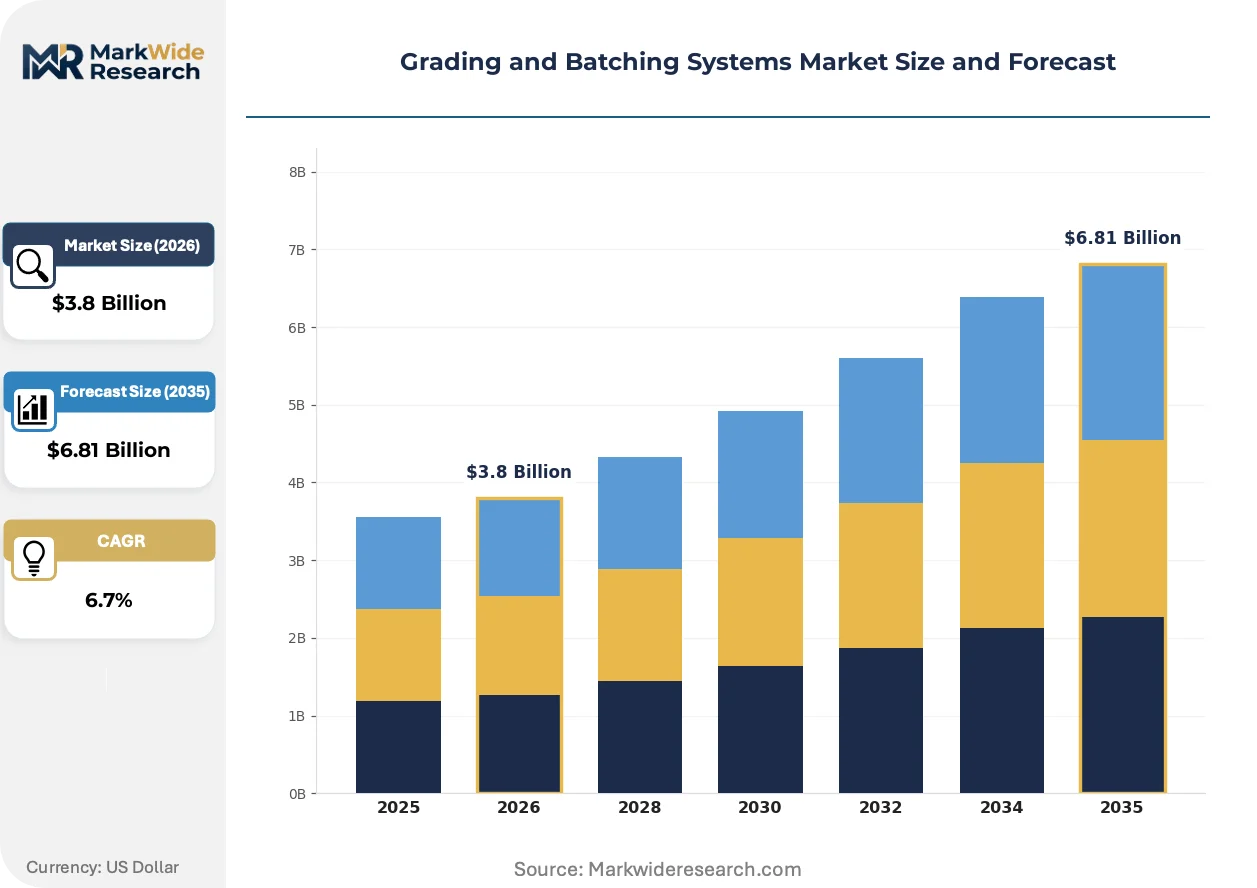
Market Dynamics
Electronic control architectures are systematically displacing legacy electromechanical systems across European food processing installations, driven by EU Green Deal energy-efficiency mandates and the operational imperative for real-time traceability compliance.
Growth Catalysts
- REACH material compliance:Manufacturers redesign component housings with recyclable polymers to satisfy ECHA substance restrictions, opening upgrade cycles across installed base.
- Optical sensor densification:AI-driven hyperspectral imaging now penetrates mid-tier dairy and meat processing lines previously served by manual inspection.
- Nuremberg-Stuttgart engineering cluster:Concentrated precision manufacturing capability accelerates prototype-to-production timelines for custom batching configurations.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin predictability for hygienic equipment fabricators serving pharmaceutical-adjacent applications.
- Load cell supplier concentration:German and Swiss sensor specialists control high-precision strain gauge supply, creating single-source vulnerability for tier-two system integrators.
- Algorithmic validation friction:EU AI Act risk classification rules delay deployment timelines for machine-learning grading software in regulated food categories.
Strategic Opportunities
- Polish and Romanian food processing:Greenfield facility construction in Central European manufacturing corridors creates demand for turnkey grading and batching lines.
- Cellular agriculture integration:Precision fermentation and cultivated protein facilities require novel batching architectures for sterile media handling.
- CE marking digitalization:Notified body streamlining of conformity assessment reduces time-to-market for modular electronic control platforms.
Industry Challenges
- Mechatronics skill scarcity:Shortage of technicians proficient in both PLC programming and mechanical calibration complicates service network expansion.
- Legacy system integration:Retrofitting 1990s-era electromechanical graders with electronic controls demands custom mechanical interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grading and Batching Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Graders, Manual Graders, Batching Scales, Weight Metric Systems Technology: Electromechanical, Hydraulic, Pneumatic, Electronic Control End User: Food Processing, Construction, Agriculture, Chemical Manufacturing Service Type: Installation, Maintenance, Calibration, Consulting |
| Companies Covered | TOMRA Systems ASA, Bühler Group, Key Technology, Satake Corporation, STEINERT GmbH, Cimbria, GEA Group, Alfa Laval, BAADER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grading and Batching Systems Market Evolving Landscape
Control system architectures, sensor modalities, and service delivery models are simultaneously transforming as energy regulations tighten and processor demands for throughput visibility intensify.
Hyperspectral imaging arrays now classify food products by chemical composition rather than surface appearance alone. Large-scale poultry and seafood processors in Denmark and the Netherlands are adopting these systems at accelerated replacement cycles. The technology is migrating from premium organic certification lines toward standard commodity grading, compressing the price premium for optical sophistication.
EU Green Deal benchmarks and F-Gas Regulation phase-down schedules are forcing refrigerant-dependent batching systems toward closed-loop thermal management. Equipment manufacturers serving frozen food processors must now engineer heat recovery into batching line designs. German KBA certification pathways for automotive-adjacent applications diverge from EFSA-aligned food safety protocols, complicating multi-sector equipment portfolios.
Service contracts are unbundling from hardware sales as processors seek predictive maintenance guarantees tied to uptime metrics. Nordic dairy cooperatives now procure grading line availability rather than capital equipment, shifting vendor revenue toward performance-based arrangements. This procurement evolution is most pronounced in Sweden and Finland, where cooperative ownership structures favor operational expenditure models.
Grading and Batching Systems Market Segmentation
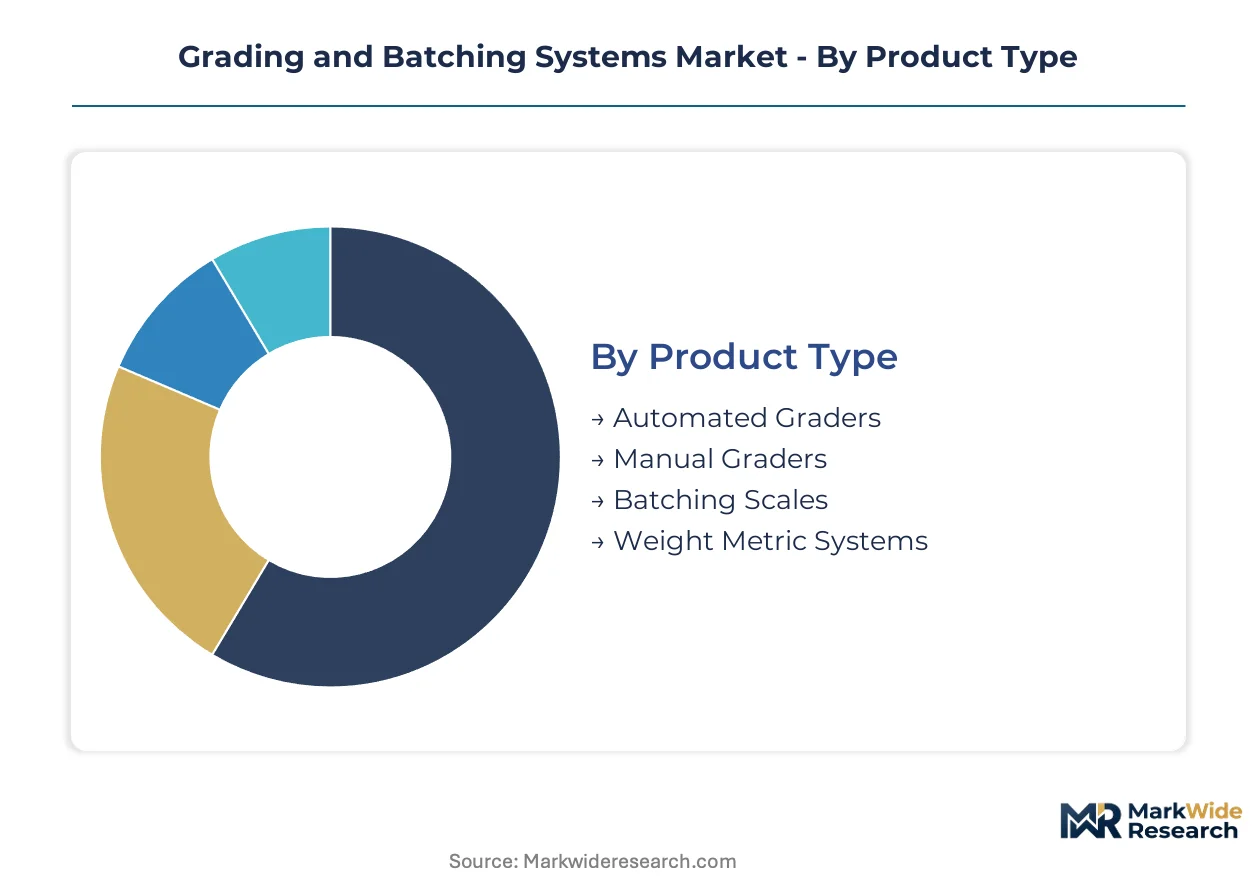
Grading and batching systems serve heterogeneous operational requirements across precision-sensitive industries. Segmentation reveals how technology choices cascade into regulatory compliance obligations and lifecycle cost structures for facility operators.
Product Type:
Cost tier differentiation separates capital-intensive automated installations from maintenance-dependent manual alternatives.
- Automated Graders:These systems integrate programmable logic controllers with optical or weight-based sensors to achieve throughput rates exceeding 20 tons per hour. Danish poultry processors and Dutch seafood cooperatives concentrate procurement here, driven by EU traceability mandates and labor cost pressures.
- Batching Scales:Load cell arrays with stainless steel platforms handle precise ingredient portioning for pharmaceutical-adjacent and food-grade applications. Germany's precision engineering corridor around Nuremberg and Stuttgart dominates fabrication, with REACH-compliant polymer housings now standard.
- Manual Graders:Operator-dependent sorting stations persist in specialty food processing where batch sizes fall below automated economic thresholds.
- Weight Metric Systems:Mature strain gauge configurations with slower replacement cycles generate recurring calibration service revenue.
Automated graders hold installed capacity. Batching scales are rotating up the share rankings.
Technology:
Application requirements dictate architecture selection, with energy efficiency and precision benchmarks driving displacement patterns.
- Electronic Control:Microprocessor-based architectures with real-time data logging satisfy EU Green Deal energy-efficiency mandates and EFSA traceability protocols. New installations across Nordic dairy processing and Central European meatpacking favor this modality.
- Electromechanical:Relay-logic and cam-driven systems persist in legacy installations where retrofit justification remains marginal.
- Pneumatic:Compressed air actuation serves explosive atmosphere applications in chemical manufacturing where electrical ignition risks are prohibitive.
- Hydraulic:High-force batching operations in construction materials handling retain this power transmission method for shear capacity.
Electronic control is climbing the fastest. Electromechanical retains residual presence in amortized infrastructure.
End User:
Volume concentration varies dramatically across sectors, with food processing commanding the dominant equipment placement rate.
- Food Processing:Dairy, meat, seafood, and bakery operations require hygienic stainless steel construction with CIP-compatible designs. Poland and Romania show expanding greenfield demand for turnkey grading lines.
- Chemical Manufacturing:Batch reactor feeding and additive dosing demand explosion-proof enclosures and ATEX certification pathways.
- Agriculture:Grain elevator and seed sorting applications prioritize throughput over precision, accepting wider tolerance bands.
- Construction:Aggregate batching for ready-mix concrete plants operates in abrasive environments with heavy-duty mechanical shielding.
Food processing anchors procurement volume. Chemical manufacturing is gaining share fastest on safety compliance spending.
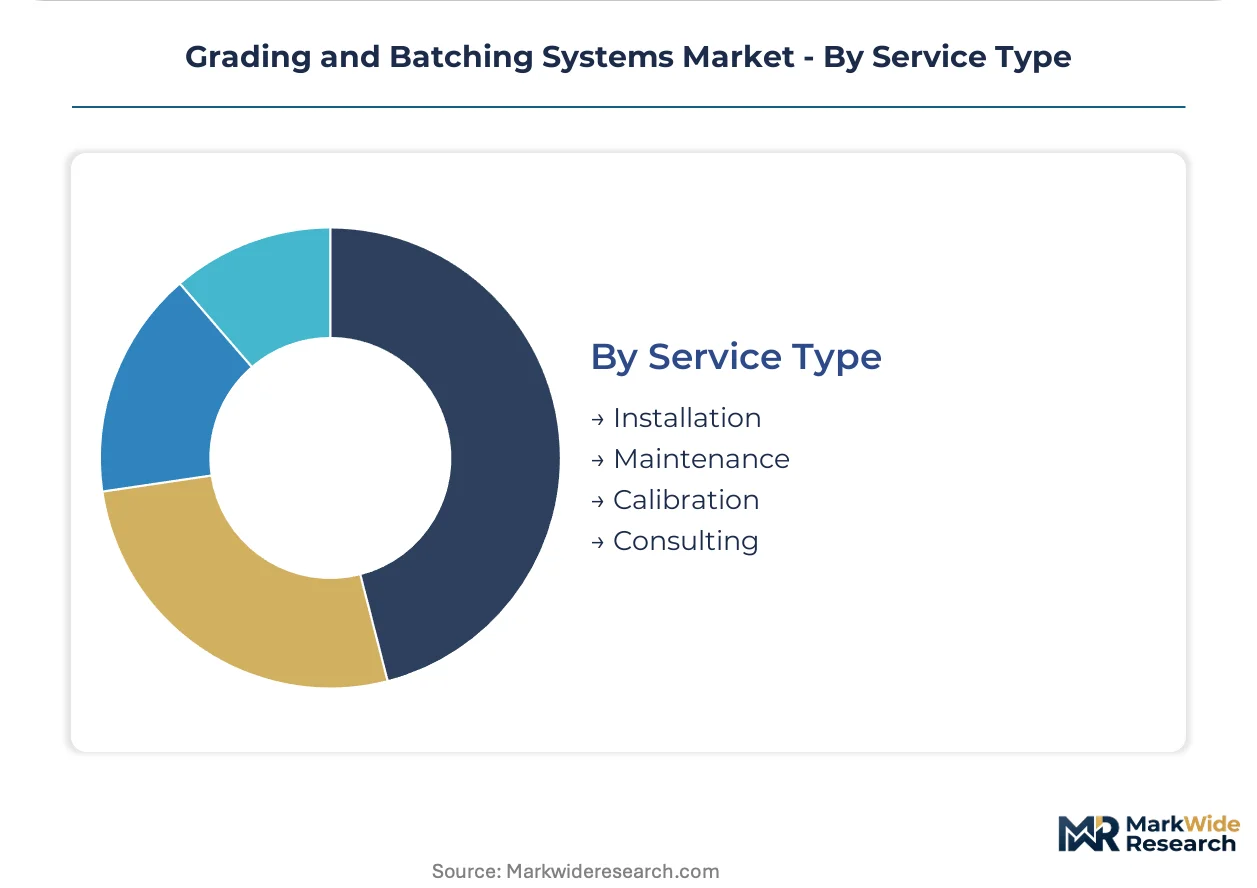
Service Type:
Customer type stratification separates capital expenditure buyers from operational expenditure adopters seeking performance guarantees.
- Maintenance:Predictive service contracts with uptime guarantees are displacing break-fix arrangements, particularly among Swedish and Finnish dairy cooperatives with cooperative ownership structures favoring opex models.
- Calibration:Accredited mass and dimension verification generates recurring revenue streams that offset hardware commoditization in weight metric systems.
- Installation:Turnkey commissioning with mechanical interface engineering addresses retrofit complexity in 1990s-era electromechanical replacements.
- Consulting:Process optimization advisory supports cellular agriculture entrants designing novel batching architectures for sterile media handling.
Maintenance holds contract value concentration. Calibration is rotating up the share rankings on regulatory audit frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA anchors the dominant geography through divergent certification pathways for automotive-adjacent versus pharmaceutical-adjacent batching systems. The EU Green Deal and REACH compliance frameworks reshape equipment placement decisions across European processing corridors.
Germany
Precision engineering clusters around Nuremberg and Stuttgart accelerate prototype-to-production timelines for custom batching configurations. KBA certification mandates diverge from EFSA-aligned food safety protocols, complicating multi-sector equipment portfolios. The Nuremberg-Stuttgart corridor concentrates high-capacity grading line fabrication serving dairy and meat processors.
France
ANSM enforces pharmaceutical-grade certification pathways distinct from food processing standards, creating specialized demand for hygienic stainless steel construction. The EU AI Act's risk classification rules delay algorithmic grading software deployment in regulated food categories. Île-de-France hosts pharmaceutical-adjacent batching system integrators serving cosmetic and nutraceutical manufacturers.
Netherlands
Large-scale poultry and seafood processors adopt hyperspectral imaging arrays at accelerated replacement cycles. F-Gas Regulation phase-down schedules force refrigerant-dependent batching systems toward closed-loop thermal management. Dutch cooperatives in the Randstad region procure grading line availability rather than capital equipment, shifting vendor revenue toward performance-based arrangements.
Poland
Greenfield facility construction in Central European manufacturing corridors creates demand for turnkey grading and batching lines. REACH material compliance mandates redesign component housings with recyclable polymers across installed base upgrade cycles. The Warsaw-Łódź industrial belt attracts German system integrators establishing service networks for food processing expansion.
Sweden
Cooperative ownership structures in Nordic dairy favor operational expenditure models with predictive maintenance guarantees. EFSA traceability protocols drive electronic control architecture adoption in new installations. Stockholm-Uppsala clusters concentrate AI-driven optical grading platform deployment across dairy processing plants.
Grading and Batching Systems Market Competitive Landscape
Precision-engineering specialists and optical-technology developers split the market into capability-differentiated tiers. Consolidation pressure concentrates around electronic control architectures displacing legacy electromechanical systems. Swiss-German engineering heritage and Nordic sensor-technology leadership define the dominant strategic archetypes. Competitive moves center on geographic expansion into Central European greenfield corridors and technology licensing for hyperspectral imaging integration.
Within the precision-engineering tier, Bühler Group and STEINERT GmbH exemplify divergent specialization strategies. Bühler Group occupies a position among Swiss-German heritage fabricators serving high-throughput food sorting installations. STEINERT GmbH anchors the magnetic sensor-based batching segment for recycling and mining applications. TOMRA Systems ASA sits within the Nordic optical-technology cluster competing through AI-driven platforms deployed across processing plants.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| Bühler Group |
| Key Technology |
| Satake Corporation |
| STEINERT GmbH |
| Cimbria |
| GEA Group |
| Alfa Laval |
| BAADER |
| Others |
Value Network & Pricing Analysis
Overcapacity in Central European fabrication facilities is compressing margin buffers for batching scale manufacturers while simultaneously accelerating payment-term concessions to secure long-lead sensor contracts. This utilization dynamic forces tier-two integrators into defensive pricing postures even as precision-engineering specialists in the Nuremberg-Stuttgart corridor maintain premium positioning through certification differentiation.
Pricing Analysis
German-manufactured electronic control systems command price spreads exceeding those of Polish-assembled equivalents by substantial margins, reflecting divergent labor cost structures and certification overhead. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked pharmaceutical-grade installations from food-processing commodity configurations. Cost compression in mid-tier optical grading stems from hyperspectral imaging module commoditization. Small-scale dairy cooperatives exhibit highest price sensitivity, while automotive-adjacent batching buyers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Extended payment terms now characterize load cell procurement from German and Swiss sensor specialists, with supply-chain finance facilities bridging cash-flow gaps for tier-two system integrators. Component fabrication concentrates in Germany, Switzerland, and Denmark, with final assembly rotating toward Poland and Romania. High-precision strain gauge supply draws from specialty metallurgy anchored in Alpine manufacturing corridors. Single-source vulnerability in optical sensor arrays creates structural exposure. Distribution runs through OEM-direct channels for large food processors and regional integrator networks for mid-tier installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from AI-driven machine vision platforms that bypass traditional mechanical grading architectures entirely. Defense requires preemptive capability acquisition and segment-specific fortification.
For Market Incumbents: Pre-empt algorithmic grading displacement by acquiring hyperspectral imaging software capabilities or licensing Nordic optical-technology platforms. Anchor high-margin service revenue through predictive maintenance contracts with Swedish and Finnish dairy cooperatives. Backward integration into load cell manufacturing mitigates supplier concentration risk in German sensor markets. For New Entrants and Emerging Players: Pursue cellular agriculture batching architectures as a white-space application with undefined vendor relationships and novel sterile-handling requirements. Target Polish and Romanian greenfield food processing corridors where incumbent service networks remain underdeveloped. Position around REACH-compliant polymer component supply as a compliance-first entry angle. For Investors and Strategic Acquirers: Capital is best deployed toward precision-engineering specialists with captive sensor technology and established pharmaceutical-grade certification pathways. Long-term viability hinges on electronic control architecture dominance displacing electromechanical legacy. Watch EU AI Act risk classification implementation timelines as the critical inflection signal for algorithmic grading software deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Captive sensor supply secures margin control against German-Swiss supplier concentration. |
| Hyperspectral Imaging Platform Licensing | Technology access accelerates competitive response to TOMRA's AI-driven optical grading deployments. |
| Predictive Maintenance Contract Unbundling | Performance-based revenue models align with Swedish-Finnish cooperative procurement preferences. |
| REACH-Compliant Polymer Component Redesign | Material compliance opens upgrade cycles across installed base in ECHA-regulated markets. |
| Cellular Agriculture Batching Architecture Development | Novel sterile media handling designs capture emerging precision fermentation facility demand. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at food processing facilities, procurement leads at dairy and meat cooperatives, aftermarket service heads at system integrators, and regulatory affairs specialists navigating EU AI Act implementation, and refined through secondary validation against ECHA substance restriction databases, KBA certification pathway documentation, EFSA traceability protocol filings, and customs records for grading equipment imports. Bottom-up equipment placement estimates were triangulated against top-down market sizing derived from precision-engineering cluster output data.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, technology architecture, end-use industry vertical, and service delivery model, with CAGRs derived from regression analysis of historical replacement cycle patterns and regulatory mandate acceleration effects. Forecast inputs included EU Green Deal energy-efficiency compliance timelines and F-Gas Regulation phase-down schedules for refrigerant-dependent batching systems.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity pricing, Central European manufacturing construction activity, or ECHA substance restriction expansion would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation velocity and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Floor Scales Market