
 Anti-Asthma Drugs Market | 2026-2036
Anti-Asthma Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Asthma Drugs Market Outlook
Biologics manufacturing capacity in Ireland and Singapore is shifting toward respiratory monoclonal antibodies as sponsors prepare for indication expansion. GlaxoSmithKline plc dominates inhaled corticosteroid-long-acting beta-agonist combinations through manufacturing scale and channel control across European and North American formularies. AstraZeneca plc differentiates its portfolio through R&D intensity in interleukin-targeted biologics for eosinophilic asthma phenotypes. Boehringer Ingelheim International GmbH anchors the nebulized maintenance segment with specialized device-drug combinations that sustain reimbursement preference in German and Japanese hospital systems.
Anti-asthma drugs comprise pharmaceutical agents engineered to reverse bronchoconstriction, suppress airway inflammation, or modulate immune-mediated disease pathways, with formulations ranging from metered-dose inhalers delivering albuterol at 90 micrograms per actuation to subcutaneous biologics dosed by patient weight and inflammatory biomarker thresholds. These products serve to reduce exacerbation frequency, improve forced expiratory volume, and enable symptom control across the asthma severity spectrum. Corticosteroids and bronchodilators occupy the largest revenue pools due to decades of generic availability and guideline-mandated first-line positioning, while monoclonal antibodies represent the fastest-expanding margin segment as payers gradually relax prior authorization barriers for phenotyped severe asthma populations. The inhalation route leads volume due to pulmonary targeting efficiency and established device ecosystems, though injectable biologics command premium pricing and are displacing chronic oral corticosteroid dependence in refractory patient cohorts.
The FDA evaluates new molecular entities for asthma through the Division of Pulmonary, Allergy, and Critical Care Products with emphasis on exacerbation reduction endpoints, while the EMA's Committee for Medicinal Products for Human Use applies stricter benefit-risk thresholds for pediatric indications and long-acting muscarinic antagonist combinations. These frameworks shape clinical trial design, label claims, and ultimately formulary placement across commercial and government payers. Stakeholders must monitor biomarker-driven patient segmentation and companion diagnostic alignment as regulators tighten evidentiary standards for phenotype-specific therapy approval.
Market Dynamics
Step-therapy protocols and prior authorization reform are restructuring how severe asthma patients access biologic therapies, concentrating purchasing power within integrated hospital networks and specialty pharmacy channels.
Growth Catalysts
- FDA Expanded Indication Pathways:Accelerated approval routes for respiratory biologics compress commercialization timelines, enabling faster patient access to phenotype-targeted monoclonal antibodies.
- Eosinophil-Driven Phenotyping:Biomarker-guided patient segmentation expands eligible populations for interleukin-targeted maintenance regimens in severe asthma cohorts.
- United States:Prior authorization reform and rising severe asthma prevalence expand reimbursement coverage for chronic monoclonal antibody therapy displacing oral corticosteroid dependence.
Market Restraints
- Biologics Manufacturing Concentration:Respiratory monoclonal antibody production clusters in Ireland and Singapore, creating single-source vulnerability for global supply continuity.
- Cold Chain Complexity:Subcutaneous biologics require continuous temperature-controlled distribution, elevating logistics costs and limiting pharmacy dispensing options.
- EMA Pediatric Benefit-Risk Thresholds:Stricter evidentiary standards for pediatric indications delay label expansion and restrict addressable patient populations in European markets.
Strategic Opportunities
- Japan:Nebulized maintenance therapy penetration remains below Western benchmarks, offering expansion potential for device-drug combination specialists.
- Companion Diagnostic Alignment:FeNO testing and eosinophil count standardization create regulatory tailwinds for phenotype-specific therapy positioning.
- Digital Inhaler Integration:Bluetooth-enabled adherence monitoring converges with telehealth platforms to enable remote patient management and outcomes-based contracting.
Industry Challenges
- Bioprocessing Talent Scarcity:Respiratory monoclonal antibody manufacturing requires specialized cell culture expertise that outpaces current workforce supply in key production hubs.
- Legacy Device Transition:Metered-dose inhaler reformulation to meet propellant regulations demands capital-intensive manufacturing line retooling without patent protection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Asthma Drugs Market |
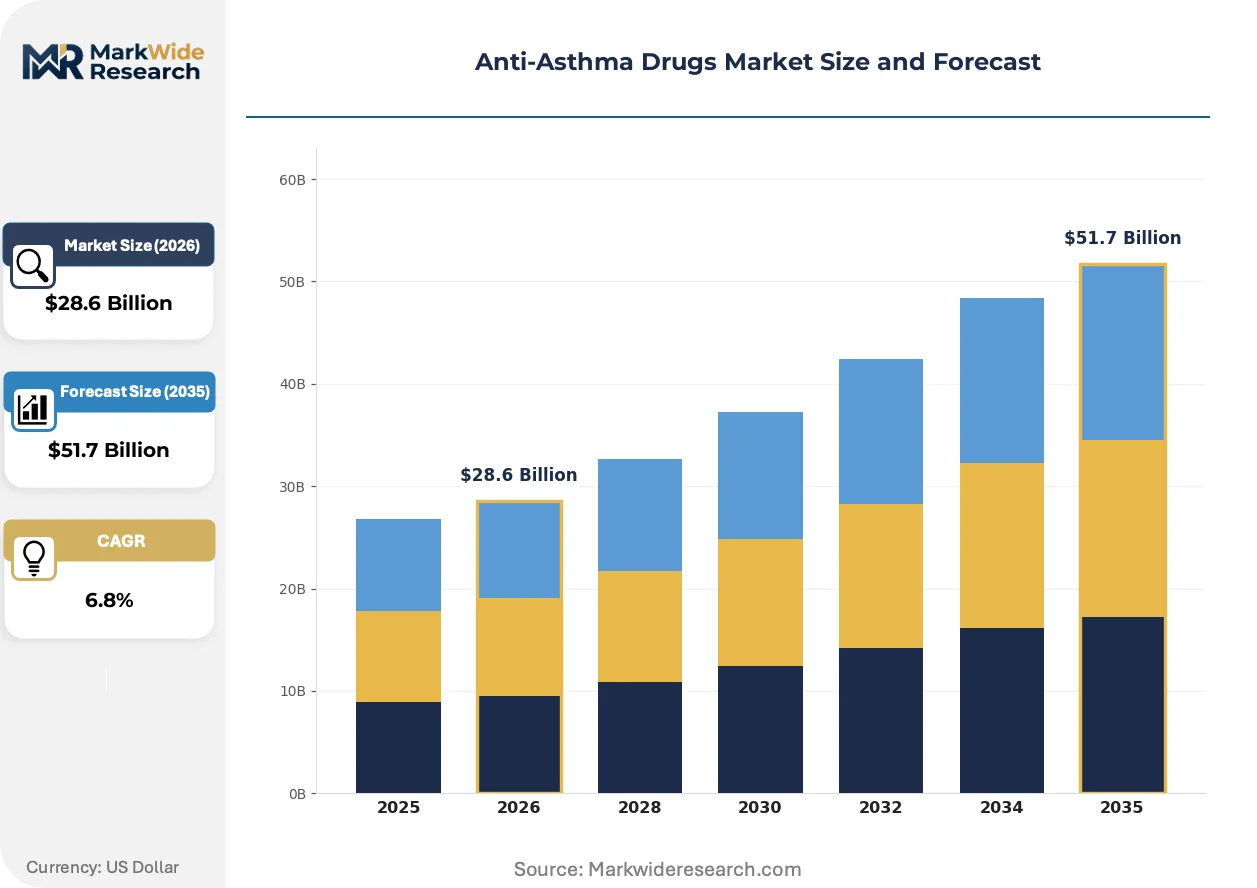
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Bronchodilators, Corticosteroids, Leukotriene Modifiers, Monoclonal Antibodies Administration Route: Inhalation, Oral, Injectable, Nebulization Patient Demographic: Adults, Pediatrics, Geriatrics, Pregnant Women Treatment Phase: Acute, Maintenance, Preventive, Rescue |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd, Novartis AG, Boehringer Ingelheim International GmbH, Sanofi, F. Hoffmann-La Roche Ltd, Chiesi Farmaceutici S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Asthma Drugs Market Strategic Shifts
Digital biomarker integration and device connectivity are transforming how adherence is monitored and reimbursed, shifting value capture toward data-enabled service models alongside molecule sales.
Smart inhalers with embedded sensors is expanding into standard-of-care protocols across United States integrated delivery networks. Pulmonology practices in Medicare Advantage plans deploy these devices to reduce emergency department utilization. The technology is expanding into risk-sharing contracts that tie manufacturer payments to documented exacerbation reduction.
REACH regulation amendments on fluorinated greenhouse gases are forcing propellant transitions in pressurized metered-dose inhalers. Hydrofluoroalkane phase-down mandates accelerate investment in dry powder and soft mist alternatives. German hospital formularies are responding with accelerated procurement timelines for propellant-free device platforms.
Hospital and specialty clinic buyers now require real-world evidence packages beyond randomized trial data for biologic therapy placement. Payers in United States commercial channels are replacing volume-based contracts with outcomes-linked agreements. This behavioral shift is most visible in asthma center networks participating in CMS innovation models.
Anti-Asthma Drugs Market Segmentation
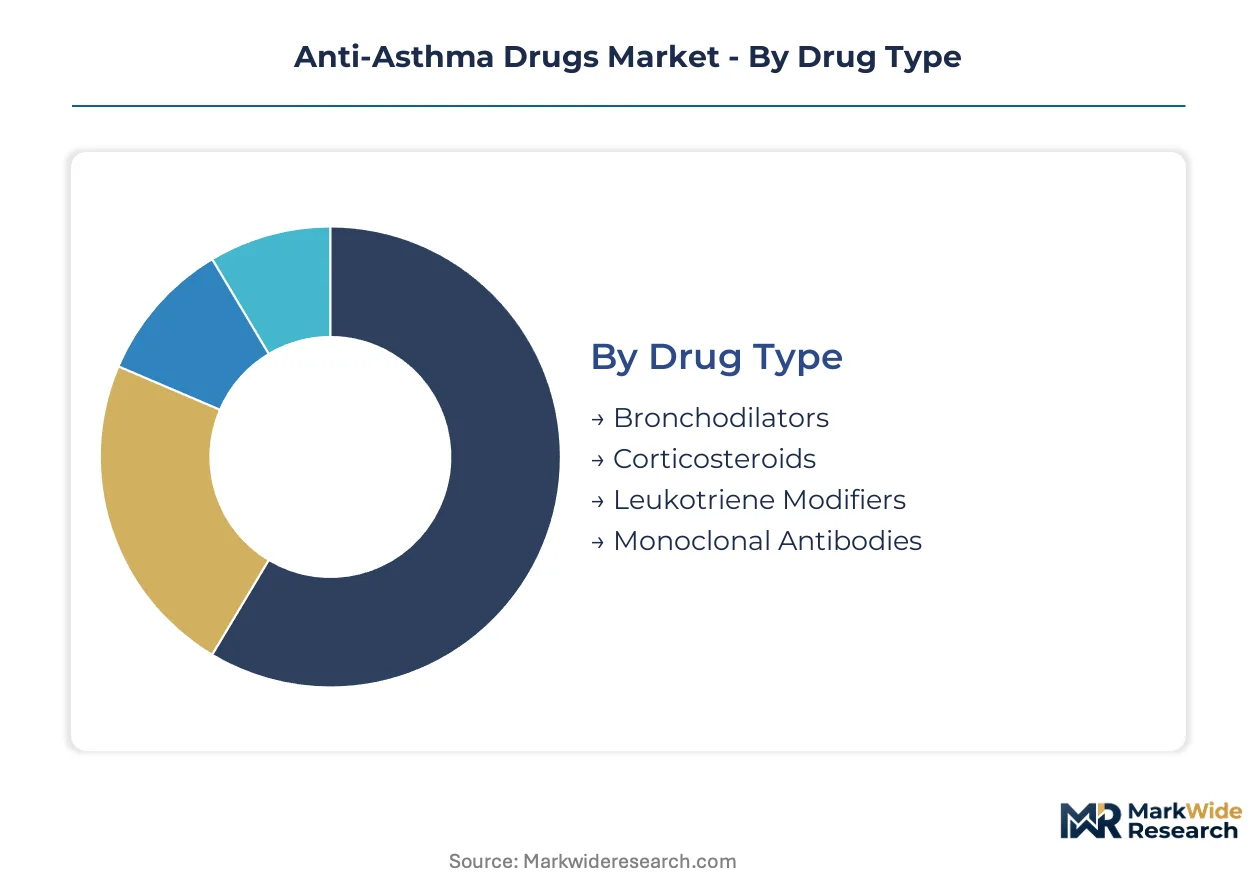
Anti-asthma drug segmentation determines reimbursement pathways, manufacturing investment, and clinical trial design. Drug type classification separates commodity corticosteroids from premium biologics with distinct margin profiles. Administration route shapes cold chain requirements and pharmacy dispensing infrastructure.
Drug Type:
Integration depth varies sharply across drug classes, with bronchodilators and corticosteroids embedded in first-line protocols while monoclonal antibodies require specialist referral and biomarker confirmation.
- Bronchodilators:Short-acting beta-agonists like albuterol deliver rapid bronchodilation through beta-2 receptor agonism at 90 micrograms per metered dose. Demand concentrates in United States emergency departments and urgent care networks where rescue medication protocols mandate immediate availability. Supply chains prioritize generic substitution to minimize out-of-pocket costs for uninsured populations.
- Corticosteroids:Inhaled formulations suppress airway inflammation through glucocorticoid receptor modulation with pulmonary-first pass metabolism reducing systemic exposure. Hospital procurement in Germany and Japan favors fixed-dose combinations with long-acting bronchodilators to simplify adherence monitoring. Fluticasone and budesonide dominate formularies through decades of safety data and generic price erosion.
- Leukotriene Modifiers:Oral tablets like montelukast block cysteinyl leukotriene receptors for aspirin-exacerbated respiratory disease and exercise-induced bronchoconstriction.
- Monoclonal Antibodies:Subcutaneous interleukin-targeted therapies including anti-IL-5 and anti-IL-4/13 agents require biomarker-driven patient selection.
Corticosteroids lead volumes today; monoclonal antibodies are gaining share fastest.
Administration Route:
Cost tier stratification separates high-volume inhalation devices from premium injectable biologics with specialized handling requirements.
- Inhalation:Dry powder and metered-dose devices deliver pulmonary targeting with 10-40% lung deposition efficiency depending on particle size and patient technique. United States Medicare Advantage plans increasingly require Bluetooth-enabled adherence tracking for prior authorization renewal. REACH F-Gas amendments are forcing hydrofluoroalkane propellant transitions that favor dry powder alternatives.
- Injectable:Subcutaneous biologics dosed by weight and eosinophil count achieve systemic cytokine blockade with quarterly to monthly dosing intervals. Specialty pharmacy channels in the United States control distribution through limited network contracts that restrict patient choice. Cold chain requirements of 2-8°C create logistics barriers for retail pharmacy dispensing.
- Oral:Systemic corticosteroids and leukotriene antagonists serve step-down therapy and corticosteroid-sparing indications.
- Nebulization:Compressor-driven aqueous aerosol generation serves pediatric and acute care settings where coordination is limited.
Inhalation dominates prescription counts; injectable routes show steepest expansion trajectory.
Patient Demographic:
Application urgency drives segmentation, with pediatric and acute populations requiring rapid-onset formulations distinct from geriatric maintenance regimens.
- Adults:Working-age patients aged 18-64 represent the largest addressable population for maintenance biologic therapy with commercial insurance coverage. United States employer-sponsored plans increasingly mandate step-therapy failure before approving monoclonal antibody access. Productivity-focused outcomes measures including absenteeism reduction are entering value-based contracts.
- Pediatrics:Children under 12 require age-appropriate device interfaces and weight-based dosing with stricter EMA benefit-risk thresholds delaying label expansion. School-based asthma management programs in the United States create demand for portable rescue inhalers with dose counters. Caregiver adherence monitoring through digital platforms is penetrating Medicaid managed care networks.
- Geriatrics:Patients over 65 with comorbid COPD require careful assessment of cardiac risks with long-acting beta-agonists.
- Pregnant Women:Inhaled corticosteroids with established safety profiles are preferred over oral systemic exposure.
Adults lead volumes today; pediatrics is gaining share fastest.
Treatment Phase:
Maturity differentiation separates decades-old rescue medications from emerging preventive biologics with novel mechanism claims.
- Maintenance:Daily controller therapy with inhaled corticosteroids or biologic monoclonal antibodies suppresses underlying inflammation and reduces exacerbation frequency. United States asthma center networks participating in CMS innovation models are adopting outcomes-linked contracts for biologic therapy. GlaxoSmithKline and AstraZeneca compete through manufacturing scale and R&D intensity respectively.
- Rescue:As-needed short-acting bronchodilators provide rapid symptom relief within minutes through smooth muscle relaxation. Generic albuterol dominates United States retail pharmacy dispensing with price points below twenty dollars per inhaler. Smart inhaler sensors are penetrating integrated delivery networks to document overuse patterns predictive of poor control.
- Acute:Systemic corticosteroids and hospital-based nebulized therapy address severe exacerbations requiring emergency intervention.
- Preventive:Pre-exercise bronchodilation and allergen immunotherapy modify disease triggers before symptom onset.
Maintenance leads volumes today; preventive approaches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing is migrating toward jurisdictions with streamlined regulatory pathways and established pharmaceutical infrastructure, creating cost-of-compliance arbitrage between established Western markets and emerging production hubs.
United States
Prior authorization reform and rising severe asthma prevalence expand reimbursement coverage for monoclonal antibody maintenance regimens. The FDA's Division of Pulmonary, Allergy, and Critical Care Products evaluates new molecular entities with emphasis on exacerbation reduction endpoints. Boston and San Diego anchor biologics R&D clusters where sponsors prepare phenotype-specific therapy filings.
Germany
Hospital procurement networks favor fixed-dose corticosteroid-bronchodilator combinations to simplify adherence monitoring across integrated care systems. The EMA's Committee for Medicinal Products for Human Use applies stricter benefit-risk thresholds for pediatric indications that delay label expansion. The Rhine-Main region concentrates nebulized device manufacturing for export to Japanese hospital systems.
Japan
Nebulized maintenance therapy penetration remains below Western benchmarks, creating expansion potential for device-drug combination specialists. METI and PMDA coordinate accelerated assessment pathways for respiratory biologics that compress commercialization timelines. The Kansai region hosts specialized manufacturing for propellant-free inhaler platforms responding to REACH F-Gas amendments.
Singapore
Biologics manufacturing capacity is shifting toward respiratory monoclonal antibodies as sponsors prepare for indication expansion across Asia-Pacific markets. The country's national pharmaceutical regulator aligns with ICH guidelines to facilitate multi-regional clinical trial acceptance. Tuas Biomedical Park anchors fill-finish operations for cold chain-dependent subcutaneous therapies.
Ireland
Respiratory monoclonal antibody production clusters create single-source vulnerability for global supply continuity despite favorable corporate tax structures. The HPRA coordinates with EMA centralized procedures for biologics manufacturing site inspections. Cork and Dublin host active pharmaceutical ingredient synthesis for interleukin-targeted therapies destined for US and European markets.
Anti-Asthma Drugs Market Competitive Environment
Established producers occupy the standard tier through decades of corticosteroid and bronchodilator manufacturing scale; emerging entrants pursue biologics specialization and digital inhaler integration. Market structure concentrates around three archetypes: diversified pharmaceutical conglomerates with respiratory portfolios, biologics-focused innovators with phenotype-targeted pipelines, and device-drug combination specialists with nebulized delivery expertise. Dominant competitive moves include strategic partnerships for companion diagnostic alignment and capacity expansion in Ireland and Singapore to secure biologics manufacturing share.
Within the diversified pharmaceutical tier, GlaxoSmithKline plc and AstraZeneca plc occupy positions reflecting distinct strategic emphases—manufacturing scale and channel control versus R&D intensity in interleukin-targeted biologics. Boehringer Ingelheim International GmbH anchors the device-drug combination specialist archetype through its GmbH structure and German origin, representing the nebulized maintenance segment's reimbursement preference in hospital systems. These three entities exemplify how competitive positioning diverges across the corticosteroid-combination, biologics-innovation, and specialized-delivery vectors.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| Sanofi |
| F. Hoffmann-La Roche Ltd |
| Chiesi Farmaceutici S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Hydrofluoroalkane propellant phase-down under REACH F-Gas amendments is simultaneously elevating dry powder inhaler manufacturing costs and concentrating active pharmaceutical ingredient synthesis in jurisdictions with established environmental compliance infrastructure. This dual compression of cost economics and supply geography is reshaping procurement negotiations between hospital formularies and device-drug combination specialists.
Pricing Analysis
Specialty pharmacy markups on subcutaneous biologics absorb cold chain logistics and prior authorization administrative costs before reaching patient out-of-pocket tiers. Three-tier pricing structure across premium biologics, standard fixed-dose combinations, and economy rescue inhalers stratifies by biomarker confirmation requirements and adherence monitoring capabilities. Cost compression in the rescue inhaler tier intensifies as generic albuterol substitution accelerates in United States retail channels. Medicaid managed care networks exhibit highest price sensitivity for maintenance therapies; commercial employer-sponsored plans show lowest sensitivity for phenotype-targeted biologics displacing oral corticosteroid dependence.
Supply Chain Analysis
Bioprocessing talent scarcity in Ireland and Singapore is constraining respiratory monoclonal antibody fill-finish capacity expansion despite favorable corporate tax structures. Active pharmaceutical ingredient synthesis draws from chemical manufacturing clusters in China and India; device assembly centers on German and Japanese precision engineering hubs. Single-source vulnerability in Cork-based interleukin-targeted therapy production creates exposure to regulatory inspection delays. Distribution runs through limited specialty pharmacy networks in the United States and hospital procurement consortia in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Anti-Asthma Drugs Market functions as a geographic-arbitrage play where biologics manufacturing investment migrates toward Ireland and Singapore to exploit favorable tax treatment and streamlined regulatory alignment, while demand capture concentrates in the United States where prior authorization reform expands reimbursement access.
For Market Incumbents: Cement biologics manufacturing scale in Ireland and Singapore before workforce scarcity hardens into binding capacity constraints. Lock in long-term device-drug combination contracts with German hospital procurement networks to defend against nebulized maintenance entrants from Japan. Prioritize companion diagnostic alignment with FeNO testing standardization to maintain phenotype-specific therapy positioning against emerging interleukin-targeted competitors. For New Entrants and Emerging Players: Specialty pharmacy limited network contracts offer the most penetrable channel layer for subcutaneous biologics seeking to bypass established corticosteroid-bronchodilator incumbents. Target Japan's underpenetrated nebulized maintenance segment where device-drug combination expertise from Western markets transfers with minimal regulatory friction. Pursue digital inhaler integration partnerships with United States Medicare Advantage plans seeking remote patient management capabilities for risk-sharing contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among device-drug combination specialists with nebulized delivery platforms and established Japanese hospital relationships. Long-term viability over the coming decade hinges on successful navigation of REACH F-Gas propellant transitions and biologics indication expansion into pediatric populations. Monitor EMA pediatric benefit-risk threshold relaxations as the critical inflection signal for addressable market expansion in European severe asthma cohorts.| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Manufacturing Scale-Up | Ireland and Singapore capacity expansion secures respiratory monoclonal antibody supply continuity for phenotype-targeted therapy launches. |
| Companion Diagnostic Alignment | FeNO testing and eosinophil count standardization creates regulatory tailwinds for interleukin-targeted maintenance regimen positioning. |
| Digital Inhaler Integration | Bluetooth-enabled adherence monitoring converges with United States Medicare Advantage telehealth platforms for outcomes-based contracting. |
| Propellant-Free Device Transition | Dry powder and soft mist platform investment responds to REACH F-Gas hydrofluoroalkane phase-down mandates in European markets. |
| Specialty Pharmacy Network Partnership | Limited distribution contracts in the United States control patient access and protect biologic therapy margins from retail pharmacy substitution. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers contributed perspective through structured interviews. Secondary sources include FDA filings, EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, and United States commercial formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored segmentation-level projections.
Granularity-level modeling distinguished drug type, administration route, patient demographic, and treatment phase dimensions at the country-regulatory cluster level. CAGRs were derived through patient flow analysis, pricing trajectory assessment, and reimbursement policy scenario testing across the projection horizon. Forecast inputs incorporated severe asthma prevalence trends, step-therapy protocol evolution, and biologics manufacturing capacity expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA pediatric indication approvals, REACH F-Gas amendment implementation pace, and United States prior authorization reform depth. Projections reflect assumptions regarding biomarker testing standardization and specialty pharmacy channel consolidation. Material deviation in regulatory approval timelines or biologics manufacturing site inspection outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
Aspirin API Market
Pharmacology
Semaglutide API Market
Pharmacology
Cough Remedies Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Drug Eruptions Treatment Market