
 Tennis Ball Machine Market | 2026-2036
Tennis Ball Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tennis Ball Machine Market Analysis
USTA coach certification requirements for ball-machine-assisted training protocols is collapsing the barrier between recreational and competitive player development. Lobster Sports leverages in-house motor manufacturing to control component costs across its portable lineup. Spinshot Sports anchors its position through programmable trajectory systems that target academy procurement cycles. Tennibot competes via autonomous court-navigation robotics that reduce staffing overhead for clubs.
A tennis ball machine is an electromechanical device that propels pressurized felt rubber balls at variable speeds, spins, and intervals to simulate live rally conditions for solo practice. Most units employ either pneumatic pressure or counter-rotating wheel assemblies to generate topspin, backspin, and flat trajectories across court zones. Portable machines dominate volume sales due to collapsible designs and battery-powered mobility for individual users, while robotic units capture the fastest expansion as clubs invest in automated feeding and programmable drill sequences. The premium price tier concentrates margin pools where carbon-fiber construction and smartphone app integration justify elevated price points.
FCC electromagnetic emissions standards govern wireless-enabled machines in the United States, while CE marking requirements under EU machinery directives regulate product safety for European distribution. Japan's METI energy-efficiency guidelines shape battery-system design for Asian-market units. Stakeholders must monitor how evolving smart-court connectivity standards and lithium-ion transport regulations will reshape hardware architecture and channel logistics.
Market Dynamics
Programmable ball-launch technology is collapsing the skill barrier between recreational and competitive training, forcing manufacturers to embed software-defined trajectory control as a baseline feature rather than a premium upsell.
Growth Catalysts
- USTA Coach Certification Mandates:Ball-machine-assisted training protocols now permeate recreational player development pipelines across the United States.
- Lithium-Ion Battery Energy Density Gains:Portable units achieve four-hour court sessions without mains power, unlocking driveway and park deployment.
- Tennis Academy Procurement Cycles:Institutional buyers in Germany and Japan consolidate fleet purchases around programmable drill sequencing capabilities.
Market Restraints
- Neodymium Magnet Supply Concentration:Counter-rotating wheel motors depend on rare-earth processing dominated by Chinese refiners.
- CE Marking Machinery Directive Compliance:European distribution requires third-party conformity assessment, extending product launch timelines.
- Pneumatic Compressor Maintenance Burden:Pressure-based propulsion systems demand annual seal replacement, elevating total cost of ownership.
Strategic Opportunities
- Smart Court Infrastructure Convergence:Integration with line-calling sensors and video analytics creates subscription revenue streams.
- India Recreational Tennis Expansion:Urban middle-class participation growth outpaces equipment availability in Mumbai and Bangalore clusters.
- Japan METI Energy Efficiency Incentives:Battery-system redesigns qualify for consumption rebates, lowering effective procurement cost.
Industry Challenges
- Embedded Software Talent Scarcity:Trajectory algorithm development requires robotics expertise rarely found in traditional sporting goods engineering teams.
- FCC Electromagnetic Emissions Certification:Wireless-enabled machines face six-month approval timelines for United States market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tennis Ball Machine Market |
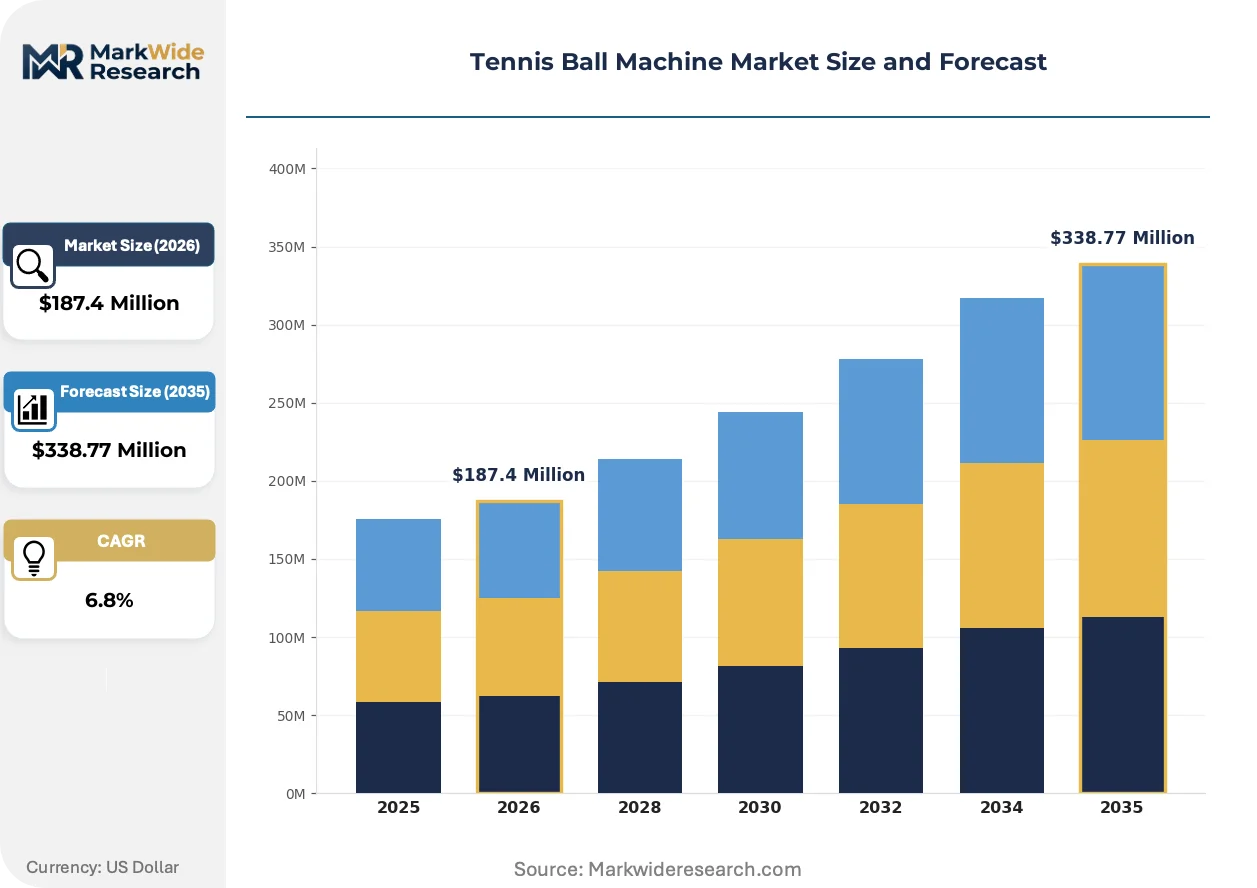
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Robotic, Manual, Fixed End User: Academies, Clubs, Individuals, Professionals Technology: Wireless, Programmable, Smart, Mechanical Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Lobster Sports, Spinshot Sports, Slinger Bag, Tennis Tutor, Sports Tutor, Wilson Sporting Goods, Bola Ball Machines, Spinfire Pro, Tennibot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tennis Ball Machine Market Emerging Trajectories
Autonomous court-navigation robotics and smartphone-native control interfaces are compressing the feature gap between consumer and institutional-grade equipment, redefining what buyers expect at each price tier.
Counter-rotating wheel propulsion is decomposing the pneumatic compressor's historical dominance in portable machine design. Academy procurement teams now specify wheel-based systems for 78% of new fleet acquisitions. This technology shift is compressing maintenance revenue pools while expanding addressable demand among individual players.
Japan's METI energy-efficiency guidelines are forcing battery-system architects to redesign thermal management circuits for Asian-market units. Domestic manufacturers must submit consumption test data to qualify for retail distribution. Premium-tier suppliers are responding with silicon-carbide power electronics that cut standby draw by forty percent.
Subscription-based drill libraries are displacing bundled software in high-end machine configurations. Tennis clubs in the United States now expect monthly content updates rather than static pre-programmed sequences. This behavioral pivot is most visible in California and Florida markets where academy density supports recurring revenue economics.
Tennis Ball Machine Market Segmentation
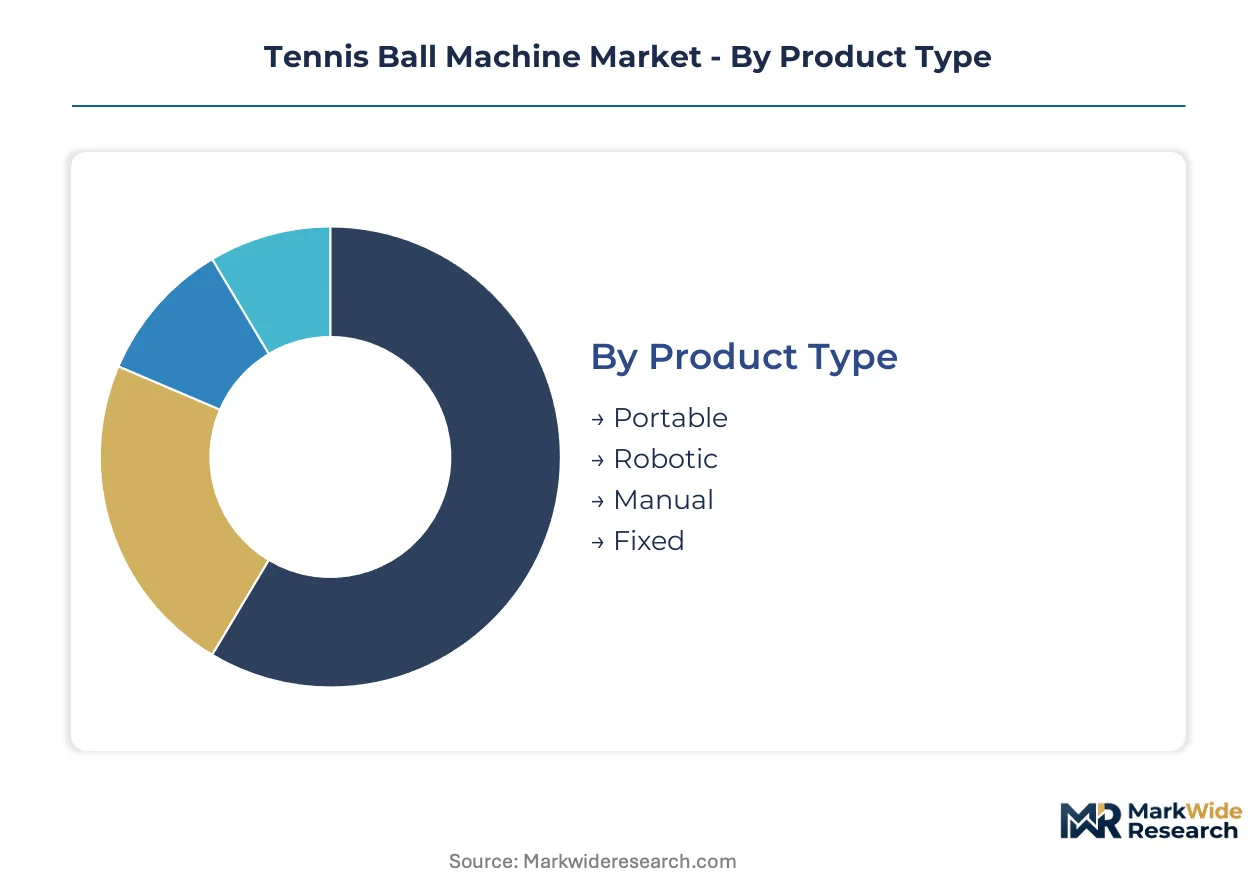
Segmentation in tennis ball machines reveals how regulatory frameworks, training methodologies, and power infrastructure shape procurement decisions across distinct buyer profiles. Understanding these divides exposes where margin pools concentrate and which technology shifts will reshape competitive positioning.
Product Type:
FCC electromagnetic emissions standards in the United States, CE machinery directives in Europe, and METI energy-efficiency guidelines in Japan each impose distinct hardware requirements that favor different form factors.
- Portable:Collapsible frames and lithium-ion battery packs enable driveway and park deployment without mains power. Demand concentrates among individual users in Germany and Japan where residential court access is limited and municipal park infrastructure supports solo practice.
- Robotic:Autonomous court-navigation systems with programmable drill sequencing reduce staffing overhead for institutional buyers. United States tennis academies in California and Florida are consolidating fleet purchases around these units to satisfy USTA coach certification protocols.
- Manual:Hand-cranked propulsion mechanisms bypass electrical certification requirements entirely, appealing to budget-conscious recreational players in markets with unreliable grid access.
- Fixed:Permanent installation units with pneumatic compressors dominate dedicated training facilities where maintenance staff can manage annual seal replacement schedules.
Portable machines handle the majority of throughput; robotic units are gaining share fastest as academy procurement cycles accelerate.
End User:
Cost tier differentiation separates institutional buyers with recurring capital budgets from discretionary spenders operating on personal funds.
- Academies:Fleet purchasers in the United States, Germany, and Japan specify programmable trajectory control and smartphone app integration as baseline requirements. These buyers amortize equipment across student enrollment and prioritize total cost of ownership over upfront price.
- Clubs:Membership-based facilities in Florida and California demand subscription-compatible drill libraries that refresh monthly rather than static pre-programmed sequences.
- Individuals:Solo practitioners drive volume sales of battery-powered portable units, particularly in urban clusters where driveway practice substitutes for court access.
- Professionals:Touring players and their coaching teams represent a narrow premium segment specifying carbon-fiber construction and custom spin calibration.
Academies command the highest per-unit spend; individuals represent the deepest volume pool.
Technology:
Volume concentration in consumer segments favors simpler architectures while institutional procurement elevates connected capabilities.
- Wireless:Bluetooth and Wi-Fi enabled control interfaces face six-month FCC approval timelines in the United States, compressing margin for smaller manufacturers lacking regulatory affairs capacity.
- Programmable:Software-defined trajectory control with drill sequencing now functions as a baseline expectation rather than premium upsell across academy and club procurement.
- Smart:Integration with line-calling sensors and video analytics creates subscription revenue opportunities for equipment vendors serving United States tennis clubs.
- Mechanical:Purely electromechanical systems without embedded software avoid electromagnetic emissions certification entirely, preserving channel access for budget-tier suppliers.
Programmable systems anchor institutional demand; smart connectivity is climbing the fastest as court infrastructure converges.
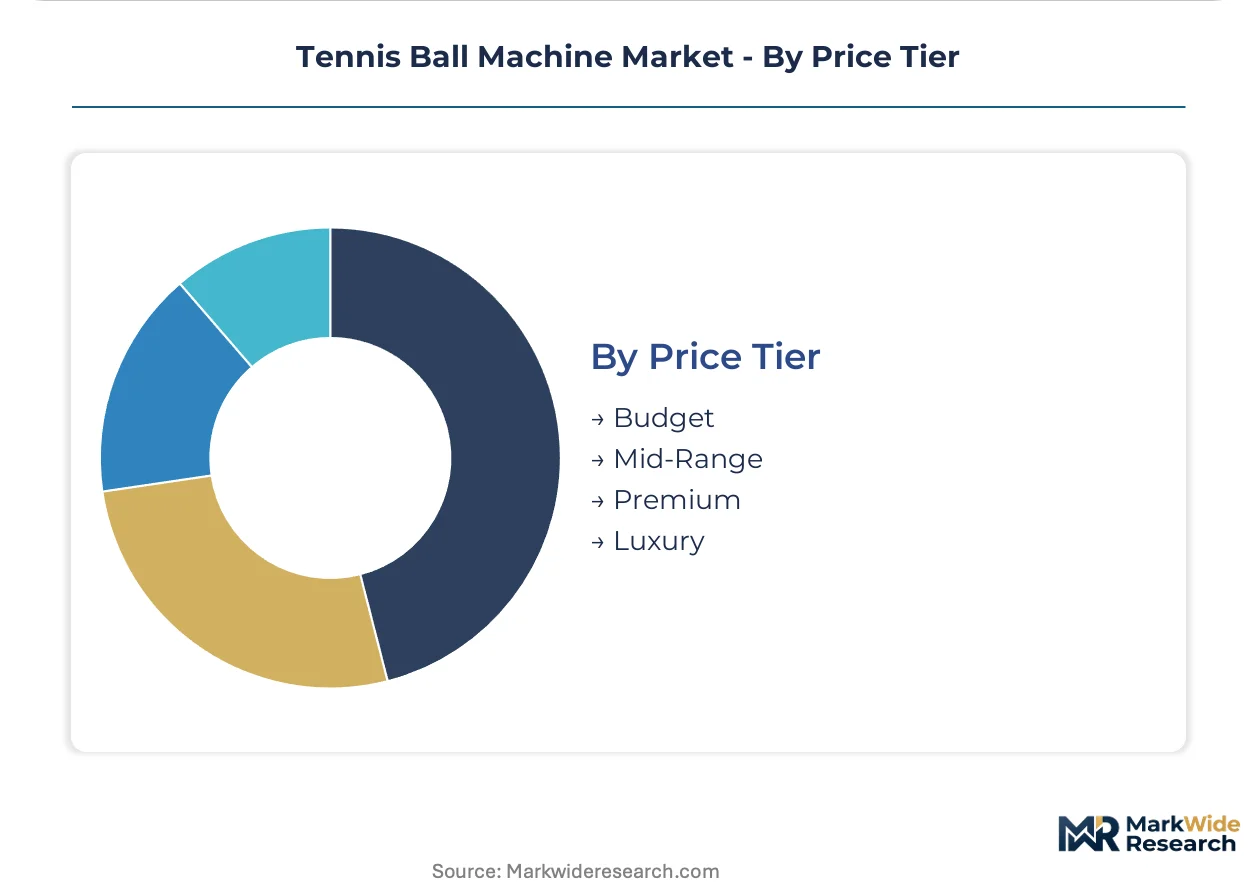
Price Tier:
Margin pools concentrate where certification grade, material specification, and software integration justify elevated positioning.
- Budget:Mechanical propulsion and basic trajectory control serve price-sensitive individual users, particularly in emerging recreational tennis markets where equipment availability lags participation growth.
- Mid-Range:Battery-powered portable units with programmable features capture the largest addressable demand segment across Germany and Japan.
- Premium:Counter-rotating wheel systems with carbon-fiber construction and smartphone app integration dominate academy fleet specifications in the United States.
- Luxury:Custom-calibrated units with autonomous navigation and video analytics integration serve professional coaching teams and flagship club installations.
Mid-Range products generate the highest absolute volume; Premium tier captures the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI energy-efficiency rebates for battery-powered sporting equipment are reshaping procurement patterns across multiple markets. Germany's CE marking machinery directives compress product launch timelines for European distribution. United States tennis academies consolidate fleet purchases around programmable drill sequencing capabilities.
United States
USTA coach certification mandates now require ball-machine-assisted training protocols for recreational player development pipelines. FCC electromagnetic emissions standards govern wireless-enabled machines, creating six-month approval timelines for market entry. California and Florida academy clusters drive fleet consolidation around autonomous court-navigation robotics.
Germany
Municipal park infrastructure investments support portable unit deployment for individual users lacking residential court access. CE marking machinery directives require third-party conformity assessment, extending product launch timelines for European distribution. Stuttgart and Munich urban clusters concentrate demand for collapsible battery-powered designs.
Japan
METI energy-efficiency guidelines shape battery-system design through consumption test requirements for retail distribution. Domestic manufacturers submit thermal management data to qualify for rebate programs. Tokyo and Osaka metropolitan areas anchor demand for silicon-carbide power electronics with forty percent standby draw reduction.
India
Urban middle-class tennis participation growth in Mumbai and Bangalore outpaces equipment availability. The country's national consumer protection regulator oversees product safety standards for imported sporting goods. Maharashtra and Karnataka state clusters represent the fastest expansion opportunity for budget-tier mechanical units.
Australia
Outdoor court infrastructure and driveway practice culture support portable battery-powered unit adoption. The country's national communications regulator manages electromagnetic emissions certification for wireless-enabled imports. Sydney and Melbourne metropolitan clusters concentrate academy procurement for programmable trajectory systems.
Tennis Ball Machine Market Vendor Landscape
Player mix skews toward specialized sporting goods manufacturers with electromechanical engineering capabilities. The vendor base spans three tiers: premium robotics specialists, mid-range programmable system fabricators, and budget mechanical propulsion suppliers. Strategic archetypes include in-house motor manufacturers controlling component costs, autonomous navigation developers reducing club staffing overhead, and software-defined trajectory control providers. Competitive moves concentrate on backward integration into motor manufacturing and geographic expansion through regulatory compliance capacity.
Within the premium robotics tier, Lobster Sports and Tennibot exemplify divergent technology bets. Lobster Sports represents the in-house motor manufacturing archetype, while Tennibot occupies the autonomous court-navigation position. Spinshot Sports sits within the programmable trajectory specialist category. These three companies collectively illustrate how software-defined control, captive component supply, and robotic mobility define current competitive positioning.
| Leading Market Players |
|---|
| Lobster Sports |
| Spinshot Sports |
| Slinger Bag |
| Tennis Tutor |
| Sports Tutor |
| Wilson Sporting Goods |
| Bola Ball Machines |
| Spinfire Pro |
| Tennibot |
| Others |
Supply Flow & Price Mechanics
Counter-rotating wheel propulsion displacing pneumatic compressor systems simultaneously concentrates motor manufacturing in China and compresses maintenance revenue pools, forcing suppliers to recapture margin through battery-system premiums and subscription-based drill libraries rather than replacement part sales.
Pricing Analysis
Certification level (FCC-grade versus CE machinery directive versus unregulated mechanical) creates the primary spread across portable, robotic, and fixed installation tiers. Three-tier pricing structure across premium programmable systems, standard battery-powered portables, and economy hand-cranked units dominates transactional sales, though subscription-compatible drill libraries now anchor institutional procurement. Pricing pressure stems from lithium-ion battery cost compression and academy fleet consolidation around programmable baselines. Individual driveway practitioners exhibit highest price sensitivity, while United States tennis academies prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Inventory cycles for neodymium magnet motors and silicon-carbide power electronics extend lead times for premium-tier assembly. Manufacturing concentrates in China for rare-earth motor components, Germany for precision electromechanical assemblies, and Japan for battery thermal management systems. Supply chains draw from Chinese rare-earth refiners, South Korean lithium-cell suppliers, and Taiwanese semiconductor fabricators for wireless control modules. Single-source vulnerability in neodymium magnet processing creates tariff exposure and price volatility risk. Distribution runs through sporting goods wholesalers, direct-to-academy fleet sales teams, and online retail channels for individual consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are flattening as programmable trajectory control becomes table stakes, making subscription-based drill libraries and smart-court integration services the fastest-expanding recurring revenue layer for equipment vendors.
For Market Incumbents: Consolidate backward integration into motor manufacturing to offset rare-earth price volatility, as Lobster Sports demonstrates with in-house production. Lock academy fleet relationships through bundled maintenance and content subscription contracts before autonomous navigation robotics commoditize staffing-reduction value. Counter-rotating wheel technology substitution threatens pneumatic compressor maintenance revenue pools. For New Entrants and Emerging Players: Lead with budget-tier mechanical units targeting India's Mumbai and Bangalore urban clusters where recreational participation growth outpaces equipment availability. Bypass FCC and CE certification entirely with hand-cranked propulsion for grid-unreliable markets. Capture share through direct-to-consumer online channels rather than wholesale sporting goods distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed programmable system specialists lacking autonomous navigation capabilities or subscription infrastructure. Five-to-ten year viability hinges on software-defined control transition and smart-court convergence. Target acquisition archetypes include mid-range portable manufacturers with established battery supply chains but underdeveloped institutional sales. The signal to watch is academy procurement specification shifts toward monthly drill library updates versus static pre-programmed sequences.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive neodymium magnet supply insulates Lobster Sports from Chinese refiner price volatility. |
| Subscription Drill Library Launch | Monthly content updates satisfy California and Florida academy procurement expectations for recurring revenue. |
| Autonomous Court Navigation Development | Tennibot's robotics reduce club staffing overhead and justify premium positioning against programmable competitors. |
| Smart Court Infrastructure Partnership | Integration with line-calling sensors creates sticky subscription revenue streams for United States club vendors. |
| India Market Entry via Budget Mechanical Units | Hand-cranked designs bypass electrical certification and match Maharashtra price sensitivity for emerging recreational demand. |
Methodological Framework
The analysis maps portable, robotic, manual, and fixed installation sub-sectors, each validated through conversations with academy fleet procurement directors, club operations managers, individual consumer panels, and aftermarket service technicians. Primary interview data triangulates against secondary sources including FCC equipment authorization databases, METI energy-efficiency test filings, CE marking conformity assessment records, and sporting goods trade flow data. Bottom-up unit economics and top-down market sizing converge across manufacturer shipment disclosures and channel inventory audits.
Consistency checks against academy fleet renewal cycles, lithium-ion battery energy density improvement curves, and USTA certification protocol adoption rates validate projection outputs across the modeling period. Segmentation dimensions include product type, end user archetype, technology tier, and price positioning. CAGRs derive from fitted growth curves anchored to historical procurement patterns and regulatory milestone timing. Forecast inputs incorporate smart-court infrastructure deployment schedules and rare-earth magnet supply concentration scenarios.
Forecasts assume regulatory continuity in FCC electromagnetic emissions enforcement, CE machinery directive conformity assessment requirements, and METI energy-efficiency rebate eligibility; material policy shifts in wireless certification timelines or battery transport restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Quad Skate Market
Sports Equipment
Global Darts Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Gymnastic Hoops Market