
 Turbo Trainer Market | 2026-2036
Turbo Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Turbo Trainer Market Outlook
Home users are unwinding the historical dominance of fitness centers in turbo trainer procurement. Wahoo Fitness leverages its app ecosystem to anchor premium positioning. Garmin/Tacx dominates direct-drive smart trainer engineering through its cycling electronics heritage. Elite specializes in fluid resistance systems for competitive cyclists seeking road-like feel.
A turbo trainer is a stationary cycling device that enables riders to pedal a bicycle in place, typically employing magnetic, fluid, direct-drive, or air resistance mechanisms to simulate road conditions and measure power output in watts. Smart trainers integrate Bluetooth and ANT+ connectivity to transmit cadence, power, and speed data to training software platforms. Smart trainers command the highest margin pools due to software subscription attach rates, while classic trainers retain volume leadership in emerging markets where price sensitivity prevails. Direct-drive technology is displacing wheel-on designs among serious cyclists seeking accuracy and reduced tire wear.
ISO standards for fitness equipment safety, FCC electromagnetic emissions rules for wireless connectivity modules, and EU CE marking requirements for electrical devices collectively shape product compliance burdens and market access thresholds. The EU's RoHS and REACH frameworks restrict hazardous substances in electronics and coatings, forcing material substitutions in resistance unit manufacturing. Stakeholders must monitor how evolving cybersecurity standards for connected fitness devices reshape firmware development priorities and liability exposure.
Market Dynamics
The transition from wheel-on to direct-drive resistance architecture is compressing R&D cycles and redrawing competitive boundaries as accuracy demands from competitive cyclists escalate.
Growth Catalysts
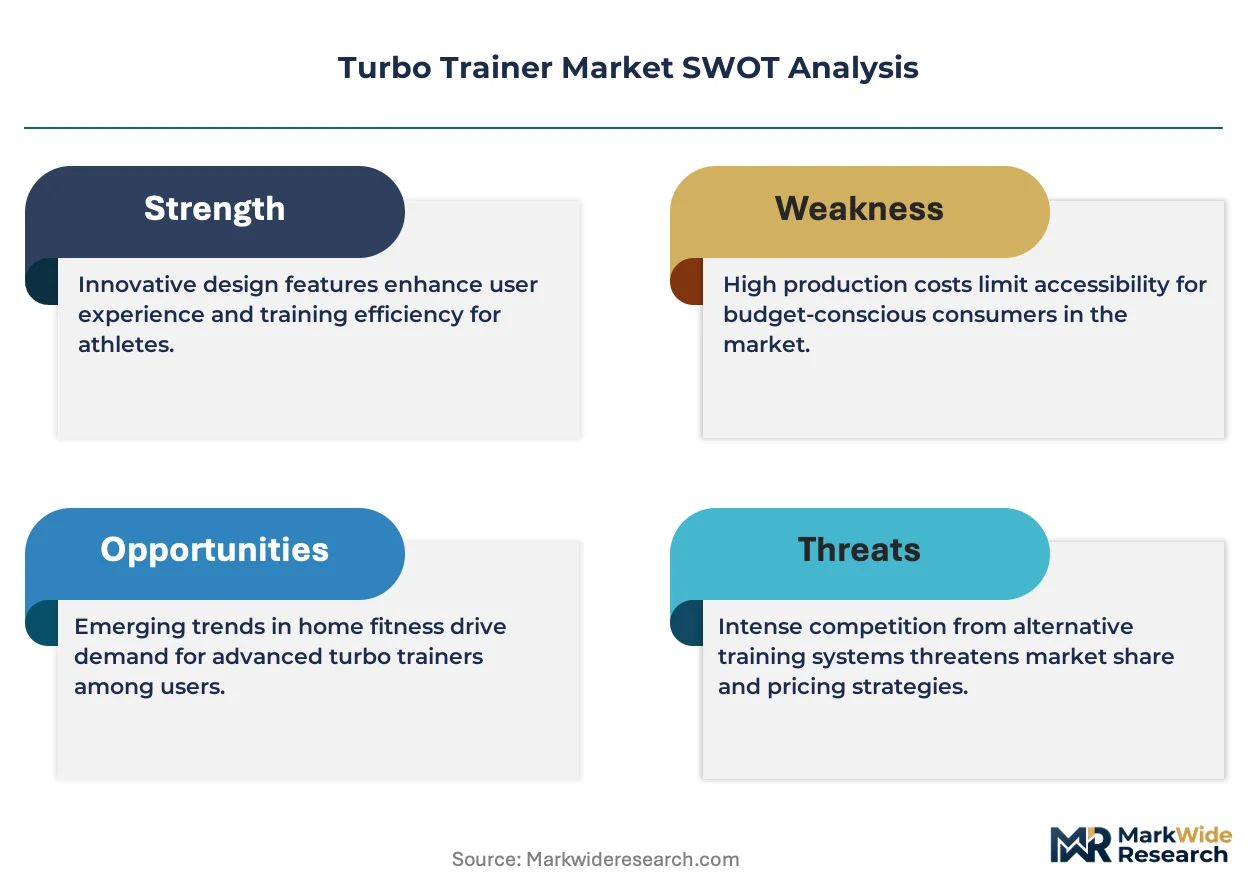
- Bluetooth and ANT+ protocol standardization:Wireless connectivity mandates from FCC and EU CE marking frameworks have unified data transmission specifications, reducing firmware fragmentation and accelerating third-party software integration.
- Home fitness infrastructure investment:Residential basement and garage conversions into dedicated training spaces are driving permanent-installation trainer purchases among recreational cyclists in Germany and Japan.
- Power meter accuracy requirements:Competitive cycling federations' calibration standards are forcing manufacturers to adopt strain-gauge and electromagnetic resistance technologies that meet ±1% precision thresholds.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing facilities creates input cost volatility and geopolitical exposure for resistance unit manufacturers.
- EU RoHS and REACH compliance burdens:Hazardous substance restrictions in electronics and coatings force material substitutions that extend qualification timelines and raise per-unit certification costs.
- Stationary bike substitution threat:All-in-one smart bikes from Peloton and NordicTrack capture price-sensitive consumers seeking zero-setup convenience, eroding entry-level turbo trainer volume.
Strategic Opportunities
- India's emerging cycling culture:BIS certification alignment and urban middle-class fitness adoption create whitespace for mid-tier wheel-on trainers before direct-drive saturation sets in.
- Software subscription bundling:Zwift, TrainerRoad, and Rouvy platform partnerships enable recurring revenue attachment that offsets hardware margin compression in mature markets.
- Commercial gym retrofit cycles:Boutique cycling studios in the United States are replacing static spin bikes with smart trainer bays that enable virtual racing and power-based class structures.
Industry Challenges
- Firmware cybersecurity certification:Connected fitness device standards from ISO and emerging national frameworks are forcing engineering teams to rebuild wireless stacks for encrypted transmission compliance.
- Legacy inventory obsolescence:Rapid direct-drive adoption leaves wheel-on trainer stock stranded in distribution channels, requiring aggressive discounting that erodes brand positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbo Trainer Market |
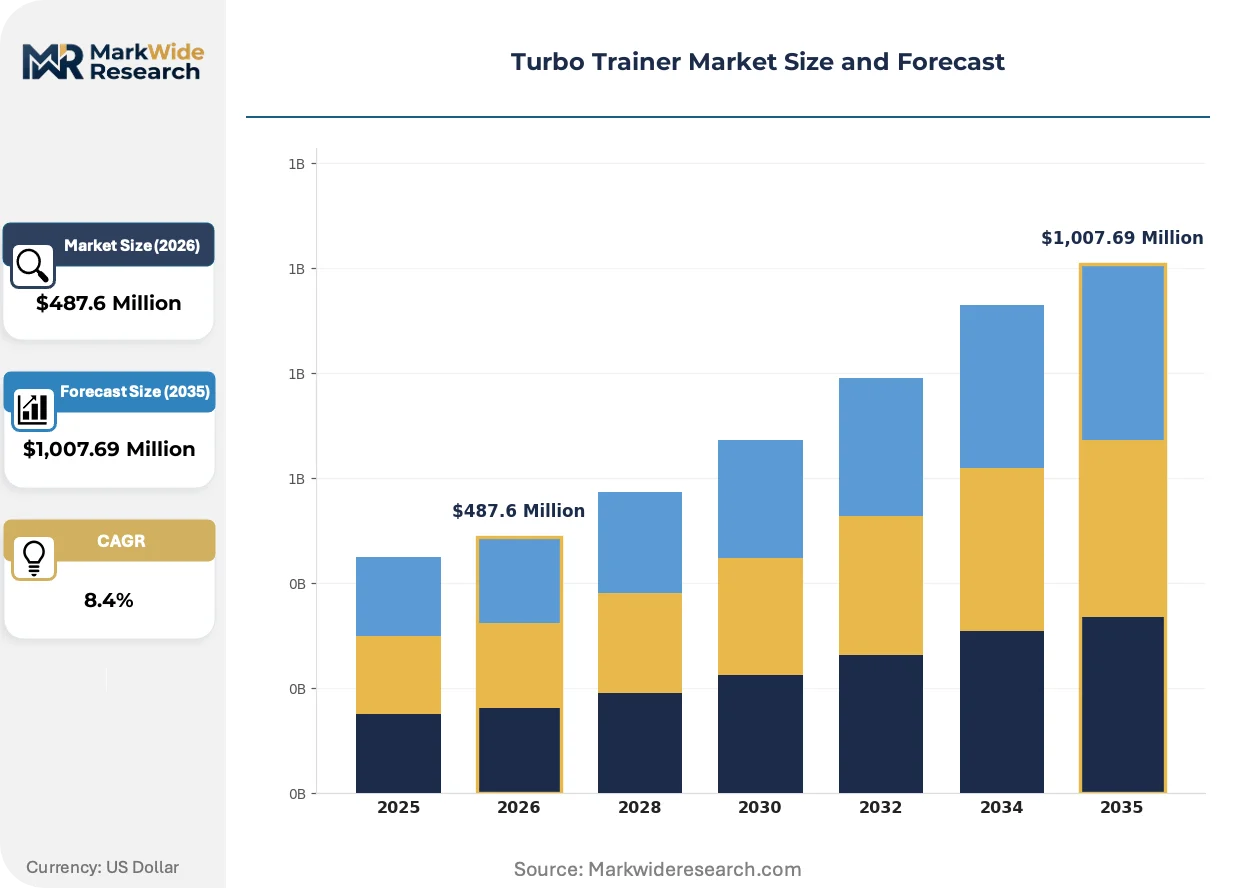
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Trainers, Classic Trainers, Rollers, Portable Trainers End User: Cycling Enthusiasts, Fitness Centers, Professional Athletes, Home Users Technology: Magnetic Resistance, Fluid Resistance, Direct Drive, Air Resistance Connectivity: Bluetooth, ANT+, Wired, Wi-Fi |
| Companies Covered | Wahoo Fitness, Garmin/Tacx, Elite, Saris, JetBlack Cycling, Minoura, Kurt Kinetic, Technogym, Stages Cycling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbo Trainer Market Strategic Shifts
Connected training ecosystems are collapsing the boundary between hardware specifications and software experience, forcing manufacturers to compete on data integration depth rather than mechanical performance alone.
Direct-drive electromagnetic resistance is bifurcating the product landscape into studio-grade precision units and consumer-accessible price tiers. Competitive cyclists and professional teams in Belgium and the Netherlands are adopting high-torque, low-inertia designs that replicate alpine gradient feel. This technology is bifurcating margin pools: premium segments capture software subscription attach rates while entry-tier products face commoditization pressure from Asian contract manufacturers.
EU cybersecurity requirements for connected fitness devices are mandating encrypted firmware updates and user data protection protocols under evolving CE marking interpretations. Manufacturers serving European markets must re-engineer wireless transmission modules to satisfy both electromagnetic emissions standards and privacy frameworks. German and French regulatory bodies are enforcing these provisions most stringently, delaying product launches for non-compliant vendors.
Virtual racing platform integration now determines purchase decisions ahead of hardware specifications for recreational buyers. Specialty cycling retailers in the United States are unbundling after-sales support into subscription-based calibration and maintenance packages. This behavioral shift is most visible among Zwift and TrainerRoad subscribers aged 35-55, who prioritize seamless software onboarding over resistance mechanism comparisons.
Turbo Trainer Market Segmentation
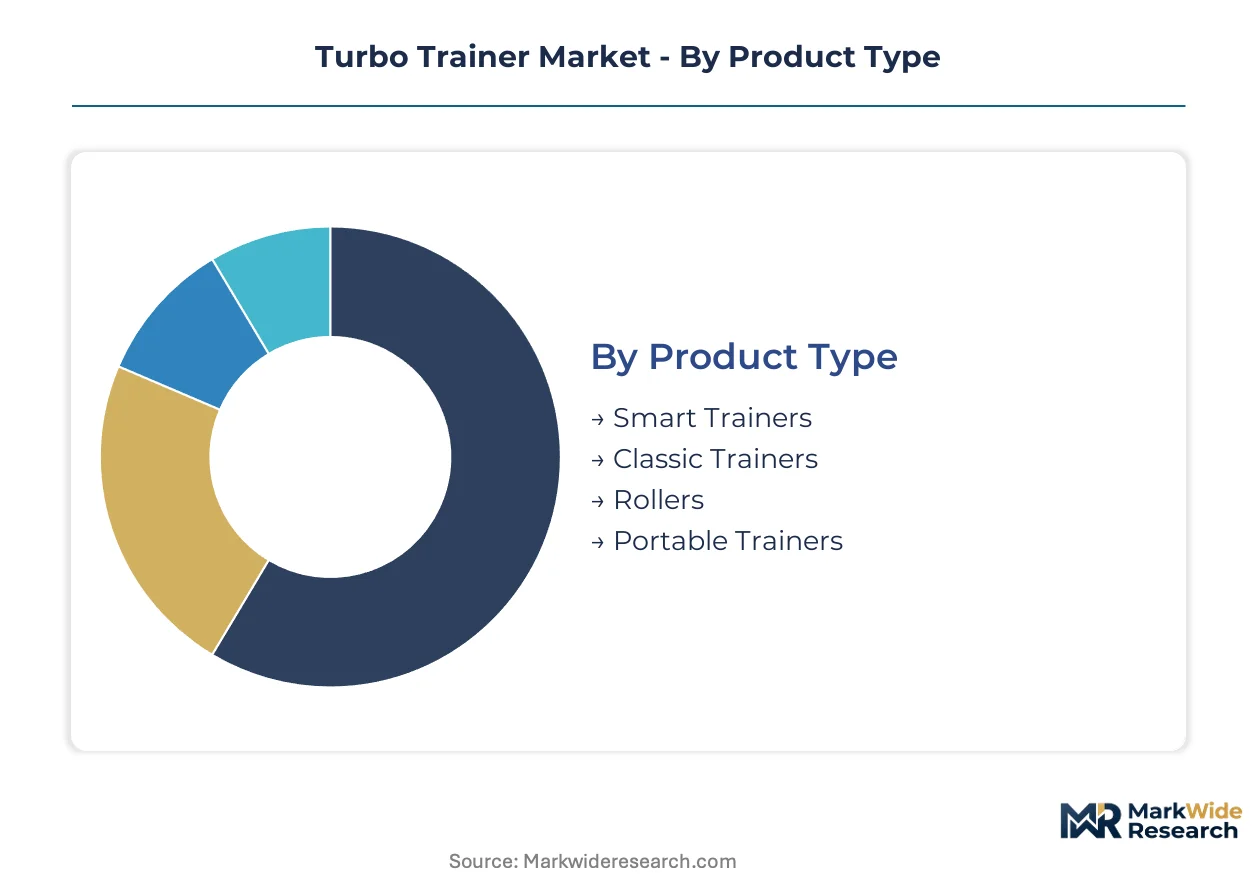
Turbo trainer segmentation reveals how resistance mechanism sophistication and connectivity integration determine margin capture. Product architecture choices directly expose manufacturers to substitution threats from stationary bikes and alternative fitness equipment.
Product Type:
Classic trainers face the most acute substitution pressure as all-in-one smart bikes from Peloton and NordicTrack capture convenience-seeking buyers.
- Smart Trainers:Integrated power measurement and wireless protocol compatibility enable seamless Zwift and TrainerRoad synchronization. Demand concentrates among competitive cyclists in Belgium and the Netherlands seeking ±1% power accuracy for structured training protocols.
- Classic Trainers:Wheel-on designs with manual resistance adjustment serve price-sensitive entry buyers. Volume persists in India and Southeast Asia where BIS certification alignment and urban fitness adoption precede direct-drive saturation.
- Rollers:Free-standing cylindrical drums demand advanced balance skills and appeal to technique-focused riders.
- Portable Trainers:Collapsible frames target traveling athletes and apartment dwellers with storage constraints.
Classic trainers retain volume leadership; smart trainers hold the steepest expansion curve.
End User:
Procurement authority is migrating from institutional buyers toward individual consumers with dedicated training spaces.
- Home Users:Residential basement and garage conversions in Germany and Japan drive permanent-installation purchases. Zwift subscription bundling now determines hardware selection ahead of mechanical specifications.
- Professional Athletes:UCI-registered teams and WorldTour squads mandate strain-gauge accuracy and electromagnetic resistance for altitude-simulation protocols.
- Cycling Enthusiasts:Recreational riders aged 35-55 prioritize software onboarding simplicity over resistance mechanism comparisons.
- Fitness Centers:Boutique studios in the United States are replacing static spin bikes with smart trainer bays for virtual racing classes.
Home users command the fastest share gain; fitness centers face structural decline.
Technology:
Cost tier stratification separates studio-grade precision units from commoditized consumer offerings.
- Direct Drive:Rear wheel removal and cassette direct attachment eliminate tire slip and improve power measurement consistency. Competitive cyclists in alpine regions favor high-torque, low-inertia designs replicating gradient feel.
- Fluid Resistance:Impeller-driven progressive resistance curves replicate road-like cadence response. Elite SRL specializes in this architecture for riders prioritizing tactile authenticity over digital integration.
- Magnetic Resistance:Eddy-current systems offer silent operation for apartment dwellers.
- Air Resistance:Fan-based units provide unlimited resistance ceiling at lower price points.
Direct drive is climbing the fastest; air resistance defends the lowest price tier.
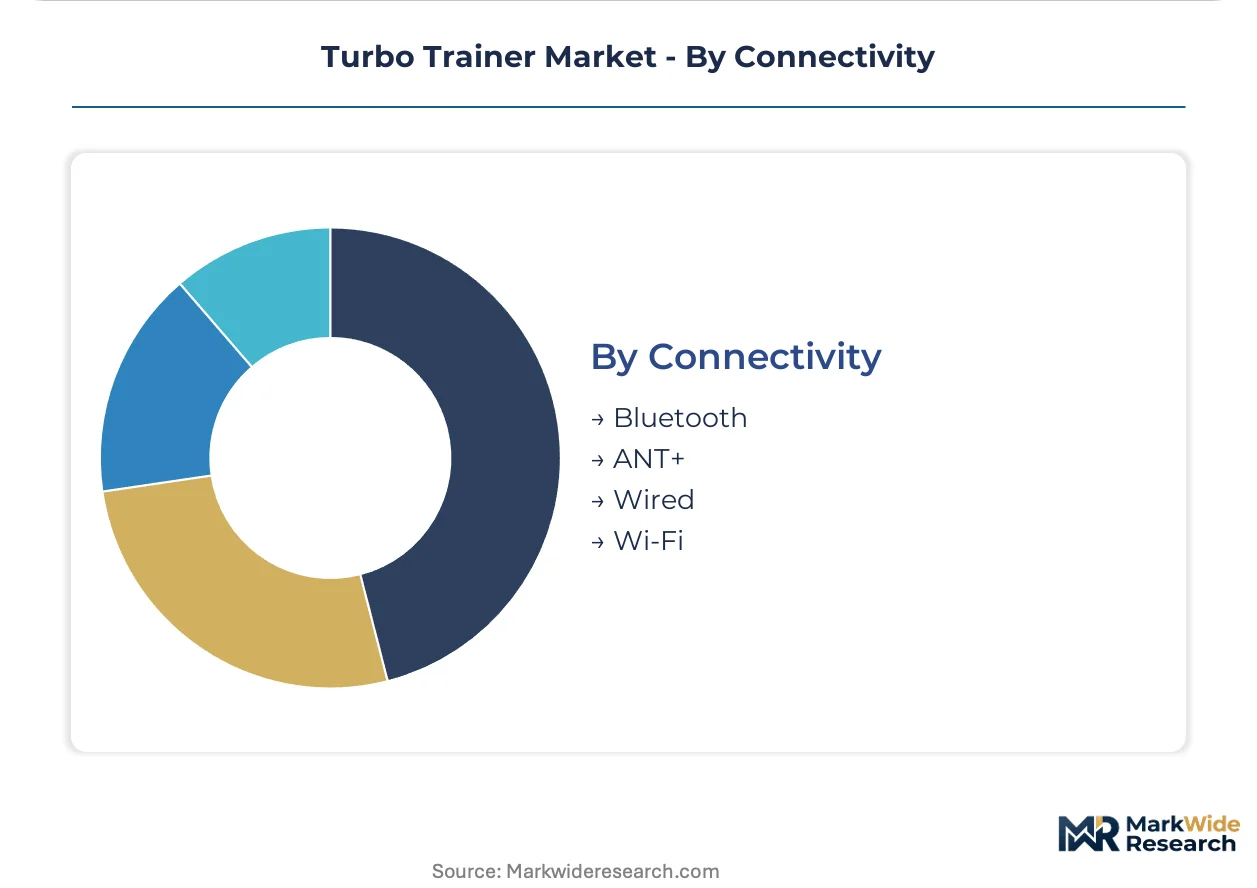
Connectivity:
Protocol standardization under FCC and EU CE marking frameworks has collapsed firmware fragmentation.
- Bluetooth:Universal smartphone and tablet compatibility enables Zwift mobile app integration without dedicated cycling computers.
- ANT+:Low-power wireless protocol dominates Garmin ecosystem connectivity and multi-sensor synchronization.
- Wi-Fi:Direct router connection eliminates smartphone bridging for firmware updates and cloud data sync.
- Wired:USB-C and Ethernet options serve users prioritizing connection stability over wireless convenience.
Bluetooth and ANT+ together retain volume leadership; Wi-Fi shows the steepest adoption slope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's cycling equipment distribution, while Japan's Shinkansen network enables just-in-time component delivery to precision manufacturers. Germany's autobahn-linked logistics corridors and the United States' intermodal rail hubs complete the infrastructure backbone.
Germany
Basement conversion trends in Bavaria and North Rhine-Westphalia drive permanent-installation smart trainer demand among recreational cyclists. The FCC's electromagnetic emissions framework shapes wireless protocol standardization for devices entering German retail channels. Stuttgart's engineering cluster hosts precision strain-gauge manufacturers supplying direct-drive resistance units to domestic brands.
United States
Boutique cycling studios in California and Texas are replacing static spin bikes with smart trainer bays for virtual racing classes. The FCC mandates Bluetooth and ANT+ certification for all wireless connectivity modules sold domestically. Colorado's Front Range corridor concentrates altitude-simulation protocol development for professional cycling teams.
Japan
Garage-to-training-space conversions in Tokyo and Osaka accelerate permanent-installation purchases among aging recreational athletes. METI's consumer electronics efficiency standards influence resistance unit power consumption specifications. Nagoya's industrial belt hosts electromagnetic component suppliers serving domestic trainer manufacturers.
India
Urban middle-class fitness adoption in Maharashtra and Karnataka creates whitespace for mid-tier wheel-on trainers before direct-drive saturation. BIS certification alignment remains mandatory for all electrical fitness equipment sold domestically. Chennai's manufacturing corridor attracts contract assemblers serving price-sensitive Southeast Asian export markets.
Belgium
UCI-registered professional teams in Flanders mandate strain-gauge accuracy for altitude-simulation training protocols. The EU's CE marking framework governs electrical safety and electromagnetic compatibility for all connected fitness devices. Kortrijk's cycling technology cluster specializes in high-torque, low-inertia direct-drive engineering for competitive applications.
Turbo Trainer Market Competitive Environment
Concentration sits with cycling electronics specialists and fitness equipment conglomerates. The vendor base spans three tiers: premium smart trainer engineers, mid-market wheel-on fabricators, and Asian contract manufacturers. Two strategic archetypes dominate: ecosystem-anchored software-hardware integrators and component-specialist precision engineers. Competitive moves center on platform partnership exclusivity and direct-drive electromagnetic resistance patent licensing.
Within the ecosystem-anchored tier, Wahoo Fitness and Garmin/Tacx exemplify software-hardware integration strategies. Elite SRL occupies a position among precision resistance specialists. These three anchors represent divergent competitive vectors: app ecosystem depth versus cycling electronics heritage versus fluid resistance authenticity.
| Leading Market Players |
|---|
| Wahoo Fitness |
| Garmin/Tacx |
| Elite |
| Saris |
| JetBlack Cycling |
| Minoura |
| Kurt Kinetic |
| Technogym |
| Stages Cycling |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day strain-gauge lead times from Stuttgart engineering clusters compress margin buffers for direct-drive manufacturers while amplifying pricing power for electromagnetic component suppliers serving premium smart trainer tiers. This inventory pressure cascades through distribution channels, forcing wheel-on fabricators into aggressive discounting that erodes brand positioning against stationary bike substitutes.
Pricing Analysis
Volume-discount tiering structures separate studio-grade precision units from consumer-accessible price bands. Three-tier pricing stratification across premium smart trainers, standard wheel-on designs, and economy air-resistance models reflects software subscription attach rates and power meter certification grades. Cost compression in entry tiers intensifies because Asian contract manufacturers flood price-sensitive markets with unbranded alternatives. Home users in Germany and Japan exhibit lowest price sensitivity due to permanent-installation preferences, while Indian urban middle-class buyers prioritize unit economics over connectivity features.
Supply Chain Analysis
Inventory obsolescence risk concentrates in wheel-on trainer stock as direct-drive adoption accelerates among competitive cyclists. Neodymium and dysprosium processing dependence on Chinese facilities creates raw material volatility for resistance unit manufacturers, while electromagnetic component sourcing draws from Japan's Nagoya industrial belt and Germany's Stuttgart cluster. Single-source vulnerability in rare-earth magnet supply chains exposes margin stability to geopolitical friction. Distribution runs through Rotterdam's container terminals for European markets and intermodal rail hubs serving North American boutique cycling studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in strain-gauge precision engineering and encrypted firmware development separates sustainable competitors from commodity assemblers in this market. The gap between studio-grade accuracy requirements and available electromagnetic resistance expertise constrains rapid capacity expansion.
For Market Incumbents: Fortify proprietary direct-drive architectures through backward integration into electromagnetic component production, securing captive supply from Nagoya and Stuttgart precision clusters. Deepen Zwift and TrainerRoad platform exclusivity to lock in subscription revenue streams that offset hardware margin compression from Asian contract manufacturers. Prioritize CE marking compliance investment ahead of evolving EU cybersecurity standards for connected fitness devices. For New Entrants and Emerging Players: Lead with BIS-certified mid-tier wheel-on trainers targeting Maharashtra and Karnataka urban fitness adopters before direct-drive saturation penetrates India's emerging cycling culture. Exploit whitespace in portable trainer segments for traveling athletes and apartment dwellers with storage constraints. Anchor go-to-market strategy through specialty cycling retailers offering bundled calibration and maintenance subscriptions. For Investors and Strategic Acquirers: Long-term, this sits as a software-hardware integration play because recurring platform revenue attachment determines enterprise value more than mechanical engineering differentiation. Target acquisition profiles center on ecosystem-anchored vendors with proven Zwift API integration and established strain-gauge calibration protocols. Watch firmware cybersecurity certification delays as the signal indicating which vendors will capture European market access versus face regulatory exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Drive Patent Licensing | Garmin/Tacx and Wahoo Fitness control electromagnetic resistance IP that determines competitive access to ±1% accuracy tiers. |
| Platform Partnership Exclusivity | Zwift integration depth now drives purchase decisions ahead of hardware specifications among recreational cyclists aged 35-55. |
| CE Marking Compliance Investment | German and French regulatory enforcement of cybersecurity standards delays product launches for non-compliant firmware architectures. |
| Backward Integration into Components | Captive strain-gauge production from Stuttgart engineering clusters insulates margin stability from rare-earth magnet volatility. |
| Software Subscription Bundling | TrainerRoad and Rouvy platform partnerships enable recurring revenue that offsets hardware margin compression in mature markets. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with cycling electronics engineers, specialty retailer buyers, boutique studio operators, and professional team equipment managers; and secondary validation through FCC equipment authorization databases, EU CE marking registries, customs trade records for cycling equipment, and SEC filings from fitness technology conglomerates. Bottom-up demand modeling from end-user procurement patterns was triangulated against top-down supply-side capacity assessments across electromagnetic component manufacturers.
Across the projection horizon, the analytical framework segmented volume and value outputs by resistance mechanism type, connectivity protocol, end-user archetype, and regional regulatory cluster. CAGRs were derived from installed base growth rates, replacement cycle compression, and software subscription attach rate trajectories. Industry-specific inputs included UCI power meter calibration standards, METI consumer electronics efficiency specifications, and BIS certification timelines for electrical fitness equipment.
Underlying assumptions cover sustained home fitness infrastructure investment, stable rare-earth magnet supply chains, and gradual direct-drive adoption curves, with deviation risk concentrated in EU cybersecurity standard evolution and stationary bike substitution acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Crampon Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
BMX Bikes Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Football Equipment Market