
 One-Piece Carbon Fiber Badminton Racket Market | 2026-2036
One-Piece Carbon Fiber Badminton Racket Market Size, Share, and Industry Trends Forecast 2026-2036
One-Piece Carbon Fiber Badminton Racket Market Insights
Modular grip-and-frame bundling is broadening buyer choice in the one-piece carbon fiber badminton racket category. Yonex leverages its captive carbon fiber supply chain to control quality from prepreg to finished frame. VICTOR anchors its position through deep specialization in high-modulus layup configurations for professional athletes. Li-Ning competes by dominating distribution through direct partnerships with China's provincial sports bureaus.
A one-piece carbon fiber badminton racket consists of a continuous monocoque shell molded from unidirectional or woven carbon fiber prepreg, typically weighing between 75 and 92 grams with shaft flex ratings from stiff to extra-flexible, engineered to transfer kinetic energy with minimal torsional deflection during smash strokes. Professional-grade rackets command the deepest margin pools due to athlete endorsement dependencies and materials certification overhead. Amateur demand grows fastest through online retail channels where nano-coating technology claims differentiate visually similar products. Recreational players sustain volume through sports outlet access in suburban markets.
Japan's METI and JIS standards govern shaft durability testing and impact resistance thresholds, while China's SAMR enforces GB labeling for carbon fiber content claims and origin disclosure. ISO 9001 quality management certification shapes OEM access to European specialty stores under CE marking expectations. Stakeholders must monitor how REACH chemical restrictions on epoxy resin formulations redirect manufacturing toward bio-based thermoset alternatives.
Market Dynamics
Competitive clubs across Southeast Asia are systematically replacing aluminum frames with monocoque carbon fiber constructions, creating a structural pull that reshapes manufacturing priorities and certification requirements throughout the supply chain.
Growth Catalysts
- GB Standards Enforcement:China's SAMR mandates carbon fiber content disclosure and origin labeling, eliminating mislabeled composite products from retail channels and building consumer trust in authentic monocoque constructions.
- Academy Cluster Concentration:Badminton academies cluster around Shenzhen and Guangzhou in China's Guangdong province, generating concentrated demand for professional-grade equipment with strict performance specifications.
- JIS Structural Integrity Mandates:Japan's METI enforces rigorous shaft durability testing and impact resistance thresholds, elevating quality baselines that premium manufacturers leverage for export positioning.
Market Restraints
- Prepreg Input Volatility:Aerospace and automotive sectors compete for identical carbon fiber grades, creating price instability for racket manufacturers dependent on T700 and T800 modulus fibers.
- Epoxy Resin Restrictions:REACH chemical regulations in Europe constrain traditional thermoset formulations, forcing costly reformulation cycles or supply exclusion from CE-marked distribution channels.
- Aluminum Substitution Persistence:Recreational players in price-sensitive markets continue purchasing welded aluminum frames, capping premium carbon fiber penetration in volume segments.
Strategic Opportunities
- Indonesia Underpenetration:Competitive club formation in Jakarta and Surabaya outpaces specialized equipment availability, creating first-mover advantages for certified suppliers.
- Nano-Coating Differentiation:Surface treatment technologies enable visual distinction between functionally similar products, supporting margin capture in online retail channels where physical inspection is absent.
- Direct-to-Academy Distribution:Bypassing traditional sports outlet intermediaries allows manufacturers to capture equipment specification data and secure recurring replacement cycles.
Industry Challenges
- Layup Technician Scarcity:High-modulus fiber placement requires specialized composite manufacturing skills concentrated in Japan and China, constraining production scaling outside established manufacturing clusters.
- ISO 9001 Certification Timelines:European specialty store access demands quality management documentation that extends market entry timelines for emerging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | One-Piece Carbon Fiber Badminton Racket Market |
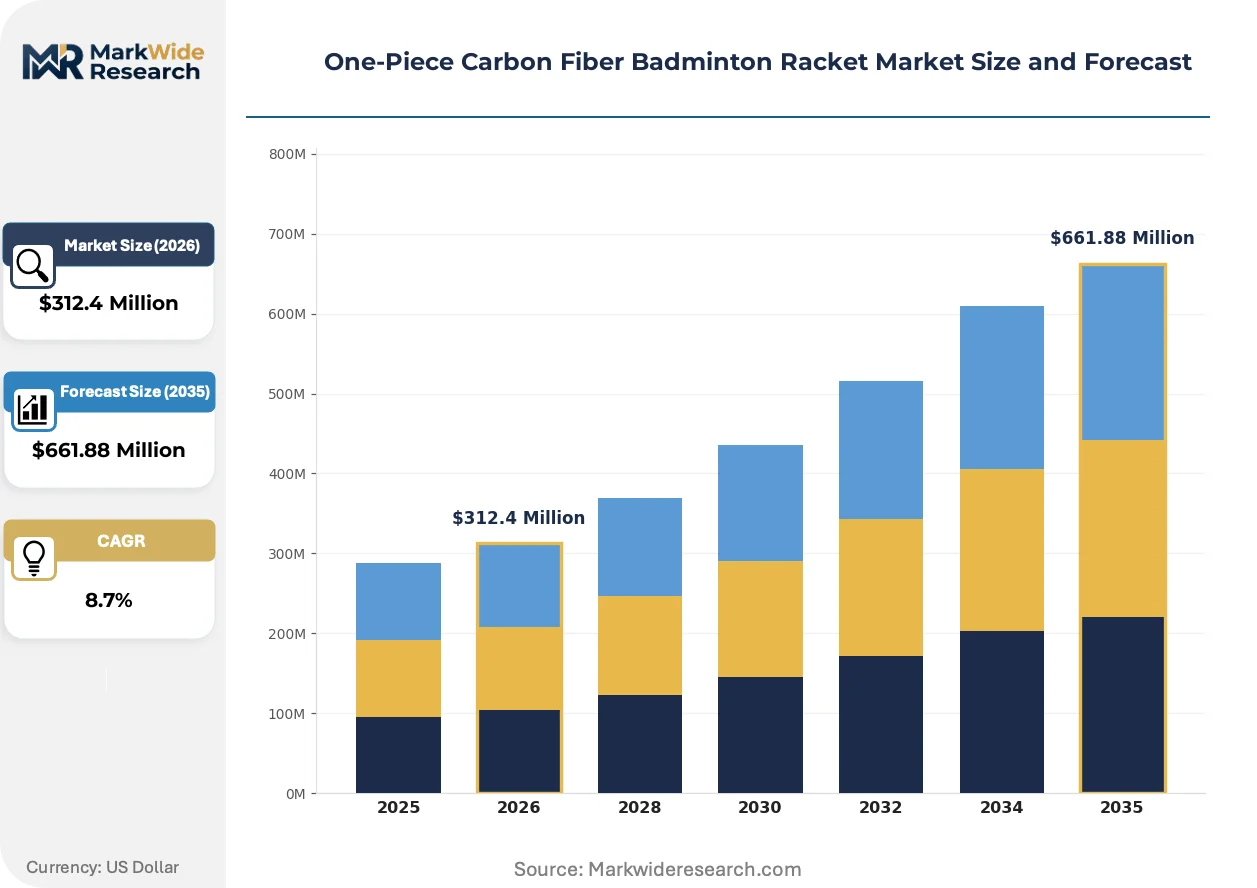
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Professional, Amateur, Recreational, Junior End User: Clubs, Schools, Individual Players, Coaches Technology: High Modulus, Nano Coating, Aerodynamic, Shock Absorbent Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Direct Sales |
| Companies Covered | Yonex, VICTOR, Li-Ning, GOSEN, RSL, Babolat, Wilson Sporting Goods, Apacs Sports, Carlton Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
One-Piece Carbon Fiber Badminton Racket Market Trends and Innovations
Automated prepreg cutting and robotic fiber placement are compressing production cycles while enabling geometric complexities previously unattainable in monocoque racket manufacturing.
Computer-controlled fiber placement is automating the layup of unidirectional and woven carbon fiber sheets with precision that manual processes cannot replicate. Professional-grade manufacturers in Japan and China are adopting these systems to reduce torsional variance between production batches. This automation is compressing the gap between prototype development and volume manufacturing, accelerating product refresh cycles.
REACH chemical restrictions on epoxy resin formulations are redirecting manufacturing toward bio-based thermoset alternatives with equivalent mechanical properties. European specialty retailers now demand documentation of resin composition for CE-marked inventory. Amateur and recreational segments face the greatest adjustment burden, as reformulated materials require recertification before market entry.
Online retail channels are displacing traditional sports outlet dominance for amateur equipment purchases, particularly in suburban markets distant from urban academy clusters. Nano-coating technology claims differentiate visually similar products where buyers cannot physically test flex ratings or weight distribution. This channel shift concentrates most visible in China's tier-two cities, where digital-native consumers research specifications independently before purchase.
One-Piece Carbon Fiber Badminton Racket Market Segmentation
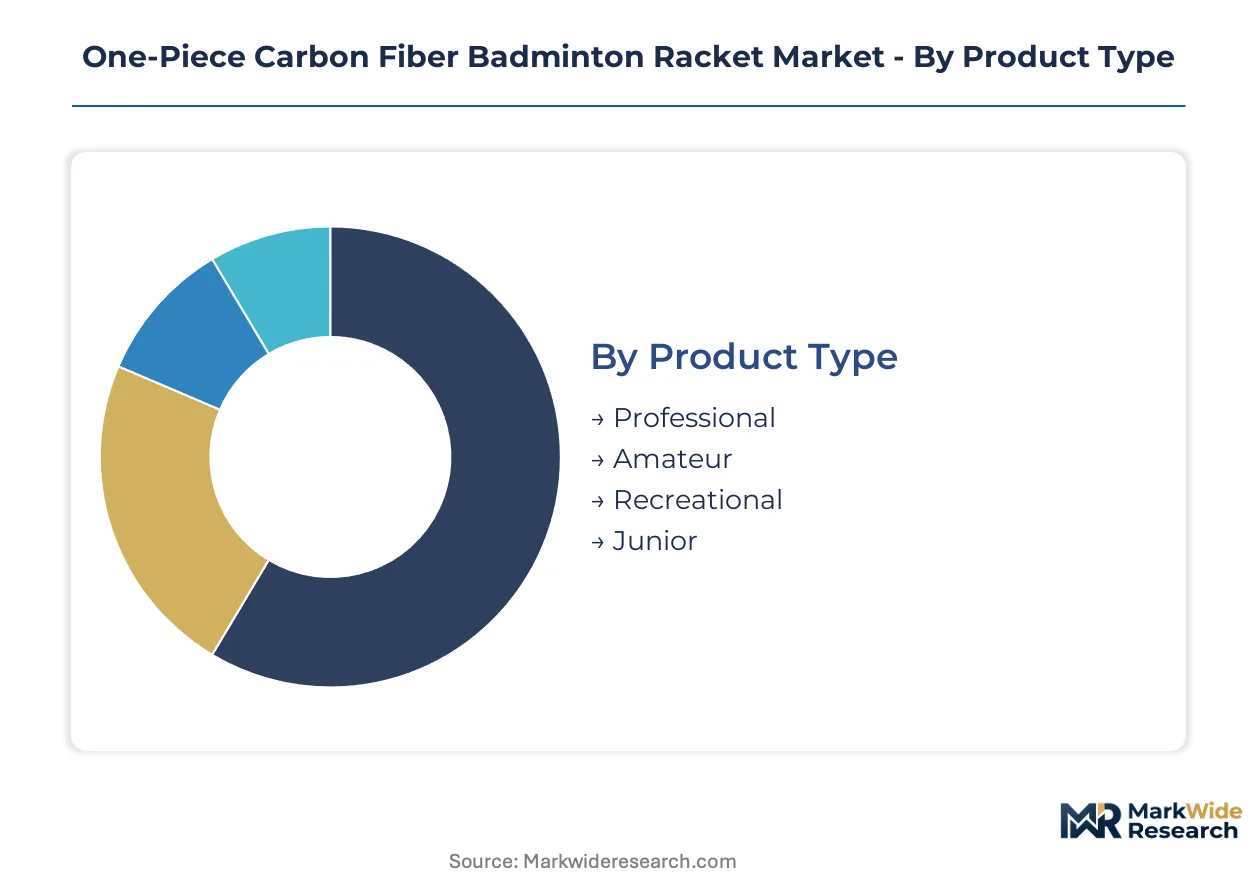
Carbon fiber racket purchasing decisions hinge on certification grade, shaft modulus, and channel accessibility. Manufacturers configure production lines around these segment boundaries to optimize margin capture across divergent buyer expectations.
Product Type:
Performance tier determines materials certification overhead and endorsement dependency.
- Professional:Athlete-grade rackets integrate T800 modulus fiber with JIS-certified shaft durability. Demand concentrates in Guangdong province academies where coaches specify strict flex ratings and weight tolerances.
- Amateur:Nano-coating surface treatments differentiate visually similar frames for online buyers. This segment expands most quickly through digital channels in China's tier-two cities.
- Recreational:Suburban sports outlets sustain volume through accessible price points and immediate availability.
- Junior:Scaled-down frames with reduced swing weight target developmental programs in Jakarta and Surabaya clubs.
Volume sits with Recreational; growth tilts toward Amateur.
End User:
Procurement authority varies sharply between institutional buyers and individual decision-makers.
- Clubs:Competitive clubs across Southeast Asia drive carbon fiber conversion from aluminum, generating concentrated batch orders with specification rigor.
- Schools:Provincial sports bureaus in China negotiate direct partnerships for equipment standardization across academy networks.
- Individual Players:Digital-native consumers research independently before purchasing through online retail, particularly distant from urban academy clusters.
- Coaches:Technical advisors influence brand selection through direct specification authority in professional training environments.
Institutional procurement dominates volume; individual channels show steepest expansion trajectory.
Technology:
Fiber architecture and surface engineering separate price tiers.
- High Modulus:T700 and T800 fiber placement requires specialized layup technicians concentrated in Japan and China. Professional athletes demand minimal torsional variance between production batches.
- Nano Coating:Surface treatment enables visual distinction where physical inspection is absent, supporting margin capture in online retail channels.
- Aerodynamic:Frame geometry optimization reduces drag coefficients for smash stroke efficiency.
- Shock Absorbent:Vibration damping layers target recreational players seeking comfort over power transfer precision.
High Modulus commands premium positioning; Nano Coating gains share fastest through digital differentiation.
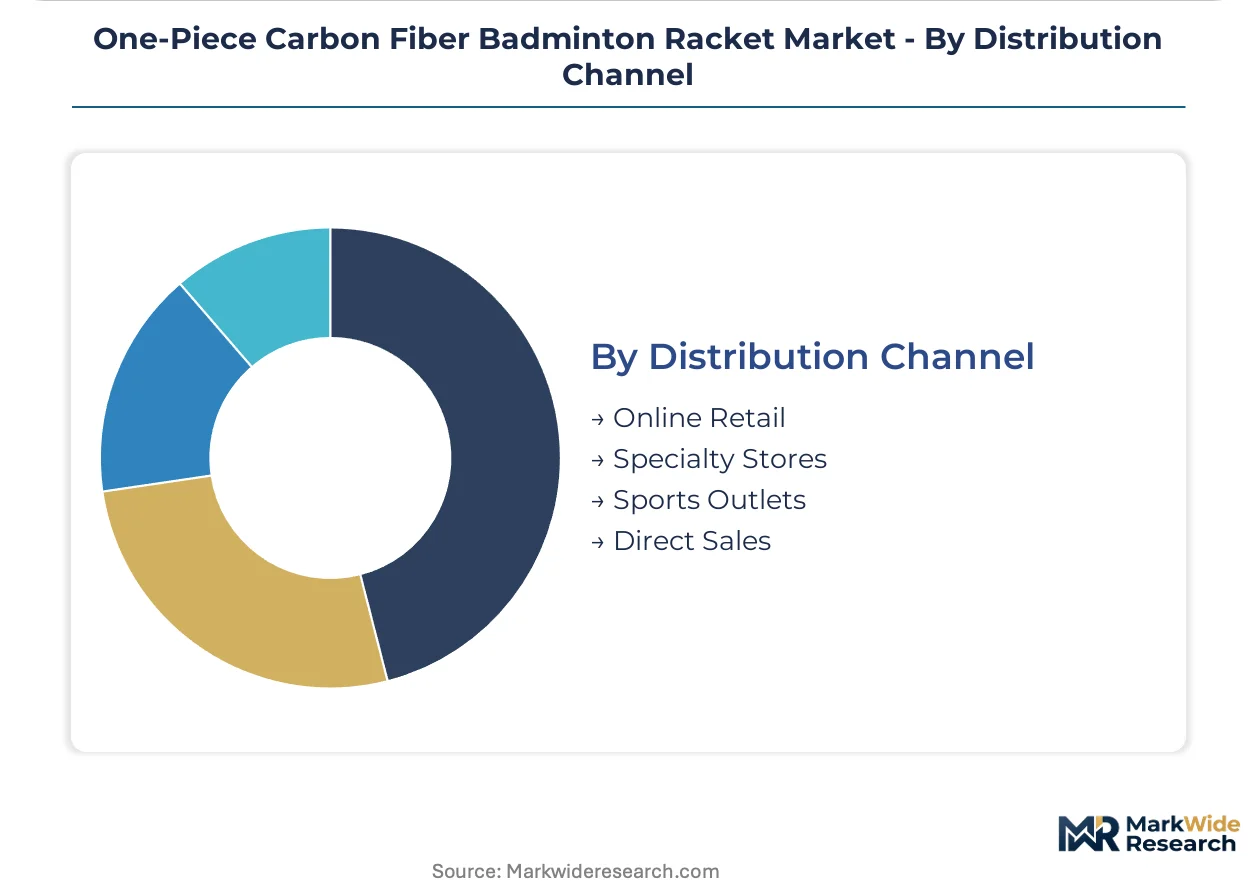
Distribution Channel:
Channel selection determines certification documentation requirements and margin structure.
- Online Retail:Displaces traditional outlet dominance for amateur purchases, concentrating in suburban markets distant from Shenzhen and Guangzhou academy clusters.
- Specialty Stores:European retailers demand ISO 9001 documentation and REACH-compliant resin certification for CE-marked inventory.
- Sports Outlets:Recreational volume sustains through immediate availability and tactile evaluation opportunities.
- Direct Sales:Academy bypass strategies capture specification data and secure recurring replacement cycles for competitive clubs.
Specialty Stores anchor professional tier pricing; Direct Sales expand most quickly through institutional relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong province hosts the densest concentration of badminton academy infrastructure, with Shenzhen and Guangzhou generating institutional procurement volumes that reshape manufacturing priorities across East Asia.
China
Badminton academies cluster around Shenzhen and Guangzhou, creating concentrated demand for professional-grade rackets with strict flex specifications. SAMR enforces GB standards mandating carbon fiber content disclosure and origin labeling, eliminating mislabeled composites from retail channels. Dongguan manufacturers supply these academies through direct partnerships with provincial sports bureaus.
Japan
Competitive clubs in Tokyo and Osaka systematically replace aluminum frames with monocoque carbon fiber constructions. METI enforces rigorous JIS standards for shaft durability testing and impact resistance thresholds. Yonex leverages its captive carbon fiber supply chain in Niigata prefecture to control quality from prepreg to finished frame.
Indonesia
Competitive club formation in Jakarta and Surabaya outpaces specialized equipment availability, creating first-mover advantages for certified suppliers. The national sports ministry promotes badminton development through subsidized academy programs. Bandung manufacturers struggle to match JIS-certified import quality for professional-tier demand.
South Korea
Seoul's recreational badminton centers drive amateur segment growth through online retail channels. The Korean Consumer Agency enforces labeling requirements for composite sports equipment. Busan distributors specialize in nano-coated surface treatments that differentiate visually similar products for digital-native buyers.
Malaysia
Kuala Lumpur's competitive clubs generate batch orders with specification rigor comparable to Guangdong academies. The Ministry of Domestic Trade monitors carbon fiber content claims under consumer protection frameworks. Penang sports outlets sustain recreational volume through immediate availability and tactile evaluation opportunities.
One-Piece Carbon Fiber Badminton Racket Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates premium-tier positioning among established East Asian manufacturers. The vendor base spans three strategic archetypes: vertically integrated carbon fiber producers controlling supply chains from prepreg to retail, specialized racket manufacturers outsourcing fiber sourcing to aerospace-grade suppliers, and sporting goods conglomerates leveraging multi-sport distribution networks. Dominant competitive moves include backward integration into prepreg manufacturing and direct-to-academy distribution partnerships that bypass traditional retail intermediaries.
Within the vertically integrated tier, Yonex exemplifies supply chain control through captive carbon fiber operations. VICTOR and Li-Ning occupy positions as specialized manufacturers with distinct competitive vectors—VICTOR through high-modulus layup configurations for professional athletes, Li-Ning through provincial sports bureau partnerships that secure institutional procurement channels. These three companies anchor the premium segment where athlete endorsement dependencies and materials certification overhead create the deepest margin pools.
| Leading Market Players |
|---|
| Yonex |
| VICTOR |
| Li-Ning |
| GOSEN |
| RSL |
| Babolat |
| Wilson Sporting Goods |
| Apacs Sports |
| Carlton Sports |
| Others |
Pricing and Supply Chain Analysis
Academy procurement specifications in China's Guangdong province are tightening flex rating tolerances and shaft modulus requirements, forcing manufacturers to reserve premium T800 fiber allocations for institutional contracts while spot buyers face extended lead times and elevated per-unit costs.
Pricing Analysis
Short lead-time premiums dominate transactional pricing for professional-grade rackets, with academy clusters in Shenzhen and Guangzhou paying contract rates for guaranteed T800 fiber allocation while recreational buyers absorb spot-market volatility. Three-tier pricing structure across professional, amateur, and recreational levels separates JIS-certified athlete-grade equipment from nano-coated amateur frames and aluminum-substitute economy options. Cost compression in the recreational tier is intensifying because Bandung manufacturers compete on price against Chinese imports. Individual players in online channels show highest price sensitivity; competitive clubs demonstrate lowest sensitivity due to specification-driven procurement.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in this category due to the structural integrity requirements of monocoque carbon fiber constructions, though warranty claim rates for shaft durability failures in Indonesia create localized reverse logistics pressure. Manufacturing gravity centers on Japan, China, and Taiwan, with Niigata prefecture housing captive prepreg operations and Dongguan hosting volume frame molding. Raw material dependencies draw from aerospace-grade carbon fiber feedstock, epoxy resin formulations, and molded grip components. Single-source vulnerability concentrates in T800 fiber supply from Japanese producers. Distribution runs through direct academy partnerships for professional tiers, online retail for amateur segments, and suburban sports outlets for recreational volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply constraint: layup technician scarcity in Japan and China props pricing for professional-grade equipment by capping production scaling outside established manufacturing clusters.
For Market Incumbents: Acquire specialized composite manufacturing talent pools in Niigata and Dongguan to secure production scaling capacity against emerging entrants from Bandung. Defensive priorities center on backward integration into prepreg manufacturing to control T800 fiber allocation, and deepening ISO 9001 certification moats to delay European specialty store access for challengers. For New Entrants and Emerging Players: SAMR enforcement of GB standards in China opens a window for certified suppliers to displace mislabeled composite products from retail channels. White-space targets cluster in Jakarta and Surabaya competitive clubs, where professional-grade availability lags demand formation. Go-to-market execution should anchor on direct-to-academy distribution partnerships that bypass traditional sports outlet intermediaries and capture specification data. For Investors and Strategic Acquirers: The window for entry favors specialized racket manufacturers with existing high-modulus layup capabilities rather than diversified sporting goods conglomerates. Long-term viability hinges on five-to-ten year fiber architecture differentiation sustainability. Acquisition screening should prioritize firms with captive carbon fiber supply relationships. The signal to watch is REACH-compliant resin certification adoption rates among European specialty retailers, indicating which suppliers can maintain CE-marked channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prepreg Manufacturing | Yonex's Niigata captive supply demonstrates quality control from fiber to finished frame. |
| Direct-to-Academy Distribution Partnership | Li-Ning's provincial sports bureau relationships secure recurring replacement cycles in Guangdong. |
| Nano-Coating Technology Investment | VICTOR's surface treatment differentiation captures margin in online channels lacking physical inspection. |
| Robotic Fiber Placement Automation | Japanese manufacturers reduce torsional variance between production batches through computer-controlled layup. |
| REACH-Compliant Resin Reformulation | European specialty retailers now demand documentation of bio-based thermoset alternatives for CE-marked inventory. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across racket manufacturing executives, academy procurement directors, composite materials engineers, and sports retail category managers. Secondary validation drew from JIS certification databases, SAMR GB standard enforcement records, METI structural integrity guidelines, and carbon fiber import manifests. Bottom-up academy demand modeling and top-down regional consumption estimates were triangulated against manufacturer shipment disclosures.
Data-stream reconciliation across production volume disclosures, academy enrollment trends, and retail channel sell-through metrics shaped the analytical framework. Segmentation dimensions modeled include performance tier, shaft modulus rating, distribution channel, and regional regulatory cluster. CAGRs were derived from slope analysis of historical shipment trajectories projected against academy formation rates and competitive club conversion patterns from aluminum. Industry-specific forecast inputs incorporated prepreg price indices and REACH chemical restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for bio-based thermoset resin formulations would alter the outlook if mechanical property equivalency fails certification thresholds. Forecasts reflect documented assumptions about academy cluster expansion rates and fiber placement automation diffusion. Practitioners should monitor SAMR enforcement intensity and Jakarta club formation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Cycling Sunglasses Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Golf Ball Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Slam Ball Market
Sports Equipment
Sandbells Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Parallel Bars Market
Sports Equipment
US Fencing Market