
 Golf Bags Market | 2026-2036
Golf Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Bags Market Outlook
Market Context
Vietnam is reconfiguring its position as a secondary manufacturing hub for golf bag assembly as brands diversify from Chinese production. Sun Mountain leverages its domestic U.S. manufacturing footprint to sustain premium positioning and faster lead times. Ping anchors its market presence through deep integration with club fitting networks and proprietary distribution. Vessel differentiates through direct-to-consumer channel control and limited-release collaboration models.
Technical Definition and Segment Structure
A golf bag is a specialized sporting equipment carrier engineered with reinforced partitioning, weather-resistant shell construction, and ergonomic load-distribution systems to transport clubs, accessories, and apparel across varied terrain and transit conditions. Stand bags incorporate retractable leg mechanisms and hip pads for walking golfers, while cart bags optimize pocket orientation and base stability for motorized trolley use. Polyester dominates material selection for mass-market stand and cart bags due to its abrasion resistance and dye-sub print compatibility, though leather persists in the premium tier where Vessel and MacKenzie Golf Bags compete on craftsmanship positioning. Travel bags represent the fastest-growing product type as airline-checked golf equipment volumes recover and hard-shell composite designs displace soft-sided alternatives among frequent flyers.
Regulatory Environment
California's Proposition 65 enforcement through the Office of Environmental Health Hazard Assessment compels nylon and polyester suppliers to disclose phthalate and flame-retardant content, elevating compliance costs for brands sourcing coated fabrics. The U.S. Consumer Product Safety Commission monitors lead content in zipper hardware and PVC trim, while ISO 9001 quality certification serves as a de facto supplier qualification standard for major retail channel access. Stakeholders must monitor evolving state-level chemical disclosure mandates and airline dimension restrictions that directly constrain travel bag design specifications.
Market Dynamics
California's Proposition 65 enforcement is compressing synthetic material supply chains and forcing reformulation investments across polyester and nylon sourcing networks serving U.S. golf bag assembly.
Growth Catalysts
- Post-pandemic participation surge:Weekend amateur golfers are returning to courses at elevated rates, expanding the addressable base for mid-tier stand and cart bag replacements.
- Airline equipment recovery:Checked golf baggage volumes at major U.S. carriers are rebounding, accelerating hard-shell travel bag adoption among frequent flyers.
- REACH chemical transparency:European ECHA disclosure requirements are pushing Asian fabric mills toward cleaner coating chemistries, opening premium positioning for compliant suppliers.
Market Restraints
- Polyester feedstock volatility:PTA and MEG pricing swings tied to crude oil fluctuations compress margin predictability for mass-market bag assemblers.
- Chinese supply concentration:Zipper hardware and PVC trim production remains concentrated in Zhejiang and Guangdong provinces, exposing brands to tariff and logistics disruptions.
- Phthalate substitution technical limits:Bio-based plasticizers in coated fabrics currently fail abrasion benchmarks required for golf bag base panels.
Strategic Opportunities
- Vietnam assembly expansion:Brands diversifying from Chinese production can leverage Ho Chi Minh City industrial zones for cut-and-sew capacity with preferential tariff access.
- Direct-to-consumer channel control:Limited-release collaboration models bypass wholesale margin compression and capture full retail markup from enthusiast segments.
- Domestic U.S. manufacturing:In-house production of premium bags insulates against ocean freight volatility and supports faster custom fitting turnaround.
Industry Challenges
- ISO 9001 certification timelines:Major retail channel access requires 12-18 month supplier qualification cycles that delay new product introductions.
- Legacy ERP integration:Small-batch craft bag makers struggle to connect artisan production workflows with enterprise inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Bags Market |
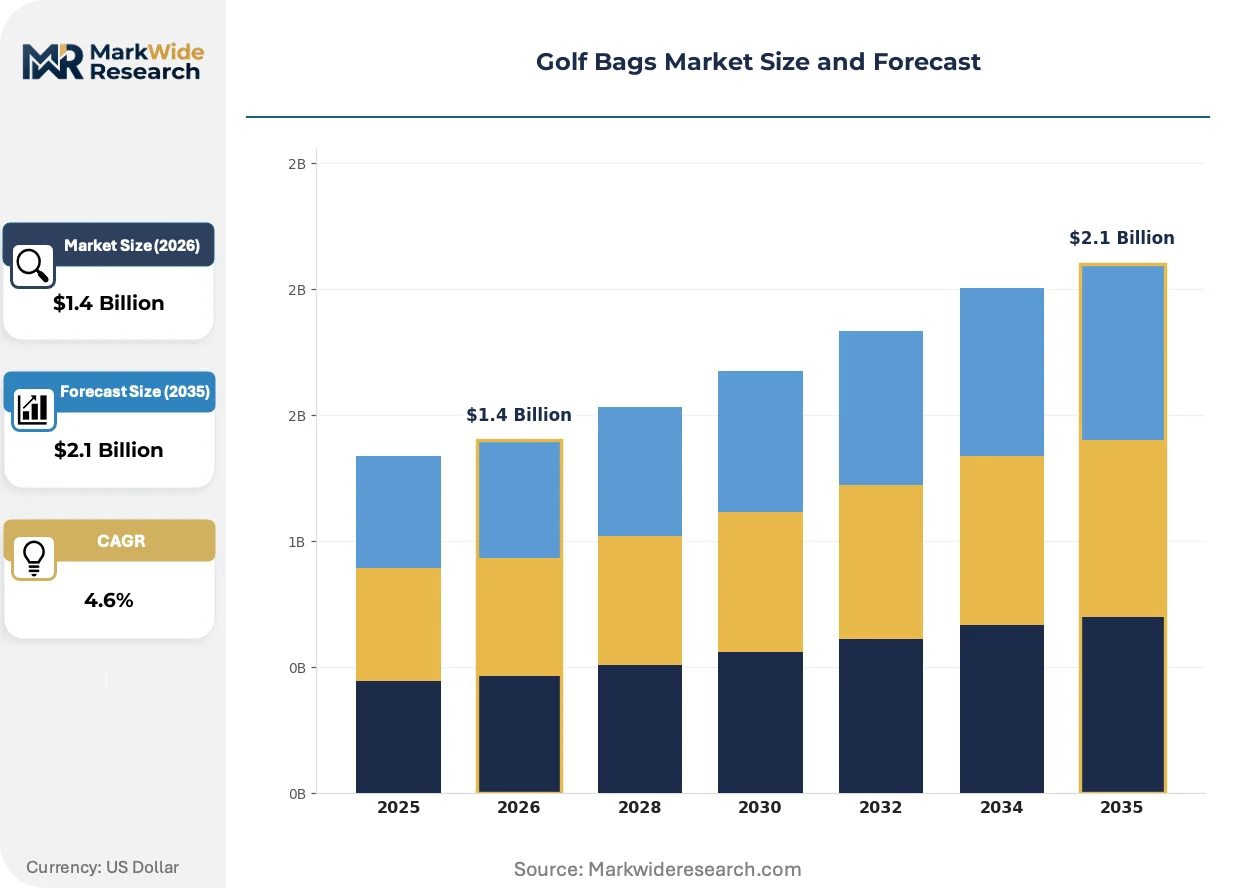
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand Bags, Cart Bags, Travel Bags, Pencil Bags Material: Leather, Nylon, Polyester, Canvas Size: Small, Medium, Large, Extra Large End User: Amateur Golfers, Professional Players, Golf Instructors, Golf Enthusiasts |
| Companies Covered | Jones Golf, BIG MAX, Sun Mountain, MacKenzie Golf Bags, Ping, Vessel, Stitch Golf, Hudson Sutler, Sunday Golf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Bags Market Strategic Shifts
Material science advances and channel restructuring are compressing traditional product lifecycles while elevating performance expectations across all price tiers.
Carbon fiber reinforced leg mechanisms are migrating from tour-grade stand bags into mid-market walking golfer offerings. Weekend players now expect sub-three-pound carry weights previously reserved for elite athlete equipment. This migration from premium to standard tiers is compressing price elasticity and forcing polyester-dependent brands toward composite sourcing partnerships.
California's Office of Environmental Health Hazard Assessment is intensifying Prop 65 enforcement against phthalate-containing coated fabrics. Nylon suppliers face elevated testing and disclosure costs that pass through to finished bag pricing. Mass-market brands sourcing from Guangdong mills are accelerating reformulation timelines to maintain California retail access.
Club fitting networks are unbundling bag sales from iron and driver purchases, disrupting the traditional pro shop bundle model. Specialty retailers now compete directly with manufacturer-owned fitting studios for high-margin accessory attachment. This channel fragmentation is most visible in Arizona and Florida markets where year-round play sustains standalone fitting center economics.
Golf Bags Market Segmentation
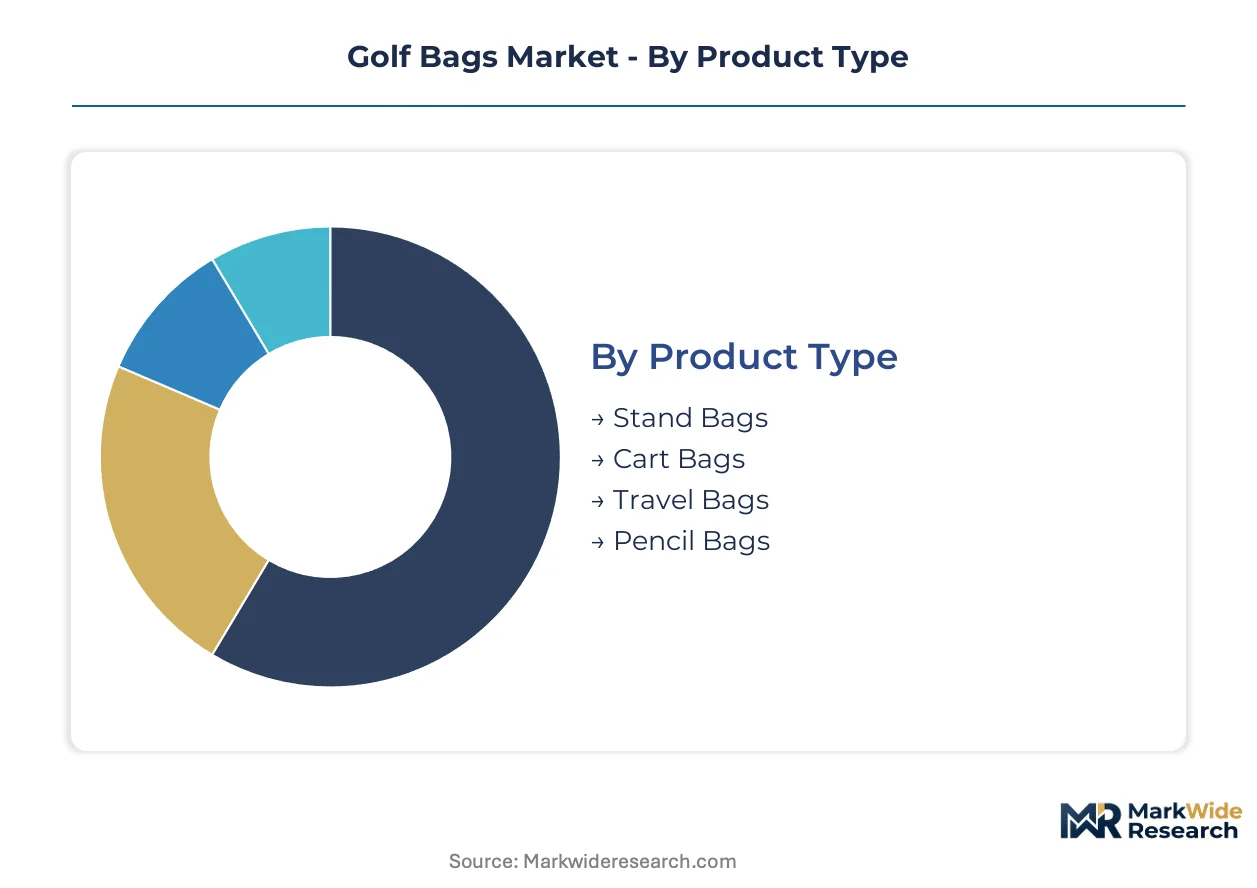
Golf bag segmentation reveals distinct service intensity profiles across product tiers. Stand and travel bags demand higher warranty and repair touchpoints than cart alternatives, shaping margin structures and channel economics for manufacturers and retailers.
Product Type:
After-sales-service intensity varies sharply by product type, with mechanical components and transit exposure driving differential support costs.
- Stand Bags:Retractable leg mechanisms and hip pad assemblies create recurring service events. Weekend amateur golfers in the United States drive replacement demand as carbon fiber reinforced legs migrate from tour-grade into mid-market offerings.
- Travel Bags:Hard-shell composite designs face airline damage claims and wheel replacement cycles. Frequent flyers recovering post-pandemic checked baggage volumes are accelerating adoption, though zipper and handle failures concentrate service requests.
- Cart Bags:Base stability systems and pocket orientation optimize for motorized trolley use with minimal moving parts. Golf instructors and cart-dependent players prioritize durability over weight reduction.
- Pencil Bags:Ultralight Sunday carry options sacrifice partitioning for portability. Minimalist construction limits service exposure to seam reinforcement and strap attachment points.
By volume, stand bags lead. By growth pace, travel bags are climbing the fastest.
Material:
Cost tier stratification separates premium craftsmanship positioning from mass-market chemical compliance pressures.
- Polyester:Abrasion-resistant shell construction dominates mass-market stand and cart bag production. California's Proposition 65 enforcement through the Office of Environmental Health Hazard Assessment is elevating testing costs for coated fabric suppliers serving U.S. assembly networks.
- Leather:Full-grain and synthetic leather variants anchor premium tier competition where Vessel and MacKenzie Golf Bags compete on craftsmanship heritage. Artisan production workflows resist ERP integration, constraining scale.
- Nylon:High-denier ripstop configurations balance weight and tear resistance for walking golfer applications. REACH transparency mandates from European ECHA are pushing Asian mills toward cleaner coating chemistries.
- Canvas:Waxed cotton and synthetic canvas blends appeal to heritage aesthetic positioning. Limited water resistance restricts adoption to fair-weather recreational segments.
Polyester commands unit volume leadership. Leather captures the steepest margin expansion trajectory.
Size:
Application context determines dimensional requirements across walking, riding, and transit use cases.
- Large:Fourteen-way top configurations and expanded apparel storage serve multi-day tournament players and destination golfers. Airline dimension restrictions directly constrain travel bag specifications in this tier.
- Medium:Standard seven to nine-way club organization balances capacity with portability for daily play. The segment concentrates replacement demand from post-pandemic participation surges.
- Small:Reduced pocket arrays and abbreviated profiles suit executive course rounds and practice sessions. Pencil bag overlap compresses distinct positioning.
- Extra Large:Oversized travel configurations accommodate multiple club sets and bulky outerwear. Hard-shell composite displacement of soft-sided alternatives is most visible here.
Medium size leads in replacement frequency. Extra large is gaining share fastest among frequent flyers.
End User:
Customer type segmentation aligns equipment specifications with skill level, frequency, and purchase authority patterns.
- Amateur Golfers:Weekend recreational players represent the fastest-expanding buyer segment as participation rates climb post-pandemic. Sub-three-pound carry weight expectations previously reserved for elite athletes now define mid-tier stand bag requirements.
- Professional Players:Tour staff and competitive amateurs demand customized fitting integration and sponsor-compliant branding. Club fitting networks unbundling bag sales from iron purchases disrupt traditional pro shop bundle economics.
- Golf Instructors:Teaching professionals prioritize durability and organization for high-volume lesson schedules. Cart bag stability and pocket accessibility outweigh weight considerations.
- Golf Enthusiasts:Collector and limited-release collaboration buyers respond to direct-to-consumer channel control and scarcity marketing. Vessel's collaboration models capture full retail markup from this segment.
Amateur golfers dominate unit volume. Enthusiasts are expanding most quickly on a revenue-per-unit basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly networks for golf bags concentrate in coastal industrial zones across three continents, with Vietnam expanding cut-and-sew capacity as brands diversify sourcing from China. Finished goods demand clusters in North America and Western Europe where course infrastructure density supports replacement cycles.
United States
Weekend amateur golfers drive replacement demand for mid-tier stand bags as post-pandemic participation rates stabilize above historical baselines. California's Office of Environmental Health Hazard Assessment enforces Proposition 65 disclosure requirements on phthalate-containing coated fabrics, elevating compliance costs for polyester suppliers. Sun Mountain maintains domestic manufacturing in Montana to serve premium positioning with faster lead times.
China
Zipper hardware and PVC trim production remains concentrated in Zhejiang and Guangdong provinces, supplying component inputs to regional assembly operations. The Ministry of Ecology and Environment monitors industrial chemical discharge from textile coating facilities in the Pearl River Delta. Dongguan industrial clusters face margin pressure from rising labor costs and environmental compliance investments.
Vietnam
Ho Chi Minh City industrial zones attract golf bag cut-and-sew investment as brands seek preferential tariff access and reduced logistics exposure to U.S.-China trade friction. The Ministry of Industry and Trade administers export processing enterprise incentives for sporting goods manufacturing. Binh Duong province hosts expanding polyester fabric finishing capacity serving regional assembly networks.
Germany
REACH transparency mandates from the European Chemicals Agency push Asian fabric mills toward cleaner coating chemistries for bags entering EU distribution. Bavaria-based specialty retailers compete with manufacturer-owned fitting studios for high-margin accessory sales. Munich and Stuttgart metropolitan areas concentrate golf enthusiast populations with elevated equipment replacement frequency.
Japan
Metropolitan Tokyo and Osaka golf communities sustain demand for ultralight stand bags with sub-three-pound carry specifications. The Ministry of Economy, Trade and Industry promotes quality certification alignment with ISO 9001 standards for supplier qualification. Chiba prefecture industrial zones handle regional distribution and limited assembly for domestic market customization.
Golf Bags Market Competitive Environment
Premium craftsmanship specialists and mass-market scale operators split the market into distinct competitive spheres with limited direct overlap. Three strategic archetypes dominate: domestic U.S. manufacturers leveraging proximity for custom turnaround, Asian assembly specialists optimizing cost-positioned volume production, and direct-to-consumer brands capturing full retail markup through channel control. Competitive moves concentrate on geographic sourcing diversification and limited-release collaboration models that bypass wholesale margin compression.
Among U.S.-based fabricators, Sun Mountain occupies a position exemplifying domestic manufacturing insulation against ocean freight volatility. Vessel represents the direct-to-consumer archetype with controlled channel economics. Ping anchors market presence through integration with club fitting networks. These three companies illustrate the strategic segmentation between proximity-based premium positioning, channel-controlled enthusiast targeting, and fitting-network distribution depth.
| Leading Market Players |
|---|
| Jones Golf |
| BIG MAX |
| Sun Mountain |
| MacKenzie Golf Bags |
| Ping |
| Vessel |
| Stitch Golf |
| Hudson Sutler |
| Sunday Golf |
| Others |
Value Chain & Pricing Dynamics
Dongguan industrial clusters in Guangdong province anchor polyester fabric finishing capacity, and their margin compression from environmental compliance investments is transmitting downstream into mass-market bag pricing power. California's Proposition 65 enforcement elevates testing costs for coated fabric suppliers, forcing brands to absorb compliance pass-throughs or reformulate toward cleaner chemistries at premium tier positioning.
Pricing Analysis
California's Office of Environmental Health Hazard Assessment dictates the pricing tier structure through phthalate disclosure mandates that stratify compliant suppliers from conventional coating operations. Three-tier pricing structure across premium, standard, and economy levels separates Vessel's direct-to-consumer craftsmanship positioning from mass-market polyester dependence, with certification grade and geographic delivery cost as primary differentiation drivers. Cost compression in the standard tier is intensifying because PTA and MEG feedstock volatility compresses margin predictability. Weekend amateur golfers exhibit highest price sensitivity, while golf enthusiasts demonstrate lowest sensitivity due to scarcity marketing and limited-release collaboration models.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for zipper hardware and PVC trim components concentrated in Zhejiang and Guangdong provinces. Assembly networks draw from Vietnam's Ho Chi Minh City industrial zones, China's Pearl River Delta coating facilities, and domestic U.S. cut-and-sew operations in Montana. Raw material dependencies rest on polyester yarn, carbon fiber leg mechanisms, and hard-shell composite resins. Distribution runs through pro shop bundles, specialty retailers, and manufacturer-owned fitting studios with direct-to-consumer channels gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rental and subscription-based equipment access models threaten ownership-based demand, requiring incumbents to defend replacement cycles through service intensity and customization value.
For Market Incumbents: Harden California retail access through accelerated phthalate-free reformulation timelines that preempt Office of Environmental Health Hazard Assessment enforcement actions. Deepen backward integration into domestic assembly capacity to insulate against ocean freight volatility and compress custom fitting turnaround. Channel control through limited-release collaboration models captures full retail markup from enthusiast segments while wholesale margin compression intensifies. For New Entrants and Emerging Players: Build out direct-to-consumer infrastructure targeting golf enthusiasts with scarcity-driven collaboration models that bypass established wholesale relationships. Vietnam's Binh Duong province offers the most penetrable manufacturing geography for cut-and-sew capacity with preferential tariff access. Position through ISO 9001 certification investment that unlocks major retail channel qualification within 12-18 month cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic U.S. manufacturers with captive supply chains and fitting network integration depth. Long-term viability rests on brands that control channel economics rather than volume-dependent Asian assembly specialists. Watch carbon fiber composite migration from tour-grade into mid-market offerings as the inflection signal for material science premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Phthalate-Free Reformulation Program | California Proposition 65 compliance preserves retail access across mass-market polyester supply chains. |
| Vietnam Assembly Footprint Expansion | Ho Chi Minh City industrial zones offer preferential tariff access and reduced U.S.-China trade friction exposure. |
| Direct-to-Consumer Channel Buildout | Limited-release collaboration models capture full retail markup from enthusiast segments bypassing wholesale compression. |
| Carbon Fiber Leg Mechanism Integration | Sub-three-pound carry specifications migrate from tour-grade into mid-market weekend amateur positioning. |
| ISO 9001 Certification Investment | Supplier qualification standard unlocks major retail channel access and accelerates new product introduction timelines. |
Study Parameters
A standing panel of brand product managers, polyester mill procurement leads, pro shop buyers, and club fitting network operators provided ongoing calibration across primary interview cycles. Secondary validation drew from U.S. Consumer Product Safety Commission filings, California Office of Environmental Health Hazard Assessment enforcement records, customs trade data, and SEC 10-K disclosures from sporting goods manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario bracketing anchored the analytical framework with low, base, and high cases reflecting participation rate trajectories and airline equipment recovery patterns. Segmentation dimensions modeled product type, material chemistry tier, end-user skill level, and regional regulatory cluster throughout the forecast period. CAGRs derived from historical replacement cycle analysis, club fitting network unbundling trends, and hard-shell travel bag adoption curves among frequent flyers.
Practitioners should monitor polyester feedstock volatility, REACH transparency mandate expansion, and airline dimension restriction updates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Quad Skate Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Gymnastic Hoops Market