
 Cleat Market | 2026-2036
Cleat Market Size, Share, and Industry Trends Forecast 2026-2036
Cleat Market Analysis
Specialized footwear engineering talent is bifurcating the competitive landscape, as brands with in-house biomechanics labs pull ahead of outsourced design models. Nike leverages vertical integration across its Oregon-based research campus to control prototyping cycles. Adidas sustains European manufacturing partnerships that anchor its premium leather cleat lines. Puma competes through aggressive positioning in emerging football markets with localized product development.
A cleat is a specialized athletic shoe featuring protruding studs or blades on its sole, typically constructed from thermoplastic polyurethane, carbon fiber, or injection-molded rubber compounds to maximize ground penetration and traction during directional changes. Its primary commercial purpose is to reduce slip-related injury incidence while enhancing power transfer during sprinting, cutting, and kicking motions across natural and artificial turf surfaces. Soccer cleats occupy the dominant revenue position due to the sport's global participant base, while synthetic materials represent the fastest-expanding segment as manufacturers substitute petroleum-based components with recycled polyester and bio-urethane alternatives. High-top footwear types command margin premiums among professional end users seeking enhanced ankle stabilization, though low-top designs retain volume leadership in youth and amateur categories.
The US Consumer Product Safety Commission and California's Proposition 65 framework govern chemical disclosure requirements for rubber and synthetic components, while the EU REACH regulation restricts phthalate content in youth-sized cleats, directly shaping material selection across supply chains. ASTM International standards for sports equipment further define performance testing protocols that brands must satisfy for retail distribution in North America. Stakeholders must monitor how evolving state-level extended producer responsibility laws in the US and EU could mandate take-back programs for worn athletic footwear, fundamentally altering cost structures and reverse logistics requirements.
Market Dynamics
EU REACH phthalate restrictions and California Proposition 65 disclosure mandates are forcing wholesale material substitutions across synthetic cleat supply chains, compressing formulation cycles and elevating compliance costs for mid-tier manufacturers.
Growth Catalysts
- Bio-based polyurethane R&D:European manufacturers accelerate plant-derived thermoplastic development to satisfy EU Green Deal procurement criteria for public-sector sports programs.
- Brazilian youth academy density:Grassroots football infrastructure sustains volume demand for molded-rubber entry-level cleats through consistent replacement cycles.
- ASTM F2336 traction testing:Standardized performance protocols enable North American retailers to justify premium pricing for certified high-grip configurations.
Market Restraints
- Petrochemical input volatility:Thermoplastic polyurethane resin costs fluctuate with crude oil benchmarks, squeezing margin predictability for injection-molded sole unit producers.
- Carbon fiber supply concentration:Japanese and South Korean precursor manufacturers control high-modulus fiber output, creating bottleneck risk for lightweight plate components.
- Leather tanning regulatory friction:Chromium VI restrictions under REACH Annex XVII limit European sourcing options for traditional kangaroo and calfskin uppers.
Strategic Opportunities
- Indian synthetic turf expansion:Municipal sports infrastructure investments in Maharashtra and Karnataka create demand for multi-stud configurations optimized for artificial surfaces.
- Take-back program mandates:Extended producer responsibility pilots in France and the Netherlands position early movers to capture circular economy subsidies for recycled rubber recovery.
- Biomechanics-AI convergence:Pressure-mapping insoles paired with machine learning gait analysis enable mass-customization at price points previously reserved for professional contracts.
Industry Challenges
- Computational footwear engineering talent scarcity:Finite element analysis specialists command salary premiums that exclude smaller brands from simulation-driven prototyping.
- Multi-jurisdiction certification timelines:Simultaneous ASTM, CE marking, and ISO 10321 compliance testing extends product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleat Market |
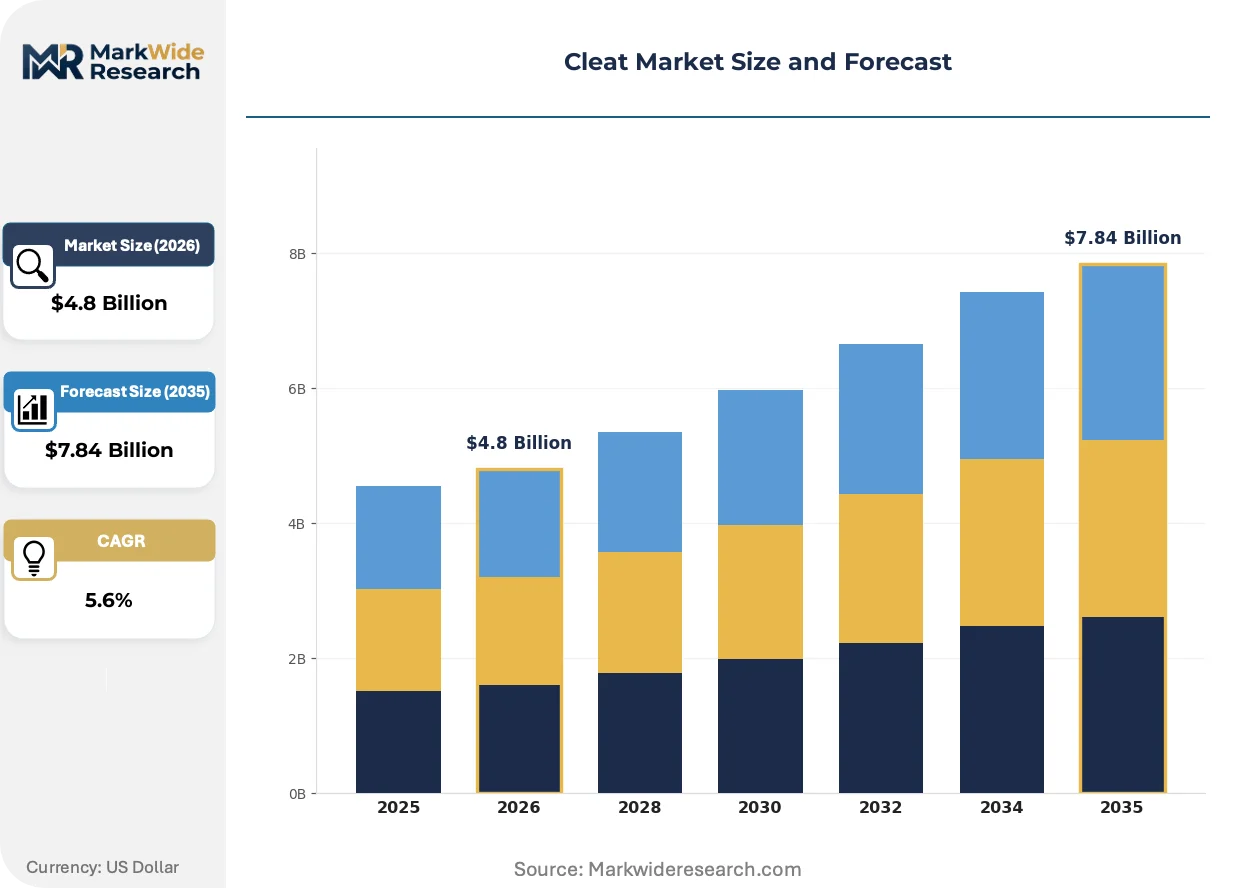
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soccer Cleats, Football Cleats, Baseball Cleats, Track Cleats Material: Leather, Synthetic, Rubber, Mesh Footwear Type: High-Top, Low-Top, Mid-Top, Turf End User: Adults, Youth, Women, Professionals |
| Companies Covered | New Balance, Under Armour, Nike, Skechers, Asics, Adidas, Mizuno, KSwiss, Puma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleat Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure requirements are compressing traditional design-to-retail timelines while fragmenting competitive advantage across specialized technical capabilities rather than brand scale alone.
Knitted synthetic uppers woven from recycled polyethylene terephthalate yarn are displacing conventional synthetic leather overlays in mid-tier soccer cleat lines. Amateur league players in Germany and the Netherlands adopt these configurations for moisture management benefits. The shift is displacing legacy cut-and-stitch manufacturing equipment from tier-two Asian contract facilities.
California's Proposition 65 enforcement expansion now requires explicit labeling for 1,3-butadiene content in rubber outsoles sold through US retail channels. Brands must reformulate styrene-butadiene rubber compounds or absorb litigation exposure costs. Youth-sized cleat distributors face the steepest compliance burden due to heightened chemical sensitivity thresholds for under-12 product categories.
Direct-to-academy procurement models bypass traditional sporting goods retail intermediaries in Brazilian and Argentine football development systems. Professional club youth divisions negotiate volume contracts with manufacturers for position-specific stud configurations. This channel compression is most advanced in São Paulo state, where four major clubs consolidated footwear purchasing through collective tender processes.
Cleat Market Segmentation
Cleat manufacturers navigate divergent performance requirements across sport-specific biomechanics, material compliance regimes, and age-group safety thresholds. Segmentation strategy determines which formulation investments and certification pathways yield sustainable margin protection against substitute footwear categories.
Product Type:
Soccer cleats face the most intense substitution pressure from multi-purpose athletic trainers, as casual players increasingly favor versatile footwear for mixed-surface recreational use.
- Soccer Cleats:Engineered with conical or bladed stud configurations optimized for rotational agility on natural grass. Brazilian youth academies and German amateur leagues sustain replacement demand through position-specific procurement programs.
- Football Cleats:Feature detachable screw-in studs and reinforced toe boxes for explosive linear acceleration. North American high school and collegiate programs anchor volume through standardized team purchasing agreements.
- Baseball Cleats:Prioritize lateral stability with molded rubber or metal spike options for diamond-specific traction. Metal configurations face restrictions in youth leagues, compressing addressable market scope.
- Track Cleats:Utilize ultra-lightweight spike plates with replaceable pyramidal pins for sprint and distance events. Niche participant bases limit production scale economies relative to field sports categories.
Soccer cleats retain volume leadership; track cleats hold the steepest expansion curve among specialized athletic applications.
Material:
Cost tier stratification separates premium heritage positioning from mass-market synthetic alternatives, with mid-tier leather products experiencing the sharpest demand erosion.
- Leather:Full-grain kangaroo and calfskin uppers deliver superior mold-to-foot customization and moisture absorption. REACH Annex XVII chromium VI restrictions constrain European sourcing, elevating compliance costs for traditional constructions.
- Synthetic:Thermoplastic polyurethane and polyethylene terephthalate formulations enable consistent colorways and weather resistance. Plant-derived bio-urethane variants are gaining procurement preference under EU Green Deal public-sector tender criteria.
- Rubber:Injection-molded outsole compounds provide durability for entry-level molded cleat configurations. California Proposition 65 disclosure mandates for 1,3-butadiene content are forcing compound reformulation across US-bound production lines.
- Mesh:Knitted synthetic uppers woven from recycled yarn displace conventional overlays in moisture-management-focused designs. German and Dutch amateur leagues are adopting these configurations for training-ground comfort.
Synthetic materials retain volume leadership; bio-based polyurethane variants are climbing the fastest among compliant formulation investments.
Footwear Type:
Application-specific ankle support requirements fragment demand across injury-prevention priorities versus speed-to-weight optimization tradeoffs.
- High-Top:Extended collar constructions stabilize the ankle mortise during cutting and landing sequences. Professional contracts in North American football and basketball-cleat crossovers justify margin premiums for medical-grade stabilization.
- Low-Top:Minimal collar profiles maximize dorsiflexion range and reduce overall mass for speed-position players. Youth and amateur categories dominate volume through price-accessible molded configurations.
- Mid-Top:Hybrid collar heights balance mobility and support for multi-position utility players. Secondary demand concentration exists among recreational athletes seeking single-pair versatility.
- Turf:Shortened stud patterns and flattened sole plates optimize traction on artificial infill surfaces. Municipal synthetic field expansion in Maharashtra and Karnataka is driving configuration-specific demand.
Low-top designs retain volume leadership; turf-optimized constructions are gaining share fastest among surface-specific adaptations.
End User:
Customer type segmentation reveals divergent price elasticity and safety regulatory exposure across age and performance tiers.
- Adults:Self-directed purchasers prioritize performance specifications and brand affiliation over price constraints. Competitive league participation sustains replacement cycles at 12-to-18-month intervals.
- Youth:Rapid foot growth necessitates frequent resizing, compressing usable product lifespan. Heightened chemical sensitivity thresholds under REACH and CPSC frameworks impose stricter material certification burdens.
- Women:Anatomical last engineering for narrower heel cups and adjusted arch profiles addresses biomechanical differentiation. Emerging product development investment is narrowing historical unisex design gaps.
- Professionals:Custom-fitted configurations with position-specific stud maps and personalized insole molding command contract-based procurement. São Paulo state club collectives are consolidating tender processes for academy-to-first-team pipeline supply.
Adult recreational users retain volume leadership; professional contract tiers are expanding most quickly among margin-accretive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Brazilian youth academies burn through molded-rubber entry cleats in six-month replacement cycles, while German amateur leagues prioritize bio-based polyurethane uppers for municipal procurement compliance.
United States
North American high school and collegiate programs anchor volume through standardized team purchasing agreements. ASTM F2336 traction testing protocols enable retailers to justify premium pricing for certified configurations. California's Proposition 65 enforcement expansion now mandates explicit 1,3-butadiene labeling for rubber outsoles, forcing compound reformulation across US-bound production lines.
Brazil
Grassroots football infrastructure sustains consistent demand for entry-level molded cleats through rapid replacement cycles. São Paulo state club collectives have consolidated footwear purchasing through collective tender processes, compressing intermediary margins. Youth academy density in the Southeast region generates position-specific procurement for academy-to-first-team pipeline supply.
Germany
Amateur league players adopt knitted synthetic uppers woven from recycled polyethylene terephthalate yarn for moisture management benefits. EU REACH Annex XVII chromium VI restrictions constrain traditional leather sourcing, elevating compliance costs for conventional constructions. The Bavaria-Rhineland manufacturing corridor hosts specialized thermoplastic polyurethane formulation facilities serving premium product lines.
India
Municipal sports infrastructure investments in Maharashtra and Karnataka create demand for multi-stud configurations optimized for artificial turf surfaces. The country's national sports equipment regulator aligns with BIS standards for youth-sized product safety thresholds. Synthetic turf expansion in Mumbai and Bangalore metropolitan clusters drives surface-specific cleat procurement.
Netherlands
Extended producer responsibility pilots position early movers to capture circular economy subsidies for recycled rubber recovery. EU Green Deal procurement criteria for public-sector sports programs accelerate plant-derived bio-urethane adoption. The Randstad logistics hub facilitates reverse logistics infrastructure for take-back program experimentation.
Cleat Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated competitive structure. The upper tier controls in-house biomechanics research and captive manufacturing assets, while mid-tier players rely on outsourced design models and Asian contract facilities. Three strategic archetypes dominate: vertically integrated performance brands with proprietary research campuses, European heritage manufacturers anchored in premium leather traditions, and emerging-market specialists competing through localized product development. Competitive moves concentrate on backward integration into thermoplastic formulation and strategic partnerships with synthetic turf infrastructure providers.
Within the integrated leader tier, Nike and Adidas exemplify divergent geographic anchoring strategies. Nike leverages its Oregon-based research campus for prototyping cycle control, while Adidas sustains European manufacturing partnerships for premium leather lines. Puma occupies a position within the emerging-market specialist archetype, competing through aggressive positioning in football-intensive geographies with localized development capabilities. Under Armour and New Balance sit within the North American performance tier, representing the specialist fabricator model focused on collegiate and professional contract procurement.
| Leading Market Players |
|---|
| New Balance |
| Under Armour |
| Nike |
| Skechers |
| Asics |
| Adidas |
| Mizuno |
| KSwiss |
| Puma |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month product launch windows from concept to retail shelf concentrate pricing power with vertically integrated incumbents who control captive thermoplastic formulation capacity. This lead-time compression shapes margin structures: brands with in-house biomechanics labs capture premium positioning while outsourced design models absorb compliance cost volatility.
Pricing Analysis
Contract-based long-term offtake agreements between Brazilian club collectives and manufacturers anchor volume tiers, while spot procurement through traditional sporting goods retail channels serves fragmented amateur demand. Price differentiation rests on certification grade—ASTM F2336 traction certification commands retail premiums—and volume scale, with academy collective tenders securing 15-20 point discounts. Cost compression in mid-tier synthetic lines is intensifying because REACH phthalate reformulation elevates R&D amortization. Youth-sized cleat buyers exhibit highest price sensitivity due to six-month replacement cycles, while professional contract tiers prioritize performance specifications over unit economics.
Supply Chain Analysis
Strategic stockpiling of thermoplastic polyurethane resin prevails among Japanese and South Korean carbon fiber precursor manufacturers, buffering against petrochemical input volatility. Raw material dependencies draw from German thermoplastic formulation facilities, Vietnamese cut-and-stitch assembly plants, and Brazilian molded-rubber compounders. Single-source vulnerability concentrates in high-modulus carbon fiber plate components. Distribution runs through direct-to-academy procurement channels in São Paulo state and traditional retail intermediaries in North American collegiate markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU REACH compliance and ASTM certification creates durable defensive moats: incumbent brands with established testing protocols face asymmetric switching costs that emerging competitors cannot replicate without 8-14 month launch delays.
For Market Incumbents: Compound biomechanics-AI convergence capabilities through pressure-mapping insole development to defend against emerging direct-to-academy challengers. Prioritize backward integration into bio-urethane formulation to capture EU Green Deal procurement preference. Extend certification investment into Indian BIS alignment ahead of municipal synthetic turf expansion. For New Entrants and Emerging Players: Lead with turf-optimized configurations targeting Maharashtra and Karnataka municipal infrastructure investments, the most penetrable geography given surface-specific demand gaps. Position around recycled rubber recovery services to capture Netherlands extended producer responsibility subsidies. Pursue white-label academy supply contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from European heritage manufacturers with premium leather traditions but stranded compliance costs under REACH Annex XVII chromium VI restrictions. Five-to-ten year viability hinges on bio-based material transition execution. Watch for biomaterials certification acceleration as the inflection signal warranting re-evaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Urethane Formulation | Captures EU Green Deal procurement preference for public-sector sports programs. |
| Direct-to-Academy Channel Expansion | Bypasses retail intermediaries in São Paulo state collective tender processes. |
| ASTM F2336 Certification Investment | Enables premium pricing justification for high-grip configurations in North America. |
| Recycled Rubber Recovery Infrastructure | Positions for circular economy subsidies under Netherlands EPR pilots. |
| Biomechanics-AI Convergence Development | Enables mass-customization at price points previously reserved for professional contracts. |
Methodological Framework
Operator-level perspectives from footwear procurement managers at Brazilian club academies, thermoplastic formulation engineers in Bavaria-Rhineland, ASTM compliance testing laboratory directors, and sporting goods retail category buyers anchored the qualitative base. Secondary validation drew from customs records, EU ECHA substance restriction updates, SEC 10-K footwear segment disclosures, and municipal sports infrastructure tender databases. Bottom-up demand modeling across academy replacement cycles and retail sell-through data triangulated against top-down market sizing from synthetic material consumption patterns.
Sensitivity analysis tested volume and value outputs across the projection horizon against petrochemical price volatility bands and regulatory enforcement intensity scenarios. Segmentation dimensions modeled include product type, material formulation tier, footwear collar height, end-user age category, and surface-specific configuration. CAGRs were derived from replacement cycle frequency analysis and procurement program expansion rates. Industry-specific forecast inputs incorporated synthetic turf installation trajectories in Indian metropolitan clusters and REACH Annex XVII amendment timelines.
Forecasts assume regulatory continuity in EU REACH, US CPSC, and California Proposition 65 frameworks; material policy shifts would require re-modeling. Forecasts reflect assumptions of academy procurement program stability and petrochemical input band containment. Revision becomes warranted when bio-based material cost parity crosses threshold viability against petroleum-derived alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Power Sports Aftermarket Market