
 Pitching Machine Market | 2026-2036
Pitching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pitching Machine Market Analysis
Sensor-enabled pitch analytics is reconfiguring how manufacturers engineer feedback loops into training equipment. JUGS Sports leverages decades of institutional brand recognition to sustain dominant placement across collegiate athletic departments. Sports Attack differentiates through wheel-based propulsion systems that anchor its professional-team installed base. Bata competes on portable pneumatic designs that extend its reach into emerging baseball markets across Latin America.
A pitching machine is a mechanical or electromechanical device engineered to propel baseballs or softballs at calibrated velocities, spin rates, and trajectories for batting and fielding practice, typically employing one-armed catapult, two-wheel friction, or compressed-air launch mechanisms with adjustable pitch speeds from 20 to 100-plus miles per hour. Baseball-configured machines occupy the largest revenue pool due to entrenched demand from MLB-affiliated training facilities and Division I programs. Electric technology leads unit shipments while hybrid systems integrating manual override with programmable motors represent the fastest-expanding margin segment. Schools constitute the most price-sensitive end-user channel, whereas professional teams concentrate spending on premium dual-use units with real-time biomechanical feedback.
OSHA workplace safety standards govern manufacturing facility compliance for domestic producers, while FCC certification requirements apply to wireless-enabled machines transmitting pitch data via Bluetooth or Wi-Fi protocols. Consumer Product Safety Commission guidelines shape liability frameworks and influence design specifications for youth-accessible equipment. Stakeholders must monitor evolving state-level athletic equipment procurement standards and assess whether embedded software triggers additional cybersecurity compliance obligations as connected training devices proliferate.
Market Dynamics
Programmable motor systems and embedded sensor arrays are compressing replacement cycles across institutional procurement channels. Athletic departments now prioritize machines with integrated biomechanical feedback over legacy mechanical units.
Growth Catalysts
- Youth League Expansion:Municipal recreation departments across Texas, Florida, and California are outfitting multi-field complexes with programmable training equipment. Public bond funding for athletic infrastructure is accelerating.
- Bluetooth-Enabled Customization:Wireless pitch programming allows coaches to sequence fastball-curveball-changeup combinations from dugout tablets. FCC certification for 2.4 GHz transmission protocols has streamlined hardware deployment.
- OSHA Manufacturing Compliance:Domestic producers leveraging automated assembly lines meet workplace safety standards more efficiently than offshore competitors. This regulatory alignment shortens delivery timelines for institutional buyers.
Market Restraints
- Aluminum and Steel Input Volatility:Wheel housing and frame fabrication depends on commodity metal pricing. Foundry capacity concentration in the industrial Midwest creates geographic supply risk.
- Pneumatic System Complexity:Compressed-air launch mechanisms require precise valve calibration. Maintenance skill scarcity at high school athletic departments limits adoption outside premium segments.
- Product Liability Exposure:Consumer Product Safety Commission guidelines for youth-accessible equipment impose design constraints. Insurance underwriting for recreational use cases has tightened.
Strategic Opportunities
- Latin American Baseball Infrastructure:Dominican Republic and Venezuelan training academies lack programmable equipment penetration. Portable pneumatic designs suit facilities without reliable electrical infrastructure.
- Cricket Cross-Application:Wheel-based propulsion systems adapt to cricket ball delivery with software recalibration. Commonwealth nations with dual-sport facilities represent untapped hardware utilization.
- State Athletic Equipment Grants:Georgia and Arizona have enacted dedicated funding streams for high school program modernization. Procurement officers prioritize connected training devices eligible for technology infrastructure allocations.
Industry Challenges
- Embedded Software Cybersecurity:Connected machines transmitting pitch data via Wi-Fi protocols face evolving state-level data protection standards. Manufacturers must assess whether firmware updates trigger additional compliance obligations.
- Biomechanical Sensor Calibration:Real-time swing analysis integration requires specialized technician deployment. Service network density lags behind hardware installation rates in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pitching Machine Market |
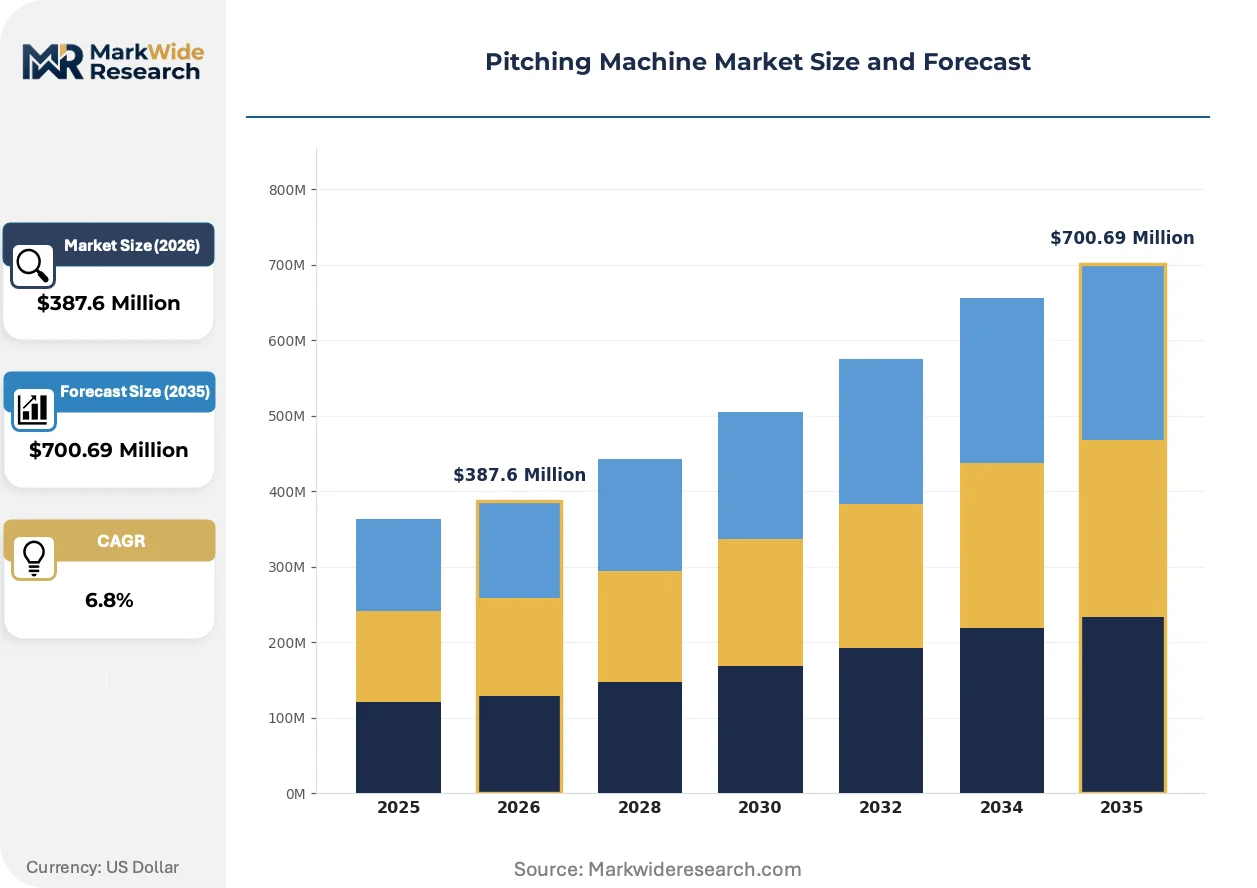
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseball, Softball, Dual-Use, Mobile Technology: Electric, Manual, Pneumatic, Hybrid End User: Schools, Clubs, Professional Teams, Individual Players Service Type: Rental, Sale, Maintenance, Support |
| Companies Covered | Bata, Hack Attack, JUGS Sports, Sports Attack, Sports Tutor, Atec, Iron Mike, MasterPitch, Heater Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pitching Machine Market Emerging Trajectories
Digital twin interfaces and cloud-connected performance databases are redefining how training value is captured and monetized. Hardware manufacturers are repositioning as subscription-enabled platform providers.
Machine learning algorithms embedded in sensor arrays is virtualizing the role of human pitching coaches in repetitive drill settings. Division I programs are deploying these systems for off-hours player development. The technology compresses labor costs while standardizing pitch sequence variety.
OSHA workplace safety standards for electromechanical equipment manufacturing have tightened inspection protocols for domestic assembly facilities. Producers must document motor housing integrity and emergency stop functionality. Smaller fabricators without dedicated compliance staff face certification timeline extensions.
Leasing arrangements with bundled maintenance and software updates are displacing outright equipment purchases at budget-constrained school districts. Third-party athletic equipment financiers are entering the channel with specialized knowledge of grant-eligible procurement structures. This shift concentrates most visible in Sun Belt states with year-round program utilization.
Pitching Machine Market Segmentation
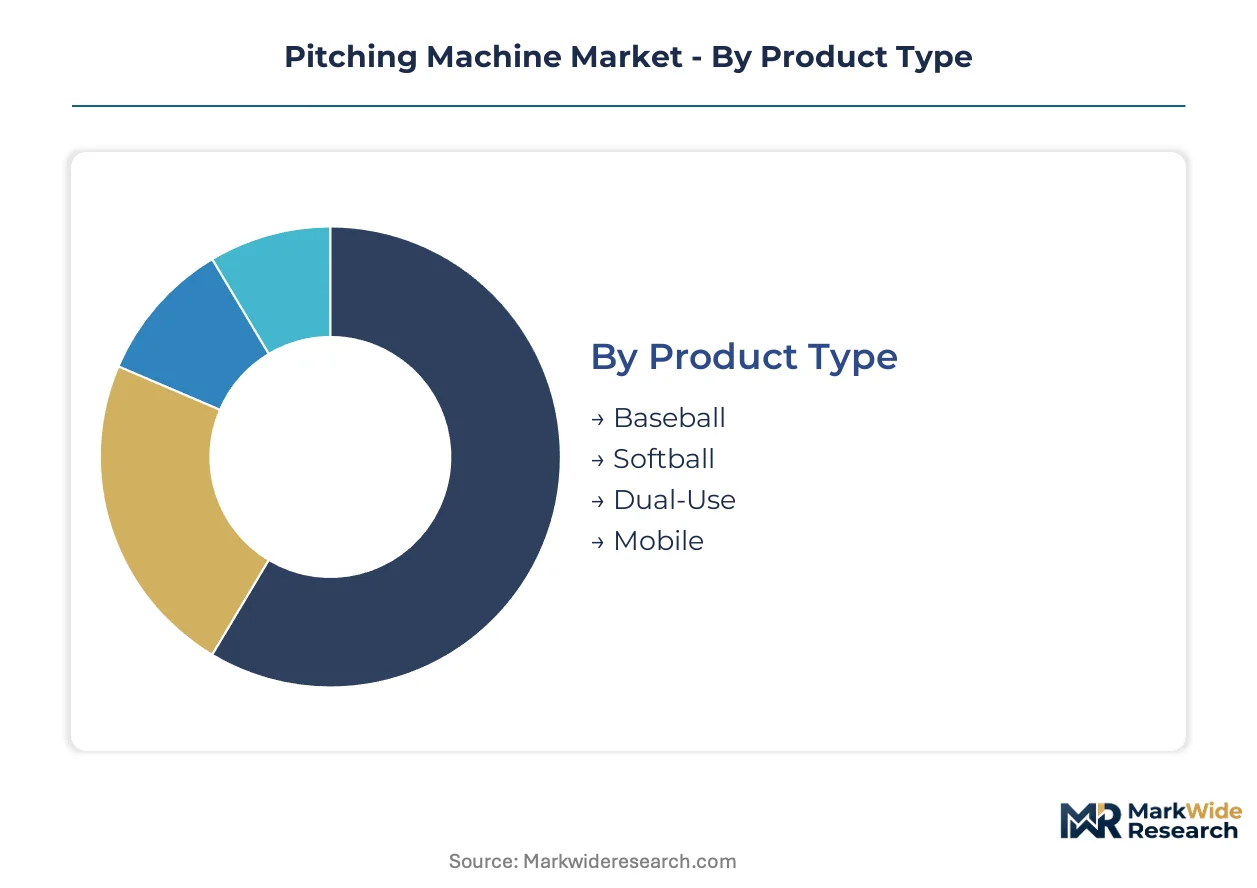
Pitching machine manufacturers engineer product portfolios around four distinct segmentation axes. Each dimension captures different procurement priorities, from institutional budget cycles to portable training requirements across diverse facility types.
Product Type:
Application context determines frame geometry, ball carriage mechanisms, and trajectory calibration ranges across the four product configurations.
- Baseball:Wheel-based propulsion systems dominate this configuration, with dual-wheel friction drives generating calibrated velocities from 20 to 100-plus miles per hour. Demand concentrates at MLB-affiliated training facilities and Division I programs across Texas and Florida, where year-round outdoor seasons justify premium capital expenditure on programmable units with real-time biomechanical feedback.
- Dual-Use:Adjustable ball carriage and interchangeable wheel surfaces accommodate both regulation baseballs and softballs within a single chassis. High school athletic departments in Georgia and Arizona prioritize these units for grant-eligible technology infrastructure allocations, consolidating procurement budgets across multiple sports programs.
- Softball:Lower velocity ceilings and larger ball aperture designs suit fastpitch training regimens at municipal recreation complexes.
- Mobile:Collapsible frames and battery-powered operation enable field-to-field repositioning without electrical infrastructure.
Baseball configurations command the established revenue base. The steepest expansion runs through dual-use systems as budget-constrained institutions consolidate procurement.
Technology:
Power source and motor architecture segment procurement channels by maintenance capability, electrical reliability, and programmable feature depth.
- Electric:Programmable motor systems with embedded sensor arrays lead unit shipments across institutional channels. These units integrate Bluetooth-enabled pitch sequencing and cloud-connected performance databases, compressing replacement cycles at collegiate athletic departments that prioritize biomechanical feedback over legacy mechanical alternatives.
- Hybrid:Manual override combined with programmable motors represents the margin-expanding frontier, allowing coaches to revert to direct control during connectivity interruptions. FCC certification for 2.4 GHz transmission protocols has streamlined hardware deployment for wireless-enabled variants in Sun Belt states.
- Pneumatic:Compressed-air launch mechanisms require precise valve calibration and maintenance skill scarcity limits adoption outside premium segments.
- Manual:Spring-tension catapult designs persist in entry-level youth league applications with minimal electrical infrastructure.
Electric systems anchor current procurement volumes. Hybrid architectures are climbing the fastest as institutions seek resilience against connectivity failures.
End User:
Customer type stratifies pricing tolerance, feature requirements, and service contract structures across the value chain.
- Professional Teams:Premium dual-use units with real-time biomechanical feedback concentrate spending at MLB-affiliated training facilities. These buyers demand integrated sensor calibration, specialized technician deployment, and bundled maintenance agreements that standardize pitch sequence variety while compressing labor costs.
- Schools:Municipal bond funding and state athletic equipment grants shape procurement timing, with Georgia and Arizona enacting dedicated funding streams for high school program modernization. Price sensitivity drives leasing arrangements with bundled software updates over outright purchase.
- Clubs:Youth baseball academies and private training facilities balance portability against programmable depth.
- Individual Players:Compact electric units with simplified controls serve backyard training environments.
Professional teams maintain premium positioning. School districts are gaining share fastest as public infrastructure funding accelerates across Sun Belt states.
Service Type:
Commercial model selection reflects capital availability, utilization intensity, and technical service network density in regional markets.
- Sale:Outright equipment purchase persists at professional facilities with dedicated maintenance staff and high utilization rates that justify depreciation schedules.
- Rental:Third-party athletic equipment financiers are entering the channel with specialized knowledge of grant-eligible procurement structures, displacing ownership at budget-constrained districts.
- Maintenance:Service contracts covering valve calibration, sensor recalibration, and firmware updates address skill scarcity at high school athletic departments.
- Support:Technical assistance subscriptions include remote diagnostics and software update distribution for connected training devices.
Direct sales retain dominance at premium tiers. Rental arrangements are expanding most quickly as specialized financiers penetrate institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional training facilities and collegiate athletic departments concentrate procurement across Sun Belt states with year-round outdoor seasons. Municipal bond funding and state athletic equipment grants are accelerating institutional purchases. Portable pneumatic designs are penetrating emerging baseball markets lacking reliable electrical infrastructure.
United States
Texas, Florida, and California municipal recreation departments are outfitting multi-field complexes with programmable training equipment. OSHA workplace safety standards govern domestic manufacturing facility compliance. Atlanta and Phoenix school districts are leveraging Georgia and Arizona state athletic equipment grants to modernize high school programs with connected training devices.
Dominican Republic
MLB-affiliated training academies are expanding programmable equipment procurement for player development infrastructure. The country's national sports ministry oversees athletic facility standards and import certification for electromechanical devices. Santo Domingo-based academies are adopting portable pneumatic designs to overcome electrical grid reliability constraints in rural training complexes.
Japan
Collegiate baseball programs and professional farm systems are integrating sensor-enabled feedback systems into daily training regimens. METI standards for electromechanical equipment manufacturing shape import requirements for connected training devices. Osaka and Nagoya industrial clusters host fabrication facilities supplying wheel-based propulsion components to regional equipment assemblers.
Australia
Cricket training facilities are adapting wheel-based propulsion systems for cricket ball delivery through software recalibration. The country's national standards body governs electromechanical equipment safety certification for institutional procurement. Melbourne and Sydney sporting complexes are deploying dual-use units capable of serving both cricket and baseball training programs.
Mexico
Youth baseball academies in northern border states are expanding equipment procurement to serve cross-border training pipelines. The national consumer protection agency oversees product liability frameworks for youth-accessible athletic equipment. Monterrey and Guadalajara industrial zones are developing assembly capacity for pneumatic systems targeting Latin American markets without reliable electrical infrastructure.
Pitching Machine Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Institutional athletic departments and professional training facilities sustain premium pricing for integrated feedback systems. Three archetypes dominate: legacy manufacturers with decades of brand recognition, wheel-based propulsion specialists, and portable pneumatic designers. Competitive moves concentrate on Bluetooth-enabled customization integration and Latin American geographic expansion.
Within the established manufacturer tier, JUGS Sports and Sports Attack exemplify divergent technical approaches to institutional market penetration. Bata occupies a position among portable equipment designers targeting emerging markets with infrastructure constraints. These three anchors demonstrate how brand heritage, propulsion architecture, and portability priorities segment competitive positioning across professional, collegiate, and youth league procurement channels.
| Leading Market Players |
|---|
| Bata |
| Hack Attack |
| JUGS Sports |
| Sports Attack |
| Sports Tutor |
| Atec |
| Iron Mike |
| MasterPitch |
| Heater Sports |
| Others |
Supply Flow & Price Mechanics
Port of Los Angeles to Dallas freight corridors are absorbing elevated container rates that compress margins for Midwest fabricators supplying wheel housing assemblies to institutional buyers. This logistics cost dynamic concentrates pricing power with domestic producers meeting OSHA workplace safety standards, while forcing Sun Belt municipal purchasers into longer procurement cycles that differentiate premium programmable units from standard electric alternatives.
Pricing Analysis
Cost-plus contracts with aluminum and steel indexation dominate institutional procurement, anchoring unit prices to commodity metal fluctuations from Midwest foundries. Price differentiation separates MLB-affiliated facilities prioritizing real-time biomechanical feedback from budget-constrained school districts selecting leasing arrangements. Pricing pressure stems from maintenance skill scarcity at high school athletic departments, which limits adoption outside bundled service tiers. Schools exhibit highest price sensitivity, while professional teams absorb premium positioning for dual-use configurations.
Supply Chain Analysis
Export-control restrictions on embedded sensor arrays and Bluetooth-enabled firmware complicate component flows from Japanese fabrication clusters to domestic assembly facilities. Supply concentration centers on Ohio and Indiana for wheel-based propulsion systems, Taiwan for programmable motor controllers, and Mexico for pneumatic valve assemblies. Raw material dependencies include aircraft-grade aluminum, hardened steel alloys, and lithium-ion battery cells. Single-source vulnerability runs through Midwest foundry capacity for frame fabrication. Distribution runs through specialized athletic equipment financiers penetrating institutional channels with grant-eligible procurement expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable motor systems and embedded sensor arrays are compressing replacement cycles across institutional procurement, creating a high-growth disruption justified by FCC certification streamlining for 2.4 GHz transmission protocols in connected training devices.
For Market Incumbents: Build switching-cost moats through proprietary cloud-connected performance databases that lock Division I programs into subscription-enabled platform ecosystems. Defensive moves center on acquiring specialized technician networks for biomechanical sensor calibration and deepening backward integration into programmable motor controller production. The threat of portable pneumatic designers from Latin American markets requires preemptive channel control across Dominican and Venezuelan training academies. For New Entrants and Emerging Players: Build out service network density in secondary Sun Belt markets where real-time swing analysis integration lags hardware installation rates. White-space targets include Georgia and Arizona school districts leveraging state athletic equipment grants for technology infrastructure modernization. Cricket cross-application in Commonwealth dual-sport facilities offers the most penetrable application segment. A direct-to-athletic-department go-to-market angle bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Portable pneumatic designers with established Latin American distribution and battery-powered operation capabilities represent the priority acquisition archetype. Long-term viability frames around five-to-ten year infrastructure buildout across emerging baseball markets lacking reliable electrical grids. The signal to watch is municipal bond funding velocity for multi-field complex development across Texas, Florida, and California public recreation departments.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth-Enabled Customization Integration | FCC certification for 2.4 GHz protocols streamlines wireless pitch programming deployment across Sun Belt institutional buyers. |
| Latin American Geographic Expansion | Portable pneumatic designs penetrate Dominican and Venezuelan academies facing electrical grid reliability constraints. |
| Leasing Arrangement Penetration | Third-party financiers with grant-eligible procurement expertise displace outright purchases at budget-constrained school districts. |
| Biomechanical Sensor Calibration Networks | Specialized technician deployment addresses maintenance skill scarcity limiting adoption at high school athletic departments. |
| Cricket Cross-Application Development | Software recalibration of wheel-based propulsion systems unlocks Commonwealth dual-sport facility utilization in Australia. |
Methodological Framework
The analysis maps wheel-based propulsion, pneumatic launch, and programmable electric sub-sectors, each validated through athletic equipment procurement officers, collegiate coaching staff, and municipal recreation directors. Primary interviews with maintenance technicians at high school athletic departments and aftermarket service heads at institutional distributors combined with secondary validation from FCC equipment authorization databases, OSHA workplace safety inspection records, and state athletic equipment grant disbursement filings. Bottom-up unit shipment modeling and top-down revenue triangulation anchored segmentation-specific growth trajectories.
Assumption sets held metal commodity pricing bands and institutional procurement cycle timing fixed while varying youth league expansion rates and connected device adoption curves across the projection horizon. Segmentation dimensions modeled include product configuration, power source architecture, end-user budget tier, and commercial model structure. CAGRs derived from replacement cycle compression analysis and grant funding velocity projections, with inputs from Bluetooth protocol penetration rates and biomechanical feedback integration timelines.
Stress conditions across aluminum and steel input volatility, municipal bond funding availability, and embedded software cybersecurity compliance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about institutional buyer prioritization of integrated feedback systems over legacy mechanical units. Material shifts in state-level data protection standards for connected training devices would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Quad Skate Market
Sports Equipment
Ladderball Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Athletic Mask Market