
 Europe Winter Sports Equipment Market | 2026-2036
Europe Winter Sports Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Winter Sports Equipment Market Foresight
Multi-source carbon fiber procurement is shifting toward regional European suppliers as manufacturers seek to reduce dependency on Asian precursor imports. Amer Sports Oyj leverages its integrated supply chain across Finland and Austria to control quality from raw material to finished ski. Groupe Rossignol anchors its production footprint in France with vertically integrated composite molding operations. HEAD Sport GmbH competes through precision-engineered binding systems that integrate with its ski and snowboard lines.
Europe winter sports equipment encompasses engineered composite structures, metal-edged sliding platforms, protective gear, and thermal accessories designed for snow and ice-based recreational and competitive activities. Skis and snowboards typically incorporate layered constructions of fiberglass, carbon fiber, or wood cores with sintered polyethylene bases and steel edges for controlled glide and turn initiation on groomed slopes and variable terrain. The product type dimension shows skis maintaining volume leadership while snowboard demand stabilizes among younger recreational players. The end user dimension reveals professional athletes and clubs driving premium equipment replacement cycles, whereas schools represent an underdeveloped institutional channel with concentrated procurement in Alpine nations.
CE marking requirements under the EU's Personal Protective Equipment Regulation govern helmet and glove safety standards, while REACH compliance constrains chemical treatments used in waterproofing membranes and base coatings. The F-Gas Regulation phases down fluorinated wax compounds historically applied to ski bases, compelling manufacturers to reformulate glide treatments. Austria's national standards body and France's consumer safety agency coordinate enforcement of these frameworks across their respective ski manufacturing clusters. Stakeholders must monitor pending revisions to EU ecodesign criteria that could mandate recycled content minimums for equipment sold in member states.
Market Dynamics
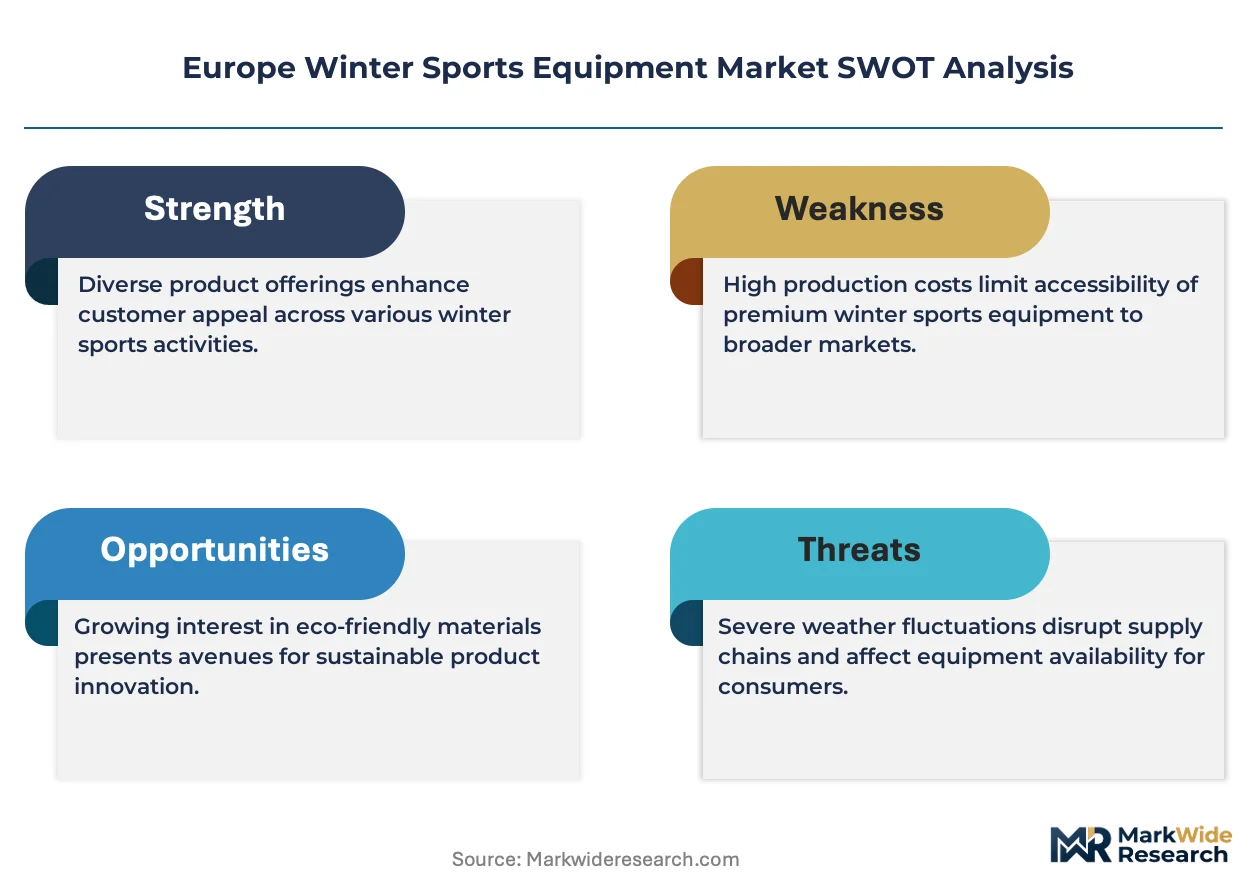
The EU Green Deal's ecodesign mandates are forcing composite ski manufacturers to requalify supply chains for recycled carbon fiber and bio-based epoxy resins ahead of anticipated recycled content minimums. This regulatory compression is reshaping procurement patterns across Alpine production clusters.
Growth Catalysts
- CE marking expansion under PPE Regulation:Mandatory helmet and protective gear certification is standardizing safety baselines across EU member states, elevating replacement demand among institutional buyers including French ski schools and Austrian alpine clubs.
- Alpine tourism infrastructure investment:Resort operators in France, Switzerland, and Austria are scaling rental fleet procurement to match visitor volume growth, creating contracted equipment refresh cycles.
- Carbon fiber regionalization:Manufacturers are qualifying European precursor suppliers to reduce Asian import dependency, shortening lead times for composite ski production.
Market Restraints
- REACH chemical compliance costs:Waterproofing membrane and base coating reformulations require extensive substance testing, elevating R&D overhead for mid-tier suppliers.
- Fluorinated wax phase-down under F-Gas Regulation:The ban on perfluorinated glide treatments is forcing base material reengineering without fully proven hydrocarbon alternatives.
- Energy-intensive composite molding:Autoclave curing and resin infusion processes face carbon cost pressure under EU Emissions Trading System expansion.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Slovakia show rising skier participation with limited domestic equipment manufacturing, creating import substitution openings.
- School and institutional procurement:Alpine nations are consolidating municipal and educational equipment purchasing through framework agreements, favoring vendors with rental-service capabilities.
- Bio-composite material convergence:Flax fiber and mycelium-core technologies are maturing to performance parity with synthetic composites for recreational-tier products.
Industry Challenges
- Composite technician skill scarcity:Hand-layup and resin transfer molding expertise is concentrating among aging workforces in French and Austrian manufacturing clusters.
- Multi-regulation certification timelines:Parallel CE marking, REACH dossier preparation, and national consumer safety agency approvals extend product launch cycles.
- Binding system integration complexity:Proprietary mounting standards across ski OEMs fragment aftermarket binding compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Winter Sports Equipment Market |
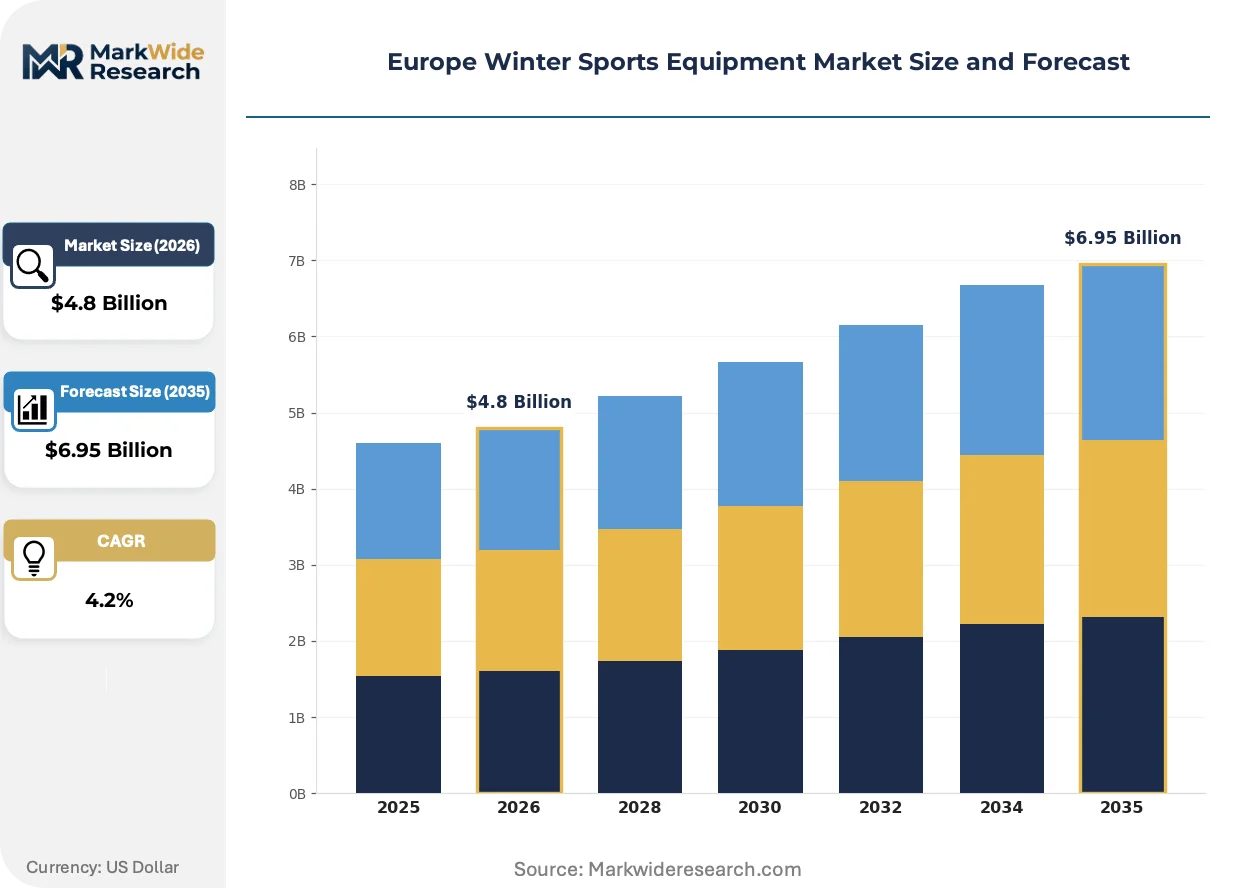
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skis, Snowboards, Ice Hockey Equipment, Gloves End User: Recreational Players, Professional Athletes, Schools, Clubs Material: Composite, Aluminum, Fiberglass, Steel Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Amer Sports Oyj, Groupe Rossignol, HEAD Sport GmbH, Fischer Sports GmbH, Tecnica Group SpA, Völkl, Atomic, Salomon, SCOTT Sports SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Winter Sports Equipment Market Shifts & Advancements
Digital design tools and sustainable material science are converging to compress product development cycles while satisfying tightening environmental compliance. Equipment vendors are repositioning around circular economy service models.
Generative design software is optimizing carbon fiber layup patterns for weight reduction and torsional rigidity. Premium ski manufacturers are adopting these tools to iterate prototypes faster. Topology optimization is converging with automated fiber placement to enable mass-customized ski geometries at production scale.
The F-Gas Regulation's phase-down of fluorinated ski wax compounds is compelling base material suppliers to reformulate glide surfaces. Manufacturers are accelerating hydrocarbon and ceramic additive research. Racing and high-performance recreational segments face the steepest performance adaptation curves as historical speed benchmarks become unattainable with compliant materials.
Rental fleet operators are unbundling equipment from lift-ticket packages and introducing subscription-based seasonal access models. This shifts capital burden from consumers to resort operators and distributors. French and Swiss alpine destinations are piloting these programs most aggressively, with equipment-as-a-service margins restructuring traditional retail channel economics.
Europe Winter Sports Equipment Market Segmentation
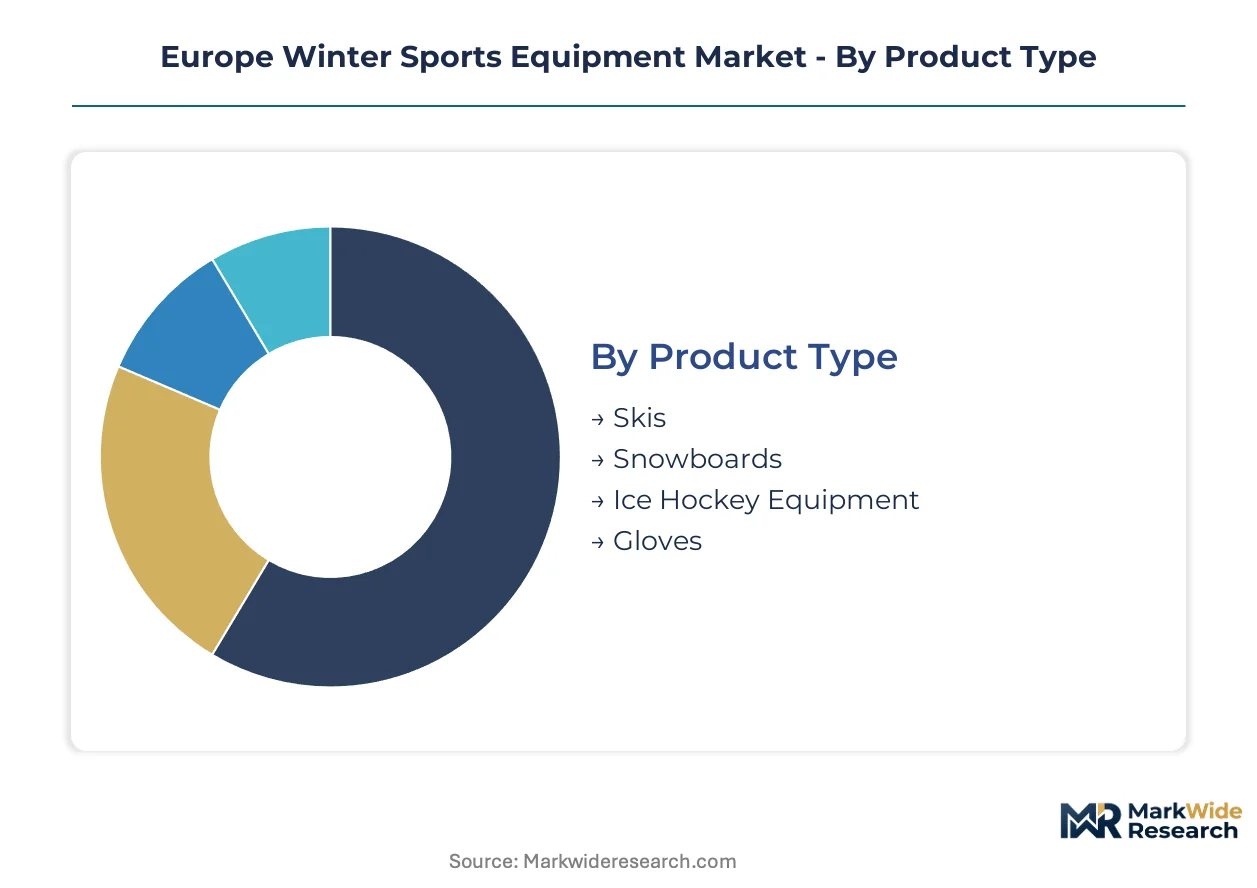
European winter sports equipment manufacturers calibrate product architectures to distinct performance tiers and institutional procurement cycles. Segment-specific material specifications and certification requirements determine margin structures across Alpine production clusters.
Product Type:
Layered composite constructions differentiate performance characteristics across sliding and protective equipment categories.
- Skis:Multi-layer sandwiches of wood cores, carbon fiber or fiberglass laminates, and sintered polyethylene bases with steel edges dominate Alpine corridor production. French and Austrian manufacturers concentrate volume in recreational carving geometries while racing-specific FIS-compliant constructions serve professional athlete replacement cycles.
- Snowboards:Directional and twin-tip profiles incorporate similar composite layups with differentiated sidecut radii for freestyle versus freeride disciplines. Demand stabilizes among younger recreational demographics in French and Swiss resort zones.
- Ice Hockey Equipment:Curved composite or wooden sticks with blade tape configurations pair with protective gear assemblies for rink-based competition.
- Gloves:Insulated membrane constructions with leather or synthetic palms and wrist protection systems complete protective ensembles for cold-weather exposure.
Mature deployment sits with Skis. Newer deployment is concentrated in Gloves as CE marking requirements expand protective gear replacement mandates.
End User:
Procurement authority and volume concentration vary sharply between individual purchase decisions and institutional framework agreements.
- Recreational Players:Individual consumers purchasing equipment for seasonal resort usage or home slope access represent the volume foundation. Austrian and French rental fleet expansions are shifting some share toward lease-over-own models.
- Professional Athletes:FIS-registered competitors and national team programs drive premium equipment specifications with tight tolerances for FIS compliance. HEAD Sport GmbH and Groupe Rossignol anchor supply relationships through sponsored athlete programs.
- Schools:Municipal and educational procurement remains underdeveloped relative to Alpine skiing participation rates. Consolidated framework agreements in France and Austria are emerging as volume channels.
- Clubs:Alpine skiing and snowboarding associations coordinate group purchasing for member equipment pools, creating contracted refresh cycles.
Volume concentration favors Recreational Players. Margin expansion is climbing the fastest in Professional Athletes as sponsored equipment specifications command premium positioning.
Material:
Supply chain regionalization and EU Green Deal compliance are reshaping precursor qualification patterns across composite production.
- Composite:Carbon fiber and epoxy resin systems with tailored fiber orientation schedules deliver stiffness-to-weight ratios for high-performance ski and snowboard constructions. Regional European precursor suppliers are gaining share as manufacturers reduce Asian import dependency.
- Aluminum:Extruded and machined alloy components serve binding hardware and edge reinforcement functions with corrosion resistance for snow exposure.
- Fiberglass:E-glass and S-glass woven reinforcements provide cost-optimized torsional rigidity for recreational-tier products.
- Steel:Hardened edge strips and binding mounting inserts deliver wear resistance and screw retention under dynamic loading.
Performance leadership resides with Composite. Cost-optimized substitution is expanding most quickly in Fiberglass as bio-based alternatives mature.
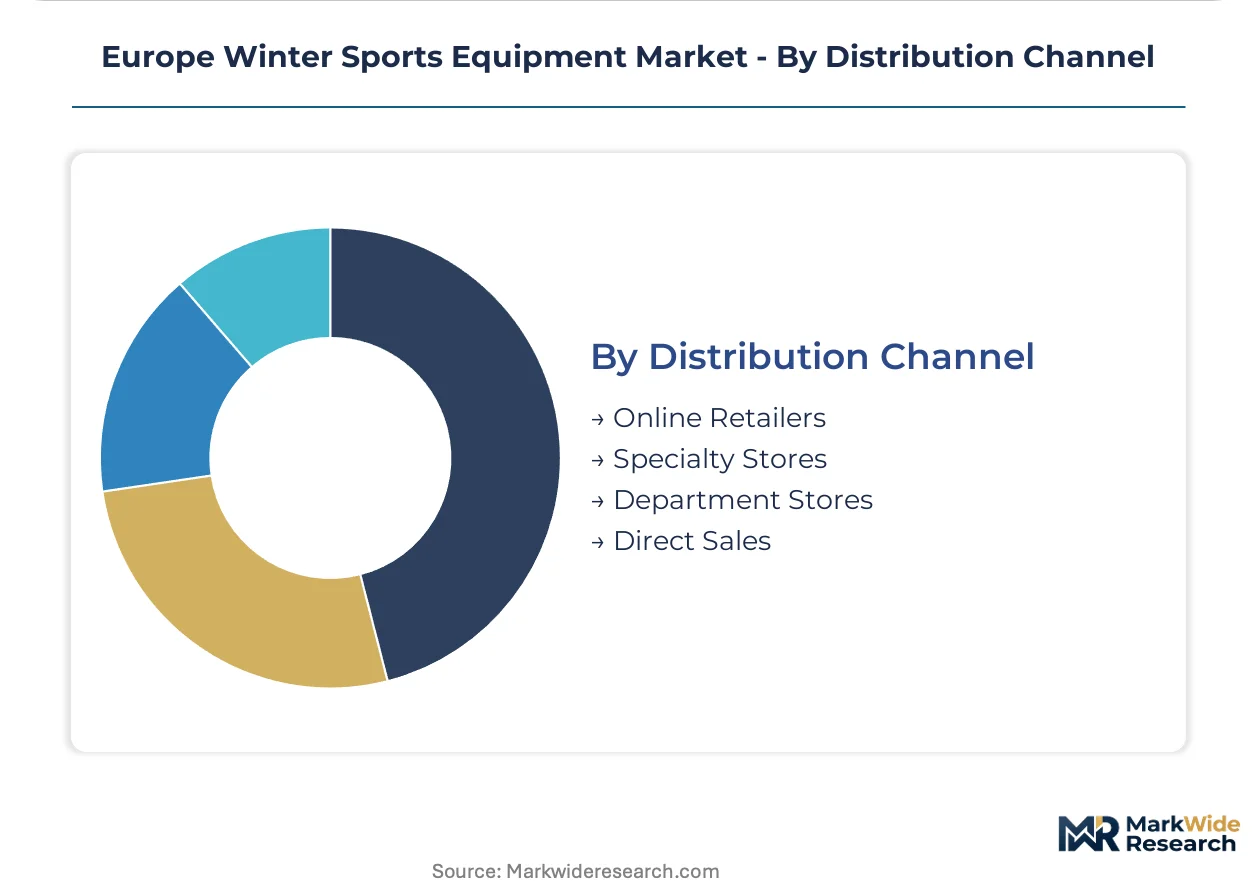
Distribution Channel:
Channel economics are restructuring around rental fleet operators unbundling equipment from lift-ticket packages.
- Online Retailers:Direct-to-consumer platforms with sizing algorithms and seasonal promotional calendars capture recreational player volume outside peak resort periods.
- Specialty Stores:Technical fitting services and binding mounting expertise concentrate in Alpine corridor retail clusters. These outlets anchor premium brand positioning for manufacturers.
- Department Stores:Seasonal sporting goods sections with limited technical service capacity serve entry-level equipment demand.
- Direct Sales:Manufacturer-owned channels and team sales programs bypass wholesale margins for professional athlete and club procurement.
Service-intensive positioning dominates Specialty Stores. Digital penetration is gaining share fastest in Online Retailers as sizing technology improves return rate economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber precursor manufacturing in southern Germany anchors composite ski production networks across the Alpine corridor. Austrian resin suppliers and French molding facilities complete integrated supply chains serving European winter sports demand.
France
Alpine tourism investment in Auvergne-Rhône-Alpes drives rental fleet procurement volumes. ANSM coordinates CE marking enforcement for protective gear sold through French retail channels. Groupe Rossignol anchors vertically integrated composite molding operations in the Isère valley near Grenoble.
Austria
Professional athlete sponsorship programs sustain premium equipment replacement cycles in Tyrol and Salzburg provinces. The national standards body enforces PPE Regulation compliance across helmet and binding manufacturers. Fischer Sports GmbH maintains production facilities in Ried im Innkreis with captive carbon fiber layup capacity.
Switzerland
Subscription-based equipment access models gain traction in Zurich and Geneva metropolitan skier populations. Swissmedic oversees medical-grade protective equipment standards for competitive athlete segments. Zürcher Oberland manufacturing clusters specialize in precision binding hardware and edge metallurgy.
Germany
Bavarian automotive composite expertise migrates into recreational ski manufacturing in Munich-Stuttgart corridor. ECHA REACH compliance documentation burdens mid-tier suppliers reformulating base coatings. HEAD Sport GmbH leverages Baden-Württemberg engineering networks for binding system integration.
Europe Winter Sports Equipment Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to share REACH compliance costs and carbon fiber qualification expenses. The vendor base clusters around three tiers: integrated Alpine producers with captive molding capacity, specialized binding and hardware fabricators, and regional distributors with rental fleet service capabilities. Tier-one players compete through sponsored athlete relationships and FIS compliance certification. Tier-two specialists differentiate on binding integration and protective gear safety ratings. Geographic expansion into Eastern European retail channels and technology licensing for bio-composite formulations represent the two most active competitive vectors.
Among Finnish-Austrian integrated producers, Amer Sports Oyj exemplifies supply chain control from precursor to finished equipment. French vertically integrated specialists occupy positions in composite molding and alpine racing sponsorship. German precision engineering firms anchor binding system compatibility and hardware durability standards. These three archetypes represent distinct competitive positioning strategies without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| Amer Sports Oyj |
| Groupe Rossignol |
| HEAD Sport GmbH |
| Fischer Sports GmbH |
| Tecnica Group SpA |
| Völkl |
| Atomic |
| Salomon |
| SCOTT Sports SA |
| Others |
Supply & Pricing Matrix
Captive carbon fiber layup capacity in Austrian and French manufacturing clusters anchors both supply security and premium pricing power for integrated ski producers. This backward integration into precursor processing insulates tier-one vendors from Asian import volatility while supporting service-bundled pricing models that mid-tier competitors cannot replicate.
Pricing Analysis
Warranty and seasonal maintenance bundling separates premium ski vendors from unbundled transactional competitors in the Alpine corridor. Three-tier pricing structure across premium, standard, and economy levels reflects FIS compliance certification and regional carbon fiber sourcing rather than commodity materials alone. Pricing pressure stems from REACH-driven reformulation costs in base coatings and waterproofing membranes. Recreational rental fleet operators exhibit highest price sensitivity, while professional athlete sponsorship programs tolerate premium positioning for FIS-compliant equipment specifications.
Supply Chain Analysis
Alpine logistics corridors through Brenner Pass and Mont Cenis tunnel concentrate freight cost exposure for composite precursor movements between southern Germany, Austria, and France. Manufacturing gravity centers on Germany for carbon fiber precursors, Austria for resin systems and layup operations, and France for molding and finishing. Raw material dependencies include Japanese and European carbon fiber tow, epoxy resin systems, and sintered polyethylene base sheets. Single-source vulnerability sits with Asian carbon fiber precursor suppliers despite regionalization efforts. Distribution runs through specialty retail clusters in Alpine resort towns and direct rental fleet contracts with French and Swiss tourism operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance costs and REACH-driven R&D overhead are forcing consolidation among mid-tier composite suppliers unable to absorb dual certification burdens. This regulatory compression creates acquisition opportunities for well-capitalized incumbents with captive testing infrastructure.
For Market Incumbents: Acquire distressed carbon fiber qualification capabilities from REACH-burdened mid-tier suppliers in French and Austrian manufacturing clusters. Integrate captive bio-composite R&D programs to preempt recycled content mandates. Binding system standardization investments will defend against proprietary mounting fragmentation threatening aftermarket revenue. For New Entrants and Emerging Players: Begin with municipal procurement frameworks in underpenetrated Slovak and Polish educational institutions where consolidated purchasing lacks established vendor relationships. Flax fiber and mycelium-core recreational products offer white-space positioning below premium carbon fiber tiers. Direct-to-rental-fleet sales partnerships bypass entrenched specialty retail channel barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated Alpine producers seeking REACH-compliant manufacturing assets. Long-term viability favors vertically positioned specialists with captive molding capacity and FIS certification relationships. Watch for F-Gas Regulation enforcement acceleration as the inflection signal compressing hydrocarbon wax alternative timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor Supply | Reduces Asian import dependency and shortens lead times for Austrian and French molding facilities. |
| Bio-Composite Material Certification Investment | Positions manufacturers ahead of EU ecodesign recycled content mandates for recreational-tier products. |
| Rental Fleet Service Partnership Expansion | Captures volume through French and Swiss subscription-based equipment access pilots restructuring channel economics. |
| CE Marking and PPE Regulation Compliance Acceleration | Unlocks institutional procurement from French ski schools and Austrian alpine clubs under expanded helmet mandates. |
| Binding System Standardization Coalition | Reduces proprietary mounting fragmentation threatening aftermarket compatibility and consumer switching costs. |
Research Methodology
Independent corroboration across primary interviews with composite manufacturing engineers, rental fleet procurement managers, and regulatory compliance officers, combined with secondary validation through ECHA REACH dossier databases, EU F-Gas Regulation implementation reports, and Alpine tourism investment disclosures, underwrites the qualitative findings. Bottom-up equipment production estimates from Austrian and French manufacturing clusters triangulate against top-down tourism visitor volume projections across the Alpine corridor.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, end-user procurement authority, material specification tier, and distribution channel structure. CAGRs derive from fitted growth curves incorporating EU Green Deal implementation pacing, F-Gas Regulation phase-down schedules, and carbon fiber regionalization timelines. Forecast inputs include ski replacement cycle frequencies by performance tier and rental fleet refresh contract durations.
Underlying measurement precision varies by segment; professional athlete equipment specifications and rental fleet procurement volumes carry tighter precision than fragmented individual recreational purchases. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and precursor supply regionalization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Basketball Gear Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Golf Club Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Rowing Boats Market
Sports Equipment
Go Kart Market
Sports Equipment
Sports Devices Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Sports and Athletic Insoles Market