
 Global Stand-Up Paddleboard Market | 2026-2036
Global Stand-Up Paddleboard Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stand-Up Paddleboard Market Foresight
ISO 6185 inflatable craft certification is reorganizing competitive access in the paddleboard industry, forcing smaller manufacturers to absorb testing costs or exit wholesale channels entirely. Starboard leverages its in-house epoxy lamination facility in Thailand to control material quality from resin sourcing to finished board. Red Paddle Co sustains dominance in the inflatable segment through proprietary MSL fusion construction that eliminates glued seams. Naish International anchors its position in high-performance racing boards with carbon fiber layups refined over decades of windsport manufacturing.
A stand-up paddleboard is a buoyant watercraft propelled by a standing rider using a single-bladed paddle, typically measuring 2.7 to 4.3 meters in length with a planing hull displacement between 150 and 300 liters depending on intended use. Most inflatable variants employ drop-stitch PVC construction bonded with heat-welded or mechanically fused seams to achieve rigidities exceeding 15 PSI internal pressure, enabling recreational paddling, flatwater touring, and wave riding across diverse aquatic environments. The inflatable product category commands the broadest distribution footprint due to roll-pack portability that appeals to apartment-dwelling consumers and rental operators lacking storage infrastructure. Carbon fiber material configurations concentrate margin pools in competitive racing and expedition touring segments where stiffness-to-weight ratios justify premium positioning. Recreational application volumes dwarf other use cases but carry thinner per-unit margins that push manufacturers toward direct-to-consumer channels.
FDA oversight of adhesives and coatings used in board construction affects US market access, while REACH compliance in Europe restricts certain phthalate plasticizers in PVC formulations and drives reformulation investments. The EU Green Deal accelerates scrutiny of petroleum-derived epoxy resins, prompting suppliers to document bio-content percentages and end-of-life recyclability pathways. Watersport rental operators and specialty retailers must track evolving certification requirements across multiple jurisdictions to avoid inventory obsolescence and liability exposure.
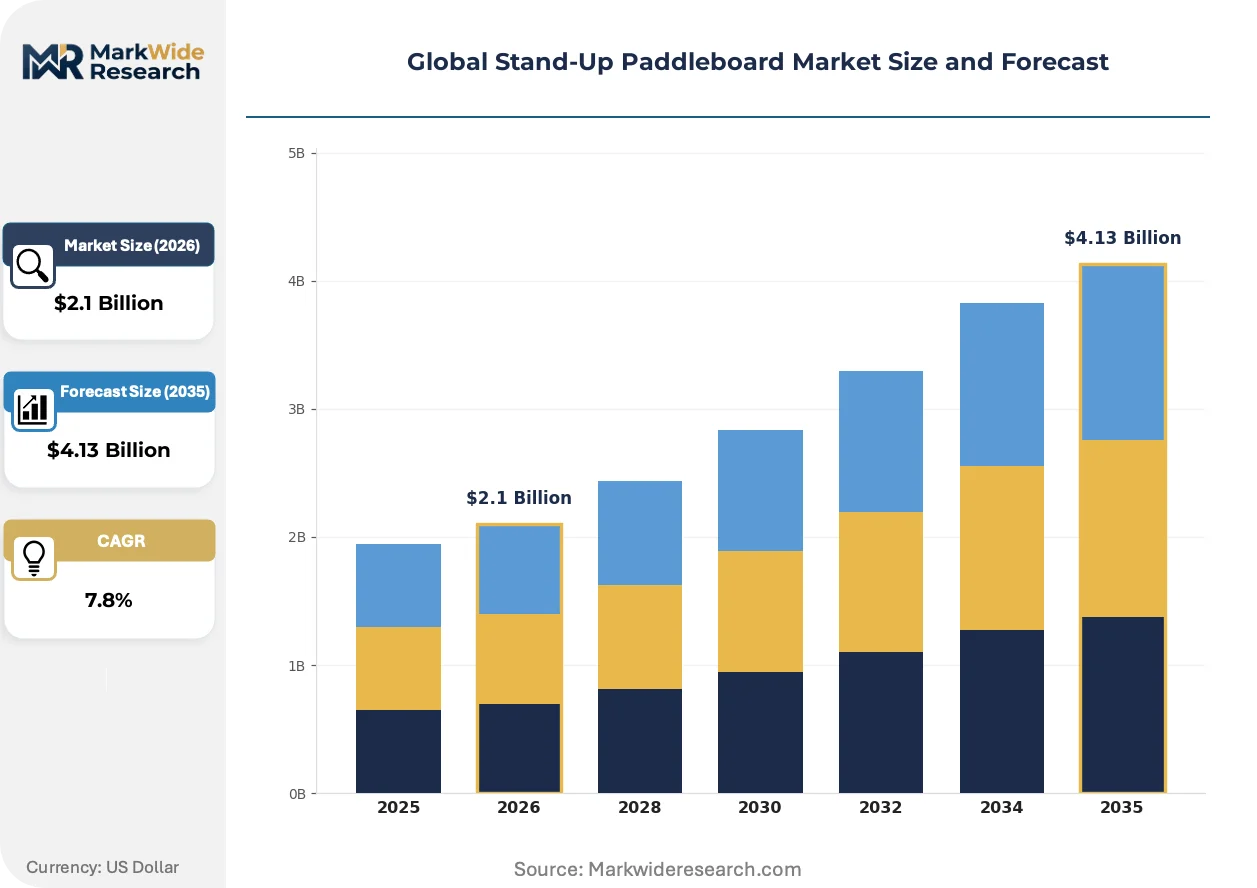
Market Dynamics
ISO 6185 inflatable craft certification is reorganizing competitive access by forcing smaller manufacturers to absorb testing costs or exit wholesale channels entirely, while EU Green Deal pressure accelerates bio-based epoxy resin adoption across supply chains.
Growth Catalysts
- Fitness Infrastructure Expansion:Watersport parks and coastal recreation centers in Florida, California, and Australia are installing permanent paddleboard fleets. Rental operators drive volume through seasonal package offerings.
- REACH-Driven Material Innovation:European phthalate restrictions in PVC formulations push suppliers toward bio-plasticizer alternatives. Reformulation investments unlock premium positioning in EU member states.
- Drop-Stitch Portability:Heat-welded seam construction enables 15+ PSI rigidity in roll-pack formats. Apartment-dwelling consumers and mobile rental operators adopt inflatable variants for storage-constrained environments.
Market Restraints
- Petroleum-Derived Input Volatility:Epoxy resin and PVC feedstock costs fluctuate with crude oil benchmarks. Manufacturers lack pricing power to pass through raw material swings.
- Thailand Production Concentration:Lamination and finishing capacity clusters in Southeast Asian facilities. Single-source geographic exposure creates tariff and logistics vulnerability.
- Carbon Fiber Stiffness Barriers:Racing and expedition segments require stiffness-to-weight ratios that inflatable constructions cannot achieve. Performance ceiling limits addressable market expansion.
Strategic Opportunities
- Underpenetrated Nordic Markets:Sweden, Norway, and Denmark show low paddleboard penetration despite extensive coastline. Cold-water wetsuit compatibility and sauna-access integration create entry vectors.
- EU Green Deal Recyclability Mandates:End-of-life documentation requirements favor manufacturers with closed-loop PVC recovery programs. Early compliance builds procurement preference with municipal rental fleets.
- Direct-to-Consumer Channel Bypass:Recreational margin compression pushes brands toward owned e-commerce and subscription rental models. Inventory control and customer data capture improve unit economics.
Industry Challenges
- ISO 6185 Certification Timeline:Third-party testing for inflatable craft safety standards extends 4-6 months. Smaller manufacturers face cash flow strain during approval windows.
- Adhesive Chemistry Expertise Gap:Heat-welded and fusion-bonded seam technologies require polymer engineering specialization. Talent scarcity constrains quality scaling in mid-tier production facilities.
- Multi-Jurisdiction Compliance Tracking:Watersport rental operators must monitor FDA adhesive oversight, REACH plasticizer rules, and evolving EU bio-content thresholds simultaneously. Inventory obsolescence risk rises with regulatory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stand-Up Paddleboard Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Around, Touring, Racing, Inflatable, Yoga Material: Epoxy, Polyethylene, Carbon Fiber, Wood, PVC Application: Recreational, Competitive Racing, Fitness Training, Adventure Touring Customer Type: Outdoor Enthusiasts, Watersport Parks, Rental Operators, Fitness Centers |
| Companies Covered | Tahe Outdoors, iROCKER, Red Paddle Co, Thurso Surf, Isle Surf & SUP, Starboard, Naish International, Aqua Marina, BOTE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stand-Up Paddleboard Market Shifts & Advancements
Material science advances and certification-driven procurement preferences are compressing traditional manufacturing hierarchies while opening white space for sustainability-positioned entrants.
Mechanically fused seam construction is decomposing the glued-seam inflatable segment by eliminating adhesive failure points and enabling higher pressure tolerances. Watersport rental operators in Australia and coastal United States communities are specifying fusion-built boards for fleet durability. This construction migration is compressing margin pools for manufacturers dependent on conventional PVC bonding equipment.
REACH compliance deadlines for phthalate-free PVC formulations are forcing European suppliers to document bio-plasticizer percentages and recyclability pathways. Reformulation investments concentrate among compounders serving watersport OEMs with EU distribution. Racing and expedition board categories face compressed timelines as ECHA scrutiny extends to petroleum-derived epoxy resin alternatives.
Rental operators are consolidating procurement around certified fleet suppliers capable of documenting ISO 6185 compliance across multi-year service contracts. Specialty retailers lose volume to direct manufacturer relationships as buyers prioritize liability protection and standardized replacement protocols. This concentration is most visible in Florida and California coastal communities where municipal watersport concessions dominate beach access points.
Global Stand-Up Paddleboard Market Segmentation
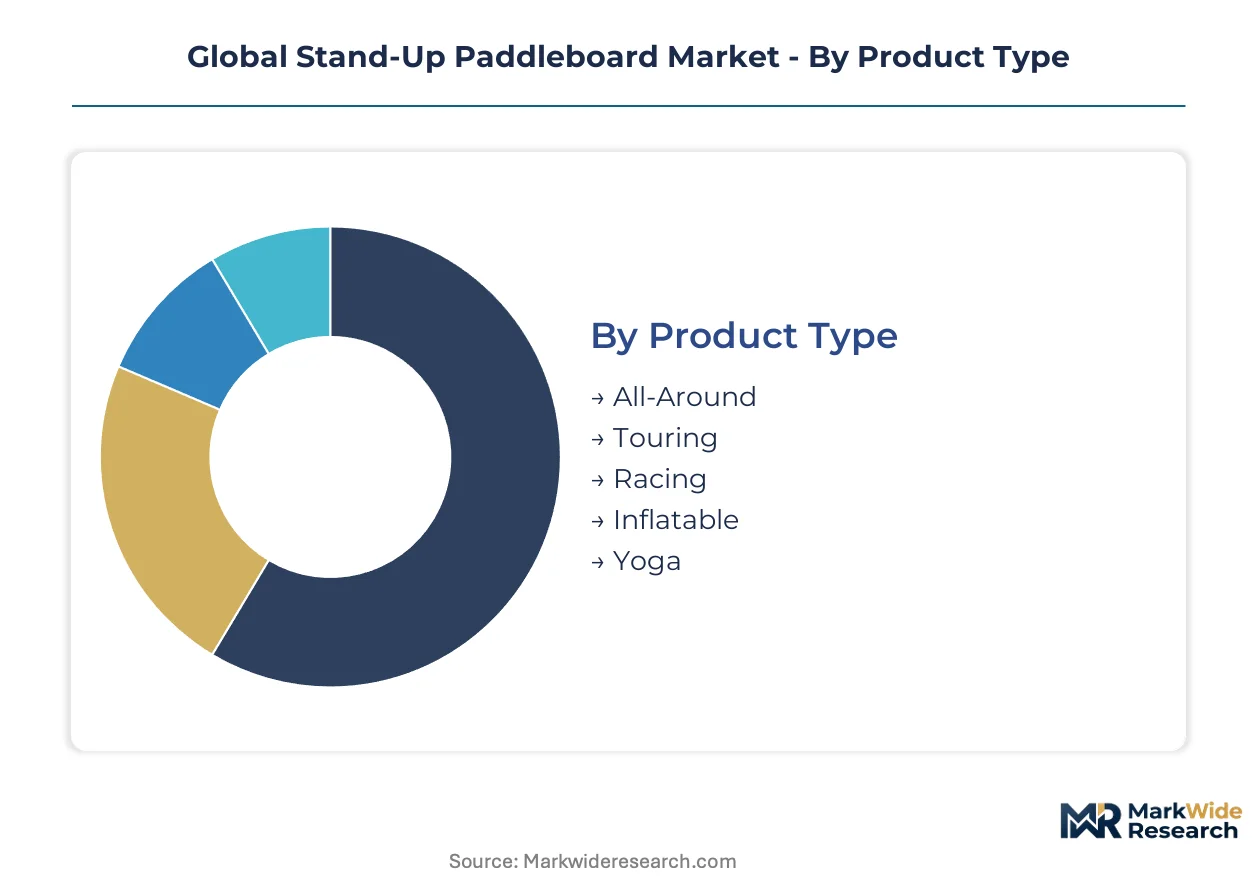
Product architecture in paddleboard manufacturing channels revenue through distinct margin pools. Construction methods and end-use specifications determine whether boards flow through specialty retail, direct-to-consumer platforms, or municipal procurement tenders.
Product Type:
Channel distribution varies sharply by board category, with inflatable variants dominating e-commerce and rental fleet procurement while rigid constructions concentrate in specialty retail.
- All-Around:Versatile hull designs measuring 3.0-3.8 meters accommodate flatwater, light surf, and casual touring. Demand clusters in Florida and California coastal communities where first-time buyers seek single-board solutions. Rental operators specify all-around fleets for operational flexibility across varying conditions.
- Racing:Displacement hulls under 4.3 meters with narrowed outlines prioritize glide efficiency over stability. Competitive circuits in Australia and the United States drive carbon fiber specifications. ISO 6185 certification requirements exclude most inflatable constructions from sanctioned events.
- Touring:Extended waterline lengths and integrated deck rigging support multi-day expeditions. Expedition operators in Nordic coastal regions specify epoxy or carbon fiber layups for load-bearing capacity.
- Inflatable:Drop-stitch PVC construction achieves 15+ PSI rigidity in roll-pack formats. Apartment-dwelling consumers and mobile rental operators adopt these for storage-constrained environments.
- Yoga:Wide, stable platforms with padded deck surfaces support fitness programming. Watersport parks in coastal United States communities install permanent yoga fleets.
All-Around dominates installed base. Racing is where expansion concentrates.
Material:
Cost tiers stratify sharply by material selection, with petroleum-derived inputs facing margin compression from EU Green Deal compliance investments.
- Epoxy:Hand-laminated fiberglass sandwiches around foam cores deliver stiffness-to-weight ratios for performance segments. Thailand production clusters control resin sourcing through in-house compounding facilities. REACH-driven bio-based reformulations are climbing the fastest in European procurement specifications.
- Carbon Fiber:Unidirectional and woven layups achieve sub-10 kilogram weights for racing and expedition categories. Premium positioning justifies specialty retail distribution with minimal discounting.
- Polyethylene:Rotomolded constructions prioritize impact resistance over weight for rental fleet durability. Municipal watersport concessions in Florida specify polyethylene for vandalism resistance.
- PVC:Drop-stitch inflatable constructions bond heat-welded or mechanically fused seams. REACH phthalate restrictions force compounders toward bio-plasticizer alternatives.
- Wood:Veneer and solid timber constructions serve artisanal positioning in specialty retail. Limited production volumes restrict channel presence to direct-to-consumer platforms.
Epoxy commands the broadest channel access. Carbon fiber is where margin pools concentrate.
Application:
Volume distribution inverts against margin structure, with high-unit recreational sales carrying thinner per-unit economics than niche performance categories.
- Recreational:Casual flatwater paddling and beach leisure drive mass-market volumes. Direct-to-consumer channels capture share as manufacturers bypass specialty retail markups.
- Competitive Racing:Sanctioned events and training programs specify ISO-compliant constructions. Carbon fiber stiffness requirements exclude most inflatable alternatives from podium contention.
- Fitness Training:Structured exercise programming in watersport parks and coastal fitness centers. Seasonal package offerings in Australia drive fleet turnover.
- Adventure Touring:Multi-day expeditions requiring load capacity and seaworthiness. Nordic coastline penetration remains underdeveloped despite extensive aquatic access.
Recreational anchors unit volumes. Adventure touring is where white space persists.
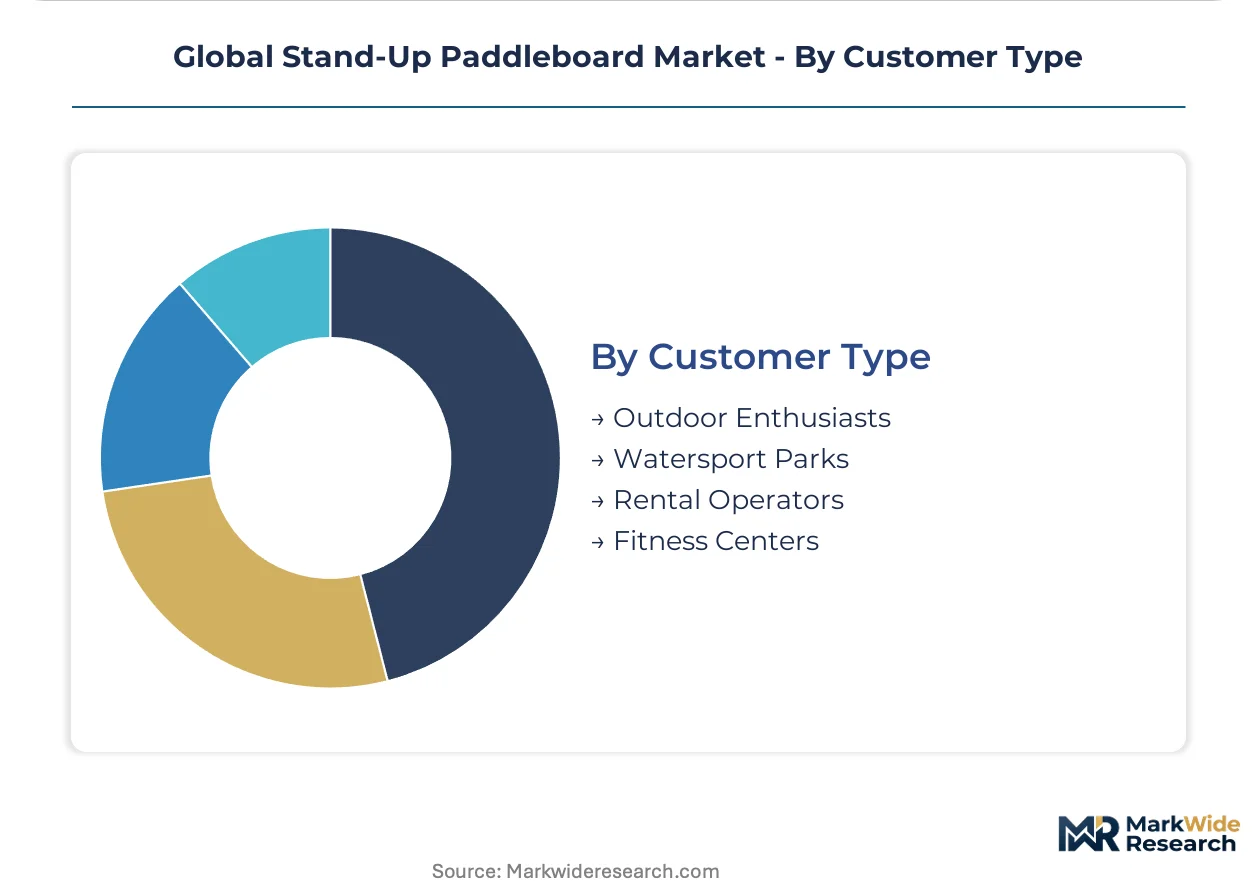
Customer Type:
Procurement authority is shifting from specialty retailers toward direct manufacturer relationships as fleet buyers prioritize liability documentation and standardized replacement protocols.
- Rental Operators:Seasonal fleet procurement in coastal United States communities and Australia concentrates around ISO 6185-certified suppliers. Multi-year service contracts specify fusion-seam construction for durability.
- Watersport Parks:Municipal concessions in Florida and California dominate beach access points. Procurement teams require end-of-life recyclability documentation under EU Green Deal alignment.
- Outdoor Enthusiasts:Individual purchasers through e-commerce and specialty retail. Inflatable portability appeals to apartment-dwelling consumers in urban coastal markets.
- Fitness Centers:Land-based gyms expanding into aquatic programming. Yoga-specific board specifications integrate with existing group exercise infrastructure.
Rental operators dominate B2B procurement. Fitness centers are where customer acquisition costs are compressing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rental operators and watersport parks concentrate procurement authority in coastal United States communities, while European regulatory pressure reshapes material specifications across Nordic and Mediterranean markets.
United States
Watersport parks in Florida and California install permanent paddleboard fleets for fitness programming and seasonal rentals. FDA oversight of adhesives and coatings affects market access for imported constructions. Municipal concessions in Miami-Dade and Orange County dominate beach access procurement.
Australia
Competitive racing circuits drive carbon fiber specifications for sanctioned events and training programs. The country's national watersport regulator enforces safety standards for inflatable craft certification. Sydney and Gold Coast clusters anchor rental fleet distribution along the eastern seaboard.
Germany
REACH compliance deadlines force suppliers toward phthalate-free PVC formulations and bio-plasticizer alternatives. ECHA scrutiny extends to petroleum-derived epoxy resin documentation requirements. Bavarian watersport retailers consolidate procurement around certified fleet suppliers.
Sweden
Cold-water wetsuit compatibility and sauna-access integration create entry vectors for paddleboard adoption despite low current penetration. The EU Green Deal accelerates end-of-life recyclability mandates for municipal rental fleets. Stockholm archipelago operators test bio-based epoxy constructions for expedition touring.
Thailand
Lamination and finishing capacity clusters in Southeast Asian facilities serving export markets. Single-source geographic exposure creates tariff and logistics vulnerability for manufacturers. Bangkok-region production sites control resin sourcing through in-house compounding operations.
Global Stand-Up Paddleboard Market Competitive Landscape
Player mix skews toward vertically integrated specialists and regional rental fleet suppliers competing on certification documentation and material compliance. The structure fragments across construction archetypes rather than consolidating around scale leaders. Three strategic archetypes dominate: in-house epoxy laminators controlling resin-to-finished-board quality, fusion-seam inflatable specialists, and carbon fiber performance fabricators. Competitive moves center on ISO 6185 certification acquisition and EU Green Deal compliance investments.
Among established watersport manufacturers, Starboard and Naish International exemplify vertically integrated production archetypes, while Red Paddle Co anchors the inflatable specialist tier. These companies represent contrasting strategic positions: epoxy lamination control versus proprietary seam construction versus carbon fiber performance heritage. Their market presence illustrates how material specialization and certification readiness determine procurement access in consolidated rental and municipal channels.
| Leading Market Players |
|---|
| Tahe Outdoors |
| iROCKER |
| Red Paddle Co |
| Thurso Surf |
| Isle Surf & SUP |
| Starboard |
| Naish International |
| Aqua Marina |
| BOTE |
| Others |
Supply & Pricing Matrix
Four-to-six-month ISO 6185 certification timelines compress working capital cycles for smaller manufacturers, concentrating pricing power among Thailand-based epoxy laminators with in-house resin compounding while forcing mid-tier players toward cost-plus contracts indexed to crude oil benchmarks.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate procurement between PVC compounders and watersport OEMs, insulating suppliers from petroleum-derived input volatility while transferring margin risk to manufacturers. Three-tier pricing structure across premium carbon fiber racing boards, standard epoxy touring constructions, and economy polyethylene rental fleets differentiates by certification grade and stiffness-to-weight performance. Pricing pressure stems from REACH-driven bio-plasticizer reformulation investments that compounders cannot fully pass through to EU buyers. Rental operators exhibit highest price sensitivity due to fleet-scale procurement and multi-year service contract negotiations, while expedition touring segments accept premium positioning for load-bearing carbon fiber specifications.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints inflate inbound logistics costs for European and United States distributors sourcing from Thailand production clusters. Lamination and finishing capacity concentrates in Thailand, with secondary PVC compounding in China and drop-stitch fabric weaving in South Korea. Raw material dependencies center on petroleum-derived epoxy resins, phthalate-free PVC formulations, and carbon fiber pre-preg from Japanese suppliers. Single-source geographic exposure in Southeast Asia creates tariff and logistics vulnerability. Distribution runs through direct manufacturer relationships with municipal watersport concessions, bypassing specialty retail markups for fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paddleboard market functions as a service-attach opportunity where subscription rental models and seasonal fleet management contracts expand faster than hardware unit sales, rewarding manufacturers with software-enabled inventory tracking and maintenance protocols.
For Market Incumbents: Fortify certification documentation capabilities to defend municipal procurement access against emerging fusion-seam specialists. Deepen backward integration into bio-based epoxy resin compounding to capture EU Green Deal premium positioning and offset REACH compliance cost absorption. Prioritize ISO 6185 testing infrastructure investments to compress approval timelines for rental fleet tenders. For New Entrants and Emerging Players: Anchor in underpenetrated Nordic markets where cold-water wetsuit compatibility and sauna-access integration create differentiated entry vectors against established Mediterranean and coastal United States competitors. Target Stockholm archipelago expedition operators with bio-based epoxy constructions documented for end-of-life recyclability. Pursue direct-to-consumer e-commerce with roll-pack inflatable variants sized for apartment-dwelling urban coastal consumers. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-transition play because EU Green Deal recyclability mandates and REACH phthalate restrictions favor compounders with closed-loop PVC recovery programs over conventional manufacturers. Acquisition targets should display in-house resin sourcing, heat-welded seam fabrication expertise, or municipal fleet contract backlogs. The signal to watch is consolidation of procurement authority among watersport parks requiring standardized replacement protocols and liability documentation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 6185 Certification Investment | Unlocks municipal fleet procurement in Florida and California coastal concessions. |
| Bio-Based Epoxy Reformulation | Positions suppliers for EU Green Deal procurement preference with documented recyclability pathways. |
| Direct-to-Consumer Channel Launch | Bypasses specialty retail markups in recreational segments with compressed per-unit margins. |
| Fusion-Seam Production Scale-Up | Eliminates adhesive failure points for rental operator durability specifications. |
| Nordic Market Entry Program | Captures white-space demand in Sweden, Norway, and Denmark through cold-water compatibility positioning. |
Research Methodology
A spread of perspectives from watersport rental fleet managers, epoxy resin compounders, municipal procurement officers, and specialty retail buyers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with distribution channel partners and aftermarket service heads alongside secondary validation through customs trade data, SEC filings of listed watersport manufacturers, and ISO certification registry records. Bottom-up unit economics from individual board constructions triangulated against top-down market sizing from regional fleet installation announcements.
Segmentation dimensions modeled span product architecture (inflatable versus rigid constructions), material grade (PVC, epoxy, carbon fiber, polyethylene), end-use application (recreational, racing, touring, fitness), and customer type (rental operators, watersport parks, individual consumers). CAGRs were derived from regression analysis of historical fleet procurement data against coastal recreation infrastructure investment trends, with inputs from REACH compliance timeline impacts and EU Green Deal implementation schedules across member states.
Underlying assumptions cover stable petroleum-derived input cost corridors and sustained municipal watersport concession expansion, with deviation risk concentrated in tariff regime shifts affecting Thailand production exports and accelerated ECHA scrutiny extending beyond phthalates to epoxy resin alternatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Balance Bike Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Diving Board Market
Sports Equipment
Spain Horse Riding Equipment Market