
 Mouthguard Market | 2026-2036
Mouthguard Market Size, Share, and Industry Trends Forecast 2026-2036
Mouthguard Market Analysis
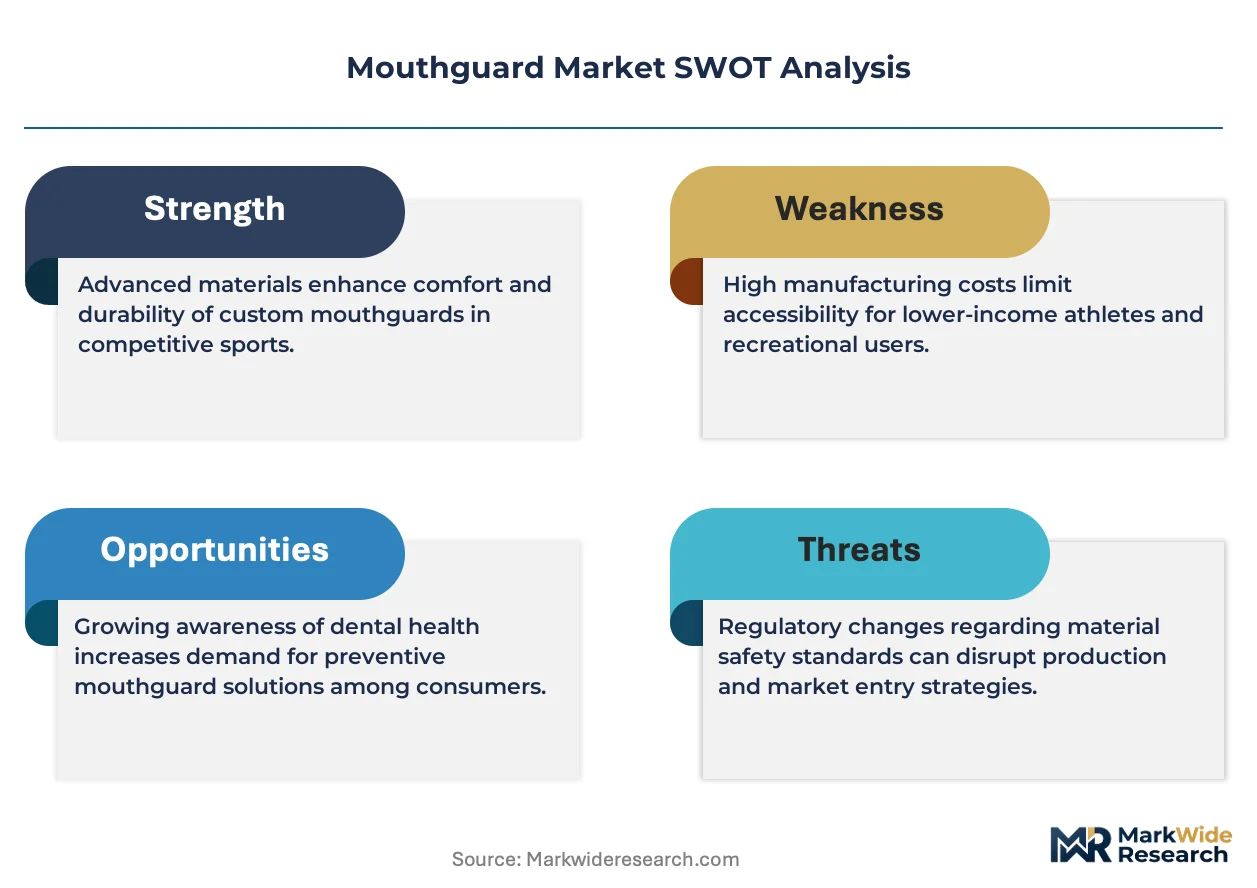
EU REACH restrictions on phthalate-containing polymers is restructuring material sourcing across the value chain, pushing manufacturers toward medical-grade silicone and bio-based polyurethane formulations. Shock Doctor Inc. leverages vertical integration in thermoplastic molding to sustain cost leadership in boil-and-bite distribution. OPRO anchors its position through dental-laboratory partnerships that control custom-fit channels in the United Kingdom and Australia. Under Armour Inc. competes via brand strength in team-sport procurement, securing roster placements with collegiate athletic departments.
A mouthguard is a removable oral appliance fabricated from elastomeric polymers—typically EVA copolymers, thermoplastic polyurethane, or medical-grade silicone—designed to absorb and dissipate impact forces across the maxillary arch while maintaining airway patency. Manufacturers employ pressure-lamination or injection-compression molding to achieve thickness gradients between occlusal surfaces and labial shields. Custom-fit products command premium positioning through dental-impression accuracy and CAD-CAM milling, while boil-and-bite segments occupy volume tiers in retail sporting-goods channels. Material differentiation clusters around Shore A hardness ratings and tear-strength specifications, with EVA dominating cost-sensitive applications and silicone penetrating sleep-apnea and pediatric segments.
The U.S. Food and Drug Administration classifies certain mouthguards as Class I or Class II medical devices, subjecting sleep-apnea and bruxism claims to 510(k) clearance pathways that elevate R&D thresholds for new entrants. ASTM F1140 and CE marking under the EU Medical Device Regulation establish impact-resistance benchmarks that manufacturers must satisfy for sports-protection claims in transatlantic markets. Stakeholders must monitor evolving state-level scholastic athletic mandates and dental-insurance reimbursement codes for sleep-disordered breathing appliances, as these policy levers will determine volume allocation between retail sporting-goods and clinical distribution channels.
Market Dynamics
EU REACH restrictions on phthalate-containing polymers are restructuring material sourcing across the mouthguard value chain, pushing manufacturers toward medical-grade silicone and bio-based polyurethane formulations while elevating compliance costs for legacy EVA processors.
Growth Catalysts
- Mandated Youth Protection:State-level scholastic athletic associations in the United States now require oral protection for contact sport participation, institutionalizing replacement cycles across high school football, hockey, and lacrosse programs.
- FDA 510(k) Pathway Expansion:Sleep-disordered breathing appliance classifications under Class II medical device regulations are opening reimbursement channels through dental sleep medicine practices.
- Thermoplastic Elastomer Innovation:Improved Shore A hardness gradients and tear-strength specifications in TPU formulations are enabling thinner occlusal surfaces without sacrificing impact absorption.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene-vinyl acetate copolymer pricing tracks crude oil derivatives, compressing margins for boil-and-bite manufacturers locked into retail price points.
- Supply Concentration Risk:Medical-grade silicone resin production concentrates among German and Japanese chemical conglomerates, creating single-source vulnerability for custom-fit dental laboratory channels.
- Biocompatibility Testing Burden:ISO 10993 cytotoxicity and sensitization protocols add eighteen-to-twenty-four month pre-market timelines for novel polymer introductions.
Strategic Opportunities
- Pediatric Sleep-Apnea Undiagnosis:The American Academy of Pediatrics guidelines now recommend oral appliance screening for adolescent obstructive sleep apnea, expanding addressable clinical volume beyond adult bruxism.
- Direct-to-Consumer Impression Kits:At-home dental modeling combined with CAD-CAM milling is bypassing traditional dental laboratory intermediaries in Australia and Canada.
- EU Green Deal Alignment:Bio-based polyurethane formulations derived from castor oil feedstocks qualify for sustainable public procurement preferences in France and the Netherlands.
Industry Challenges
- CAD-CAM Technician Scarcity:Dental laboratory networks face acute shortages of operators proficient in 3D intraoral scanning and five-axis milling equipment.
- Dual Certification Complexity:Manufacturers serving both sports-protection and sleep-medicine segments must maintain parallel ASTM F1140 impact testing and FDA 510(k) quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mouthguard Market |
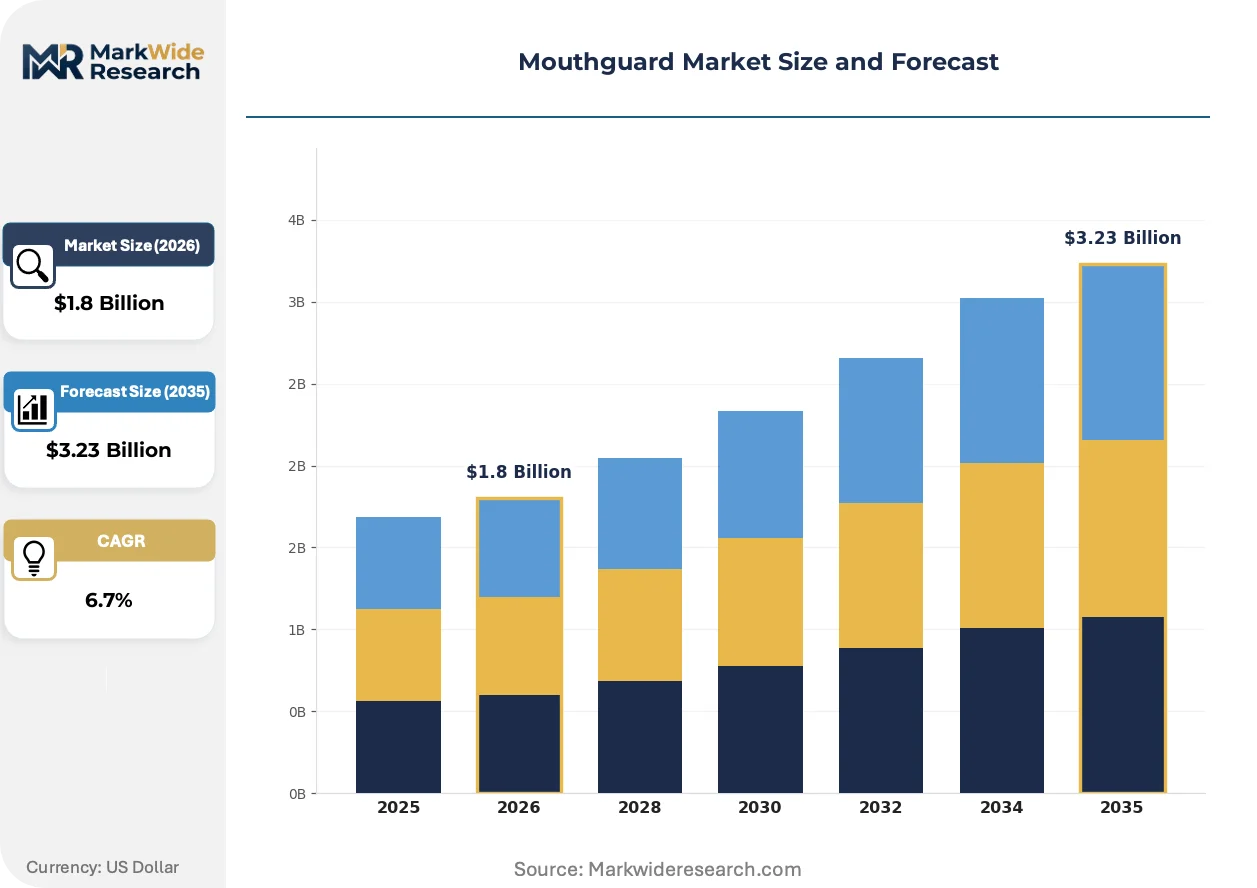
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom-fit, Stock, Boil-and-bite, Mouth-formed Material: Polyurethane, EVA, Silicone, Polyvinyl Chloride End User: Athletes, Dental Patients, Sleep Apnea Patients, Children Application: Sports Protection, Teeth Grinding, Sleep Improvement, Dental Protection |
| Companies Covered | Shock Doctor Inc., OPRO, Nike Inc., Under Armour Inc., Decathlon S.A., Brain Pad Inc., Venum, Battle Sports Science LLC, Makura Sport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mouthguard Market Emerging Trajectories
Material science breakthroughs and regulatory reclassification are converging to reshape competitive positioning, with digital fabrication methods compressing custom-fit production timelines while sustainability mandates force polymer portfolio overhauls.
Pressure-lamination of multi-density thermoplastic polyurethane is electrifying custom-fit fabrication by enabling automated thickness gradients that previously required manual layering. Dental laboratories in Germany and Switzerland are adopting these systems to reduce chairside adjustment time for sleep-apnea appliances. The technology is compressing delivery windows from fourteen days to seventy-two hours while improving occlusal accuracy.
EU Medical Device Regulation enforcement through notified bodies in Ireland and the Netherlands is elevating clinical evidence requirements for bruxism and temporomandibular disorder claims. Manufacturers must now submit prospective clinical data rather than predicate device equivalency for novel designs. Sleep-apnea segments face the steepest compliance burden, with smaller European brands exiting rather than absorbing notified body audit costs.
Team-sport procurement departments are consolidating vendor rosters around single-source suppliers capable of delivering customized colorways and logo integration at volume. Collegiate athletic departments in the United States now mandate annual replacement programs bundled with equipment supplier contracts. This concentration is displacing individual athlete retail purchases through sporting-goods channels.
Mouthguard Market Segmentation
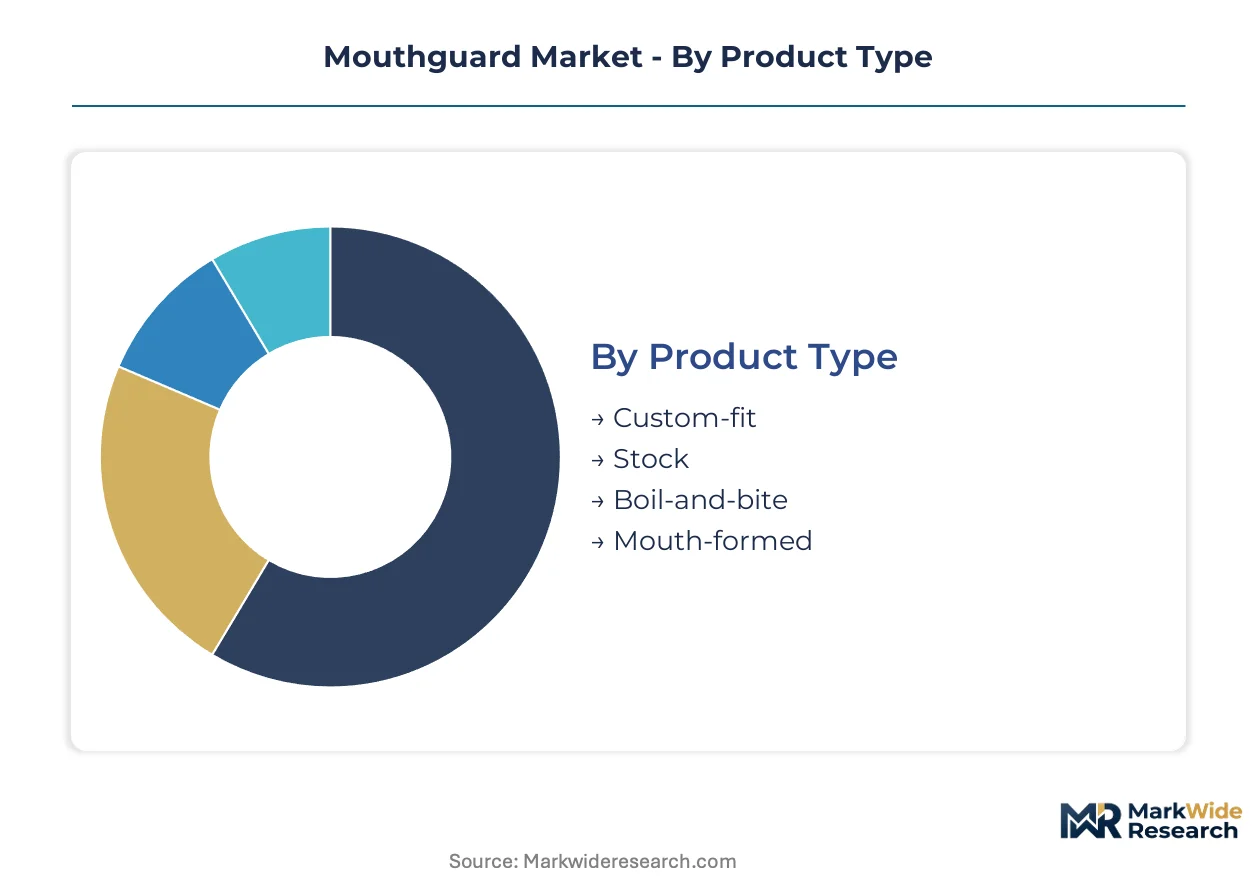
Mouthguard segmentation reflects divergent manufacturing economics across fabrication methods, material chemistries, and clinical versus retail distribution channels. Each dimension carries distinct regulatory burdens and margin structures that determine competitive entry costs.
Product Type:
Capital intensity varies sharply across fabrication methods, with CAD-CAM milling infrastructure requiring six-figure equipment investments while thermal molding operates at far lower fixed costs.
- Custom-fit:Dental-impression accuracy and five-axis milling produce occlusal surfaces matched to individual maxillary arches. Sleep apnea and bruxism patients in dental sleep medicine practices drive replacement cycles, with FDA 510(k) clearance elevating R&D thresholds for new entrants.
- Boil-and-bite:Thermoplastic elastomer sheets soften in heated water for athlete self-molding. High school football and hockey programs across Texas and California institutionalize annual replacement, compressing delivery windows to retail sporting-goods channels.
- Stock:Pre-formed EVA shells in standardized sizes occupy emergency replacement and entry-level price tiers. Margins pressure manufacturers locked into mass retail distribution agreements.
- Mouth-formed:Pressure-lamination of multi-density layers enables automated thickness gradients previously requiring manual assembly. German and Swiss dental laboratories adopt these systems to reduce chairside adjustment time.
Custom-fit absorbs the bulk of installed capacity; boil-and-bite is expanding most quickly.
Material:
Feedstock sourcing concentration determines supply security, with medical-grade silicone resin production clustering among German and Japanese chemical conglomerates.
- EVA:Ethylene-vinyl acetate copolymers dominate cost-sensitive boil-and-bite applications through Shore A hardness ratings between 75 and 85. Petrochemical derivative pricing tracks crude oil volatility, compressing margins for processors without backward integration into resin supply.
- Silicone:Medical-grade formulations penetrate pediatric and sleep-apnea segments where biocompatibility ISO 10993 protocols govern. Australian and Canadian direct-to-consumer impression kits specify platinum-cured silicones for at-home dental modeling workflows.
- Polyurethane:Thermoplastic and castor-oil-derived bio-based formulations qualify for EU Green Deal sustainable procurement preferences in France and the Netherlands.
- Polyvinyl Chloride:Phthalate-plasticized variants face EU REACH restriction-driven phaseouts, displacing volume toward compliant alternatives.
EVA commands the largest production footprint; silicone posts the steepest expansion trajectory.
End User:
Customer acquisition economics split between institutional procurement departments and individual clinical referrals, with reimbursement codes determining addressable volume.
- Athletes:Collegiate athletic departments consolidate vendor rosters around single-source suppliers delivering customized colorways. State-level scholastic mandates in Illinois and Florida institutionalize protection requirements.
- Sleep Apnea Patients:American Academy of Pediatrics screening guidelines expand adolescent obstructive sleep apnea addressable volume beyond adult bruxism populations.
- Dental Patients:Temporomandibular disorder claims under EU Medical Device Regulation now require prospective clinical data rather than predicate device equivalency.
- Children:Pediatric-specific sizing and compliance features address airway patency concerns distinct from adult anatomical requirements.
Athletes generate the highest unit volumes; sleep apnea patients yield the strongest pricing power.
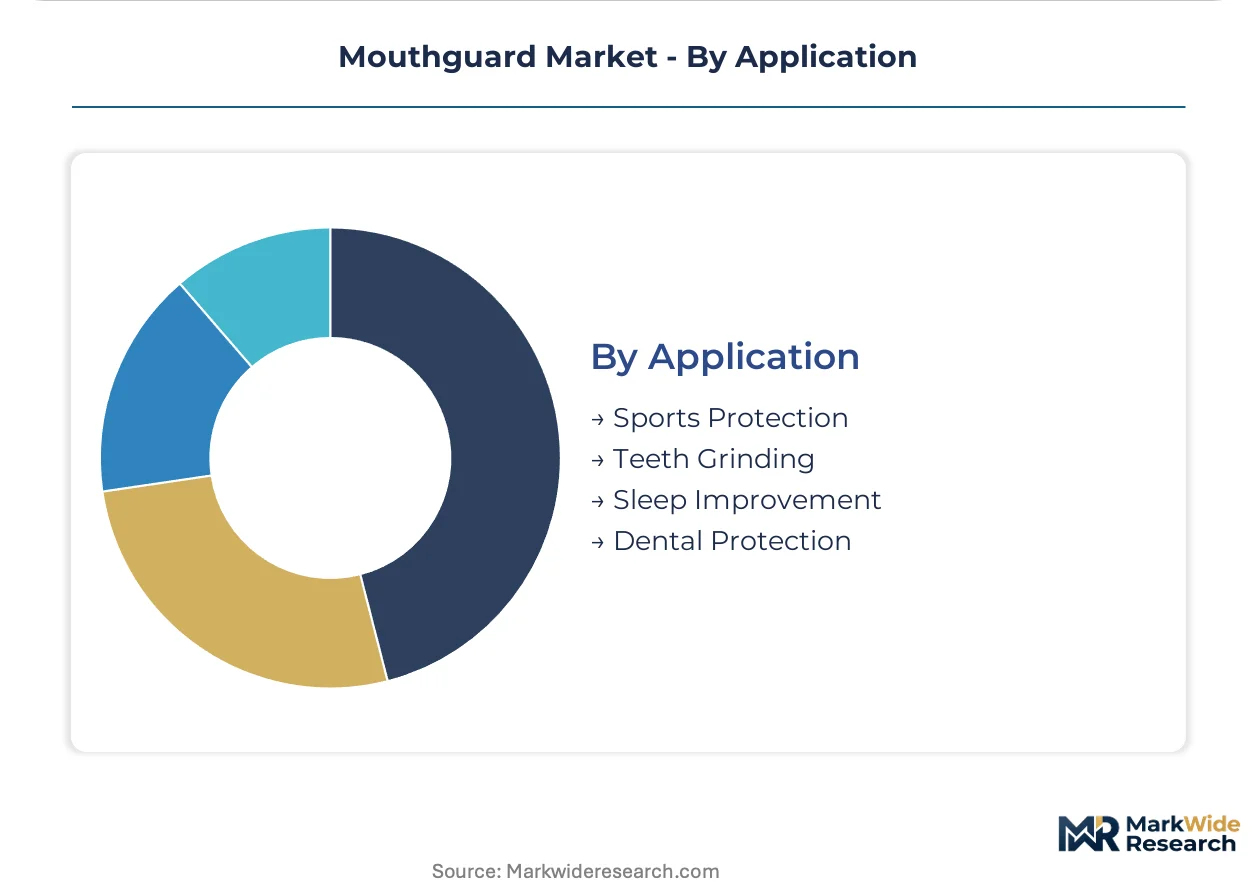
Application:
Dual certification complexity forces parallel quality management systems when manufacturers serve both sports-protection and sleep-medicine segments.
- Sports Protection:ASTM F1140 impact-resistance benchmarks govern transatlantic market access. Team-sport procurement bundles displace individual retail purchases through roster placement contracts.
- Sleep Improvement:Class II medical device classification opens dental-insurance reimbursement channels. Notified body audit costs in Ireland and the Netherlands drive smaller European brand exits.
- Teeth Grinding:Bruxism appliance claims face elevated clinical evidence requirements under EU MDR enforcement.
- Dental Protection:Orthodontic and post-procedural applications require compatibility with fixed appliances and temporary restorations.
Sports protection anchors current revenue; sleep improvement gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milwaukee anchors North American mouthguard fabrication through Shock Doctor's thermoplastic molding operations, while Nottingham in the United Kingdom hosts OPRO's dental-laboratory partnerships. These clusters concentrate distinct manufacturing archetypes—mass-market boil-and-bite versus precision custom-fit—across transatlantic markets.
United States
Scholastic athletic programs in Texas and California institutionalize annual mouthguard replacement cycles for football and hockey. State-level mandates from Illinois and Florida athletic associations require oral protection for youth contact sport participation. Milwaukee-based thermoplastic molding operations supply boil-and-bite volumes to mass retail sporting-goods channels.
United Kingdom
Dental sleep medicine practices in London and Manchester drive custom-fit demand for bruxism and sleep-apnea appliances. EU Medical Device Regulation enforcement through Irish and Dutch notified bodies elevates clinical evidence requirements for novel designs. Nottingham anchors OPRO's dental-laboratory partnerships controlling custom-fit channels.
Germany
Medical-grade silicone resin production concentrates among chemical conglomerates supplying dental laboratory networks. German dental laboratories adopt pressure-lamination systems for automated thickness gradients in sleep-apnea appliances. Bavarian and Baden-Württemberg precision manufacturing clusters compress custom-fit delivery windows.
Australia
Direct-to-consumer impression kits bypass traditional dental laboratory intermediaries in Sydney and Melbourne markets. Platinum-cured silicone specifications govern at-home dental modeling workflows for sleep-apnea segments. OPRO's partnerships with Australian dental practices control custom-fit distribution.
Canada
At-home dental modeling combined with CAD-CAM milling expands addressable clinical volume beyond traditional laboratory channels. Provincial athletic associations in Ontario and British Columbia mirror US scholastic protection mandates. Toronto and Vancouver dental practices adopt direct-to-consumer workflows for pediatric sleep-apnea screening.
Mouthguard Market Vendor Landscape
The competitive structure tilts toward brand-driven sporting-goods suppliers and precision dental-laboratory specialists. Market concentration splits between mass-market boil-and-bite manufacturers and custom-fit fabricators serving clinical channels. Three archetypes dominate: vertically integrated thermoplastic molders, dental-laboratory network operators, and athletic-apparel brand licensors. M&A activity concentrates on CAD-CAM milling capacity acquisitions, while strategic partnerships lock in collegiate athletic department procurement contracts.
Among vertically integrated molders, Shock Doctor Inc. exemplifies cost leadership through captive thermoplastic supply chains. OPRO occupies a position within the dental-laboratory specialist tier, anchoring custom-fit distribution through clinical partnerships. Under Armour Inc. represents the athletic-apparel brand-licensor archetype, leveraging roster placements with collegiate athletic departments to secure team-sport procurement contracts.
| Leading Market Players |
|---|
| Shock Doctor Inc. |
| OPRO |
| Nike Inc. |
| Under Armour Inc. |
| Decathlon S.A. |
| Brain Pad Inc. |
| Venum |
| Battle Sports Science LLC |
| Makura Sport |
| Others |
Supply Flow & Price Mechanics
Collegiate athletic department procurement consolidation around single-source suppliers capable of delivering customized colorways and logo integration at volume is compressing margins for boil-and-bite manufacturers without backward integration into thermoplastic resin supply. This buyer concentration forces suppliers toward either premium custom-fit positioning through dental-laboratory partnerships or cost leadership through captive molding operations, with pricing power diverging sharply between these archetypes.
Pricing Analysis
Value-based pricing anchored to clinical outcome metrics dominates custom-fit sleep-apnea appliances, where FDA 510(k) clearance and dental-insurance reimbursement codes justify premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates CAD-CAM milled silicone from pressure-laminated TPU and basic EVA boil-and-bite products. Cost compression in retail boil-and-bite tiers is intensifying because petrochemical feedstock volatility tracks crude oil derivatives. High school athletic programs exhibit highest price sensitivity, while dental sleep medicine practices show lowest sensitivity due to reimbursement pass-through.
Supply Chain Analysis
ISO 10993 biocompatibility certification and FDA quality management system compliance create gating barriers that filter raw material suppliers and elevate procurement costs for novel polymer introductions. Medical-grade silicone resin production concentrates in Germany and Japan, while thermoplastic polyurethane compounding clusters in the United States and China. Feedstock sourcing rests on ethylene-vinyl acetate copolymers, platinum-cured silicone precursors, and castor-oil-derived polyols. Single-source vulnerability in German and Japanese chemical conglomerates exposes custom-fit dental laboratory channels to supply interruption. Distribution runs through sporting-goods retail chains for boil-and-bite volumes and dental laboratory networks for custom-fit appliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital fabrication methods including CAD-CAM milling and pressure-lamination systems are displacing manual layering techniques in custom-fit production, compressing delivery timelines from weeks to days while elevating capital requirements for participation.
For Market Incumbents: Anticipate margin compression in boil-and-bite retail channels as collegiate procurement consolidation accelerates annual replacement program bundling. Defensive moves center on acquiring CAD-CAM milling capacity to capture custom-fit dental sleep medicine volume, and securing backward integration into medical-grade silicone resin supply to offset petrochemical price volatility. Threat from direct-to-consumer impression kits bypassing traditional dental laboratory intermediaries demands channel control investments in at-home dental modeling workflows. For New Entrants and Emerging Players: Enter via pediatric sleep-apnea screening workflows, where American Academy of Pediatrics guideline expansion creates addressable clinical volume beyond entrenched adult bruxism markets. White-space targets include bio-based polyurethane formulations qualifying for EU Green Deal sustainable procurement preferences in France and the Netherlands, and at-home impression kit distribution in Australia and Canada. Go-to-market angle emphasizes bypassing dental laboratory intermediaries through direct-to-consumer CAD-CAM integration. For Investors and Strategic Acquirers: The window for entry favors precision dental-laboratory specialists with established notified body relationships and ISO 10993 testing completion. Long-term viability hinges on dual-certification capability spanning ASTM F1140 sports-protection and FDA 510(k) sleep-medicine segments. Acquisition target archetype: regional dental laboratory networks with installed five-axis milling capacity and pediatric sleep-apnea patient pipelines. Signal to watch: state-level scholastic athletic mandate expansion beyond current Illinois and Florida coverage.| Strategic Initiative | Industry Significance |
|---|---|
| CAD-CAM Milling Capacity Acquisition | Compresses custom-fit delivery windows from fourteen days to seventy-two hours for sleep-apnea appliances. |
| Medical-Grade Silicone Backward Integration | Captures resin supply security against German and Japanese chemical conglomerate concentration risk. |
| Direct-to-Consumer Impression Kit Launch | Bypasses traditional dental laboratory intermediaries in Australian and Canadian markets. |
| Bio-Based Polyurethane Formulation Development | Qualifies for EU Green Deal sustainable procurement preferences in France and Netherlands. |
| Dual Certification Quality System Investment | Enables parallel ASTM F1140 and FDA 510(k) compliance for sports and sleep-medicine segments. |
Methodological Framework
Independent corroboration across primary interviews with dental laboratory technicians, collegiate athletic equipment managers, thermoplastic molding operations directors, and dental sleep medicine practitioners, combined with secondary validation through FDA 510(k) filings, ASTM standard documentation, EU Medical Device Regulation notified body records, and customs trade data, underwrites the qualitative findings. Bottom-up demand modeling from state-level scholastic athletic mandate coverage and top-down supply assessment from resin production capacity data establish triangulation boundaries.
Rate-of-change decomposition across the analysis window segments volume trajectories by fabrication method, material chemistry, end-user archetype, and application type, with CAGRs derived from regression against historical replacement cycle frequencies and procurement contract renewal patterns. Modeling incorporates ISO 10993 biocompatibility testing timeline impacts on novel polymer introduction rates and notified body audit cost burdens on European brand participation.
Revisions become necessary when EU REACH enforcement intensity escalates phthalate-containing polymer phaseouts, when state-level scholastic athletic mandate coverage expands beyond current jurisdictions, or when direct-to-consumer impression kit regulatory classification shifts. A model refresh is warranted upon material change in dental-insurance reimbursement code adoption for sleep-disordered breathing appliances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Football Equipment Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Global Darts Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Rubber Fitness Flooring Market