
 Preformed Firestop Devices Market | 2026-2036
Preformed Firestop Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Preformed Firestop Devices Market Analysis
Certified firestop installer labor pools are rotating toward modular construction workflows, tightening availability for conventional site-built projects. 3M Company leverages its captive materials science R&D to sustain dominance in intumescent compound formulations. Hilti Corporation anchors its position through direct channel control over specification-grade fastening and firestop systems. BASF SE differentiates via vertical integration into halogen-free polymer feedstocks that underpin next-generation firestop pillows.
Preformed firestop devices are engineered passive fire protection components, typically fabricated from intumescent graphite, mineral wool, or silicone-based compounds, designed to seal penetrations in rated wall and floor assemblies against flame and smoke propagation. Steel-bodied compression plugs occupy the mature core of the product mix, while adhesive-mounted intumescent wraps represent the fastest-growing installation category as curtain-wall retrofits accelerate across aging commercial stock. Mineral fiber firestop pillows retain the deepest margin pool in industrial process facility applications where re-penetration and maintenance cycles drive recurring specification.
OSHA workplace safety directives and the International Building Code shape product testing protocols and installer certification requirements across the United States construction economy. EMA and REACH frameworks in Europe constrain halogenated additive formulations, redirecting formulation investment toward phosphorus and nitrogen-based intumescent chemistry platforms. Stakeholders must monitor evolving model code adoptions at the municipal level, where local amendments to fire-resistance rating requirements can abruptly restructure specification eligibility for legacy product families.
Market Dynamics
Modular construction workflows are redirecting certified firestop installer labor pools away from conventional site-built projects, tightening field capacity just as International Building Code enforcement intensifies across commercial high-rise development. This labor rotation is compressing project timelines and elevating specification-grade product premiums.
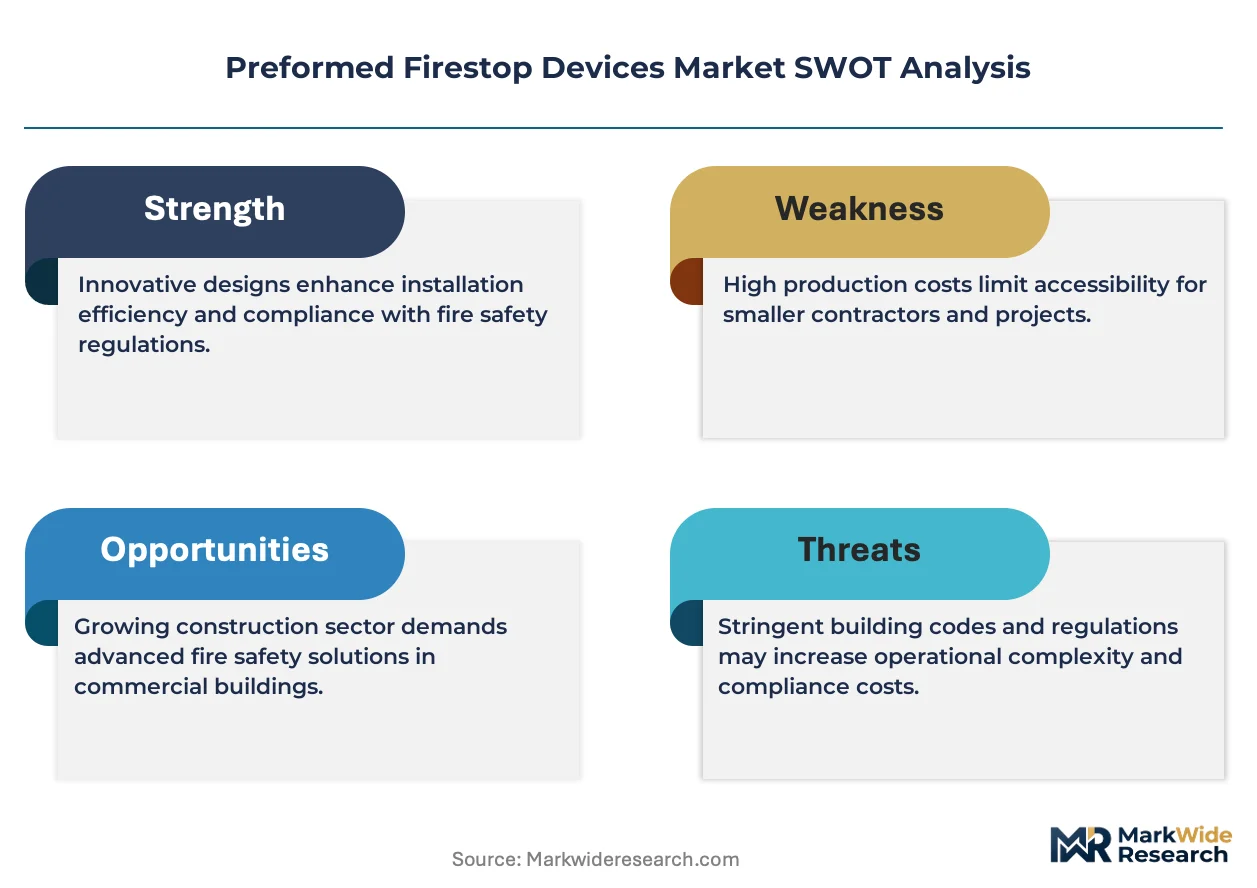
Growth Catalysts
- International Building Code enforcement:Stricter fire-resistance rating requirements in US commercial high-rise construction are mandating specification-grade penetration sealing, expanding addressable project scope for certified systems.
- Germany energy retrofit mandates:National building efficiency programs are accelerating passive fire protection upgrades across aging commercial stock, concentrating demand for adhesive-mounted intumescent wraps.
- Intumescent graphite chemistry:Halogen-free phosphorus and nitrogen-based formulations are gaining formulation preference under ECHA REACH constraints, redirecting R&D investment toward compliant compound platforms.
Market Restraints
- Mineral wool input volatility:Industrial mineral fiber supply concentrates among limited European producers, exposing margin compression when energy costs spike at manufacturing nodes.
- F-Gas Regulation compliance friction:European HVAC sealing applications face reformulation costs and testing recertification timelines that delay product eligibility windows.
- Steel-bodied plug substitution:Compression-based mechanical seals face displacement risk from adhesive-mounted wraps in curtain-wall retrofit segments where speed governs contractor selection.
Strategic Opportunities
- Industrial process facility re-penetration cycles:Maintenance-driven replacement demand for mineral fiber firestop pillows creates recurring revenue pools in petrochemical and power generation installations.
- OSHA workplace safety directive expansion:Enhanced installer certification requirements are creating specification lock-in for manufacturers with captive training infrastructure.
- Silicone-based compound convergence:Hybrid formulations combining intumescent expansion with silicone weather sealing are opening exterior curtain-wall applications previously closed to single-function products.
Industry Challenges
- Certified installer capacity scarcity:Modular construction workflows are absorbing qualified labor pools, extending project lead times for conventional site-built firestop installation.
- Model code amendment fragmentation:Municipal-level variations in fire-resistance rating requirements create product eligibility uncertainty across multi-jurisdiction development portfolios.
- Legacy assembly compatibility:Preformed devices face integration complexity with existing rated wall and floor assemblies where original penetration configurations lack documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preformed Firestop Devices Market |
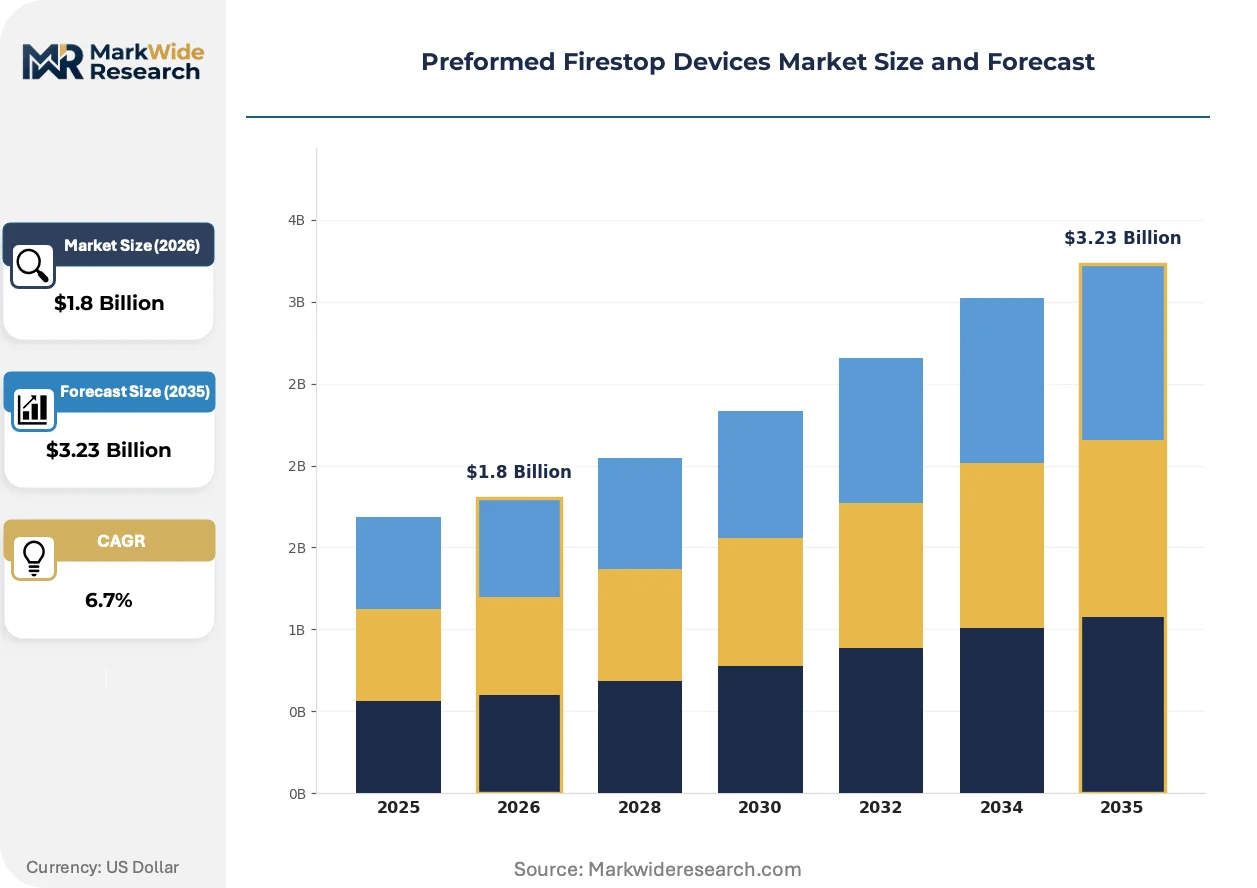
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Wraps, Compression Plugs, Firestop Pillows, Firestop Sealants Installation Method: Pre-assembled, Field-applied, Modular, Adhesive-mounted End User: Construction Firms, Contractors, Architects, Building Owners Material: Steel, Plastic, Mineral Fiber, Silicone |
| Companies Covered | 3M Company, Hilti Corporation, Etex Group, BASF SE, RPM International, Inc., Specified Technologies Inc., Knauf Insulation, Sika AG, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preformed Firestop Devices Market Emerging Trajectories
Adhesive-mounted installation methods are compressing field labor requirements while intumescent chemistry platforms pivot toward halogen-free formulations under chemical regulatory pressure. Specification behavior is shifting toward bundled passive fire protection systems that consolidate penetration sealing with structural fastening.
Intumescent wrap systems are displacing steel-bodied compression plugs in commercial retrofit applications. Curtain-wall contractors facing accelerated project timelines specify adhesive-mounted wraps that eliminate mechanical fastening and reduce per-penetration installation time. This displacement is compressing demand for traditional plug formats in aging commercial stock upgrades while elevating specification importance for surface preparation and substrate compatibility.
EMA and REACH frameworks in Europe are constraining halogenated additive formulations across construction chemical portfolios. Manufacturers are redirecting compound development toward phosphorus and nitrogen-based intumescent chemistry platforms that maintain expansion performance without restricted brominated components. German industrial facility upgrades under national energy mandates represent the most concentrated demand zone for compliant reformulated products.
Buyer concentration among national modular construction contractors is consolidating procurement authority for firestop specification. These contractors are unbundling after-sales technical support from product supply, instead requiring manufacturers to embed installation training within base purchase agreements. United States commercial high-rise developments utilizing prefabricated envelope panels exhibit the most advanced procurement model compression, with specification decisions migrating from individual subcontractors to general contractor procurement offices.
Preformed Firestop Devices Market Segmentation
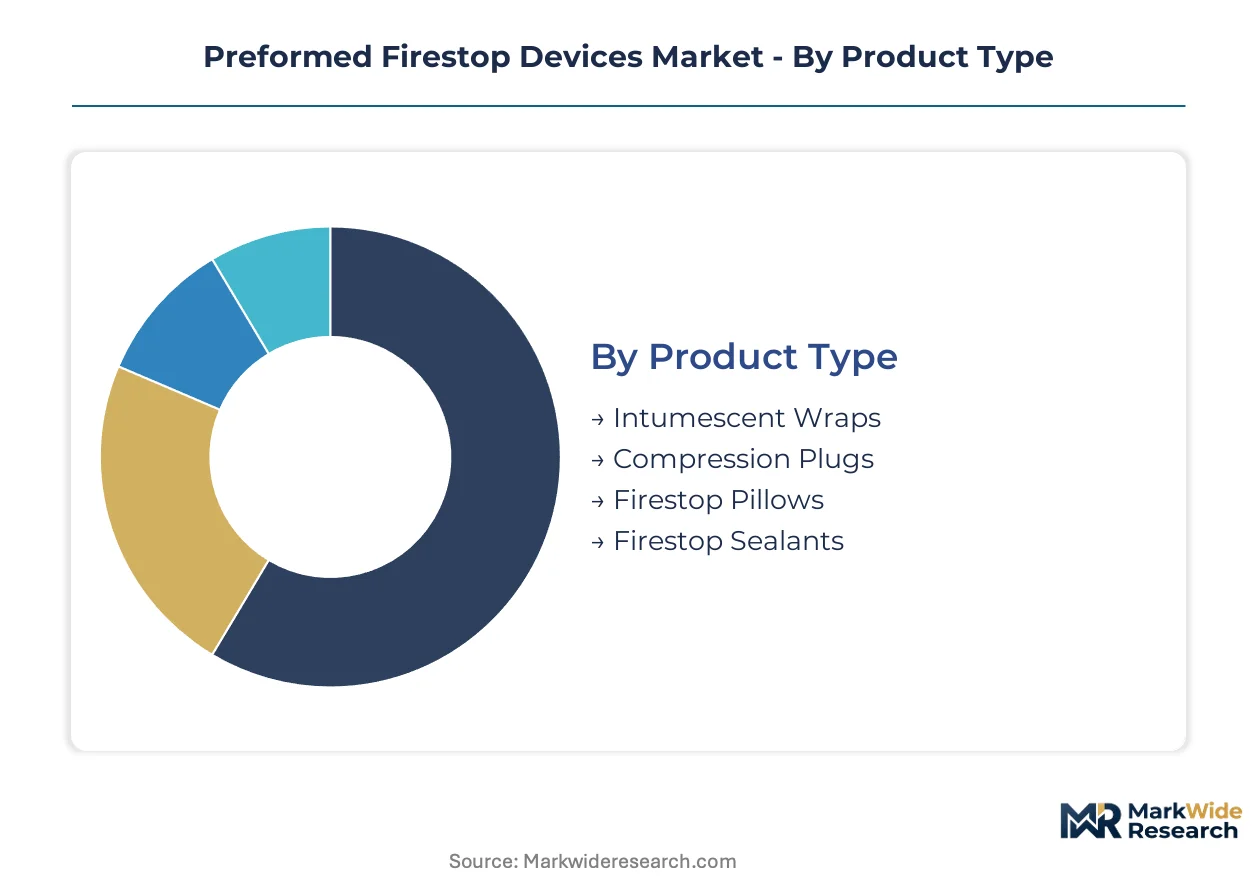
Preformed firestop devices fragment across four structural dimensions that determine specification behavior, procurement authority, and margin capture. Product chemistry and installation mechanics drive substitution risk, while end-user concentration and material cost exposure reshape competitive positioning across construction workflows.
Product Type:
Compression plugs face the most acute substitution pressure as adhesive-mounted alternatives compress installation labor requirements in retrofit applications.
- Intumescent Wraps:Fabricated from expandable graphite compounds bonded to flexible substrates, these systems activate at elevated temperatures to seal penetrations against flame and smoke propagation. Demand concentrates in Germany where F-Gas Regulation compliance and national energy retrofit mandates accelerate passive fire protection upgrades across aging commercial building stock.
- Compression Plugs:Steel-bodied mechanical seals rely on radial compression against penetration openings to maintain fire-resistance ratings. Industrial process facilities in the United States retain specification preference for these formats where re-penetration cycles and maintenance access requirements favor mechanical removal and reinstallation.
- Firestop Pillows:Mineral fiber batts wrapped in protective jackets provide reconfigurable sealing for cable tray and pipe bundle penetrations.
- Firestop Sealants:Pumpable compounds deliver continuous seals in irregular penetration geometries where preformed devices lack dimensional match.
Compression plugs retain volume leadership; intumescent wraps hold the steepest expansion curve.
Installation Method:
Cost tier stratification separates premium factory-integrated formats from economy field-applied alternatives, with labor efficiency driving specification migration.
- Pre-assembled:Factory-integrated firestop components arrive with penetration sleeves and sealing elements pre-installed, eliminating field measurement and cutting. Modular construction contractors in the United States specify these formats to compress envelope panel fabrication timelines and reduce on-site certified installer dependencies.
- Adhesive-mounted:Peel-and-stick intumescent wraps bond directly to substrates without mechanical fastening, reducing per-penetration installation time. Curtain-wall retrofit contractors facing OSHA workplace safety directives and accelerated project schedules specify these systems to minimize scaffolding exposure and labor hour accumulation.
- Field-applied:Conventional site-built installation requires certified firestop installers to measure, cut, and fit devices at penetration locations.
- Modular:Prefabricated penetration assemblies integrate with off-site manufactured wall and floor panels.
Field-applied methods retain volume leadership; adhesive-mounted systems are climbing the fastest.
End User:
Procurement authority concentration among national contractors is compressing specification influence from individual trades to consolidated general contractor procurement offices.
- Construction Firms:National modular construction contractors unbundle after-sales technical support from product supply, requiring manufacturers to embed installation training within base purchase agreements. United States commercial high-rise developments utilizing prefabricated envelope panels exhibit the most advanced procurement model compression.
- Contractors:Specialty firestop subcontractors retain specification influence in conventional site-built projects where penetration complexity demands application-specific product selection.
- Architects:Design-phase specification authority constrains product eligibility through fire-resistance rating documentation and assembly listing requirements.
- Building Owners:Facility managers drive replacement demand in industrial process installations where maintenance cycles trigger re-penetration and firestop renewal.
Construction firms retain volume leadership; building owners hold the steepest expansion curve.
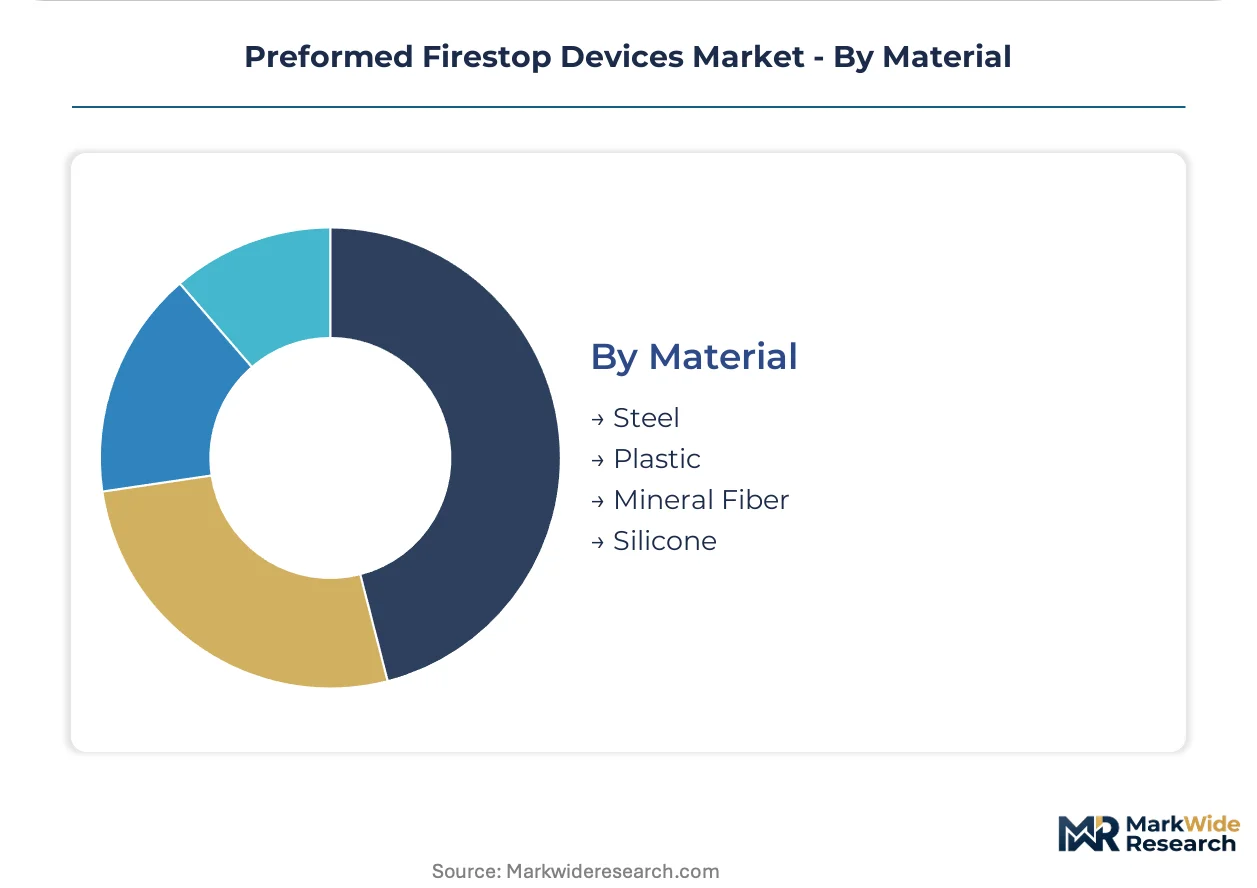
Material:
Supply concentration among limited European producers exposes margin compression when energy costs spike at mineral fiber manufacturing nodes.
- Mineral Fiber:Industrial mineral wool batts provide high-temperature insulation and fire sealing in process facility applications. European producers under ECHA REACH constraints face input cost volatility that transmits through pillow and batt pricing to petrochemical and power generation end users.
- Silicone:Elastomeric compounds combine intumescent expansion with weather sealing, opening exterior curtain-wall applications previously closed to single-function products. Hybrid formulation development concentrates among manufacturers with captive polymer science capabilities.
- Steel:Metal-bodied compression plugs dominate mature specification standards for mechanical penetration sealing.
- Plastic:Polymer-based devices serve lower-temperature applications where cost sensitivity exceeds fire-performance requirements.
Steel retains volume leadership; silicone holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes preformed firestop devices through modular construction workflows, while Germany drives demand via energy retrofit mandates on aging commercial stock. This consumption-mix differential separates new-build specification patterns from retrofit upgrade cycles.
United States
Commercial high-rise developers face intensified OSHA workplace safety directives and International Building Code enforcement. Certified installer labor pools are rotating toward prefabricated envelope panel fabrication, tightening field capacity for conventional site-built projects. The Pacific Northwest and Southeast corridor exhibit the most advanced modular procurement models, with specification decisions migrating to general contractor procurement offices.
Germany
National building efficiency programs and F-Gas Regulation compliance are accelerating passive fire protection upgrades across aging commercial stock. ECHA REACH constraints on halogenated additives redirect formulation investment toward phosphorus and nitrogen-based intumescent chemistry platforms. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate demand for adhesive-mounted intumescent wraps in curtain-wall retrofit applications.
China
Urban renewal initiatives and dual carbon goals are expanding fire-resistance rating requirements in commercial building renovations. GB standards and MIIT industrial policy shape product testing protocols for penetration sealing systems. The Yangtze River Delta and Pearl River Delta manufacturing corridors drive specification-grade mineral fiber firestop pillow demand in process facility construction.
Japan
METI building energy efficiency mandates and JIS standards compliance are elevating specification requirements for halogen-free firestop formulations. High-rise commercial development in Tokyo and Osaka prioritizes adhesive-mounted installation methods to compress project timelines. The Kanto region anchors domestic demand for silicone-based hybrid compounds combining intumescent expansion with weather sealing.
United Kingdom
Post-Grenfell regulatory revisions and Building Safety Act implementation are tightening fire-resistance documentation requirements for penetration sealing. CE marking transitions and UKCA conformity pressures are extending product recertification timelines for European suppliers. London and the Southeast corridor concentrate retrofit specification activity for steel-bodied compression plugs in heritage commercial stock upgrades.
Preformed Firestop Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in preformed firestop devices. Materials science conglomerates with captive polymer R&D occupy the upper tier, while regional fabrication specialists serve contractor procurement channels below. Three archetypes dominate: diversified chemicals conglomerates with intumescent formulation capabilities, construction fastening specialists with direct specification control, and mineral fiber producers with industrial process facility relationships. Competitive moves concentrate on backward integration into halogen-free feedstocks and captive installer certification infrastructure.
Among diversified chemicals conglomerates, 3M Company and BASF SE exemplify integrated leaders with materials science depth. Hilti Corporation anchors the construction fastening specialist archetype with direct channel presence. These three entities represent distinct competitive vectors: formulation chemistry control, specification-grade system bundling, and installer certification capture. Their positioning reflects divergent bets on whether adhesive-mounted wraps or factory-integrated modular formats will dominate next-generation procurement.
| Leading Market Players |
|---|
| 3M Company |
| Hilti Corporation |
| Etex Group |
| BASF SE |
| RPM International, Inc. |
| Specified Technologies Inc. |
| Knauf Insulation |
| Sika AG |
| Morgan Advanced Materials |
| Others |
Supply Flow & Price Mechanics
Adhesive-mounted intumescent wraps displacing steel-bodied compression plugs in curtain-wall retrofits simultaneously redraw supply geography toward flexible substrate manufacturers in Germany and compress pricing power for legacy mechanical seal producers. This substitution dynamic reroutes procurement authority from industrial metalworking clusters to polymer chemistry specialists, fragmenting historical pricing benchmarks across installation-method lines.
Pricing Analysis
Long-term offtake agreements dominate specification-grade procurement among national modular construction contractors, while spot purchasing persists for maintenance-driven replacement orders in industrial facilities. Three-tier pricing structure across premium, standard, and economy levels separates factory-integrated pre-assembled formats from field-applied alternatives, with certification tier and after-sales training bundling as primary differentiation drivers. Cost compression in economy-grade mineral fiber pillows is intensifying because European energy input volatility transmits through limited producer concentration. Building owners in process facility applications exhibit lowest price sensitivity due to regulatory compliance imperatives, whereas curtain-wall retrofit contractors face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific manufacturing corridors through Rotterdam and Hamburg port complexes expose European distributors to container availability fluctuations on the Shanghai-Rotterdam trade lane. Supply concentrates among German intumescent compound formulators, Chinese mineral fiber producers, and United States silicone polymer specialists, with raw material dependencies spanning expandable graphite feedstocks, industrial mineral wool, and halogen-free phosphorus-based additives. Single-source vulnerability in European mineral fiber manufacturing creates structural risk during energy price spikes. Distribution runs through specification-grade fastening distributors and direct contractor procurement offices, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preformed firestop devices present a fragmentation opportunity as procurement authority consolidates among national modular contractors while specification complexity multiplies across retrofit, new-build, and industrial maintenance workflows. This demand-side shift creates defendable niches for specialists with captive chemistry or certification infrastructure.
For Market Incumbents: Fortify specification lock-in through captive installer certification programs that embed training within base purchase agreements, countering labor pool rotation toward modular workflows. Backward integration into halogen-free phosphorus feedstocks defends margin position against ECHA REACH compliance costs while securing supply priority during raw material allocation cycles.
For New Entrants and Emerging Players: Anchor in adhesive-mounted intumescent wrap segments where speed-to-install specifications displace legacy mechanical seals in Germany's energy retrofit pipeline. White-space concentration exists in silicone-based hybrid compounds for exterior curtain-wall applications, with go-to-market traction through direct engagement with national modular construction procurement offices rather than traditional distributor channels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors materials science specialists with captive polymer R&D and specification-grade bundling capabilities over pure-play fabricators. Long-term viability across the projection horizon hinges on regulatory compliance agility rather than scale economies alone. The signal to watch is municipal-level International Building Code amendment velocity, which abruptly restructures product eligibility and rewards agile formulation portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halogen-Free Feedstocks | ECHA REACH compliance secures formulation continuity for German retrofit demand. |
| Captive Installer Certification Infrastructure | OSHA workplace safety directives create specification lock-in through embedded training. |
| Hybrid Silicone-Intumescent Compound Development | Exterior curtain-wall applications open previously closed specification categories. |
| Long-Term Supply Agreements with Modular Contractors | Prefabricated envelope panel fabrication compresses procurement decision timelines. |
| Geographic Capacity Expansion in Southeast United States | Pacific Northwest and Southeast corridor modular construction concentrates demand. |
Methodological Framework
Operator-level perspectives from certified firestop installers, modular construction procurement officers, specification-grade fastening distributors, and industrial facility maintenance directors anchored the qualitative base for this study. Primary field engagement combined with secondary validation from International Building Code amendment filings, OSHA workplace safety directive records, ECHA REACH substance restriction updates, and customs trade data for intumescent compound and mineral fiber categories. Bottom-up penetration sealing demand estimates triangulated against top-down construction spending allocations across commercial high-rise and industrial process facility segments.
Sensitivity analysis around labor pool rotation velocity and regulatory amendment timing shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product chemistry platform, installation mechanics, end-user procurement authority concentration, and material cost exposure. CAGRs derived from installation-method substitution curves and retrofit cycle frequency in aging commercial stock, with mineral fiber input cost volatility and certified installer capacity constraints as key forecast inputs.
Material uncertainties — abrupt municipal code amendments, energy cost spikes at European mineral fiber nodes, and modular construction workflow adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution elasticity and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Electrochromic Glass Market
Construction and Engineering
Canada Architectural Coatings Market
Construction and Engineering
France Commercial HVAC Market
Construction and Engineering
US Residential Furnace Market
Construction and Engineering
Conventional Overhead Conductor Market
Construction and Engineering
Woodworking Power Tools Market
Construction and Engineering
Italy Cement Market
Construction and Engineering
Heavy Loader Market
Construction and Engineering
Diamond Hole Saw Market
Construction and Engineering
Compactor Market
Construction and Engineering
Compressed Earth Block Machine Market
Construction and Engineering
Decorative Tiles Market
Construction and Engineering
Japan Commercial Construction Market
Construction and Engineering
Asia-Pacific Ceramic Sanitary Ware Market
Construction and Engineering
Baler Market
Construction and Engineering
Self-Consolidating Concrete (SCC) Market