
 Digital Load Indicator Market | 2026-2036
Digital Load Indicator Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Load Indicator Market Insights
Aftermarket service revenue is narrowing toward calibration and recertification contracts as original equipment margins compress. Vishay Precision Group leverages its strain gauge heritage to dominate high-accuracy segments across aerospace and industrial scales. Straightpoint competes through wireless load monitoring specialization, while Mettler Toledo anchors laboratory and process weighing with integrated digital indicator platforms.
A digital load indicator is an electronic display device that converts analog signals from load cells into readable weight or force measurements, typically achieving resolutions of 1 part in 10,000 or better for precision industrial applications. These instruments serve critical safety and quality control functions by providing real-time load data to prevent equipment overload and ensure regulatory compliance in lifting and weighing operations. Wired load indicators retain dominance in permanent installations where signal stability outweighs mobility requirements, yet wireless display units represent the fastest-expanding segment as battery efficiency and mesh networking protocols enable untethered crane and construction site deployments. Strain gauge technology leads by installed base due to proven linearity and temperature compensation, though capacitive sensing gains traction in corrosive environments where traditional foil gauges degrade.
OSHA crane safety standards and the EU Machinery Directive shape product certification requirements, compelling manufacturers to embed redundant safety relays and sealed enclosures rated to IP67 or higher. The EU AI Act and emerging predictive maintenance regulations will soon classify certain smart load indicators as safety-critical AI components, triggering additional conformity assessment obligations. Stakeholders must monitor how regulatory convergence between North American and European safety standards affects product platform strategies and certification cost structures.
Market Dynamics
Wireless mesh networking protocols are compressing installation timelines for construction and logistics operators while simultaneously eroding the installed base advantage of wired legacy systems. This technological inflection is redistributing value capture toward battery-efficient display manufacturers and away from traditional cable-assembly suppliers.
Growth Catalysts
- OSHA crane safety enforcement:Tighter calibration mandates for lifting equipment in the United States are accelerating replacement cycles for analog gauge systems across commercial construction sites.
- Precision engineering standards:German industrial automation investments are elevating digital load indicator deployment in manufacturing and logistics operations.
- Strain gauge linearity:Proven temperature compensation characteristics sustain reliability premiums in aerospace and heavy industrial weighing applications.
Market Restraints
- Semiconductor input volatility:Analog-to-digital converter chip supply concentration in East Asian foundries creates production scheduling uncertainty for indicator manufacturers.
- EU conformity assessment burden:The EU AI Act's emerging classification of predictive maintenance load indicators as safety-critical components extends certification timelines and raises compliance costs.
- Capacitive sensing substitution:Corrosive environment applications are migrating toward capacitive alternatives where traditional foil strain gauges degrade prematurely.
Strategic Opportunities
- Underpenetrated Indian infrastructure:Central Electricity Authority and Bureau of Indian Standards harmonization efforts are creating first-mover advantages for certified digital indicator suppliers in power transmission and port modernization projects.
- Predictive maintenance convergence:Integration of vibration sensing with load data streams is enabling condition-based monitoring contracts that displace traditional break-fix service models.
- EU Green Deal procurement incentives:Public infrastructure tenders with embedded carbon accounting requirements favor lightweight wireless indicators over copper-intensive wired installations.
Industry Challenges
- Calibration technician scarcity:Specialized metrology expertise required for ISO 376 and OIML R60 traceability is concentrating in aging workforce pools across industrialized markets.
- Legacy system integration friction:Proprietary communication protocols in installed crane control architectures complicate retrofit deployments of open-standard wireless indicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Load Indicator Market |
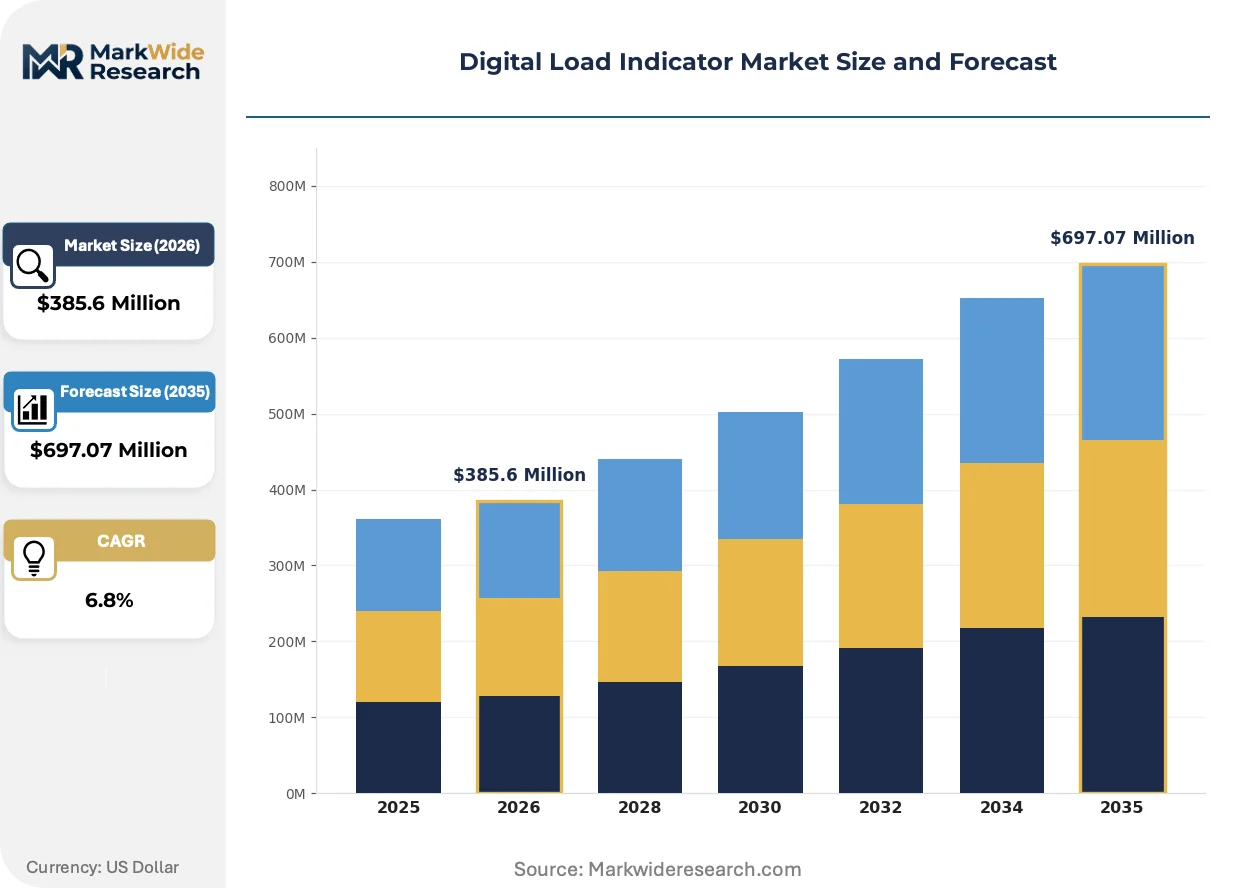
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Load Indicator, Wired Load Indicator, Digital Crane Scale, Load Cell Indicator, Wireless Display Unit Technology: Strain Gauge, Hydraulic, Pneumatic, Piezoelectric, Capacitive Application: Cranes, Load Testing, Manufacturing Monitoring, Construction Safety, Shipping Weighing End User: Construction Firms, Manufacturing Plants, Shipping Companies, Testing Laboratories, Heavy Machinery Operators |
| Companies Covered | Vishay Precision Group, Straightpoint, Mettler Toledo, Spectris, Flintec, Precia Molen, LCM Systems, Eilon Engineering, Thames Side Sensors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Load Indicator Market Trends and Innovations
Real-time data architectures are displacing batch-recorded weighing workflows across safety-critical lifting operations. This shift is compressing the acceptable latency window for load indication while expanding the functional boundary of what these devices must process and transmit.
Silicon carbide strain sensing elements are hybridizing the performance envelope of traditional foil gauges with the corrosion resistance of capacitive alternatives. Offshore wind turbine maintenance contractors in the North Sea are adopting these hybrid sensors at accelerated pace to address salt-air degradation of conventional installations. The technology is hybridizing supplier value chains as materials specialists acquire signal-conditioning electronics capabilities to deliver integrated subsystems.
The EU AI Act's safety-critical component classification is mandating redundant safety relay architectures and sealed IP67 enclosures for smart load indicators with embedded predictive algorithms. This regulatory friction is compressing product development timelines for manufacturers lacking existing conformity assessment infrastructure. Laboratory and process weighing segments in Germany and France are experiencing the steepest compliance cost escalations as notified bodies develop interpretation guidance for AI-integrated measurement devices.
Service contract unbundling is fragmenting buyer-supplier relationships in the crane and lifting equipment channel. End-users in United States construction markets are separating hardware procurement from calibration and recertification services, compressing original equipment margins while expanding aftermarket revenue pools for specialized metrology service providers. This behavioral shift is most visible in metropolitan infrastructure corridors where OSHA inspection frequency has intensified operator sensitivity to documentation compliance.
Digital Load Indicator Market Segmentation
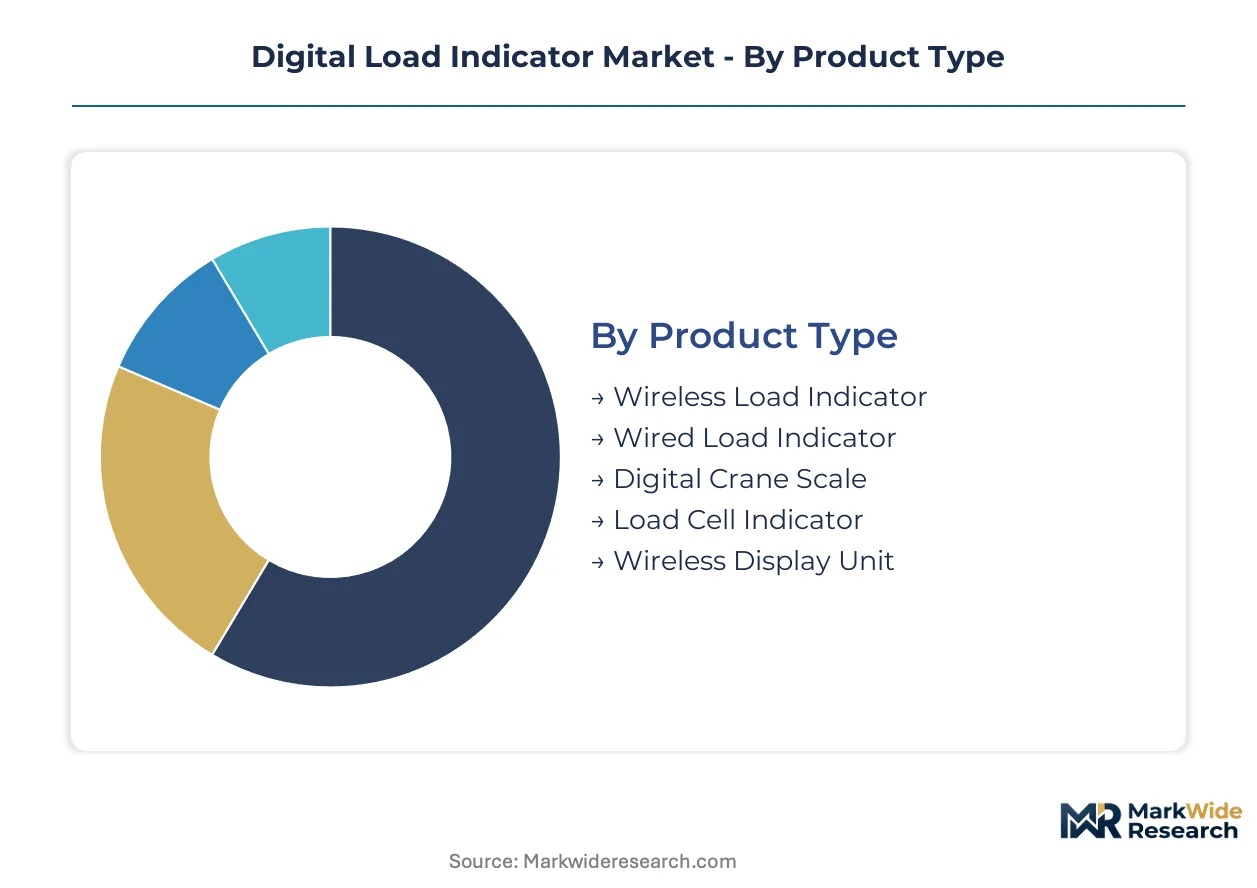
Product differentiation in digital load indicators follows distinct replacement rhythms. Construction procurement cycles compress hardware refresh timelines, while laboratory calibration mandates stretch service intervals. Understanding these temporal patterns reveals where revenue concentrates versus where it expands.
Product Type:
Replacement velocity separates permanent infrastructure installations from portable field deployments. Wired systems embed for decades in factory floors, while wireless units cycle through construction sites on project timelines.
- Wireless Load Indicator:Battery-powered units with integrated radio frequency transmission enable untethered crane operations and mobile construction workflows. North American infrastructure corridors drive procurement as OSHA inspection intensity elevates documentation requirements for temporary lifting setups.
- Wired Load Indicator:Hardwired signal paths deliver millisecond-level latency for permanent manufacturing installations. German precision engineering standards sustain demand in automated production lines where electromagnetic interference resistance outweighs mobility needs.
- Digital Crane Scale:Integrated weighing systems combine load sensing with onboard processing for suspended load measurement. Port modernization projects in India concentrate procurement where Bureau of Indian Standards certification creates compliance gates.
- Load Cell Indicator:Modular display units pair with third-party strain gauge sensors across industrial weighing platforms. Food processing and pharmaceutical manufacturing in France and Italy anchor replacement demand.
- Wireless Display Unit:Standalone visualization hardware receives mesh-networked signals from distributed sensors. Offshore wind maintenance contractors in the North Sea adopt these for turbine component lifting where cable routing proves impractical.
Wired Load Indicator dominates installed base. Wireless Load Indicator is where expansion concentrates.
Technology:
Cost tier stratification aligns with environmental exposure severity. Standard foil gauges occupy price-sensitive indoor applications, while exotic materials command premiums for corrosive or extreme-temperature deployments.
- Strain Gauge:Metal foil or semiconductor elements measure deformation through resistance change, achieving linearity within 0.03% across calibrated temperature ranges. Aerospace material testing and heavy industrial weighing in the United States sustain technology leadership through proven traceability to NIST standards.
- Capacitive:Electrode gap variation senses load without mechanical strain element fatigue, eliminating corrosion vulnerability in chemical processing and marine environments. Offshore oil platform operators in Norway and the United Kingdom accelerate substitution where salt spray degrades conventional gauges.
- Hydraulic:Fluid pressure transduction converts mechanical force to readable output in explosive atmosphere applications. Mining and underground construction in Australia and Canada retain this legacy technology where electrical ignition risks persist.
- Piezoelectric:Crystal elements generate charge proportional to dynamic force, excelling at impact and vibration measurement. Automotive crash testing laboratories in Germany and Japan anchor niche demand.
- Pneumatic:Air pressure modulation provides intrinsic safety in grain handling and dust-laden environments. Agricultural processing in the United States Midwest maintains sporadic procurement.
Strain Gauge captures the highest volume tier. Capacitive is climbing the fastest as corrosive environment specifications tighten.
Application:
Customer type fragmentation separates safety-critical lifting from quality-control weighing. Crane operators face regulatory inspection exposure, while manufacturing monitors prioritize process integration.
- Construction Safety:Real-time overload prevention systems integrate with crane control architectures to interrupt lift operations at threshold breach. United States commercial construction sites drive replacement cycles as OSHA enforcement intensifies in metropolitan infrastructure corridors.
- Cranes:Integrated load moment indicators calculate structural limits across boom geometry configurations. Tower crane fleets in Germany and France embed these as standard equipment under EU Machinery Directive compliance mandates.
- Manufacturing Monitoring:In-process weighing validates assembly tolerances and material consumption in automated production. Automotive component plants in Mexico and the United States sustain demand for high-speed data acquisition.
- Load Testing:Calibration-grade verification of lifting equipment and structural elements demands traceable measurement chains. Third-party inspection services in the United Kingdom and Netherlands concentrate procurement.
- Shipping Weighing:Container and bulk cargo measurement supports trade documentation and vessel stability calculations. Port authorities in Singapore and Rotterdam anchor large-scale deployments.
Cranes dominates installed base. Construction Safety is gaining share fastest as regulatory inspection frequency escalates.
End User:
Procurement sophistication separates asset-heavy operators from service-dependent laboratories. Volume buyers negotiate hardware commoditization, while calibration-dependent users lock into long-term service relationships.
- Construction Firms:Project-based equipment procurement cycles compress replacement timelines versus permanent industrial installations. United States metropolitan infrastructure contractors separate hardware acquisition from calibration services, fragmenting supplier relationships.
- Manufacturing Plants:Process integration requirements prioritize communication protocol compatibility over standalone measurement accuracy. German industrial automation investments elevate digital indicator deployment in automotive and machinery production.
- Heavy Machinery Operators:Fleet standardization across cranes, excavators, and material handlers drives volume procurement with aftermarket service bundling. Mining contractors in Australia and Chile concentrate demand for ruggedized field units.
- Testing Laboratories:ISO 17025 accreditation mandates dictate calibration traceability and measurement uncertainty documentation. National metrology institutes and commercial calibration houses in France, Germany, and the United States anchor demand.
- Shipping Companies:SOLAS convention compliance for verified gross mass reporting drives container weighing system upgrades. Container lines and terminal operators in Singapore, Rotterdam, and Los Angeles sustain replacement demand.
Manufacturing Plants dominates installed base. Construction Firms is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. United States construction contractors absorb premium pricing for OSHA-compliant wireless systems, while Indian port operators prioritize certified economy-tier units for Bureau of Indian Standards compliance.
United States
Metropolitan infrastructure corridors drive wireless load indicator procurement as OSHA crane safety enforcement intensifies documentation requirements. The Department of Labor mandates calibration traceability for lifting equipment across commercial construction sites. Tower crane fleets in New York, Chicago, and Los Angeles anchor replacement demand for integrated load moment indicators.
Germany
Automotive component plants and automated production lines sustain demand for hardwired precision indicators with millisecond-level latency. The EU Machinery Directive and impending EU AI Act compliance obligations compress product development timelines for smart indicators with embedded predictive algorithms. Industrial clusters in Bavaria and Baden-Württemberg concentrate high-accuracy deployment for aerospace material testing.
India
Port modernization and power transmission projects concentrate procurement as Central Electricity Authority and Bureau of Indian Standards harmonization creates compliance gates. Public infrastructure tenders favor certified suppliers with established calibration networks. Jawaharlal Nehru Port Trust and Mundra Port anchor large-scale container weighing system upgrades.
United Kingdom
Offshore wind maintenance contractors in the North Sea accelerate adoption of hybrid silicon carbide strain sensing for salt-air corrosion resistance. The Health and Safety Executive enforces LOLER regulations for lifting equipment inspection intervals. Aberdeen and Hull marine engineering clusters drive demand for sealed IP67 wireless display units.
China
Domestic manufacturing scale and dual carbon goals favor lightweight wireless indicators over copper-intensive wired installations in greenfield industrial parks. SAMR national standards alignment with OIML R60 elevates calibration infrastructure investment. Yangtze River Delta automotive and machinery production anchors process weighing integration demand.
Digital Load Indicator Market Competitive Landscape
Capability concentration sits with heritage strain gauge specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base stratifies across three tiers: precision-engineering specialists with metrology lineage, wireless connectivity-focused technology entrants, and integrated weighing platform providers with laboratory-to-field portfolios. Dominant competitive moves include backward integration into sensor element manufacturing and geographic expansion through calibration service network franchising.
Within the precision-engineering specialist tier, Vishay Precision Group exemplifies heritage capability in high-accuracy strain gauge applications, while Straightpoint occupies a position in wireless load monitoring specialization. Mettler Toledo anchors the integrated platform provider archetype with laboratory and process weighing convergence. These three represent distinct strategic postures: component heritage, connectivity specialization, and end-to-end system integration.
| Leading Market Players |
|---|
| Vishay Precision Group |
| Straightpoint |
| Mettler Toledo |
| Spectris |
| Flintec |
| Precia Molen |
| LCM Systems |
| Eilon Engineering |
| Thames Side Sensors |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in East Asian analog-to-digital converter foundries is compressing production scheduling flexibility for indicator manufacturers, forcing allocation prioritization toward long-term contract buyers and eroding spot-market pricing power for smaller OEMs.
Pricing Analysis
Aftermarket calibration and recertification service contracts now drive lifetime value capture as original equipment hardware margins compress. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade strain gauge systems with NIST traceability from construction-tier wireless units and economy indicators for Indian port compliance. Pricing pressure stems from semiconductor input volatility and buyer unbundling of hardware from service procurement. Construction firms in United States metropolitan corridors show lowest price sensitivity due to OSHA enforcement exposure, while Indian public infrastructure tender participants prioritize certified economy-tier units.
Supply Chain Analysis
Contract manufacturing for signal-conditioning electronics concentrates in Taiwan and South Korea, with final assembly and calibration capacity distributed across Germany, United States, and China. Raw material dependencies center on high-purity copper for strain gauge foil, silicon carbide substrates for hybrid sensing elements, and lithium-ion cells for wireless display power. Single-source vulnerability in East Asian ADC chip supply creates production scheduling risk. Distribution runs through industrial instrumentation distributors and OEM direct channels, with aftermarket service networks increasingly franchised to specialized metrology providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward construction firms unbundling hardware procurement from calibration services, fragmenting supplier relationships and compressing original equipment pricing leverage.
For Market Incumbents: Insulate margin position by embedding predictive maintenance algorithms as subscription-tier software companions, locking buyers into recurring calibration contracts. Deepen backward integration into strain gauge element manufacturing to offset semiconductor input volatility. Prioritize certification investment for EU AI Act safety-critical component classification ahead of notified body interpretation guidance. For New Entrants and Emerging Players: Mid-market wireless load indicators for Indian power transmission and port modernization projects represent the most penetrable entry point, where Bureau of Indian Standards harmonization creates first-mover compliance advantages. Offshore wind maintenance contractors in the North Sea offer secondary white-space for sealed IP67 display units. Go-to-market through calibration service network franchising bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage strain gauge specialists with established metrology service infrastructure. Long-term viability favors targets with embedded predictive maintenance capabilities and existing conformity assessment relationships with European notified bodies. Watch for EU AI Act implementation timeline acceleration as inflection signal for compliance-cost escalation and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Elements | Captive supply of strain gauge foil reduces semiconductor input volatility exposure. |
| Predictive Maintenance Algorithm Development | EU AI Act classification mandates redundant safety relay architectures for smart indicators. |
| Calibration Service Network Franchising | OSHA inspection intensity elevates documentation requirements for construction safety applications. |
| Wireless Mesh Protocol Certification | Battery efficiency standards enable untethered crane deployments in North American infrastructure corridors. |
| Silicon Carbide Sensing Element Adoption | Offshore wind contractors in the North Sea address salt-air degradation of conventional foil gauges. |
Research Methodology
A spread of perspectives from crane fleet operators, calibration service technicians, OEM procurement managers, and notified body assessors converged on the working assumptions for this analysis. Primary interviews with construction safety directors and industrial automation engineers combined with secondary validation from OSHA enforcement data, EU Machinery Directive implementation reports, Bureau of Indian Standards certification records, and SAMR national standards alignment documentation. Bottom-up unit economics triangulated against top-down industrial instrumentation market sizing.
Demand-supply balance dynamics across product type, technology, application, and end-user segmentation anchored the analytical framework over the projection horizon. Modeled dimensions included wired versus wireless connectivity, strain gauge versus capacitive sensing, construction safety versus manufacturing monitoring applications, and construction firm versus manufacturing plant end-user archetypes. CAGRs derived from replacement cycle analysis and regulatory enforcement intensity trajectories incorporated semiconductor supply constraints and EU AI Act compliance timeline uncertainty.
Macroeconomic conditions sit as an overlay; deviation in infrastructure investment cycles, East Asian foundry capacity utilization, or trans-Atlantic regulatory harmonization pace would shift the trajectory. Quarterly review of OSHA inspection frequency data, EU notified body guidance publication, and Indian Central Electricity Authority tender issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Industrial Joysticks Market