
 Thermal Cleaning System Market | 2026-2036
Thermal Cleaning System Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Cleaning System Market Analytics
Equipment leasing and project finance for thermal cleaning installations is fragmenting competitive access across mid-sized manufacturers. Schwing Technologies GmbH leverages its German engineering base to dominate high-temperature pyrolysis systems for polymer removal. Baker Furnace Inc. competes through vertical integration into combustion chamber fabrication, controlling critical component costs. Nabertherm GmbH sustains technology leadership in precision thermal processing, specializing in batch configurations for laboratory and industrial scale operations.
Thermal cleaning systems employ controlled pyrolysis or thermal decomposition, typically operating between 400°C and 600°C, to remove organic contaminants such as polymers, paints, and oils from metal components without abrasive damage. Continuous cleaning configurations lead volume deployment in automotive parts remanufacturing, where throughput requirements favor conveyorized thermal decomposition over batch cycling. Portable systems represent the fastest-expanding delivery mode, as oilfield service providers seek mobile pyrolysis units for on-site drill bit and downhole tool refurbishment at remote extraction sites.
The EPA enforces Maximum Achievable Control Technology standards for thermal oxidizers, compelling system upgrades with afterburners and scrubber integration. OSHA mandates lockout-tagout and confined-space protocols for batch oven maintenance, shaping operator training and equipment design requirements. ISO 14001 environmental management certification increasingly gates supplier qualification for aerospace OEMs. Stakeholders must monitor evolving state-level emissions thresholds and weigh capital deployment timing against anticipated regulatory tightening in industrial thermal processing.
Market Dynamics
EPA Maximum Achievable Control Technology standards are forcing thermal oxidizer upgrades across North American manufacturing, compressing replacement cycles and redistributing capital toward closed-loop pyrolysis architectures with integrated afterburner systems.
Growth Catalysts
- Aerospace OEM Certification Requirements:ISO 14001 environmental management certification now gates supplier qualification for turbine component refurbishment contracts, accelerating thermal cleaning adoption at maintenance facilities in Germany and the United States.
- REACH Chemical Compliance:ECHA restrictions on solvent-based cleaning agents are eliminating chemical alternatives for polymer removal, directing mold and die manufacturers toward pyrolysis-based thermal decomposition systems.
- Remote Oilfield Mobilization:Portable thermal cleaning units enable on-site drill bit refurbishment at extraction sites in West Texas and North Dakota, eliminating logistics costs of shipping contaminated components to centralized facilities.
Market Restraints
- Refractory Material Cost Volatility:Alumina-silica ceramic linings for high-temperature chambers face price instability tied to bauxite supply concentration in Guinea and Australia, compressing margins for system fabricators.
- German Engineering Cluster Concentration:Precision thermal processing technology development concentrates in Baden-Württemberg and Bavaria, creating supplier bottleneck risk for non-European buyers seeking high-fidelity batch configurations.
- Water Scrubber Substitution Threat:Closed-loop aqueous cleaning systems with advanced filtration are capturing low-temperature polymer removal applications below 350°C, constraining addressable market expansion for thermal methods.
Strategic Opportunities
- Indian Precision Manufacturing Expansion:Pune and Chennai industrial corridors are establishing tool and die maintenance clusters with limited thermal cleaning penetration, creating first-mover positioning for pyrolysis system deployment.
- EU Green Deal Industrial Emissions Incentives:Member state decarbonization subsidies for process heat electrification are accelerating demand for electric-resistance thermal cleaning as replacement for gas-fired combustion chambers.
- Automotive Remanufacturing Convergence:Integration of thermal cleaning with automated inspection robotics is enabling single-flow processing for engine block refurbishment, compressing cycle times at remanufacturing facilities in Detroit and Stuttgart.
Industry Challenges
- Pyrolysis Technician Certification Delays:OSHA confined-space and lockout-tagout protocols require specialized training programs that extend workforce deployment timelines by four to six months at batch oven installations.
- Legacy Control System Integration:Retrofitting continuous conveyorized thermal cleaners with Industry 4.0 monitoring architectures requires custom middleware development, extending commissioning periods and inflating project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Cleaning System Market |
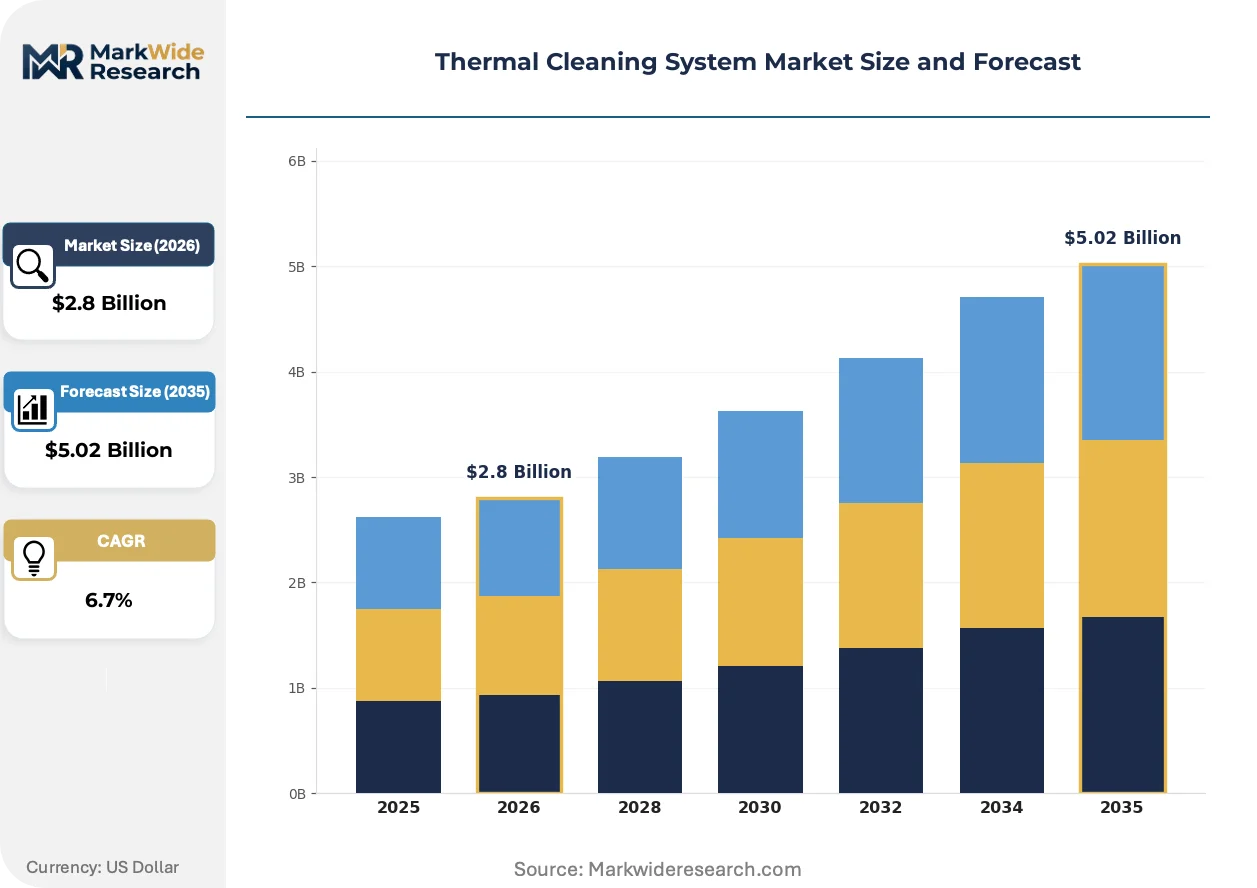
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Cleaning, Continuous Cleaning, Portable Systems, Custom Solutions Application: Industrial Equipment, Automotive Parts, Aerospace Components, Oilfield Services Delivery Mode: On-Site Services, Off-Site Services, In-House Systems, Mobile Units End User: Manufacturers, Clinics, Service Providers, Government Agencies |
| Companies Covered | Schwing Technologies GmbH, Baker Furnace Inc., Nabertherm GmbH, Despatch Industries, Heraeus Holding GmbH, Deco Technology Group, Inc., Flame Treating Systems, Inc., Nippon Gases, KleenTec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Cleaning System Market Evolving Landscape
Infrared thermography and real-time gas analysis are converging to enable predictive maintenance and emissions compliance verification, shifting competitive advantage toward system integrators with sensor fusion capabilities rather than standalone equipment fabricators.
Electric-resistance heating elements with silicon carbide substrates are rendering obsolete gas-fired combustion chambers in applications below 650°C, automotive parts remanufacturers in Michigan and Ohio are adopting these configurations to eliminate NOx permitting complexity, and this transition is compressing the installed base of natural gas thermal cleaners by accelerating replacement timelines.
The EPA's 2023 updates to Maximum Achievable Control Technology standards for halogenated waste streams are mandating secondary combustion chambers and continuous emissions monitoring, chemical processing facilities in Texas and Louisiana are retrofitting existing thermal oxidizers with integrated scrubber trains, and batch pyrolysis operators serving polymer recycling are absorbing capital cost increases of fifteen to twenty percent to achieve compliance.
Service contracting models are displacing equipment ownership for mid-volume manufacturers, thermal cleaning providers in Germany's Ruhr industrial region are offering throughput-based pricing with guaranteed uptime commitments, and this shift is concentrating maintenance expertise with OEM service organizations while fragmenting purchasing authority between operations and procurement functions at buyer facilities.
Thermal Cleaning System Market Segmentation
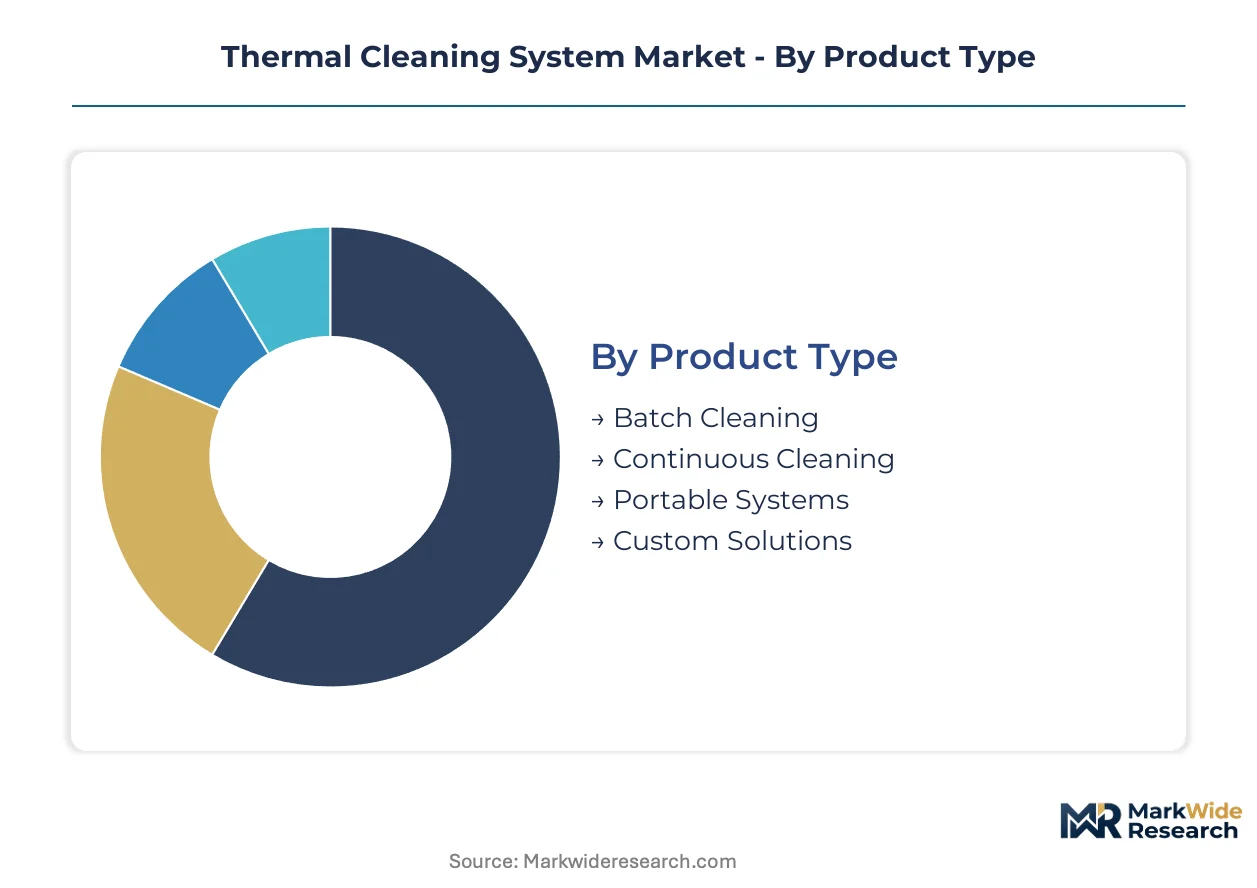
Thermal cleaning system architecture varies sharply by operational cadence and mobility requirements. Aerospace OEMs in Stuttgart and oilfield contractors in West Texas impose fundamentally different constraints on chamber design, throughput capacity, and emissions control integration.
Product Type:
Batch configurations dominate mold and die maintenance where component variety exceeds volume, while continuous systems serve automotive remanufacturing lines with standardized throughput.
- Batch Cleaning:Chamber-based thermal decomposition cycles accommodate irregular component geometries and mixed polymer loads. German precision engineering clusters in Baden-Württemberg favor these systems for high-fidelity turbine blade refurbishment where thermal profile control prevents substrate damage.
- Continuous Cleaning:Conveyorized thermal processing achieves sustained throughput for engine block and transmission component remanufacturing. Detroit-area automotive facilities deploy these configurations to compress cycle times below four hours per unit.
- Portable Systems:Trailer-mounted pyrolysis units enable drill bit refurbishment at remote extraction sites in North Dakota and West Texas.
- Custom Solutions:Purpose-built thermal chambers integrate with existing production lines for semiconductor equipment manufacturers in Dresden.
The dominant share belongs to Batch Cleaning, while Portable Systems is closing the gap fastest.
Application:
Emissions compliance thresholds and substrate sensitivity requirements fragment demand across end-use sectors.
- Industrial Equipment:Mold and die maintenance for polymer injection operations requires precise temperature ramping to preserve surface integrity. REACH chemical restrictions are eliminating solvent alternatives across EU manufacturing corridors.
- Automotive Parts:Engine block and transmission component remanufacturing demands high-volume thermal decomposition with integrated emissions scrubbing.
- Aerospace Components:Turbine blade refurbishment at FAA-certified facilities in Ohio and Texas mandates pyrolysis systems with argon atmosphere capability.
- Oilfield Services:Downhole tool cleaning at shale extraction sites requires mobile thermal processing with explosion-proof electrical enclosures.
Industrial Equipment retains the largest installed base, though Oilfield Services is gaining share fastest.
Delivery Mode:
Capital constraints and maintenance expertise availability determine whether buyers own equipment or contract throughput.
- On-Site Services:Thermal cleaning providers deploy mobile units to buyer facilities, eliminating logistics costs for contaminated component transport. German Ruhr industrial region operators now guarantee uptime commitments under throughput-based contracts.
- Off-Site Services:Centralized thermal processing facilities in Houston and Rotterdam handle large-volume polymer removal for mid-sized manufacturers lacking capital for in-house installation.
- In-House Systems:Aerospace OEMs and automotive tier-1 suppliers maintain captive thermal cleaning to protect proprietary component geometries.
- Mobile Units:Trailer-mounted pyrolysis systems serve oilfield contractors requiring immediate drill bit refurbishment at remote wellheads.
In-House Systems command the highest revenue per installation, while On-Site Services is expanding most quickly.
End User:
Procurement authority and technical staffing capabilities diverge sharply across buyer categories.
- Manufacturers:Automotive and aerospace producers integrate thermal cleaning into remanufacturing workflows, with EPA MACT standards forcing upgrades to closed-loop architectures.
- Clinics:Medical device refurbishment facilities employ low-temperature pyrolysis for polymer removal from surgical instruments.
- Service Providers:Independent thermal cleaning contractors in Germany's industrial corridor are consolidating maintenance expertise under OEM service organizations.
- Government Agencies:Military depots and aerospace maintenance facilities specify thermal cleaning for turbine component lifecycle extension.
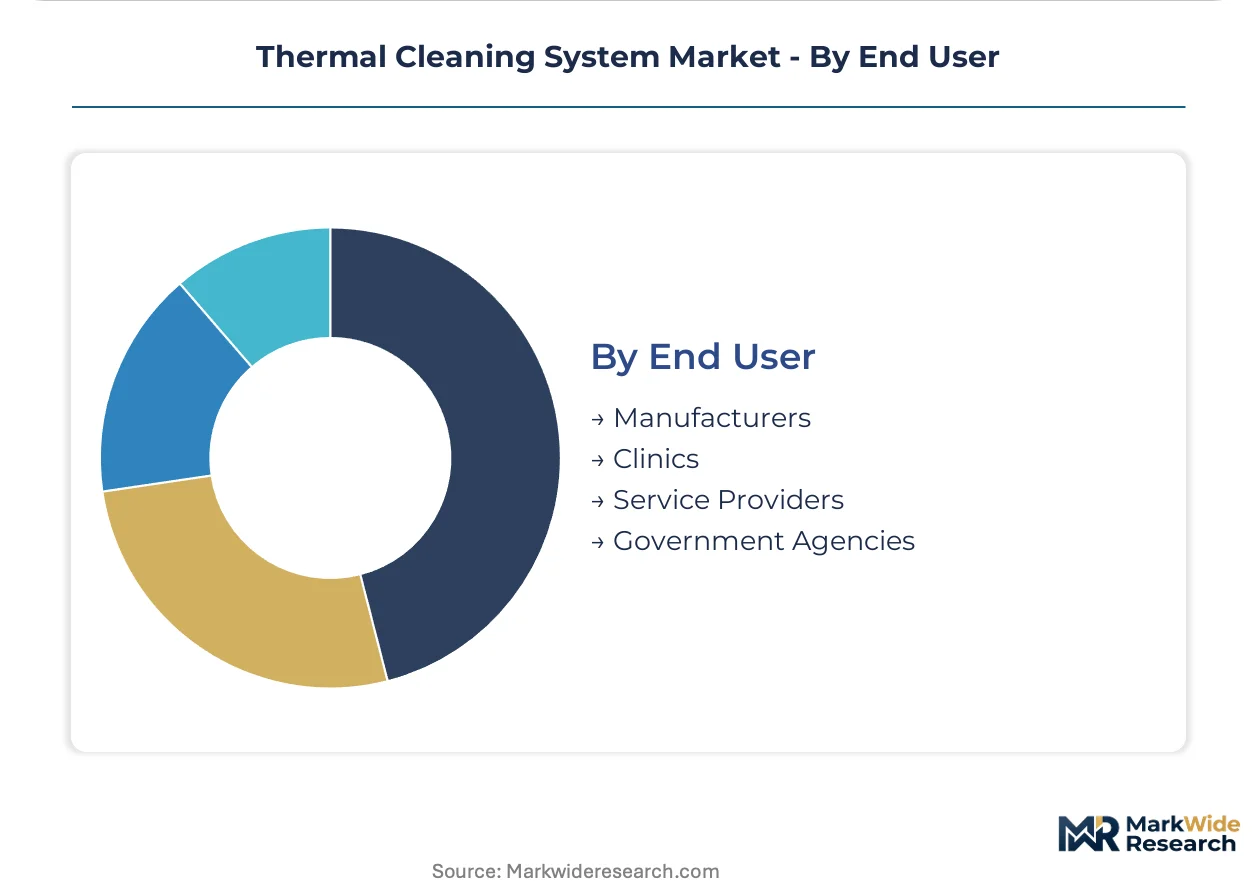
Manufacturers account for the dominant procurement volume, while Service Providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal subsidies for process heat electrification are redirecting capital toward electric-resistance thermal cleaning systems across industrial manufacturing corridors. EPA Maximum Achievable Control Technology standards are compressing replacement cycles for gas-fired thermal oxidizers in North American facilities. Precision engineering clusters in Germany and emerging tool-and-die corridors in India are driving divergent demand patterns for batch versus continuous configurations.
United States
Aerospace maintenance facilities in Ohio and Texas are expanding thermal cleaning adoption for turbine component refurbishment under FAA certification requirements. EPA's 2023 MACT updates for halogenated waste streams mandate secondary combustion chambers and continuous emissions monitoring. Shale extraction operators in West Texas and North Dakota are deploying portable pyrolysis units for on-site drill bit refurbishment.
Germany
REACH chemical restrictions on solvent-based cleaning agents are eliminating chemical alternatives for polymer removal in mold and die manufacturing. EU Green Deal industrial emissions incentives accelerate demand for electric-resistance thermal cleaning as replacement for gas-fired combustion chambers. Precision engineering clusters in Baden-Württemberg and Bavaria dominate high-fidelity batch configuration development for turbine blade refurbishment.
India
Pune and Chennai industrial corridors are establishing tool and die maintenance clusters with limited thermal cleaning penetration, creating first-mover positioning opportunities. The country's national environmental regulator is tightening industrial emissions thresholds for thermal processing equipment. Maharashtra and Tamil Nadu manufacturing hubs are absorbing pyrolysis system deployments for polymer injection mold maintenance.
China
Dual carbon goals and industrial decarbonization mandates are accelerating electric-resistance thermal cleaning adoption in automotive remanufacturing facilities. The Ministry of Ecology and Environment enforces emissions standards for industrial ovens that parallel EPA MACT architecture. Yangtze River Delta manufacturing clusters are integrating thermal cleaning with automated inspection robotics for engine block refurbishment.
Japan
METI industrial efficiency standards are compelling upgrades to closed-loop pyrolysis architectures in precision component manufacturing. JIS certification requirements for thermal processing equipment shape supplier qualification protocols for aerospace OEMs. Kansai and Chubu industrial regions concentrate demand for batch configurations serving semiconductor equipment manufacturers.
Thermal Cleaning System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented competitive tiers. German engineering houses dominate high-temperature pyrolysis system supply through captive fabrication capabilities. North American fabricators compete through vertical integration into combustion chamber production. Three archetypes define positioning: precision-batch specialists, continuous-system integrators, and mobile-service operators. Dominant competitive moves include backward integration into refractory lining supply and geographic expansion through distributor partnerships in emerging manufacturing corridors.
Among German-based precision engineering specialists, Schwing Technologies GmbH and Nabertherm GmbH exemplify the batch-configuration archetype serving aerospace and laboratory-scale applications. Baker Furnace Inc. represents North American continuous-system integration, occupying a position shaped by vertical control over combustion component fabrication. These three companies anchor distinct competitive vectors: German precision-batch leadership, North American throughput-focused integration, and emerging mobile-service mobilization for oilfield applications.
| Leading Market Players |
|---|
| Schwing Technologies GmbH |
| Baker Furnace Inc. |
| Nabertherm GmbH |
| Despatch Industries |
| Heraeus Holding GmbH |
| Deco Technology Group, Inc. |
| Flame Treating Systems, Inc. |
| Nippon Gases |
| KleenTec Inc. |
| Others |
Value Network & Pricing Analysis
Alumina-silica ceramic lining cost volatility tied to bauxite supply concentration in Guinea and Australia compresses margins for system fabricators while simultaneously widening pricing spreads between premium electric-resistance configurations and commodity gas-fired alternatives. This feedstock dependency forces buyers toward long-term refractory supply contracts that embed cost pass-through mechanisms, reshaping procurement from transactional spot purchasing to structured offtake arrangements.
Pricing Analysis
Certification level creates the primary spread across thermal cleaning system tiers, with EPA MACT-compliant configurations commanding substantial premiums over baseline equipment lacking integrated afterburner and continuous emissions monitoring architectures. Three-tier pricing structure separates aerospace-grade argon-atmosphere batch systems from standard industrial pyrolysis units and economy gas-fired alternatives without scrubber integration. Pricing pressure stems from electric-resistance heating element adoption in automotive remanufacturing, where silicon carbide substrate configurations eliminate NOx permitting costs but accelerate replacement timelines for legacy combustion chambers. Mid-sized mold and die manufacturers exhibit highest price sensitivity, while aerospace OEMs and oilfield contractors prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Bauxite feedstock for alumina-silica refractory linings draws from concentrated extraction in Guinea and Australia, with secondary processing capacity clustering in China and Germany. Silicon carbide heating elements rest on petroleum coke supply chains anchored in the United States and China, while precision control system components source from Japanese and German automation specialists. Single-source vulnerability concentrates in high-temperature ceramic insulation, where limited qualified suppliers extend lead times during commodity price spikes. Distribution runs through OEM-direct channels for large aerospace and automotive accounts, with regional distributor networks serving mid-volume manufacturers in industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive tier-1 suppliers and aerospace OEMs pursuing captive remanufacturing capabilities, fragmenting purchasing authority between operations and procurement functions while elevating throughput-based service contracting as a viable alternative to capital ownership.
For Market Incumbents: Pre-empt portable system mobilization by oilfield service contractors through backward integration into trailer-mounted platform fabrication, neutralizing the threat from emerging mobile-service operators in West Texas and North Dakota. Deepen certification investment in EPA MACT secondary combustion architectures before regulatory tightening accelerates replacement cycles, locking in upgrade revenue streams from existing installed base. For New Entrants and Emerging Players: Tool and die maintenance clusters in Pune and Chennai represent the most penetrable entry point, where limited thermal cleaning penetration coincides with REACH-equivalent emissions tightening by India's national environmental regulator. Portable pyrolysis deployment for shale extraction operators offers immediate revenue without manufacturing scale requirements, leveraging distributor partnerships with oilfield equipment lessors for channel access. For Investors and Strategic Acquirers: EPA's 2023 MACT updates for halogenated waste streams reshape the acquisition landscape toward system integrators with sensor fusion capabilities rather than standalone equipment fabricators. Long-term viability centers on electric-resistance technology transitions and service-contracting revenue models, with acquisition targets favoring precision-batch specialists in German engineering clusters or continuous-system integrators with automotive remanufacturing relationships. Monitor state-level emissions threshold announcements as early signals of regulatory acceleration compressing replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Supply | Captive alumina-silica lining production insulates margins from Guinea-Australia bauxite price volatility. |
| Electric-Resistance Technology Transition | Silicon carbide substrate adoption eliminates NOx permitting complexity for Michigan automotive remanufacturers. |
| Throughput-Based Service Contracting | German Ruhr operators now guarantee uptime commitments, concentrating maintenance expertise with OEM service organizations. |
| Sensor Fusion Capability Development | Infrared thermography integration with real-time gas analysis shifts competitive advantage toward system integrators. |
| Geographic Expansion via Distributor Partnerships | Pune and Chennai industrial corridors offer first-mover positioning for pyrolysis system deployment. |
Research Methodology
Initial hypotheses were tested against primary input from thermal cleaning system OEM technical directors, automotive remanufacturing plant engineers, aerospace maintenance facility procurement managers, and oilfield service contractor operations heads, then refined through secondary validation against EPA enforcement databases, ECHA REACH restriction updates, SEC 10-K filings from publicly traded industrial equipment manufacturers, and customs trade data for alumina-silica refractory imports. Bottom-up equipment deployment counts triangulated against top-down industrial emissions compliance expenditure estimates.
Demand-supply balance dynamics across the analysis window were modeled through segmented bottom-up sizing of batch, continuous, portable, and custom system configurations by application vertical, with CAGRs derived from regression against industrial capital expenditure cycles and regulatory compliance deadline clustering. Forecast inputs incorporated electric-resistance heating adoption curves in automotive remanufacturing, REACH chemical restriction phase-out timelines, and shale extraction activity patterns in North Dakota and West Texas.
Practitioners should monitor EPA state-level emissions threshold announcements, ECHA solvent restriction expansion scope, and bauxite export policy shifts in Guinea for early signals requiring forecast revision. Cross-checking against industrial furnace capital expenditure surveys and aerospace OEM supplier qualification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Global Laser Material Market