
 Microbubble Cleaning Device Market | 2026-2036
Microbubble Cleaning Device Market Size, Share, and Industry Trends Forecast 2026-2036
Microbubble Cleaning Device Market Insights
China's Zhejiang and Jiangsu provinces is fragmenting as domestic manufacturers scale ultrafine bubble generator output for export markets. Moleaer Inc. anchors North American supply through its dissolved gas infusion platforms, while Shandong Sundon Technology Co., Ltd. dominates cost-optimized industrial unit production for Asian process industries. Fawoo Nanotech Co., Ltd differentiates through nanobubble patents in water treatment applications, and HACK UFB Co., Ltd specializes in compact systems for precision electronics cleaning.
Microbubble cleaning devices generate bubbles typically below 50 microns in diameter using hydrodynamic cavitation, gas dissolution, or ultrasonic excitation to achieve superior contaminant removal through elevated surface area-to-volume ratios and sustained buoyancy. The equipment serves precision manufacturing, medical sterilization, and environmental remediation by delivering chemical-free cleaning with reduced water consumption. Stationary systems occupy the dominant revenue position in semiconductor and automotive production lines where continuous throughput demands fixed infrastructure, while portable devices represent the fastest-expanding category as field-service teams adopt mobile units for industrial maintenance. Ultrasonic wave technology leads installed base owing to mature transducer supply chains, though electrolysis-based systems are gaining share where ozone generation adds antimicrobial value.
EPA effluent guidelines in the United States restrict chemical discharge from industrial cleaning operations, redirecting facilities toward bubble-based aqueous processes that eliminate solvent waste streams. Japan's METI energy efficiency standards for manufacturing equipment create compliance pathways for low-power microbubble systems, while South Korea's MFDS validates medical-grade cleaning protocols that specify bubble size distribution thresholds. Stakeholders must track how evolving cross-border equipment certification reciprocity affects market entry timing for regional specialists.
Market Dynamics
Semiconductor fabs in South Korea and Japan are consolidating wafer surface preparation workflows around fixed microbubble infrastructure, compressing equipment replacement cycles and elevating certification requirements for bubble size distribution precision.
Growth Catalysts
- EPA effluent guidelines:United States industrial facilities face discharge restrictions that redirect cleaning operations toward bubble-based aqueous processes eliminating solvent waste streams.
- Wafer surface preparation:Semiconductor fabs in South Korea are expanding procurement of microbubble systems as node geometries shrink and contamination thresholds tighten.
- Japan's PMDA protocols:Tightened medical device cleaning validation standards push hospitals toward certified equipment with documented bubble size thresholds.
Market Restraints
- Transducer supply concentration:Ultrasonic wave technology depends on mature but geographically concentrated transducer manufacturing, creating input bottlenecks.
- Electrolysis system costs:Ozone-generating platforms require precious metal electrodes and specialized power electronics, elevating capital intensity versus hydrodynamic alternatives.
- Validation timeline friction:Japan's PMDA and South Korea's MFDS impose extended certification cycles for medical-grade units, delaying revenue recognition.
Strategic Opportunities
- Portable device expansion:Field-service teams in automotive and electronics maintenance are adopting mobile microbubble units for on-site contamination removal.
- Environmental remediation:Hydrodynamic cavitation systems are penetrating soil and groundwater treatment applications where chemical injection faces regulatory prohibition.
- Japan's METI efficiency standards:Energy compliance pathways for low-power microbubble equipment create preferential positioning against legacy solvent-based systems.
Industry Challenges
- Bubble metrology expertise:Semiconductor fabs require technicians capable of calibrating sub-50-micron distribution measurements, a skill set concentrated among Japanese and South Korean equipment specialists.
- Legacy system integration:Automotive production lines must retrofit microbubble stations into existing aqueous cleaning infrastructure without disrupting continuous throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbubble Cleaning Device Market |
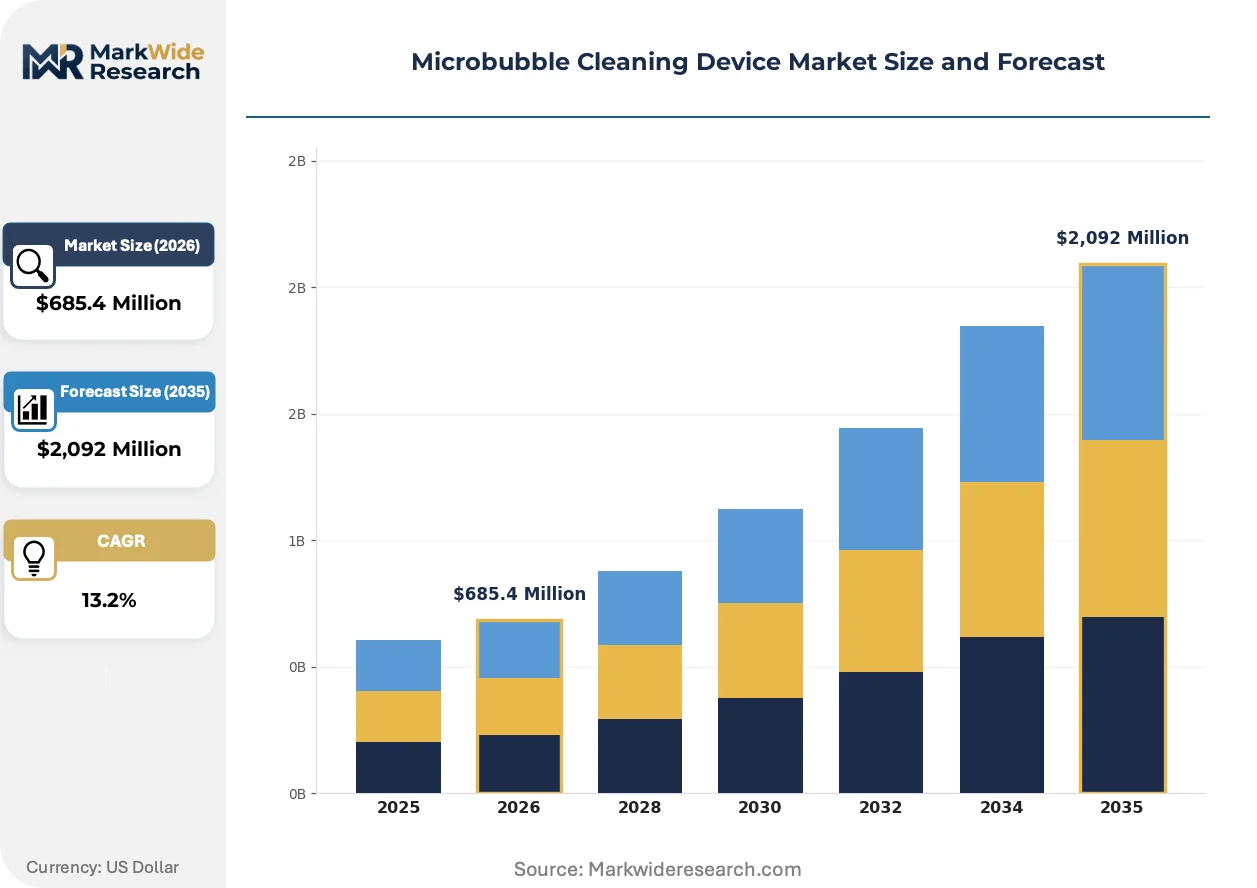
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,092 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
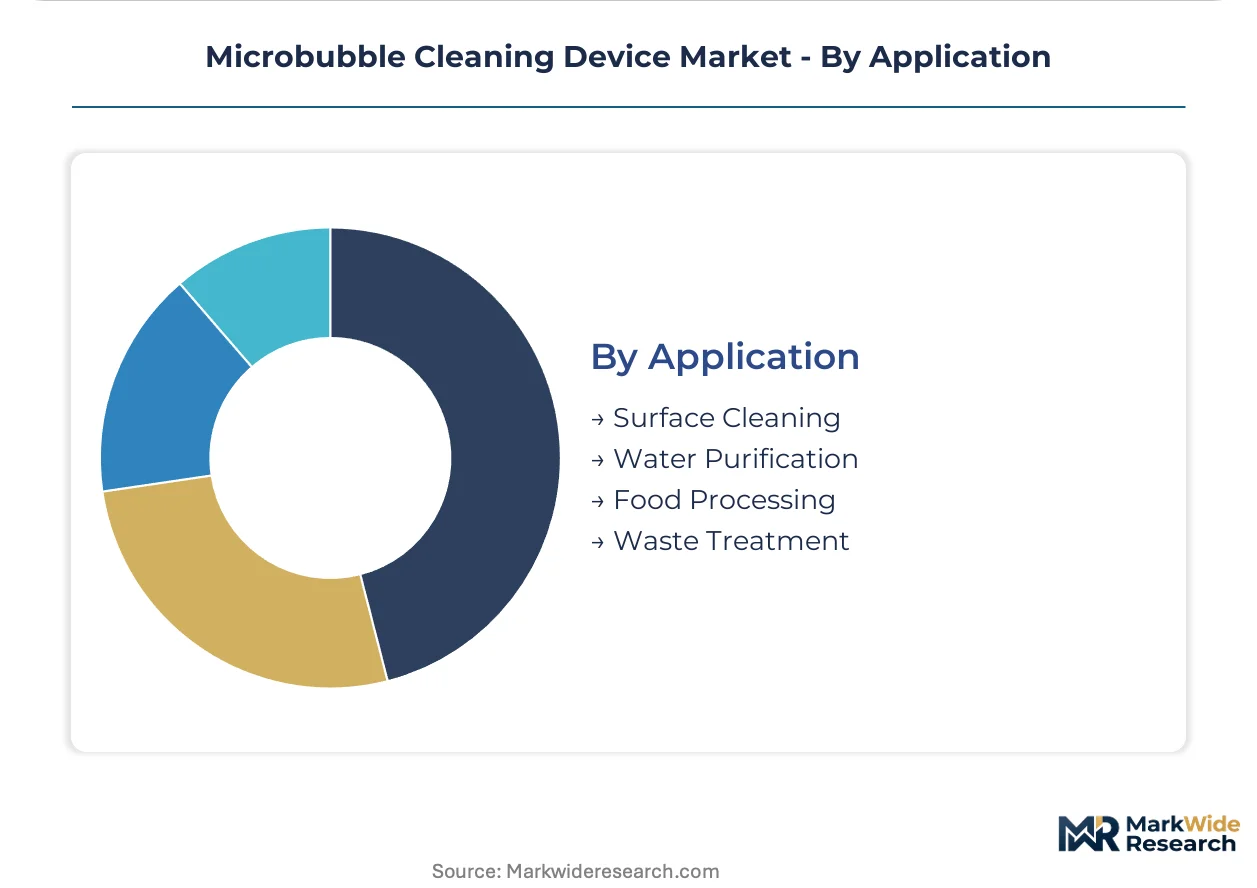
| Segmentation | Product Type: Portable Devices, Stationary Systems, Industrial Units, Home Applications Technology: Ultrasonic Waves, CFD, Laser-Assisted, Electrolysis End User: Manufacturing, Automotive, Healthcare, Residential Application: Surface Cleaning, Water Purification, Food Processing, Waste Treatment |
| Companies Covered | Moleaer Inc., Acniti LLC, Shandong Sundon Technology Co., Ltd., Pacific Water Technology, Fine Bubble Technologies, Shanghai Mutao Environmental Technology Co., Ltd., Fawoo Nanotech Co., Ltd, Anzai Kantetsu Co. Ltd, HACK UFB Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbubble Cleaning Device Market Trends and Innovations
Electrolysis-based generation is compressing the technology stack for antimicrobial applications, while regulatory pressure on chemical discharge accelerates aqueous process substitution across precision manufacturing corridors.
Electrolysis-based microbubble generation is virtualizing the ozone delivery layer for medical sterilization and food processing applications. Japanese hospitals and pharmaceutical cleanrooms are adopting these systems at accelerating pace to meet PMDA antimicrobial validation requirements. This convergence is virtualizing the traditional chemical sterilization supply chain, compressing logistics and inventory carrying costs for end-users.
Japan's METI energy efficiency standards for manufacturing equipment now include microbubble system power consumption thresholds. Industrial facilities must demonstrate compliance to access preferential electricity tariffs and carbon accounting credits. Semiconductor fabs in Osaka and Nagoya industrial zones are retrofitting ultrasonic platforms to meet these specifications ahead of enforcement deadlines.
Service unbundling is fragmenting the traditional equipment-plus-maintenance contract model. South Korean semiconductor fabs now procure microbubble generators separately from bubble metrology and calibration services, pressuring OEM margins. This decoupling is most visible in the Seoul metropolitan manufacturing corridor, where third-party metrology specialists are capturing recurring revenue streams previously retained by equipment vendors.
Microbubble Cleaning Device Market Segmentation

Microbubble cleaning equipment segments diverge sharply in service intensity, with semiconductor fabs demanding continuous calibration support while residential users require minimal intervention. Understanding these tiered after-market profiles shapes vendor profitability and channel strategy across the value chain.
Product Type:
After-sales service intensity varies dramatically across product tiers, with industrial installations demanding dedicated field engineering teams while portable units operate on break-fix remote support models.
- Stationary Systems:Fixed infrastructure dominates revenue in semiconductor and automotive production lines where continuous throughput demands dedicated bubble metrology stations. South Korean fabs in the Seoul metropolitan corridor compress replacement cycles as node geometries shrink below 7nm, elevating certification requirements for bubble size distribution precision.
- Portable Devices:Mobile units are expanding most quickly as field-service teams adopt lightweight systems for on-site contamination removal in electronics maintenance and automotive repair. Japanese automotive suppliers around Nagoya industrial zones deploy these for just-in-time cleaning without disrupting production line flow.
- Industrial Units:Heavy-duty platforms integrate hydrodynamic cavitation generators for chemical-free processing in environmental remediation and large-scale manufacturing.
- Home Applications:Compact consumer devices target residential water purification and personal care segments with simplified operation protocols.
By volume, stationary systems lead. By growth pace, portable devices are ahead.
Technology:
Technology selection drives capital intensity and operating cost structures, with mature transducer supply chains competing against emerging electrolysis platforms requiring precious metal inputs.
- Ultrasonic Waves:Mature transducer technology anchors the installed base through proven reliability in precision electronics cleaning. Osaka semiconductor fabs retrofit these platforms to meet Japan's METI energy efficiency standards ahead of enforcement deadlines.
- Electrolysis:Ozone-generating systems are gaining share in medical sterilization and food processing where antimicrobial validation is mandatory. Japanese hospitals adopt these to satisfy PMDA cleaning protocol requirements, compressing traditional chemical sterilization supply chains.
- CFD:Computational fluid dynamics optimization enables precise bubble size control for specialized semiconductor wafer preparation applications.
- Laser-Assisted:Emerging optical cavitation methods target ultra-precise contamination removal in advanced manufacturing environments.
Ultrasonic wave technology holds the largest installed base. Electrolysis platforms climb the fastest on antimicrobial demand.
End User:
End-user concentration determines pricing power and contract structure, with consolidated manufacturing buyers extracting service unbundling concessions while fragmented residential segments accept bundled offerings.
- Manufacturing:Precision production facilities in East Asian industrial corridors drive specification-setting for bubble size distribution thresholds. South Korean semiconductor fabs now procure generators separately from metrology services, fragmenting traditional equipment-plus-maintenance contracts.
- Healthcare:Japanese hospitals and pharmaceutical cleanrooms face tightened PMDA validation protocols pushing toward certified equipment with documented performance thresholds.
- Automotive:Production lines require retrofit compatibility with existing aqueous cleaning infrastructure without throughput disruption.
- Residential:Consumer segments prioritize simplicity and capital efficiency over performance optimization.
Manufacturing commands the dominant revenue share. Healthcare shows the steepest specification escalation.
Application:
Application focus shapes regulatory exposure and chemical substitution potential, with effluent-restricted processes redirecting toward bubble-based aqueous alternatives.
- Surface Cleaning:Wafer preparation and precision electronics dominate technical requirements, with sub-50-micron bubble distributions mandatory for contamination control. EPA effluent guidelines in the United States redirect facilities from solvent-based processes toward aqueous bubble systems.
- Water Purification:Municipal and industrial treatment plants adopt nanobubble systems for chemical-free oxidation, with Fawoo Nanotech patent portfolios concentrated in this segment.
- Food Processing:Antimicrobial cleaning without chemical residues addresses regulatory and consumer preference shifts in Japan and South Korea.
- Waste Treatment:Hydrodynamic cavitation penetrates soil and groundwater remediation where chemical injection faces prohibition.
Surface cleaning generates the highest equipment value per unit. Waste treatment is expanding most quickly on regulatory prohibition of chemical alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in East Asian industrial corridors, with South Korean and Japanese fabs driving specification-setting for sub-50-micron bubble distribution precision. Chinese provinces scale cost-optimized output for export markets while North American demand anchors on dissolved gas infusion platforms.
South Korea
Semiconductor fabs in the Seoul metropolitan corridor compress replacement cycles as node geometries shrink below 7nm. The MFDS validates medical-grade cleaning protocols that specify bubble size distribution thresholds, extending certification timelines. Busan-Ulsan industrial zones host precision electronics manufacturers expanding microbubble procurement for wafer surface preparation.
Japan
Osaka and Nagoya industrial zones retrofit ultrasonic platforms to meet METI energy efficiency standards ahead of enforcement deadlines. The PMDA tightened medical device cleaning validation protocols, pushing hospitals toward certified equipment with documented performance thresholds. Pharmaceutical cleanrooms in Kansai accelerate adoption of electrolysis-based systems for antimicrobial sterilization.
China
Zhejiang and Jiangsu provinces fragment as domestic manufacturers scale ultrafine bubble generator output for export markets. The MEE effluent guidelines restrict chemical discharge from industrial cleaning operations, redirecting facilities toward bubble-based aqueous processes. Shandong Peninsula production clusters dominate cost-optimized industrial unit fabrication for Asian process industries.
United States
Industrial facilities face EPA effluent guidelines that restrict chemical discharge from cleaning operations, redirecting toward aqueous bubble systems. The FDA maintains medical device cleaning validation requirements that overlap with emerging bubble-based sterilization protocols. Midwest automotive production lines and Southwest semiconductor fabs drive stationary system demand for continuous throughput applications.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg retrofit microbubble stations into existing aqueous cleaning infrastructure without disrupting production flow. The ECHA REACH framework restricts solvent use in industrial processes, creating compliance pathways for chemical-free cleaning alternatives. North Rhine-Westphalia chemical and pharmaceutical clusters evaluate nanobubble systems for environmental remediation applications.
Microbubble Cleaning Device Market Competitive Landscape
Specialized technology developers and diversified industrial equipment fabricators split the market along performance-versus-cost vectors. The vendor base organizes into three strategic archetypes: patent-holding nanobubble specialists, dissolved gas platform providers, and cost-optimized industrial unit manufacturers. Competitive positioning hinges on technology licensing agreements and geographic expansion into East Asian manufacturing corridors.
Within the nanobubble specialist tier, Fawoo Nanotech Co., Ltd and HACK UFB Co., Ltd exemplify concentrated expertise in sub-micron bubble generation for precision applications. Shandong Sundon Technology Co., Ltd anchors the cost-optimized fabrication segment, representing scale-driven production capabilities for process industries. Moleaer Inc. occupies a position bridging North American demand with dissolved gas infusion platform supply.
| Leading Market Players |
|---|
| Moleaer Inc. |
| Acniti LLC |
| Shandong Sundon Technology Co., Ltd. |
| Pacific Water Technology |
| Fine Bubble Technologies |
| Shanghai Mutao Environmental Technology Co., Ltd. |
| Fawoo Nanotech Co., Ltd |
| Anzai Kantetsu Co. Ltd |
| HACK UFB Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Shandong Peninsula production clusters anchor cost-optimized industrial unit fabrication, compressing margins for mid-tier equipment vendors while concentrating pricing power among nanobubble patent holders serving semiconductor fabs. This geographic asymmetry between mass-market supply and precision demand shapes tiered contract structures across the value chain.
Pricing Analysis
Japan's PMDA dictates the pricing tier structure through medical-grade certification requirements that separate validated equipment from uncertified alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy portable levels reflects bubble size distribution precision and after-sales service bundling. Cost compression in the standard industrial tier is intensifying because South Korean fabs now unbundle metrology services from equipment procurement. Residential buyers exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for sub-50-micron precision guarantees.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for transducer-dependent ultrasonic platforms. Component sourcing draws from Japanese piezoelectric ceramic suppliers, South Korean precision electronics fabricators, and Chinese steel and aluminum processors. Single-source vulnerability concentrates in mature transducer manufacturing where geographic consolidation creates input bottlenecks. Distribution runs through OEM direct sales for stationary systems and specialized industrial distributors for portable devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbubble cleaning equipment represents a high-growth disruption as EPA effluent guidelines and Japan's PMDA protocols simultaneously eliminate solvent alternatives and mandate certified aqueous systems.
For Market Incumbents: Insulate core semiconductor fab relationships through captive bubble metrology service capabilities that resist unbundling pressure from South Korean procurement teams. Deepen backward integration into transducer manufacturing to offset supply concentration risk in Japanese and South Korean component markets. For New Entrants and Emerging Players: Build out portable device distribution networks targeting Japanese automotive suppliers around Nagoya industrial zones where just-in-time cleaning demand outpaces incumbent service coverage. Prioritize electrolysis-based ozone generation platforms for hospital procurement channels facing PMDA antimicrobial validation deadlines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because effluent restrictions and medical device validation protocols create durable demand anchors for certified equipment. Target nanobubble patent portfolios and dissolved gas infusion platform developers as acquisition candidates. Watch EPA enforcement intensity and Japan's METI efficiency standard implementation as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Portfolio Acquisition | Secures sub-micron bubble generation IP that Fawoo Nanotech and HACK UFB currently monopolize in water treatment. |
| Electrolysis Platform Scale-Up | Addresses PMDA antimicrobial validation requirements that Japanese hospitals now mandate for sterilization equipment. |
| Transducer Supply Agreement | Mitigates geographic concentration risk in Japanese and South Korean piezoelectric ceramic manufacturing. |
| Portable Device Channel Partnership | Captures field-service demand from Nagoya automotive suppliers adopting mobile cleaning units. |
| Metrology Service Unbundling | Aligns with Seoul semiconductor fab procurement patterns that separate generator purchases from calibration contracts. |
Research Methodology
Operator-level perspectives from semiconductor fab process engineers, hospital biomedical equipment managers, automotive supplier maintenance directors, and industrial water treatment plant operators anchored the qualitative base. Primary interviews combined with secondary validation from EPA effluent guideline filings, Japan's PMDA medical device registration databases, South Korean MFDS certification records, and METI energy efficiency standard disclosures. Bottom-up equipment unit economics and top-down sector expenditure patterns were triangulated to constrain forecast variance.
Scenario-bracketing around regulatory enforcement intensity and semiconductor node geometry transition pace framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, generation technology, end-user industry, and application with regional regulatory cluster overlays. CAGRs were derived from installed base replacement cycle compression and new adoption curve penetration. Forecast inputs incorporated bubble metrology technician availability constraints and precious metal electrode cost trajectories for electrolysis platforms.
Stress conditions across EPA enforcement delays, Japan's PMDA certification timeline extensions, and transducer supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Soldering Iron Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Digital Tachometer Market