
 Vertical Centrifugal Separator Market | 2026-2036
Vertical Centrifugal Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Centrifugal Separator Market Insights
API-grade specification upgrades for refinery and chemical plant applications is unwinding legacy equipment replacement cycles across the vertical centrifugal separator market. GEA Group leverages its disk stack technology leadership to sustain premium positioning in petrochemical processing installations worldwide. Alfa Laval anchors its competitive stance through extensive service networks and aftermarket parts dominance across European and North American refinery corridors.
A vertical centrifugal separator is a rotating machinery device that uses centrifugal force to separate immiscible liquids or solids from liquids based on density differentials, typically operating at bowl speeds exceeding 3,000 rpm and generating gravitational forces above 5,000 g. Its primary industrial purpose is continuous-phase separation in process industries where purity specifications and throughput reliability determine operational economics. Self-cleaning separators command the widest installed base due to reduced downtime in 24/7 refinery and chemical plant operations, while disk stack technology captures the fastest growth trajectory as facilities prioritize compact footprint and high g-force separation efficiency. Manual cleaning separators retain relevance in smaller food processing and metal recovery installations where batch flexibility outweighs automation premiums.
EPA effluent limitations under the Clean Water Act and OSHA process safety management requirements shape equipment specifications for U.S. refinery and chemical plant installations, while REACH and ATEX directives in Europe mandate material traceability and explosion-proof designs for separators handling volatile hydrocarbons. These regulatory frameworks elevate capital costs for non-compliant suppliers while creating durable preference for certified manufacturers with established testing protocols. Stakeholders must monitor evolving PFAS treatment mandates and emerging state-level water reuse regulations, as these will redirect procurement criteria toward separators capable of handling sub-micron particulate loads in advanced wastewater applications.
Market Dynamics
API-grade specification upgrades are compressing replacement cycles across refinery and chemical plant installations, forcing facilities to retire legacy separators ahead of scheduled maintenance intervals. Equipment procurement teams now prioritize certified compliance over extended asset life.
Growth Catalysts
- EPA effluent limitations:U.S. refinery operators must upgrade separation equipment to meet Clean Water Act discharge standards, triggering systematic replacement of non-compliant legacy units.
- Disk stack technology:Petrochemical processors in Germany's industrial clusters are adopting compact high-g-force separators to maximize throughput per square meter of plant footprint.
- Wastewater treatment expansion:Municipal facilities in the United States are procuring self-cleaning vertical centrifugal separators to handle rising influent volumes from industrial pretreatment programs.
Market Restraints
- Stainless steel price volatility:Separator bowl and disk stack fabrication costs fluctuate with nickel alloy spot markets, compressing margins for fixed-price contract manufacturers.
- Explosion-proof certification backlog:ATEX directive testing queue times at notified bodies extend equipment delivery schedules by four to eight months for hydrocarbon-handling applications.
- Membrane filtration substitution:Crossflow microfiltration systems capture sub-micron separation tasks in pharmaceutical biotechnology, displacing centrifugal methods in sterile process lines.
Strategic Opportunities
- PFAS remediation mandates:Emerging state-level regulations in the United States will require separators capable of concentrating per- and polyfluoroalkyl substances from industrial wastewater streams.
- Modular skid packaging:Pre-assembled separator systems with integrated controls reduce field installation labor, opening sales channels through engineering procurement contractors.
- Metal recovery from sludge:Precious metals refiners in Germany are retrofitting batch separators to extract palladium and platinum from electrowinning residues.
Industry Challenges
- Rotordynamics specialist scarcity:Separator manufacturers compete for finite talent pools capable of high-speed bearing design and vibration analysis above 6,000 rpm.
- Legacy control system integration:Modern separators with digital condition monitoring must interface with decades-old distributed control systems through protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Centrifugal Separator Market |
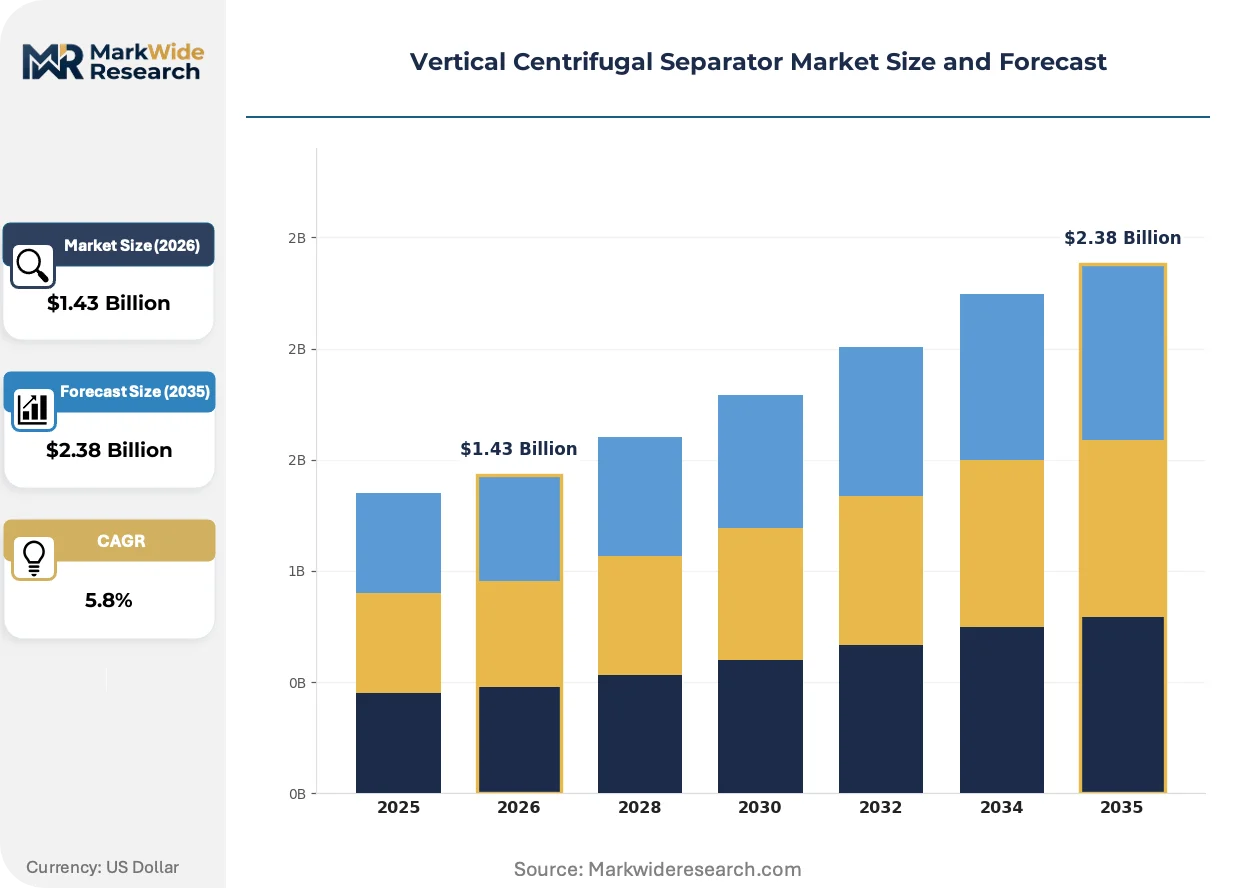
| Market Size in 2026 | $1.43 Billion |
| Market Size in 2035 | $2.38 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage Separator, Multi-Stage Separator, Self-Cleaning Separator, Manual Cleaning Separator Technology: Hydrocyclone, Rotary Bowl, Scroll, Disk Stack, Tube, Plate Application: Petrochemical Processing, Food Processing, Wastewater Treatment, Chemical Manufacturing, Metal Recovery End User: Refineries, Food & Beverage Plants, Water Treatment Facilities, Chemical Plants, Mining Operations |
| Companies Covered | GEA Group, Alfa Laval, Pieralisi, Flottweg, ANDRITZ, Tomoe Engineering, Plant SARRZ, Macfuge, SPX FLOW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Centrifugal Separator Market Trends and Innovations
Equipment architecture is converging around intelligent condition monitoring and footprint reduction, while regulatory compliance automation reshapes how separators are specified and procured across process industries.
Disk stack centrifuge design is miniaturizing through advanced computational fluid dynamics optimization that maintains separation efficiency in bowl diameters below 300 millimeters. Pharmaceutical biotechnology facilities are adopting these compact units for pilot-scale continuous processing. The technology is miniaturizing cleanroom installation requirements and reducing capital expenditure thresholds for multi-product facilities.
REACH substance restriction amendments are compelling separator manufacturers to eliminate hexavalent chromium surface treatments from bowl components and substitute trivalent alternatives. Chemical plant operators in Europe must now document material composition traceability through the supply chain. Disk stack separators with full material certification command procurement preference in German and Dutch refinery corridors.
Aftermarket service unbundling is fragmenting traditional full-service contracts into discrete offerings for spare parts, remote diagnostics, and field maintenance. Refinery procurement teams in the United States are negotiating these elements separately to optimize total cost of ownership. This purchasing pattern is most pronounced among integrated petrochemical operators with centralized engineering standards.
Vertical Centrifugal Separator Market Segmentation
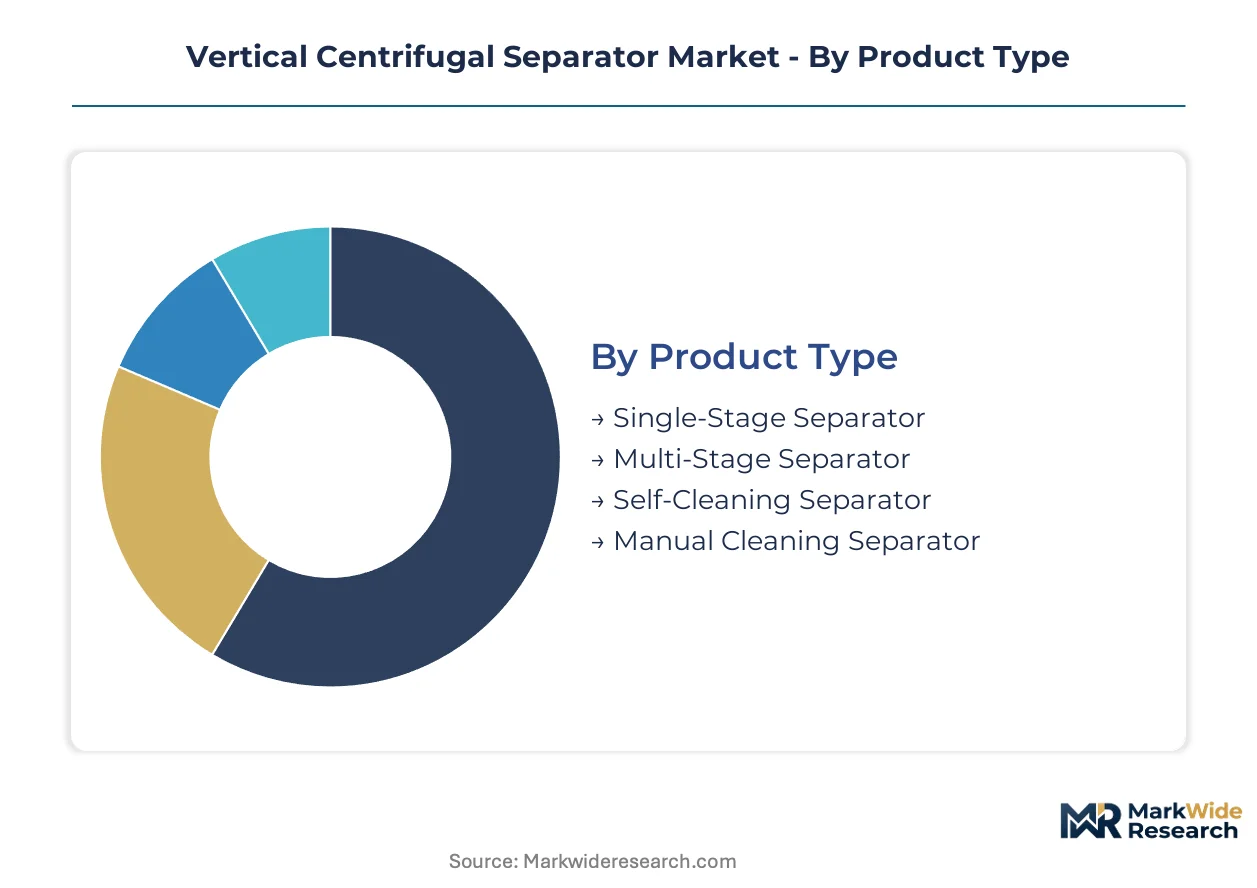
Vertical centrifugal separator procurement varies sharply across product architectures, separation mechanisms, and end-use environments. Regulatory mandates on discharge quality and process safety create divergent specification requirements that reshape segment prioritization.
Product Type:
EPA effluent limitations and ATEX explosion-proof directives drive specification divergence between automated and manually serviced configurations.
- Self-Cleaning Separator:Continuous discharge systems eliminate downtime through automated solids ejection at full operating speed. Refinery operators in the United States specify these units to maintain Clean Water Act compliance during 24/7 operations without batch interruption.
- Multi-Stage Separator:Cascaded bowl arrangements achieve progressive density separation in a single housing. Chemical manufacturing clusters in Germany deploy these for complex hydrocarbon purification where single-pass efficiency determines throughput economics.
- Single-Stage Separator:Simplified bowl geometry suits straightforward liquid-liquid separation with lower capital thresholds.
- Manual Cleaning Separator:Batch-operated units with tool-disassembly cleaning retain relevance in smaller food processing installations where operational flexibility outweighs labor costs.
Established volume favors Self-Cleaning Separator; emerging adoption favors Multi-Stage Separator.
Technology:
Capital intensity and footprint constraints concentrate procurement toward compact high-g-force architectures in premium process applications.
- Disk Stack:Conical plate arrays multiply settling area within minimal bowl diameter, generating gravitational forces above 5,000 g. Petrochemical processors prioritize these for space-constrained retrofits where throughput per square meter determines project feasibility.
- Rotary Bowl:Solid-wall cylindrical designs handle abrasive slurries and high-solids feeds without component wear. Mining operations in metal recovery applications specify hardened alloy bowls for electrowinning residue processing.
- Hydrocyclone:Pressure-driven vortex separation operates without rotating machinery, reducing maintenance in coarse particle applications.
- Scroll:Conveyor-discharge mechanisms continuously remove settled solids in decanter-style configurations.
- Tube:Vertical tubular elements provide gentle separation for shear-sensitive biological materials.
- Plate:Parallel plate settlers offer gravity-assisted pre-separation upstream of centrifugal polishing.
Disk Stack commands premium positioning; Rotary Bowl captures replacement demand in abrasive service.
Application:
Discharge standard stringency and feed composition variability determine technology selection across industrial verticals.
- Wastewater Treatment:Municipal and industrial facilities require robust solids-liquid separation for pretreatment and sludge dewatering. Self-cleaning units with corrosion-resistant bowls address rising influent volumes from industrial discharge programs in the United States.
- Petrochemical Processing:Hydrocarbon separation demands ATEX-certified explosion-proof construction and material traceability under REACH. German refinery corridors specify full certification documentation for bowl components in volatile service.
- Food Processing:Hygienic design standards govern separator specification for edible oil and dairy applications.
- Chemical Manufacturing:Aggressive solvents and temperature extremes require specialized alloy selections.
- Metal Recovery:Precious metals refiners retrofit batch separators for palladium and platinum extraction from process residues.
Wastewater Treatment drives volume expansion; Petrochemical Processing sustains premium pricing.
End User:
Operational scale and technical staffing levels create divergent procurement patterns between centralized engineering standards and decentralized maintenance capabilities.
- Refineries:Integrated petrochemical operators with centralized engineering standards negotiate unbundled service contracts for spare parts, remote diagnostics, and field maintenance separately. API-grade specification upgrades compress replacement cycles ahead of scheduled intervals.
- Water Treatment Facilities:Municipal procurement teams prioritize total cost of ownership and standardized maintenance protocols. Self-cleaning separators reduce labor requirements in facilities with limited specialized technical staff.
- Chemical Plants:Process-specific material compatibility and explosion-proof certification dominate specification.
- Food & Beverage Plants:Hygienic design and clean-in-place capability determine vendor selection.
- Mining Operations:Abrasive service conditions and remote location logistics influence durability requirements.
Refineries anchor aftermarket revenue; Water Treatment Facilities represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy equipment fabricators in Germany and the United States supply vertical centrifugal separators to refinery and wastewater markets worldwide, while import-dependent industrial clusters in China and India drive localized assembly partnerships. Trade flows concentrate disk stack technology from European specialists toward Asian petrochemical expansions.
United States
EPA effluent limitations under the Clean Water Act compel municipal wastewater facilities to upgrade separation equipment, triggering procurement of self-cleaning units. OSHA process safety management requirements shape refinery specifications for explosion-proof designs. Gulf Coast petrochemical corridors around Houston and Louisiana drive replacement cycles as API-grade standards compress asset lifespans.
Germany
REACH compliance mandates material traceability for bowl components handling volatile hydrocarbons, elevating preference for certified European manufacturers. ATEX directive testing requirements extend delivery schedules for explosion-proof configurations. Industrial clusters in North Rhine-Westphalia and Bavaria around Ludwigshafen and Munich prioritize compact disk stack separators for space-constrained chemical plant retrofits.
China
Dual carbon goals and tightening MEE discharge standards accelerate separator adoption in municipal wastewater treatment expansions. Domestic fabricators compete with European imports on price in standard industrial applications. Yangtze River Delta manufacturing hubs around Shanghai and Ningbo concentrate demand for high-throughput units in chemical processing installations.
India
CEA wastewater reuse regulations and state-level industrial effluent mandates expand addressable market for solids-liquid separation equipment. PLI scheme incentives support localized assembly partnerships with foreign technology licensors. Gujarat and Maharashtra industrial corridors around Vadodara and Mumbai drive procurement for refinery and petrochemical downstream applications.
Japan
METI energy efficiency guidelines favor compact high-g-force separators that reduce power consumption per unit throughput. JIS standards govern material specifications for food processing and pharmaceutical applications. Kansai region chemical manufacturers around Osaka prioritize disk stack technology for multi-product flexibility in specialty chemical production.
Vertical Centrifugal Separator Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and service bundling dimensions. The vendor base concentrates around three tiers: diversified process equipment conglomerates with full aftermarket ecosystems, mid-scale technology specialists focused on disk stack innovation, and regional fabricators serving price-sensitive batch applications. Strategic moves center on unbundled service contract negotiation and modular skid packaging to capture engineering procurement contractor channels.
Within the diversified conglomerate tier, GEA Group and Alfa Laval exemplify positioning built on extensive service networks and aftermarket parts dominance. Flottweg occupies a position among specialized German fabricators emphasizing technical depth in high-speed rotating machinery. These three anchors represent distinct competitive vectors: global service footprint, technology specialization, and regional engineering proximity.
| Leading Market Players |
|---|
| GEA Group |
| Alfa Laval |
| Pieralisi |
| Flottweg |
| ANDRITZ |
| Tomoe Engineering |
| Plant SARRZ |
| Macfuge |
| SPX FLOW |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month delivery backlogs for ATEX-certified explosion-proof configurations concentrate pricing power among German and U.S. fabricators with established testing protocols, while stainless steel inventory cycles amplify margin volatility for fixed-price contract manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across refinery and chemical plant procurement. Pricing stratifies across premium certified, standard compliant, and economy non-certified tiers, with REACH documentation and ATEX certification commanding substantial premiums. Cost compression in the economy tier is intensifying because domestic Chinese fabricators compete on price in standard industrial applications. Municipal water treatment facilities exhibit highest price sensitivity due to budget constraints, while integrated petrochemical operators with centralized engineering standards prioritize total cost of ownership over unit price.
Supply Chain Analysis
Inventory cycles for nickel alloy bowl components run 90-120 days, exposing fabricators to spot market volatility in stainless steel feedstock. Manufacturing concentrates in Germany, the United States, and China, with European specialists dominating disk stack technology for high-g-force applications. Bowl fabrication draws from specialty nickel alloys, precision bearings, and explosion-proof electrical components. Single-source vulnerability persists in high-speed bearing supply from Japanese and German specialists. Distribution runs through engineering procurement contractors for modular skid packages and direct OEM sales for large refinery installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated petrochemical operators with centralized procurement standards, as refinery sector consolidation concentrates specification-setting authority among fewer engineering teams.
For Market Incumbents: Fortify aftermarket service unbundling capabilities to capture remote diagnostics and spare parts revenue separately from equipment sales. Deepen backward integration into specialty alloy bowl fabrication to offset stainless steel price volatility. Prioritize certification investment in PFAS-capable separator designs ahead of emerging state-level mandates. For New Entrants and Emerging Players: Differentiate on modular skid packaging with integrated controls to bypass established direct sales channels through engineering procurement contractors. Target municipal wastewater treatment facilities in India and China where localized assembly partnerships satisfy PLI scheme and dual carbon procurement criteria. Pursue white-metal recovery retrofit opportunities in German precious metals refining clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified process equipment conglomerates seeking to divest non-core separation technology units. Mid-cap specialists with disk stack IP and established ATEX certification protocols offer durable 5-10 year positioning as regulatory stringency escalates. Monitor PFAS treatment mandate adoption velocity across U.S. state legislatures as inflection indicator for advanced separator demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel alloy sourcing insulates margins from spot market volatility affecting bowl fabrication costs. |
| Modular Skid Packaging Development | Pre-assembled systems reduce field installation labor and open EPC contractor distribution channels. |
| PFAS-Capable Separator Certification | Early positioning ahead of EPA and state-level mandates captures emerging wastewater treatment demand. |
| Remote Diagnostics Platform Launch | Digital condition monitoring enables unbundled service contracts with integrated petrochemical operators. |
| Localized Assembly Partnership | India PLI scheme and China domestic content rules favor joint ventures over direct import competition. |
Research Methodology
The analysis maps self-cleaning, multi-stage, single-stage, and manual cleaning separator architectures, each validated through maintenance directors at refineries, plant engineers at chemical manufacturing facilities, OEM procurement teams, and aftermarket service heads. Primary interview insights triangulate against customs and trade data, SEC filings from listed equipment manufacturers, ACC and Cefic industry reports, and refinery capex disclosure databases. Bottom-up unit economics and top-down sector sizing cross-validate volume and value outputs.
Consistency checks against external benchmarks validate projections across the analysis window. The modeling framework segments by product type, technology mechanism, application vertical, and end-user operational scale. CAGRs derive from equipment replacement cycle compression rates, regulatory mandate adoption curves, and capacity expansion announcements in petrochemical and wastewater sectors. Input assumptions incorporate stainless steel price trajectory scenarios and ATEX certification queue time estimates.
Forecasts assume regulatory continuity in EPA effluent limitation regimes and REACH substance restriction frameworks; material policy shifts would require re-modeling. Outputs reflect assumptions about disk stack technology adoption velocity and membrane filtration substitution thresholds in pharmaceutical biotechnology. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Case Handling Machines Market