
 Global Sodium Borohydride Market | 2026-2036
Global Sodium Borohydride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Borohydride Market Foresight
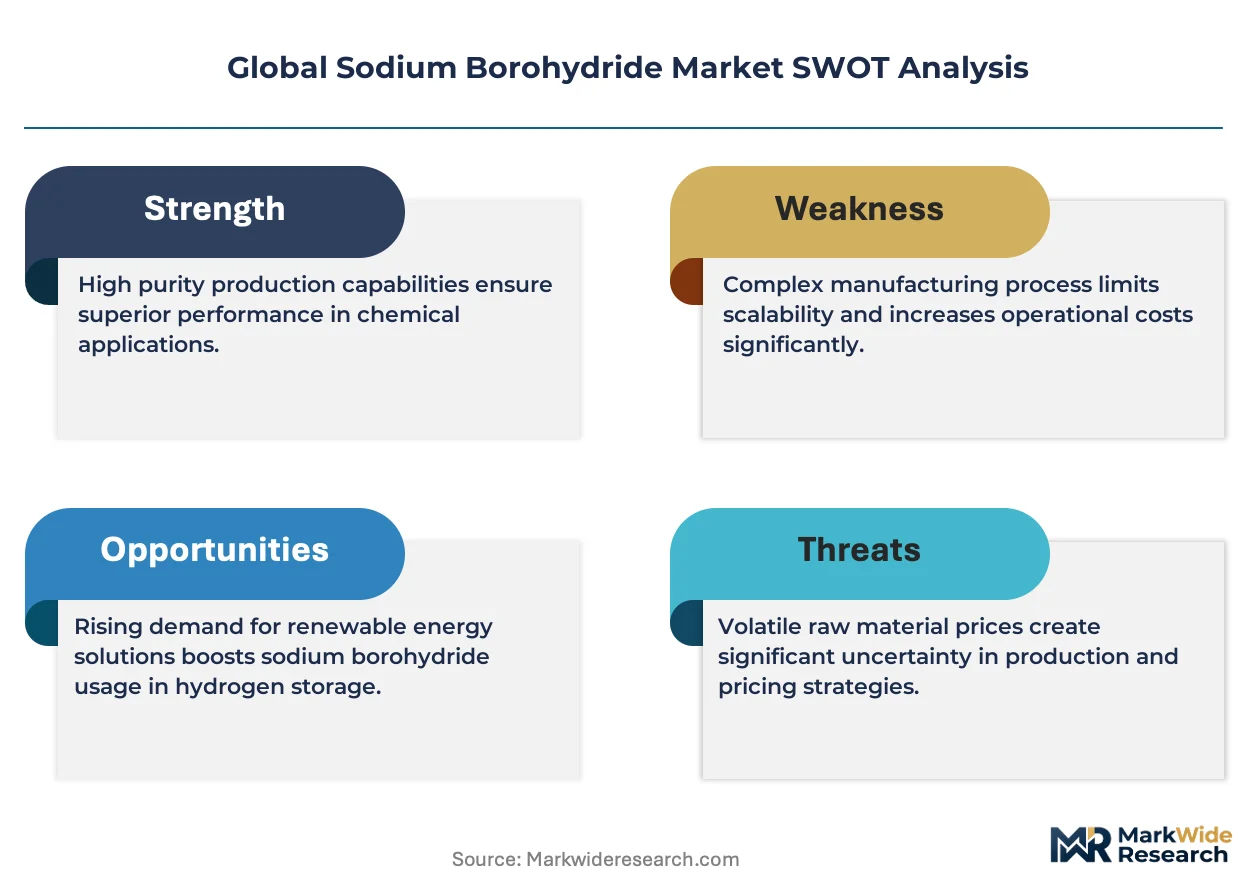
The capital-intensity divergence between integrated borohydride producers and merchant chemical specialists is reorganizing competitive tiers in sodium borohydride supply. Vertellus Specialties leverages captive boron raw material access and multi-step synthesis integration to sustain margin structures that commodity traders cannot match. Kemira anchors its position through pulp and paper channel control in Nordic markets, while Ascensus Specialties differentiates via pharmaceutical-grade certification and dedicated reductive chemistry portfolios.
Sodium borohydride (NaBH₄) is a white crystalline inorganic salt with a molecular weight of 37.83 g/mol, typically supplied as powder, granules, aqueous solution, or pellets depending on handling safety and reactivity requirements; it functions primarily as a selective reducing agent in organic synthesis and as a hydrogen source for wastewater deoxygenation. The powder and aqueous solution formats dominate current volume flows, with aqueous solution commanding premium pricing in pharmaceutical intermediates due to controlled-hazard shipping economics and downstream formulation convenience. Chemical synthesis and pharmaceutical intermediates represent the structurally expanding application clusters, while paper pulp bleaching maintains mature, price-sensitive offtake patterns tied to regional pulp mill operating rates.
EPA effluent guidelines under the Clean Water Act and REACH substance registration requirements in Europe constrain market entry through purity documentation and environmental release protocols, compelling producers to maintain dual-continent compliance infrastructures. China's NMPA pharmaceutical ingredient oversight and evolving GB standards for chemical handling further fragment regulatory qualification burdens across supply chains. Stakeholders must monitor hydrogen storage derivative applications and borohydride fuel cell research trajectories, as these adjacent technology domains could redirect merchant volumes away from traditional reducing-agent markets within the forecast window.
Market Dynamics
Pharmaceutical manufacturers are consolidating reductive chemistry procurement around certified sodium borohydride suppliers capable of documenting impurity profiles down to parts-per-billion thresholds, compressing merchant market access for uncertified traders.
Growth Catalysts
- EPA effluent guideline tightening:The Clean Water Act mandates are accelerating pulp mill adoption of borohydride-based deoxygenation chemistry over sulfur-based alternatives.
- Captive pharmaceutical integration:Drug manufacturers in China are building in-house borohydride derivative capacity to secure intermediate supply chains.
- Hydrogen storage R&D:Borohydride fuel cell research programs are creating pull-through demand for high-purity material in energy applications.
Market Restraints
- Boron trifluoride etherate cost volatility:Feedstock price swings from Turkish and US boron ore sources destabilize synthesis economics for non-integrated producers.
- REACH registration burdens:ECHA substance documentation requirements impose six-figure compliance costs that bar smaller traders from EU pharmaceutical supply chains.
- Lithium aluminum hydride substitution:Selective reduction applications in fine chemical synthesis face displacement where handling protocols favor non-aqueous reductants.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO bulk drug park incentives are attracting borohydride intermediate producers to establish localized derivative manufacturing.
- Aqueous solution formulation:Controlled-hazard shipping economics favor pre-diluted product formats for just-in-time pharmaceutical delivery models.
- Green chemistry mandates:EU Green Deal sustainable process requirements are elevating borohydride reduction pathways above metal-catalyzed hydrogenation in regulatory scoring.
Industry Challenges
- Pharmaceutical-grade certification timelines:NMPA and FDA dual-filing protocols extend qualification cycles to 18-24 months for new borohydride supply sources.
- Process safety engineering scarcity:Pyrophoric handling expertise for sodium borohydride manufacturing constrains capacity expansion at specialty chemical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Borohydride Market |
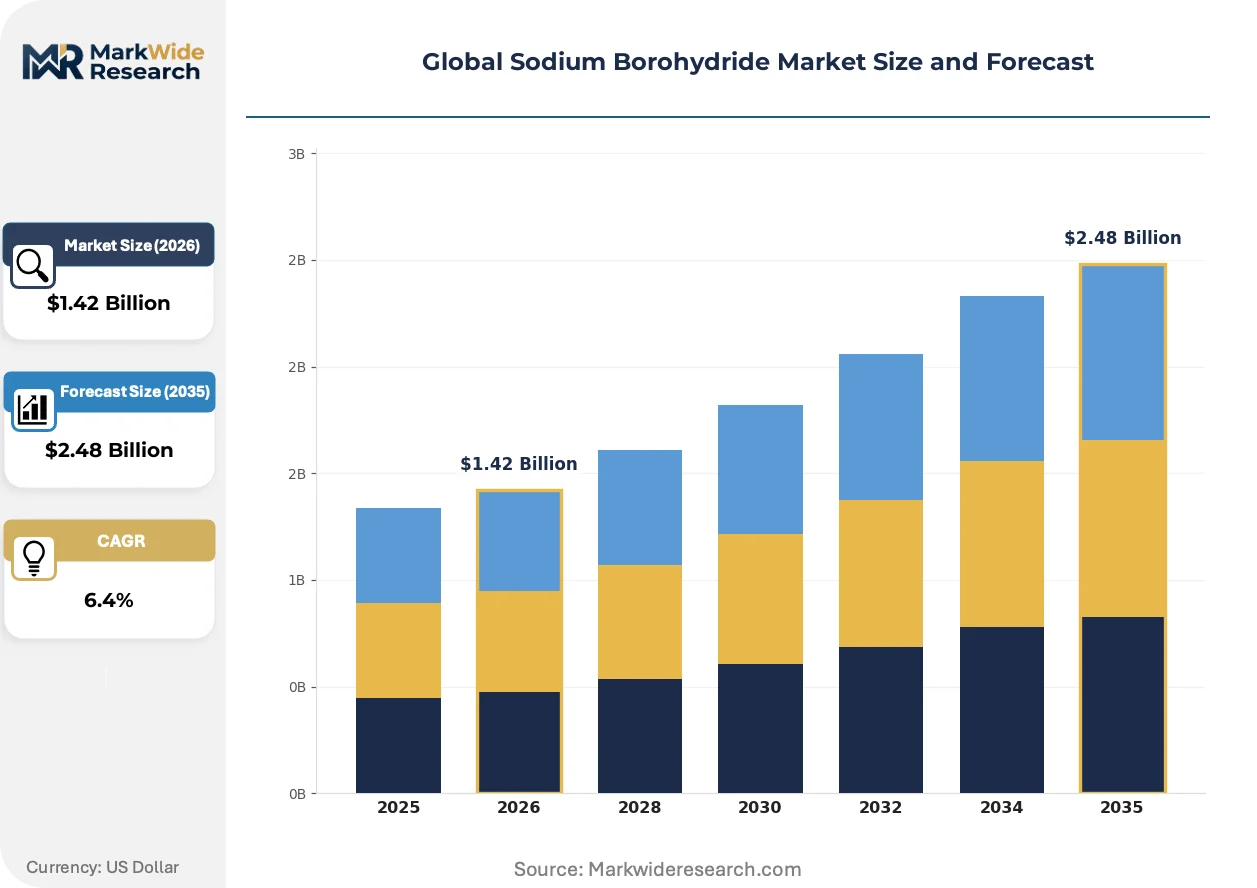
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Aqueous Solution, Pellets Application: Paper Pulp Bleaching, Water Treatment, Chemical Synthesis, Pharmaceutical Intermediates End Use Industry: Pulp & Paper, Water Purification, Chemical Manufacturing, Pharmaceutical Production Packaging Type: Drums, Bulk Bags, Bottles, Plastic Containers |
| Companies Covered | Vertellus Specialties, Kemira, Montgomery Chemicals, Shandong Guobang Pharmaceutical, Nantong Hongzhi Chemicals, Ascensus Specialties, JSC Aviabor, Guangxi Guilin Pharmaceutical, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Borohydride Market Shifts & Advancements
Continuous-flow reduction reactors and borohydride derivative stabilization chemistry are displacing batch manufacturing paradigms across pharmaceutical and fine chemical value chains.
Stabilized sodium borohydride pellets with moisture-resistant coatings are displacing conventional powder formats in automated pharmaceutical manufacturing lines. Contract development and manufacturing organizations are adopting pellet-fed continuous reactors to reduce operator exposure and improve yield consistency. This format shift is displacing traditional drum-handling logistics and manual weighing protocols across GMP synthesis suites.
REACH authorization list expansion is forcing reformulation of legacy borohydride-containing pharmaceutical intermediates to exclude candidate substance impurities. ECHA substance evaluation workflows now require full analytical characterization of boron-containing byproducts in downstream drug substances. European pharmaceutical manufacturers are responding by qualifying suppliers with dedicated borohydride purification trains capable of sub-ppm impurity control.
Just-in-time aqueous solution delivery contracts are compressing inventory holding patterns among pharmaceutical intermediate buyers. Large molecule drug manufacturers are unbundling reductant procurement from broader fine chemical supply agreements to secure dedicated borohydride logistics lanes. This purchasing model change is most visible in Massachusetts and New Jersey pharmaceutical corridors, where temperature-controlled tanker deliveries now replace drum stockpiling at synthesis facilities.
Global Sodium Borohydride Market Segmentation
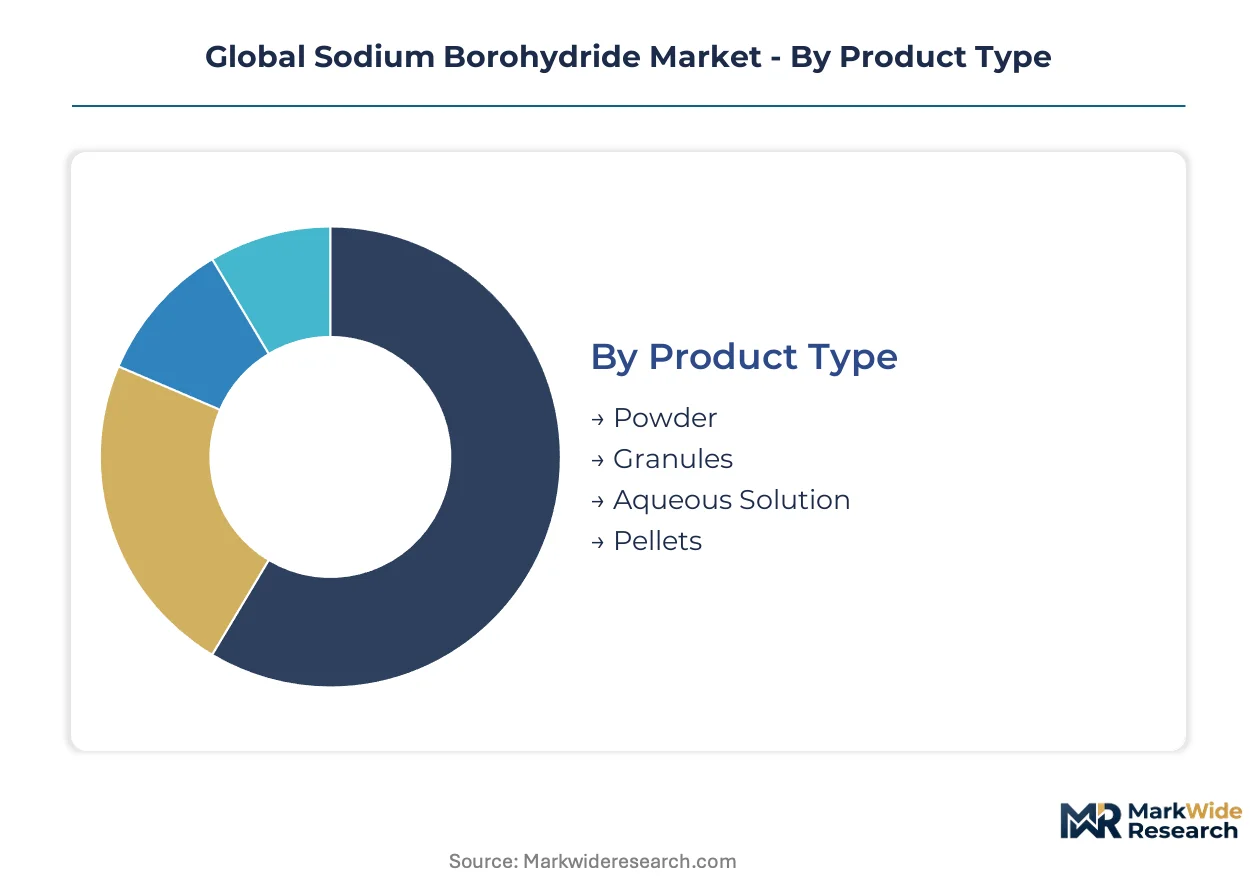
Sodium borohydride procurement channels diverge sharply across product formats and purity grades. Pharmaceutical buyers favor pre-qualified aqueous solutions delivered via temperature-controlled logistics, while pulp mills source bulk powder through commodity chemical distributors.
Product Type:
Powder and pellet formats flow through industrial chemical distributors serving pulp and paper mills, whereas aqueous solutions and high-purity granules move via pharmaceutical-grade logistics channels with full chain-of-custody documentation.
- Powder:White crystalline solid with 98% minimum assay, supplied in moisture-barrier packaging for industrial reducing applications. Demand concentrates in Nordic pulp mills replacing sulfur-based deoxygenation chemistries under tightened EPA effluent guidelines. Boron trifluoride etherate cost volatility compresses margins for non-integrated powder traders.
- Aqueous Solution:Pre-diluted alkaline formulations at 12% or 20% concentration, eliminating on-site dissolution hazards. Massachusetts and New Jersey pharmaceutical corridors drive just-in-time tanker deliveries replacing drum stockpiling. REACH-compliant suppliers command premium positioning through sub-ppm impurity documentation.
- Granules:Free-flowing crystalline form with controlled particle size distribution for automated feeding systems. Water purification facilities in Germany and France specify granules for continuous deoxygenation reactors.
- Pellets:Moisture-resistant coated cylinders displacing powder in GMP synthesis suites. CDSCO-registered Indian pharmaceutical parks are adopting pellet-fed continuous reactors to reduce operator exposure.
By volume, powder leads. By growth pace, aqueous solution is climbing the fastest.
Application:
Cost tier differentiation separates commodity deoxygenation applications from certified pharmaceutical reduction chemistry, with the latter commanding 3-4x unit economics.
- Pharmaceutical Intermediates:Selective reduction of carbonyl groups in active pharmaceutical ingredient synthesis, requiring NMPA and FDA dual-filing protocols. Chinese drug manufacturers are building captive borohydride derivative capacity to secure intermediate supply chains. ECHA substance evaluation workflows now mandate full analytical characterization of boron-containing byproducts.
- Chemical Synthesis:Fine chemical production of agrochemicals, flavors, and fragrances through controlled reduction pathways. EU Green Deal sustainable process requirements are elevating borohydride pathways above metal-catalyzed hydrogenation in regulatory scoring.
- Paper Pulp Bleaching:Deoxygenation of pulp mill effluent streams to prevent corrosion and improve brightness stability. Kemira anchors supply through channel control in Finnish and Swedish markets.
- Water Treatment:Municipal and industrial wastewater deoxygenation preventing dissolved oxygen damage to infrastructure. EPA Clean Water Act mandates are accelerating borohydride adoption over sulfur-based alternatives in US municipal systems.
Pharmaceutical intermediates generate highest margins. Paper pulp bleaching moves largest tonnage.
End Use Industry:
Customer type determines packaging, certification, and service intensity, with pharmaceutical producers requiring 18-24 month qualification cycles versus spot-market pulp mill purchasing.
- Pharmaceutical Production:GMP-certified synthesis of APIs and advanced intermediates with full impurity profiling to parts-per-billion thresholds. Process safety engineering scarcity for pyrophoric handling constrains qualified supplier expansion.
- Chemical Manufacturing:Agrochemical and fine chemical producers utilizing borohydride for selective reduction without noble metal catalysts.
- Pulp & Paper:Integrated mills and merchant pulp producers operating continuous deoxygenation systems tied to regional operating rates.
- Water Purification:Municipal utilities and industrial wastewater treatment facilities deploying borohydride for dissolved oxygen control.
Pharmaceutical production demands most intensive supplier qualification. Pulp & paper offers steadiest volume offtake.
Packaging Type:
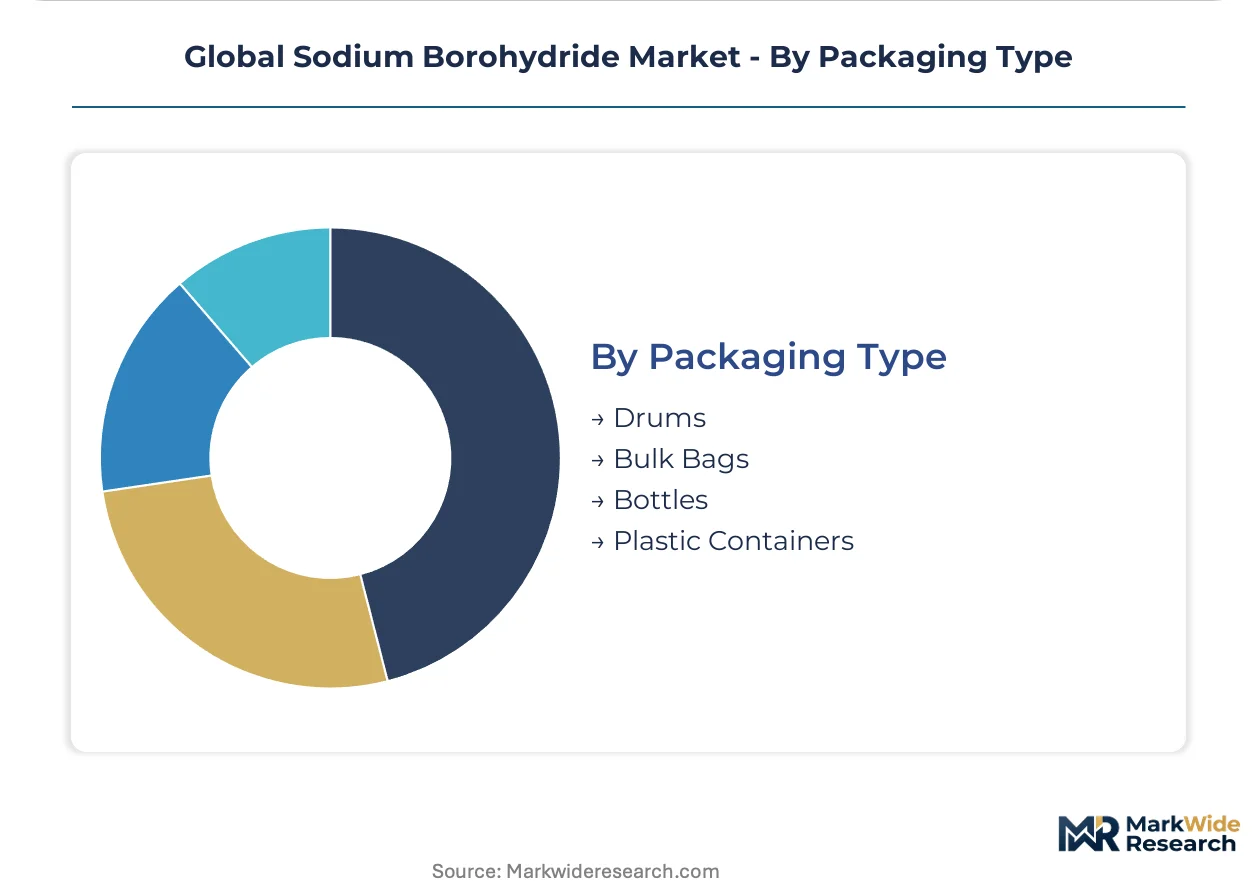
Supply concentration in China and the US dictates regional packaging preferences, with bulk formats dominating Asian captive consumption and unitized packaging serving fragmented European pharmaceutical demand.
- Drums:Standard 50-200 kg steel containers with nitrogen padding for powder and granule formats, dominant in legacy chemical distribution channels.
- Bulk Bags:Flexible intermediate bulk containers of 500-1000 kg for pulp mill and water treatment continuous feed systems.
- Bottles:Amber glass or fluoropolymer containers for laboratory-scale pharmaceutical R&D and analytical reagent supply.
- Plastic Containers:HDPE or fluorinated polymer vessels for aqueous solution formats requiring corrosion resistance and controlled-hazard shipping compliance.
Bulk bags dominate industrial volume. Plastic containers for aqueous solutions are gaining share fastest in pharmaceutical corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers command pricing leverage through captive boron access, while European pharmaceutical buyers absorb premium logistics costs to secure REACH-compliant supply chains. This asymmetry concentrates margin capture in East Asian manufacturing clusters while downstream value pools in Western regulatory jurisdictions.
United States
Massachusetts and New Jersey pharmaceutical corridors drive just-in-time aqueous solution demand through temperature-controlled tanker networks. EPA Clean Water Act effluent guidelines accelerate borohydride adoption in pulp mill deoxygenation systems. The Pacific Northwest pulp belt increasingly specifies sodium borohydride over sulfur-based alternatives under tightening federal discharge mandates.
Germany
Water purification facilities in the Rhine-Ruhr industrial zone specify granule formats for continuous dissolved oxygen control in municipal systems. ECHA REACH authorization workflows now mandate sub-ppm impurity documentation for boron-containing byproducts in pharmaceutical applications. Bavarian fine chemical producers leverage EU Green Deal scoring to elevate borohydride reduction pathways above catalytic hydrogenation.
China
Jiangsu and Zhejiang pharmaceutical manufacturers are building captive borohydride derivative capacity to secure intermediate supply chains for API export markets. NMPA bulk drug oversight and evolving GB standards for pyrophoric chemical handling reshape domestic qualification protocols. Shandong-based producers benefit from integrated boron raw material access through regional borate mining corridors.
India
Gujarat and Maharashtra bulk drug parks attract borohydride intermediate producers through CDSCO-registered manufacturing incentives. Domestic pharmaceutical formulators increasingly source localized reductant supply to reduce import dependency for high-purity material. Hyderabad's active pharmaceutical ingredient cluster is qualifying pellet-fed continuous reactor systems to align with global GMP standards.
Finland
Nordic pulp mills anchor regional consumption through Kemira's channel control in bleaching chemical supply. Integrated forest products producers operate continuous deoxygenation systems tied to regional operating rates and effluent compliance. The Baltic Sea marine protection framework drives sulfur substitution in coastal mill discharge management.
Global Sodium Borohydride Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Vertically integrated boron processors sustain margin structures through captive raw material access, while merchant specialists compete on pharmaceutical-grade certification and logistics flexibility. The vendor base separates into three strategic archetypes: integrated material producers, pharmaceutical-grade specialists, and regional chemical distributors. Dominant competitive moves include backward integration into boron sourcing and geographic expansion through qualified pharmaceutical supply chain partnerships.
Among integrated producers, Vertellus Specialties and Kemira exemplify the upstream-control archetype through multi-step synthesis integration. Shandong Guobang Pharmaceutical and Nantong Hongzhi Chemicals occupy positions within the China-based pharmaceutical-grade supply tier. Ascensus Specialties represents the certified-specialist archetype focused on dedicated reductive chemistry portfolios.
| Leading Market Players |
|---|
| Vertellus Specialties |
| Kemira |
| Montgomery Chemicals |
| Shandong Guobang Pharmaceutical |
| Nantong Hongzhi Chemicals |
| Ascensus Specialties |
| JSC Aviabor |
| Guangxi Guilin Pharmaceutical |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Capacity utilization at Shandong-based integrated boron processors sets price floors that non-integrated merchant traders cannot match, concentrating margin capture in East Asian manufacturing clusters while downstream pharmaceutical buyers in Massachusetts and New Jersey absorb premium logistics costs for REACH-compliant supply chains.
Pricing Analysis
The customization-premium spread between configured-to-order aqueous solutions and standard powder formats runs through certification grade and volume scale as primary differentiation drivers. Contract-based long-term offtake dominates pharmaceutical procurement, while commodity spot pricing governs pulp mill deoxygenation chemical purchases. Pricing pressure stems from boron trifluoride etherate cost volatility destabilizing synthesis economics for non-integrated producers. Pulp and paper buyers exhibit highest price sensitivity, whereas pharmaceutical manufacturers prioritize impurity documentation over unit cost.
Supply Chain Analysis
Boron ore transit from Turkish mining districts through Rotterdam port infrastructure creates a chokepoint that constrains European merchant producer economics. Manufacturing concentrates in China, the United States, and Finland, with raw material dependencies on borate minerals, sodium metal, and hydrogen feedstocks. Single-source vulnerability from concentrated boron ore sourcing in Turkey and the western United States elevates supply risk. Distribution runs through pharmaceutical-grade logistics channels with full chain-of-custody documentation for certified applications, and bulk chemical distributors for industrial deoxygenation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as EPA effluent guideline tightening drives pulp mill substitution of sulfur-based deoxygenation chemistry, creating sustained demand pull through the forecast horizon.
For Market Incumbents: Compound channel control in Nordic pulp markets through dedicated logistics infrastructure and long-term service contracts. Deepen backward integration into boron raw material access to defend margin structures against feedstock volatility. Prioritize pharmaceutical-grade certification investment to capture NMPA and FDA dual-filing protocol demand from Chinese API exporters.
For New Entrants and Emerging Players: Lead with aqueous solution formulation capabilities targeting just-in-time delivery contracts in Massachusetts and New Jersey pharmaceutical corridors. Target CDSCO-registered Indian bulk drug parks as the most penetrable geography, where localized borohydride intermediate production reduces import dependency. Pursue toll manufacturing partnerships with established pharmaceutical logistics providers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated boron processors with captive raw material access and multi-step synthesis capabilities over merchant chemical specialists. Long-term viability across the analysis window hinges on hydrogen storage derivative application development and borohydride fuel cell research trajectories. Monitor ECHA REACH authorization list expansion as the critical inflection signal for reformulation-driven demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Sourcing | Captive borate mineral access insulates margin structures from Turkish ore price volatility. |
| Pharmaceutical-Grade Certification Investment | NMPA and FDA dual-filing protocols unlock parts-per-billion impurity documentation premiums. |
| Aqueous Solution Capacity Expansion | Pre-diluted alkaline formulations align with just-in-time tanker delivery models in US pharmaceutical corridors. |
| Pellet-Fed Continuous Reactor Deployment | Moisture-resistant coated formats reduce operator exposure in CDSCO-registered Indian manufacturing parks. |
| Long-Term Supply Agreement with Pulp Mills | Channel control in Finnish and Swedish markets anchors steady volume offtake under Baltic Sea marine protection frameworks. |
Research Methodology
The analysis maps powder, aqueous solution, granule, and pellet product formats, each validated through procurement directors at pharmaceutical intermediate producers, pulp mill chemical engineers, water treatment facility operators, and specialty chemical distribution managers. Primary interview data triangulates against customs and trade flow records, SEC 10-K filings from disclosed borohydride producers, ECHA substance registration databases, and NMPA bulk drug oversight disclosures. Bottom-up volume modeling across end-use industries reconciles with top-down market sizing through cross-reference consistency checks.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models grade tier, end-use industry, packaging format, and regional production hub as primary segmentation dimensions. CAGRs derive from regression analysis of historical demand patterns and elasticity-adjusted projection inputs. Forecast inputs incorporate EPA effluent guideline implementation timelines and CDSCO bulk drug park incentive program uptake as industry-specific demand drivers.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement, ECHA REACH authorization workflows, and NMPA pharmaceutical ingredient oversight; material policy shifts would require re-modeling across affected geographies. Practitioners should keep alternative scenarios live as hydrogen storage derivative commercialization trajectories and borohydride fuel cell research milestones evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furfural Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Isobutene Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
US Hydrochloric Acid Market