
 Picric Acid Market | 2026-2036
Picric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Picric Acid Market Analysis
ISO 9001 certification is unwinding the competitive landscape for picric acid suppliers, filtering out uncertified producers from defense and pharmaceutical procurement channels. Merck KGaA leverages its analytical standards portfolio to dominate laboratory-grade supply in Europe. Indian Platinum Pvt. Ltd. anchors regional production for explosives applications through backward integration into phenol feedstocks. Odyssey Organics Pvt. Ltd. specializes in custom synthesis for dye intermediate manufacturers seeking consistent batch quality.
Picric acid (2,4,6-trinitrophenol, C₆H₂(NO₂)₃OH) is a highly nitrated aromatic compound synthesized via direct nitration of phenol sulfonic acid, valued for its acidic properties and explosive potential when desensitized. Laboratory-grade formulations command premium positioning due to stringent impurity thresholds below 0.1% for analytical applications, while technical-grade output serves bulk explosives manufacturing where cost efficiency outweighs purity margins. Pharmaceutical-grade picric acid sustains niche demand from topical antiseptic compounders, though regulatory scrutiny limits volume expansion. Crystal form dominates physical distribution channels due to superior storage stability versus hygroscopic powder variants.
REACH registration requirements in Europe, EPA hazardous substance reporting in the United States, and BIS certification mandates in India collectively elevate compliance costs while restricting market entry for unqualified suppliers. OSHA process safety management standards further constrain North American manufacturing scale-up, pushing volume toward jurisdictions with calibrated enforcement frameworks. Stakeholders must monitor evolving explosive precursor regulations across multiple jurisdictions to anticipate supply chain disruptions and qualification timeline extensions.
Market Dynamics
REACH compliance deadlines and evolving explosive precursor regulations are compressing supplier qualification timelines while concentrating procurement among certified producers. ISO 9001 certification now functions as a gatekeeping mechanism for defense and pharmaceutical channels.
Growth Catalysts
- Explosives manufacturing expansion:Indian domestic producers scale phenol-to-picric backward integration to supply mining and defense sectors with desensitized formulations.
- REACH registration thresholds:European purity mandates above 99.5% for analytical applications pull laboratory-grade volumes toward certified chemical suppliers.
- Dye intermediate synthesis:Textile chemical manufacturers in South Asia source consistent batch-quality picric acid for azo coupling reactions.
Market Restraints
- Phenol feedstock volatility:Crude oil-linked benzene pricing transmits cost instability through nitration supply chains.
- Indian production concentration:Overreliance on Maharashtra and Gujarat manufacturing clusters exposes buyers to monsoon logistics disruptions.
- Substitution by 2,4-dinitrophenol:Lower-nitrated phenols displace picric acid in select dye applications where explosive hazard outweighs performance gain.
Strategic Opportunities
- Pharmaceutical antiseptic revival:Topical compounders in Southeast Asia seek GMP-certified picric acid for astringent formulations as chlorhexidine alternatives face resistance concerns.
- EPA hazardous substance reporting:Compliance service providers bundle picric acid inventory management for US university research facilities.
- Continuous nitration reactor technology:Flow chemistry methods reduce batch-to-batch impurity variance below 0.05% for high-specification buyers.
Industry Challenges
- Explosives precursor licensing timelines:DGFT and state-level police clearances in India extend order-to-delivery cycles by 8-12 weeks for international shipments.
- Analytical chemist scarcity:Qualified technicians for HPLC impurity profiling command premium wages, constraining quality control scale-up at mid-size producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Picric Acid Market |
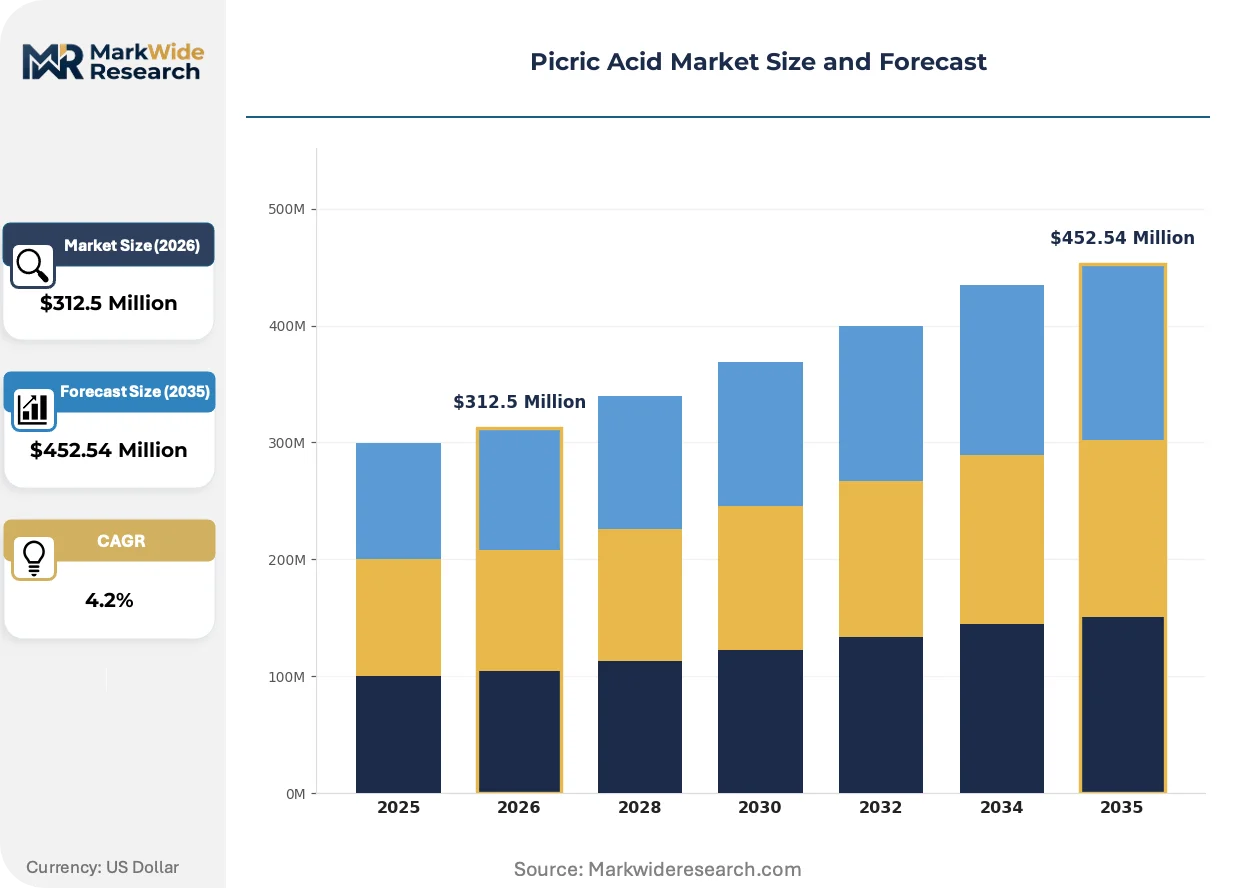
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, Laboratory Grade, Pharmaceutical Grade, Technical Grade Application: Explosives, Dyes, Pharmaceuticals, Laboratory Reagents Form: Crystals, Powder, Solutions, Granules End User: Chemical Manufacturers, Pharmaceutical Companies, Research Institutions, Educational Labs |
| Companies Covered | RICCA Chemical Company, Indian Platinum Pvt. Ltd., Merck KGaA, Parchem Fine & Specialty Chemicals Inc., Otto Chemie Pvt. Ltd., Odyssey Organics Pvt. Ltd., Aadhunik Industries Pvt. Ltd., Spectrum Laboratory Products, Inc., Loba Chemie Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Picric Acid Market Emerging Trajectories
Process intensification and regulatory digitization are compressing traditional batch manufacturing economics while fragmenting procurement channels between commodity explosives supply and precision laboratory tiers.
Continuous flow nitration reactors replace stirred-tank batch systems in phenol sulfonic acid processing. European specialty chemical manufacturers adopt these units to reduce thermal runaway risks and improve yield consistency. Laboratory-grade picric acid produced via flow chemistry is supplanting legacy batch material in analytical standards applications due to sub-0.05% impurity profiles.
ECHA's updated REACH registration requirements for explosive precursors mandate downstream user documentation chains. Chemical distributors must now verify end-use declarations before releasing picric acid shipments. Pharmaceutical compounders in Germany and France face the steepest compliance burdens, driving consolidation toward integrated manufacturer-direct procurement.
Research institutions unbundle chemical supply from equipment maintenance contracts. Universities in the United Kingdom and Netherlands now source picric acid through specialized hazardous material logistics providers rather than general laboratory distributors. This channel shift accelerates in regions where institutional procurement offices centralize explosive precursor oversight under single vendor relationships.
Picric Acid Market Segmentation
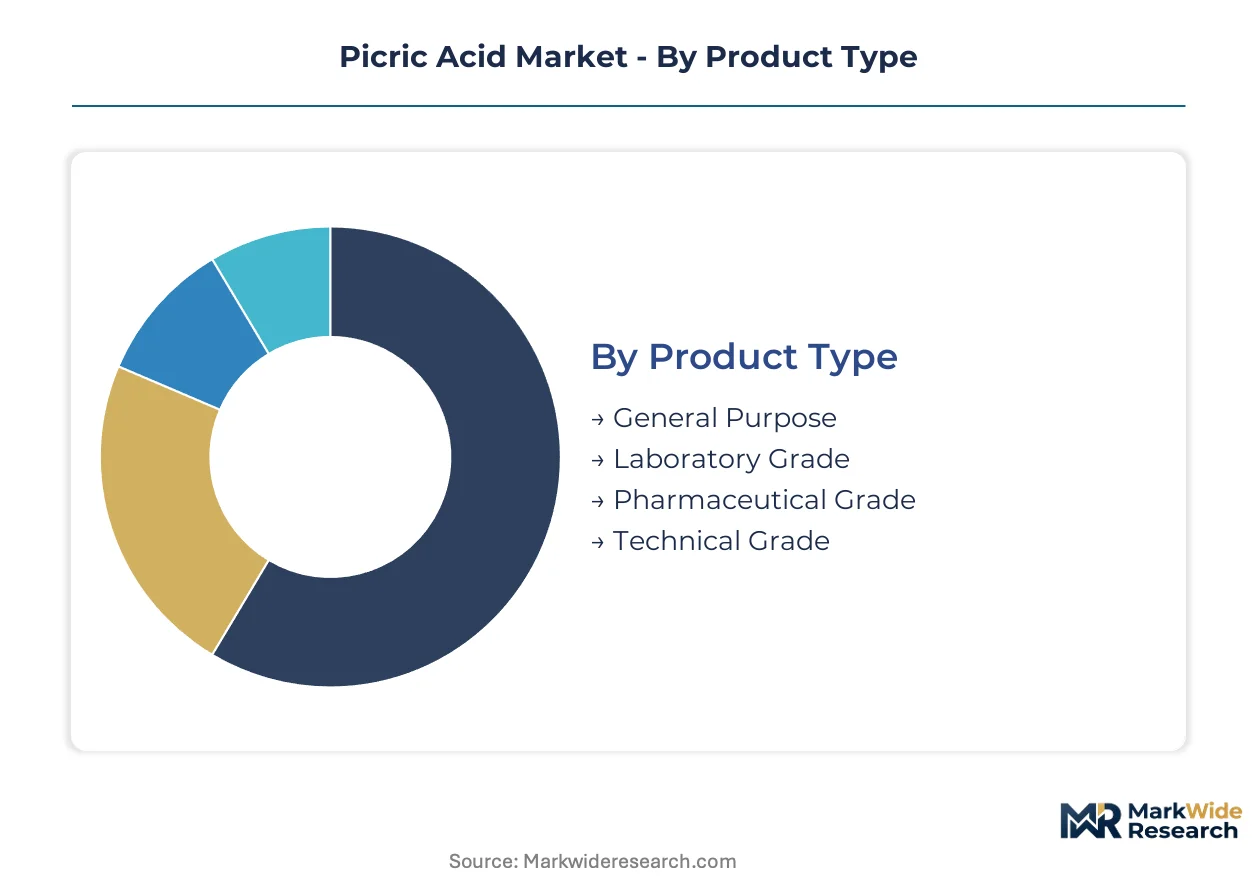
Picric acid procurement channels diverge sharply by purity grade and end-use hazard classification, with defense contractors and pharmaceutical compounders rarely overlapping supplier bases. Channel fragmentation intensifies as REACH documentation requirements and explosives precursor licensing create parallel qualification tracks for laboratory versus technical volumes.
Product Type:
Laboratory-grade and pharmaceutical-grade material flows through certified chemical distributors with end-use verification protocols, while technical-grade volumes move via bulk chemical traders serving mining and defense sectors.
- General Purpose:Intermediate purity specifications serve small-scale dye manufacturers and educational institutions with moderate hazard controls. Demand concentrates in Maharashtra and Gujarat industrial clusters where BIS certification suffices for domestic procurement.
- Laboratory Grade:Sub-0.1% impurity thresholds require HPLC-verified batch certificates and cold-chain logistics for moisture-sensitive crystals. European analytical standards buyers source exclusively through Merck KGaA and ISO 9001-certified distributors with REACH downstream user documentation.
- Pharmaceutical Grade:GMP-compliant production with sterilization validation supports topical antiseptic compounders in Southeast Asia. CDSCO and EMA regulatory filings restrict supplier pools to manufacturers with dedicated pharmaceutical cleanroom suites.
- Technical Grade:Cost-optimized nitration output with 95-98% purity meets desensitized explosives formulation requirements. Indian defense PSUs and mining contractors procure through DGFT-licensed traders with state police clearance documentation.
Technical grade dominates installed base. Pharmaceutical grade is where expansion concentrates.
Application:
Margin structures vary threefold across applications, with explosives manufacturing absorbing feedstock volatility through long-term phenol contracts while laboratory reagents command spot-market premiums.
- Explosives:Desensitized picric acid formulations for ammonium picrate production supply Indian ordnance factories and commercial mining operations. DGFT export licensing and state-level police NOC requirements extend order cycles by 8-12 weeks for international shipments.
- Dyes:Azo coupling reactions in textile chemical manufacturing consume consistent-batch technical grade from Indian Platinum and Odyssey Organics. Substitution pressure from 2,4-dinitrophenol limits volume growth where explosive hazard outweighs colorfastness performance.
- Pharmaceuticals:Topical astringent and antiseptic compounding revives niche demand as chlorhexidine resistance concerns emerge in Southeast Asian hospital formulary committees. GMP certification requirements filter procurement toward integrated manufacturer-direct channels.
- Laboratory Reagents:Analytical standards and histological staining applications require sub-0.05% impurity profiles achievable only through continuous flow nitration. Research institutions in the United Kingdom and Netherlands unbundle supply from equipment contracts to specialized hazardous material logistics providers.
Explosives anchors volume throughput. Laboratory reagents is climbing the fastest.
Form:
Physical stability requirements determine storage and transport economics, with hygroscopic variants demanding climate-controlled warehousing that eliminates price-sensitive buyers.
- Crystals:Superior storage stability and reduced dust explosion risk dominate defense and pharmaceutical procurement specifications. Maharashtra-based manufacturers favor prilled crystal production for monsoon-season logistics resilience.
- Powder:Rapid dissolution kinetics serve dye intermediate synthesis where batch cycle time outweighs handling hazards. Hygroscopic degradation necessitates nitrogen-purged packaging and 18-month shelf life limits.
- Solutions:Pre-dissolved aqueous formulations eliminate dust exposure for educational laboratories with limited fume hood infrastructure. Shelf life constraints restrict distribution radius to 500 kilometers from compounding facilities.
- Granules:Intermediate surface area-to-volume ratio balances dissolution speed with flowability for automated explosives processing lines. Limited commercial availability concentrates supply among European specialty chemical manufacturers.
Crystals dominate installed base. Solutions is gaining share fastest.
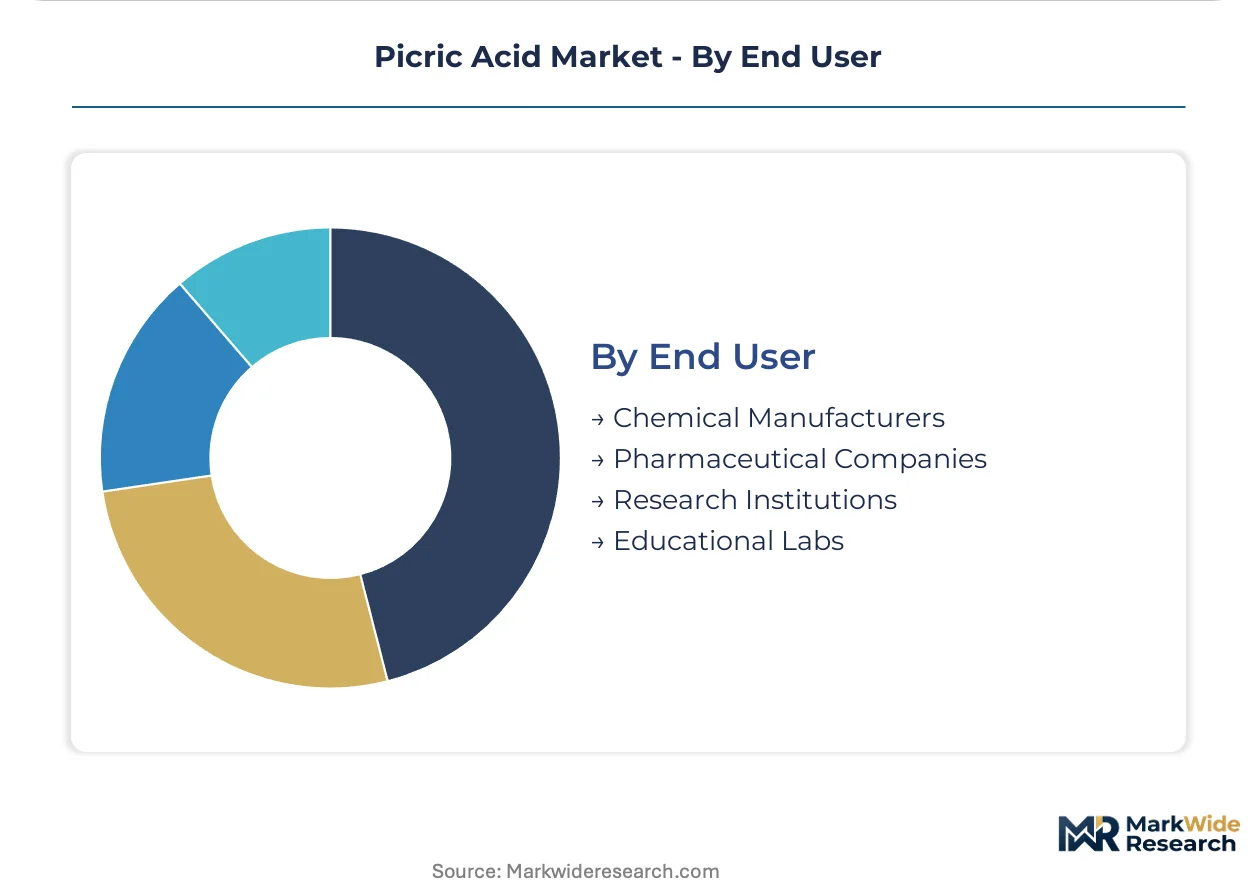
End User:
Procurement sophistication separates institutional buyers with centralized explosive precursor oversight from fragmented chemical manufacturers managing spot inventory.
- Chemical Manufacturers:Dye intermediate and bulk explosives producers integrate backward into phenol feedstocks to secure nitration capacity. Indian Platinum anchors regional supply through captive phenol sulfonic acid production.
- Pharmaceutical Companies:Topical formulation specialists in Germany and France consolidate procurement under single-vendor GMP-certified relationships to streamline ECHA documentation chains. Antiseptic revival in Southeast Asia drives new supplier qualification cycles.
- Research Institutions:University chemistry departments in the United Kingdom and Netherlands centralize picric acid oversight under hazardous material logistics providers rather than general laboratory distributors. EPA hazardous substance reporting compliance bundles inventory management with supply contracts.
- Educational Labs:Secondary school and undergraduate teaching laboratories source general-purpose grade through regional chemical suppliers with simplified hazard communication protocols. Substitution by safer histological stains constrains volume.
Chemical manufacturers dominate installed base. Research institutions is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration deadlines in Europe and DGFT licensing protocols in India are compressing supplier qualification timelines while concentrating procurement among certified producers. Explosives precursor regulations in multiple jurisdictions are reshaping trade flows and manufacturing investment patterns.
India
Mining sector demand and defense ordnance manufacturing absorb technical-grade volumes from Maharashtra and Gujarat production clusters. DGFT export licensing and state police NOC requirements extend international order cycles by 8-12 weeks. Indian Platinum anchors supply through captive phenol sulfonic acid production in western industrial corridors.
Germany
Laboratory-grade procurement for analytical standards pulls volumes toward ECHA-registered distributors with downstream user documentation. REACH explosive precursor mandates force pharmaceutical compounders to consolidate under single-vendor relationships. Merck KGaA dominates European supply through ISO 9001-certified channels serving research institutions.
United States
EPA hazardous substance reporting requirements drive university research facilities toward bundled inventory management contracts. OSHA process safety management standards constrain domestic manufacturing scale-up. Midwest and Southeast educational laboratories source general-purpose grade through regional chemical suppliers with simplified hazard protocols.
United Kingdom
Research institutions centralize picric acid oversight under specialized hazardous material logistics providers rather than general distributors. Institutional procurement offices consolidate explosive precursor management under single vendor relationships. London and Manchester university chemistry departments unbundle chemical supply from equipment maintenance contracts.
France
Topical antiseptic compounders face steep ECHA documentation burdens for pharmaceutical-grade procurement. ANSM regulatory filings restrict supplier pools to manufacturers with dedicated pharmaceutical cleanroom suites. Île-de-France and Auvergne-Rhône-Alpes pharmaceutical clusters drive consolidation toward integrated manufacturer-direct channels.
Picric Acid Market Vendor Landscape
Player mix skews toward mid-size specialty chemical manufacturers with regional certification advantages. Supplier qualification requirements filter procurement toward ISO 9001-certified producers with REACH registration or DGFT licensing. Three archetypes dominate: backward-integrated phenol processors, laboratory-grade specialists with analytical standards portfolios, and custom synthesis providers for dye intermediates. Capacity expansion and certification acquisition represent the dominant competitive moves as uncertified producers exit defense and pharmaceutical channels.
Within the laboratory-grade tier, Merck KGaA and Spectrum Laboratory Products exemplify positioning through analytical standards dominance and hazardous material logistics bundling. Indian Platinum and Odyssey Organics anchor regional production archetypes, with the former representing backward-integrated phenol processing and the latter occupying custom synthesis specialization for consistent batch quality.
| Leading Market Players |
|---|
| RICCA Chemical Company |
| Indian Platinum Pvt. Ltd. |
| Merck KGaA |
| Parchem Fine & Specialty Chemicals Inc. |
| Otto Chemie Pvt. Ltd. |
| Odyssey Organics Pvt. Ltd. |
| Aadhunik Industries Pvt. Ltd. |
| Spectrum Laboratory Products, Inc. |
| Loba Chemie Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
REACH registration and DGFT licensing regimes simultaneously gate supplier qualification and stratify price tiers across the picric acid market, compressing uncertified producers into commodity explosives channels while elevating laboratory-grade premiums through documentation burdens.
Pricing Analysis
Certification level creates the primary spread between technical-grade and laboratory-grade picric acid, with ISO 9001 and REACH registration adding 15-25% documentation premiums to analytical standards volumes. Price differentiation rests on impurity thresholds and end-use verification protocols, with pharmaceutical GMP compliance commanding the highest tier. Cost compression in technical-grade shipments is intensifying as Indian phenol processors expand nitration capacity. Mining contractors and defense ordnance factories exhibit greatest price sensitivity, while research institutions absorb certification premiums for batch-traceable material.
Supply Chain Analysis
Strategic stockpiling dominates explosives-grade procurement as DGFT licensing extends order-to-delivery cycles, whereas laboratory buyers favor just-in-time replenishment through hazardous material logistics providers. Supply concentrates in India, Germany, and the United States, with Maharashtra and Gujarat clusters anchoring technical-grade output. Feedstock dependencies on phenol, sulfuric acid, and nitric acid expose nitration economics to crude oil-linked benzene volatility. Single-source vulnerability concentrates in Indian phenol sulfonic acid processors. Distribution runs through certified chemical distributors for laboratory and pharmaceutical grades, while bulk explosives volumes move via DGFT-licensed traders with state police clearance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified HPLC technicians for impurity profiling represent the critical capability gap constraining quality control scale-up, filtering market participation toward producers with analytical chemistry depth.
For Market Incumbents: Secure backward integration into phenol feedstocks to defend margin position against benzene price volatility, while accelerating continuous flow nitration reactor adoption to sub-0.05% impurity specifications that batch competitors cannot match. Invest in REACH registration maintenance and explosive precursor licensing infrastructure to extend qualification timelines that lock out uncertified entrants. For New Entrants and Emerging Players: Bundled compliance services for EPA hazardous substance reporting represent the most penetrable service-layer gap, where university research facilities seek inventory management partnerships beyond commodity chemical supply. Target Southeast Asian pharmaceutical compounders seeking GMP-certified picric acid for topical antiseptic revival as chlorhexidine alternatives face resistance concerns. Establish manufacturer-direct relationships with dye intermediate producers requiring consistent batch quality rather than competing on spot price. For Investors and Strategic Acquirers: ECHA's updated REACH registration requirements for explosive precursors reshapes the acquisition landscape toward integrated producers with downstream user documentation capabilities. Five-to-ten year viability favors backward-integrated phenol processors with captive nitration capacity and established pharmaceutical cleanroom infrastructure. Watch DGFT export licensing timeline extensions as the signal indicating supply concentration risk and pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Nitration Adoption | Flow chemistry methods reduce thermal runaway risks while achieving sub-0.05% impurity thresholds for analytical standards buyers. |
| Backward Integration into Phenol | Captive phenol sulfonic acid production insulates Indian Platinum and similar processors from benzene feedstock volatility. |
| REACH Registration Investment | ECHA compliance documentation chains filter laboratory-grade procurement toward registered distributors with downstream user verification. |
| GMP Certification Acquisition | Pharmaceutical cleanroom suites qualify producers for CDSCO and EMA-regulated topical antiseptic compounding in Southeast Asia. |
| Hazardous Material Logistics Partnership | Specialized providers bundle EPA compliance with inventory management for university research facilities centralizing explosive precursor oversight. |
Methodological Framework
Desk research of customs trade databases, chemical industry association filings, and regulatory registration records preceded structured interviews with plant managers at nitration facilities, procurement leads at dye intermediate manufacturers, distribution channel partners in hazardous material logistics, and technical R&D directors at analytical standards suppliers. Primary fieldwork combined with secondary validation from BIS certification registries, DGFT licensing databases, and ECHA REACH submissions. Bottom-up volume estimates triangulated against top-down market sizing across grade tiers and end-use applications.
Variance decomposition across purity grade, physical form, and end-use hazard classification shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include laboratory versus technical versus pharmaceutical grade, crystal versus powder versus solution form, and explosives versus dyes versus pharmaceuticals versus laboratory reagents application. CAGRs derived from regression analysis against phenol feedstock pricing indices and explosives manufacturing output trends. Continuous nitration technology adoption curves and REACH registration timeline extensions served as industry-specific forecast inputs.
Underlying assumptions cover stable phenol sulfonic acid supply availability and DGFT licensing protocol continuity, with deviation risk concentrated in monsoon logistics disruptions to Maharashtra and Gujarat manufacturing clusters and evolving explosive precursor regulations across multiple jurisdictions. Revision becomes warranted when phenol feedstock volatility exceeds historical bands or when regulatory qualification timelines compress supplier pools beyond concentration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Global Sodium Sulfate Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Global Sodium Hydrosulfite Market