
 Hydroxypropionic Acid Market | 2026-2036
Hydroxypropionic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxypropionic Acid Market Analysis
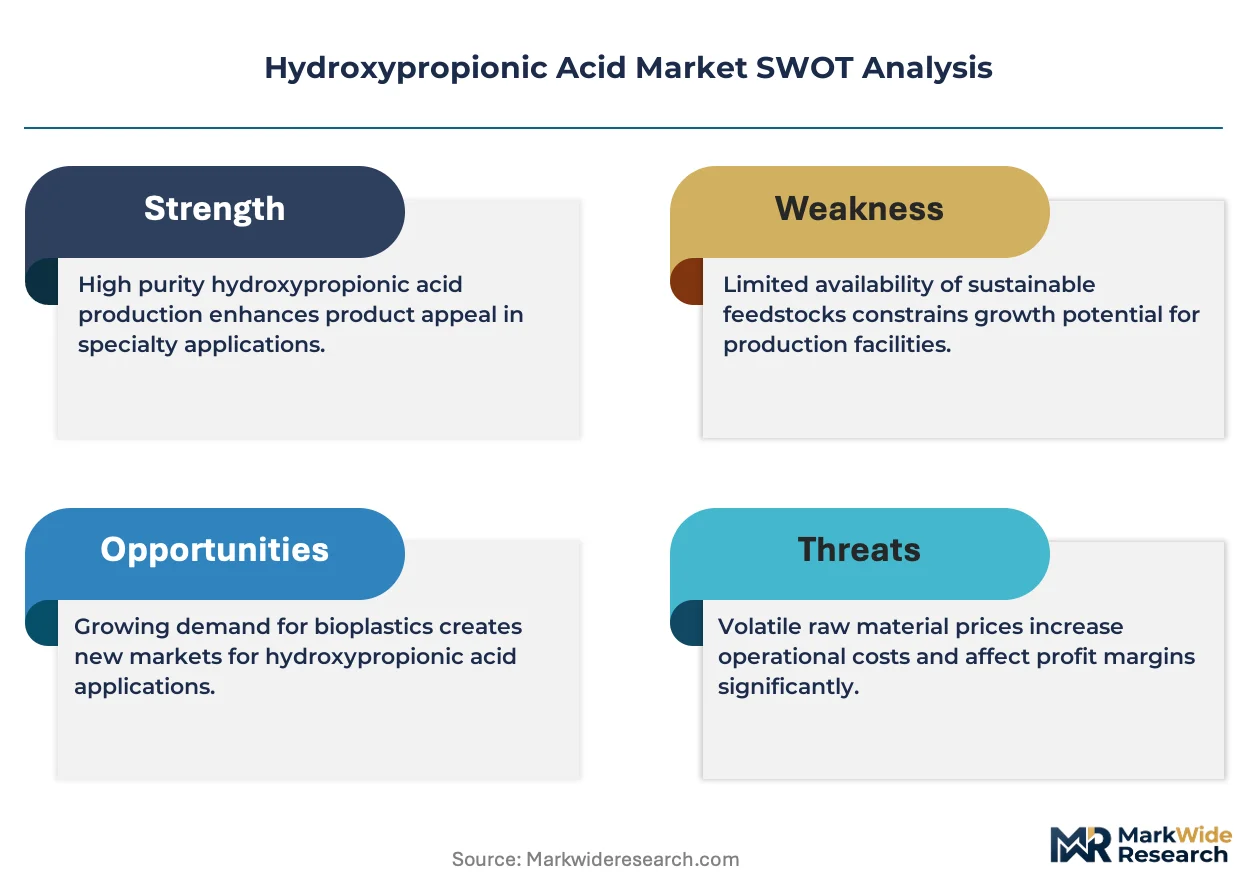
ISO 17025 accreditation is collapsing as the baseline qualification for hydroxypropionic acid suppliers serving pharmaceutical and food-grade buyers, compressing the qualified vendor pool to firms with verified analytical capabilities. Cargill leverages its agricultural feedstock integration to secure low-cost glucose streams for fermentation routes. BASF anchors European supply through its Ludwigshafen complex, where backward integration into propylene oxide chemistry sustains cost position. Novozymes competes via enzyme engineering leadership, offering biocatalyst packages that reduce conversion cycle times.
Hydroxypropionic acid, or 3-hydroxypropionic acid, is a three-carbon carboxylic acid with molecular formula C₃H₆O₃, typically produced through microbial fermentation of glucose or glycerol using engineered yeast or bacterial strains, and functions as a platform chemical for acrylic acid derivatives, bioplastics, and specialty esters. Synthetic Hydroxypropionic Acid currently dominates volume as petrochemical routes retain cost advantage at scale, though Natural Hydroxypropionic Acid commands premium positioning in cosmetics and clean-label food applications where fermentation-derived provenance justifies higher unit economics. Biopolymers represent the fastest-growing application segment, with manufacturers substituting petroleum-based acrylic acid precursors in superabsorbent polymer and coating formulations.
EPA bio-preferred procurement standards and REACH substance registration requirements in Europe are redirecting formulation R&D toward bio-based hydroxypropionic acid pathways, while FDA food additive petitions govern GRAS status for acidulants in beverage and confectionery uses. China's GB standards for industrial biochemicals and NMPA pharmaceutical excipient rules add compliance layers for import-dependent buyers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Fermentation-based production economics are tightening competitive pressure on synthetic hydroxypropionic acid routes, as agricultural feedstock volatility and carbon-accounting requirements reshape capital allocation decisions across biopolymer supply chains.
Growth Catalysts
- REACH substance registration:ECHA's tightening bio-based chemical benchmarks are redirecting formulation R&D toward fermentation-derived hydroxypropionic acid pathways in European coatings and adhesives sectors.
- Superabsorbent polymer substitution:Biopolymer manufacturers are expanding procurement of bio-based feedstocks for diaper and hygiene product applications, displacing petroleum-derived acrylic acid precursors.
- Leverkusen-Ludwigshafen cluster:Industrial biotechnology concentration in Germany's Rhine corridor anchors scaled fermentation infrastructure and specialized enzyme engineering talent pools.
Market Restraints
- Glucose feedstock volatility:Corn and wheat price swings directly compress fermentation route margins, exposing producers to agricultural commodity cycles absent in propylene oxide chemistry.
- ISO 17025 accreditation scarcity:Pharmaceutical and food-grade buyers are collapsing their qualified vendor pools to firms with verified analytical capabilities, concentrating supply risk among fewer certified suppliers.
- Petrochemical cost advantage:Synthetic hydroxypropionic acid retains unit economics superiority at industrial scale, limiting bio-based penetration in price-sensitive industrial applications.
Strategic Opportunities
- EPA bio-preferred procurement:Federal purchasing mandates for bio-based products are creating dedicated demand channels for fermentation-derived acidulants and platform chemicals in US institutional markets.
- Cosmetics clean-label positioning:Fermentation-derived provenance commands premium pricing in personal care formulations, with natural hydroxypropionic acid substituting for synthetic alternatives in skincare and fragrance applications.
- CRSF enzyme-package licensing:Biocatalyst technology convergence with continuous processing equipment is enabling toll-manufacturing models that reduce capital barriers for regional market entry.
Industry Challenges
- GRAS petition timelines:FDA food additive review cycles for novel acidulants extend 24-36 months, delaying revenue recognition for fermentation-derived grades targeting beverage and confectionery markets.
- Cross-border compliance divergence:China's GB standards for industrial biochemicals, Europe's REACH registration tiers, and US EPA criteria create stranded inventory risk for multi-jurisdictional suppliers.
- Fermentation scale-up capex intensity:Commercial bioreactor infrastructure requires 150-200 million dollar commitments for nameplate capacity, constraining mid-cap participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxypropionic Acid Market |
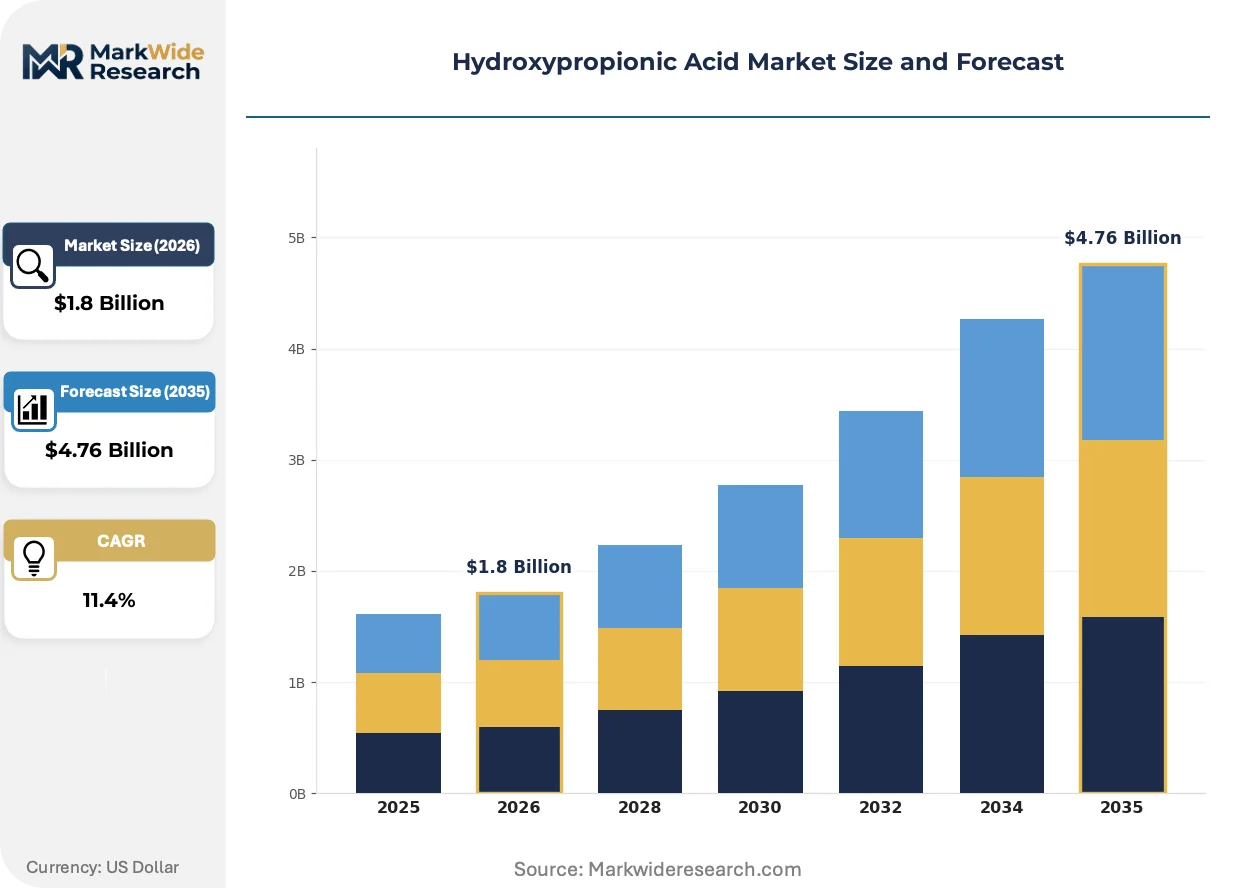
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Hydroxypropionic Acid, Synthetic Hydroxypropionic Acid, Derivatives, Blends Application: Cosmetics, Food & Beverage, Pharmaceuticals, Biopolymers End User: Manufacturers, Research Institutions, Healthcare Providers, Retailers Packaging Type: Bulk Containers, Drums, Jars, Sachets |
| Companies Covered | BASF, Cargill, LG Chem, ADM, Novozymes, Corbion, DSM-Firmenich, Thermo Fisher Scientific, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxypropionic Acid Market Emerging Trajectories
Platform chemical economics are fragmenting as modular biomanufacturing units and distributed fermentation capacity erode the scale advantages of centralized petrochemical complexes. Three concurrent shifts are reshaping competitive positioning.
Continuous fermentation technology is fragmenting traditional batch-production economics in hydroxypropionic acid manufacturing. Engineered yeast strains with enhanced glycerol tolerance are achieving titer rates that approach synthetic route efficiency. Biopolymer manufacturers in Germany and the Netherlands are piloting integrated fermentation-polymerization units that compress conversion cycle times from weeks to days.
REACH registration requirements are tightening substance data obligations for hydroxypropionic acid importers and formulators. ECHA's expanded bio-based chemical sustainability benchmarks are forcing petrochemical producers to document carbon intensity across supply chains. European coatings manufacturers are accelerating substitution trials to preempt compliance-driven supply disruptions.
Buyer certification requirements are compressing vendor qualification cycles for pharmaceutical and food-grade hydroxypropionic acid procurement. ISO 17025 accreditation has displaced generic quality statements as the baseline threshold for contract consideration. Procurement teams in Japan and South Korea are consolidating supplier panels to firms with verified analytical capabilities and documented fermentation provenance.
Hydroxypropionic Acid Market Segmentation
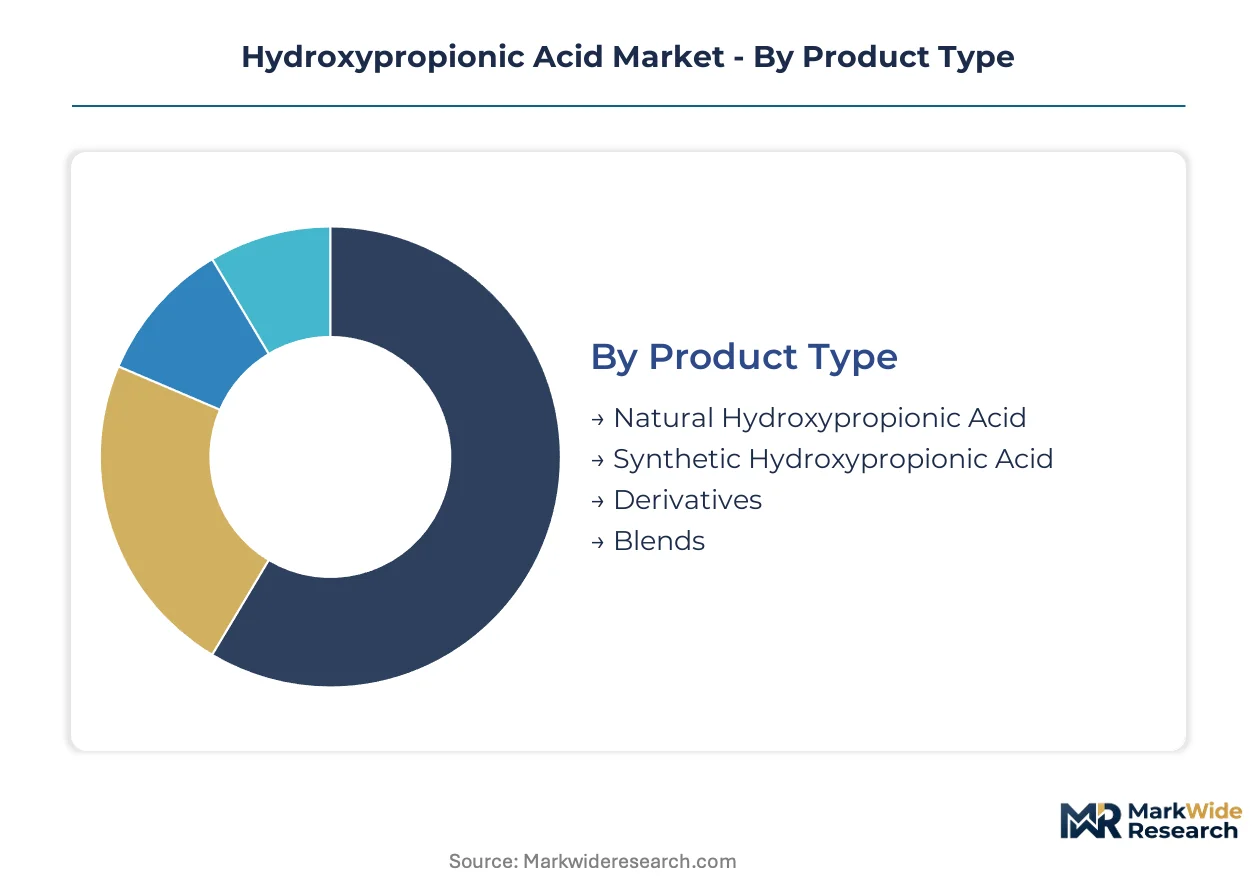
Segmentation in hydroxypropionic acid markets tracks divergent compliance pathways across regulatory jurisdictions. Product origin determines REACH registration tiers, FDA GRAS eligibility, and carbon-accounting methodologies that reshape procurement decisions.
Product Type:
REACH substance registration tiers and EPA bio-preferred procurement criteria create divergent commercial pathways for each production origin.
- Natural Hydroxypropionic Acid:Fermentation-derived grades from engineered yeast or bacterial strains carry documented carbon intensity credentials required by ECHA sustainability benchmarks. Cosmetics formulators in Germany and the Netherlands pay premium pricing for provenance verification in clean-label skincare applications.
- Synthetic Hydroxypropionic Acid:Petrochemical routes via propylene oxide chemistry retain cost advantage at industrial scale. BASF's Ludwigshafen complex anchors European supply through backward integration into captive feedstock streams.
- Derivatives:Acrylic acid precursors and specialty esters for superabsorbent polymer applications.
- Blends:Formulated grades combining natural and synthetic fractions to balance cost and compliance positioning.
Synthetic Hydroxypropionic Acid handles the majority of throughput; Natural Hydroxypropionic Acid is the fastest mover on share.
Application:
End-use concentration patterns reflect divergent certification requirements and margin structures across customer segments.
- Biopolymers:Polyhydroxyalkanoate and polylactic acid alternative manufacturers in Germany's Leverkusen-Ludwigshafen corridor anchor fermentation-based procurement. REACH registration data obligations accelerate substitution trials away from petroleum-derived acrylic acid precursors in diaper and hygiene product formulations.
- Cosmetics:Fermentation-derived provenance commands premium positioning in personal care formulations where clean-label claims justify higher unit economics.
- Food & Beverage:FDA GRAS petition timelines extend revenue recognition cycles for acidulant applications in beverage and confectionery markets.
- Pharmaceuticals:ISO 17025 accreditation requirements compress qualified vendor pools for excipient-grade procurement.
Biopolymers absorb the largest volume flows; Biopolymers also posts the steepest expansion trajectory.
End User:
Customer type determines specification stringency and contract structure across the value chain.
- Manufacturers:Biopolymer producers and coatings formulators drive bulk procurement with fermentation provenance requirements.
- Research Institutions:Pilot-scale fermentation trials and biocatalyst development programs.
- Healthcare Providers:Compounding pharmacies and specialty pharmaceutical manufacturers.
- Retailers:Clean-label product lines requiring documented supply chain transparency.
Manufacturers command the dominant share of offtake; Research Institutions show the most rapid enrollment growth.
Packaging Type:
Logistics configuration tracks customer scale and contamination risk thresholds.
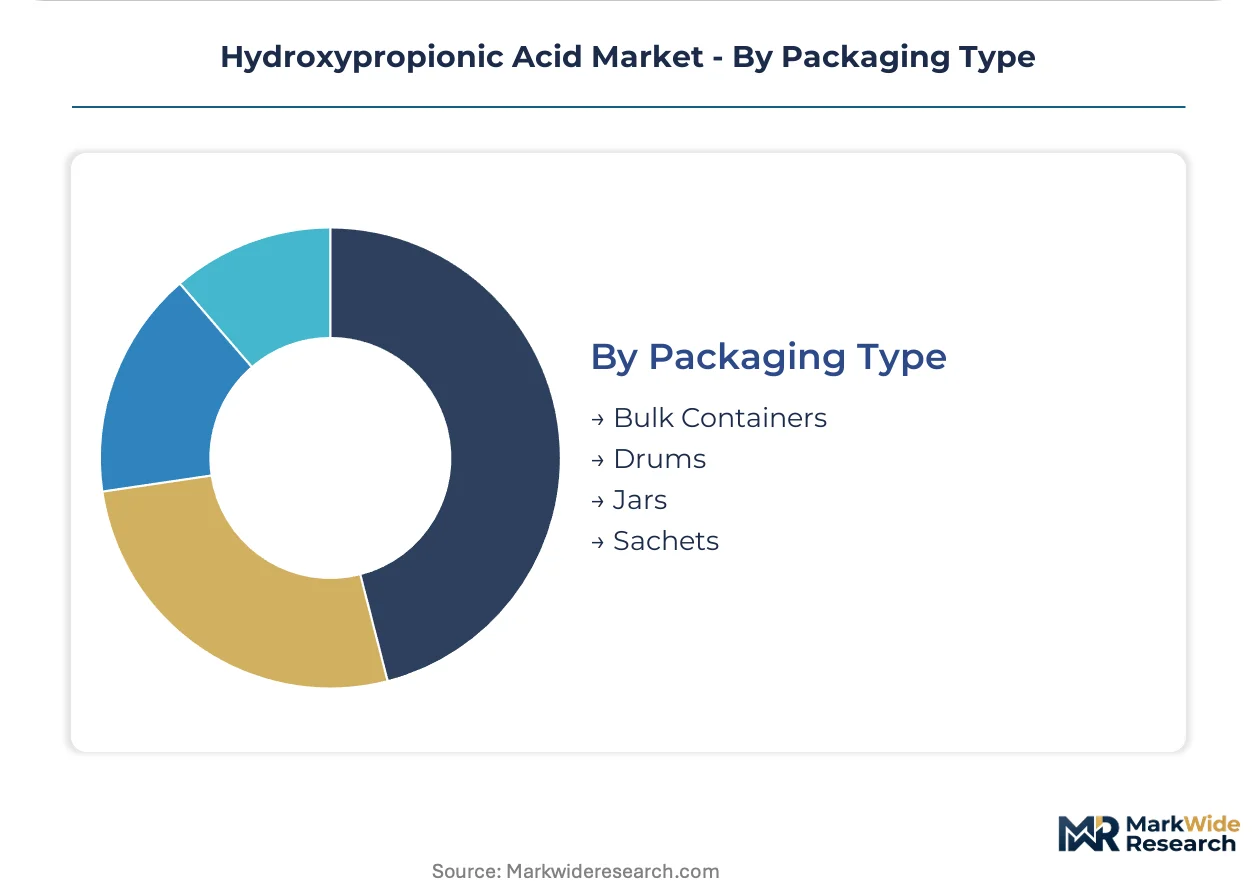
- Bulk Containers:Tanker and ISO-tank deliveries for integrated fermentation-polymerization units.
- Drums:Standard industrial packaging for coatings and adhesives formulators.
- Jars:Pharmaceutical and food-grade specifications with tamper-evident sealing.
- Sachets:Sample and pilot-scale quantities for R&D procurement.
Bulk Containers move the greatest tonnage; Sachets are climbing the fastest on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker terminals anchor European hydroxypropionic acid throughput, while Union Pacific's rail corridors connect Midwest agricultural feedstock basins to biomanufacturing clusters. These infrastructure assets determine regional competitive positioning.
United States
EPA bio-preferred procurement mandates drive institutional demand for fermentation-derived grades. FDA GRAS petition backlogs delay food-grade market entry by 24-36 months. Iowa corn belt glucose streams feed Cargill's bioprocessing infrastructure.
Germany
ECHA REACH registration tiers redirect coatings formulators toward bio-based pathways. The Leverkusen-Ludwigshafen corridor concentrates fermentation capacity and enzyme engineering talent. BASF's Ludwigshafen complex maintains synthetic route dominance through propylene oxide integration.
China
GB standards for industrial biochemicals create compliance friction for import-dependent buyers. NMPA pharmaceutical excipient rules govern healthcare applications. Yangtze River Delta biomanufacturing parks scale fermentation infrastructure for domestic biopolymer feedstock.
Netherlands
Port of Rotterdam liquid bulk terminals handle transatlantic hydroxypropionic acid flows. EU Green Deal carbon-accounting requirements accelerate bio-based substitution trials. Corbion's biotech operations in Gorinchem exemplify integrated fermentation-polymerization positioning.
Japan
METI biomanufacturing roadmaps prioritize platform chemical self-sufficiency. PMDA pharmaceutical standards compress qualified vendor pools for excipient-grade procurement. Osaka-Kobe industrial zone hosts pilot-scale continuous fermentation trials.
Hydroxypropionic Acid Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and feedstock integration dimensions. The vendor base stratifies into three tiers: petrochemical conglomerates with backward-integrated propylene oxide assets, agricultural processors leveraging captive glucose streams, and enzyme technology licensors. Strategic moves center on fermentation scale-up commitments and biocatalyst package licensing.
Within the petrochemical tier, BASF anchors European supply through its Ludwigshafen complex. Cargill occupies a position among agricultural processors with Midwest feedstock integration. Novozymes exemplifies the enzyme technology archetype, licensing biocatalyst packages that reduce conversion cycle times for toll manufacturers.
| Leading Market Players |
|---|
| BASF |
| Cargill |
| LG Chem |
| ADM |
| Novozymes |
| Corbion |
| DSM-Firmenich |
| Thermo Fisher Scientific |
| TotalEnergies |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Leverkusen-based fermentation operators and German biopolymer manufacturers lock in supply access while providing visibility into feedstock-adjusted pricing corridors. These arrangements insulate procurement teams from glucose volatility while exposing them to carbon-accounting premiums under EU Green Deal compliance frameworks.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade hydroxypropionic acid, with ISO 17025-accredited suppliers commanding substantial premiums over generic chemical-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects fermentation provenance, analytical verification depth, and volume commitment scale. Pricing pressure stems from synthetic route cost compression as BASF's Ludwigshafen complex leverages propylene oxide integration. Coatings formulators exhibit the highest price sensitivity, while cosmetics manufacturers demonstrate inelastic demand for documented fermentation origin.
Supply Chain Analysis
Germany and the Netherlands anchor European fermentation capacity, with the Leverkusen-Ludwigshafen corridor hosting scaled bioreactor infrastructure and Rotterdam's liquid bulk terminals handling transatlantic feedstock flows. Production draws from Midwest US corn belt glucose streams and European wheat-derived substrates, with enzyme engineering concentrated in Danish and German biotechnology clusters. Single-source vulnerability persists around specialized biocatalyst suppliers, particularly for continuous fermentation packages. Distribution runs through integrated fermentation-polymerization units serving biopolymer manufacturers directly, supplemented by drum shipments to coatings and adhesives formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among German biopolymer manufacturers has shifted negotiating leverage toward volume buyers capable of committing to multi-year offtake structures. This buyer-power concentration rewards suppliers with certified provenance and scale.
For Market Incumbents: Secure backward integration into agricultural feedstock streams to defend margins against glucose price volatility. Deepen ISO 17025 analytical capabilities to maintain qualification status as pharmaceutical and food-grade buyers collapse vendor panels. Anchor capacity expansion in the Leverkusen-Ludwigshafen corridor to exploit cluster effects in enzyme engineering talent and shared infrastructure. For New Entrants and Emerging Players: Lead with toll-manufacturing models utilizing licensed biocatalyst packages to bypass capital-intensive bioreactor construction. Target cosmetics clean-label segments in the Netherlands and Germany where fermentation-derived provenance commands premium positioning. Pursue EPA bio-preferred procurement channels in US institutional markets as a beachhead application with dedicated demand mandates. For Investors and Strategic Acquirers: The market sits at a fermentation-scale-up phase that favors enzyme technology licensors and modular biomanufacturing equipment providers. Long-term viability hinges on carbon-accounting regime durability across European and North American jurisdictions. Acquisition focus should center on firms with verified REACH registration dossiers and documented supply chain transparency. The signal to watch is ECHA's tightening of bio-based chemical sustainability benchmarks, which would accelerate substitution trials and expand addressable market for fermentation-derived grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill's agricultural asset base secures low-cost glucose streams for fermentation economics. |
| Continuous Fermentation Technology Licensing | Novozymes biocatalyst packages reduce conversion cycle times for toll-manufacturing entrants. |
| ISO 17025 Accreditation Investment | Verified analytical capabilities compress qualified vendor pools to certified suppliers only. |
| REACH Registration Tier Advancement | ECHA sustainability benchmarks redirect coatings formulators toward bio-based procurement. |
| Integrated Fermentation-Polymerization Units | Corbion's Gorinchem operations exemplify compressed conversion cycles from weeks to days. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation plant managers, biopolymer procurement leads, enzyme engineering directors, and coatings formulator technical teams, then refined through secondary validation against ECHA REACH registration databases, US EPA bio-preferred procurement records, customs trade flows, and SEC filings from listed chemical conglomerates. Bottom-up capacity modeling triangulated with top-down demand segmentation across product grades and end-use applications.
Variance decomposition tracked forecast sensitivity to feedstock price assumptions, regulatory compliance cost trajectories, and substitution elasticity between synthetic and fermentation-derived grades. Segmentation dimensions modeled include production origin, application vertical, certification tier, packaging format, and regional production hub concentration. CAGRs were derived from installed capacity buildout schedules, demand elasticity estimates, and carbon-accounting premium persistence assumptions across the projection horizon.
Forecasts assume regulatory continuity in EU REACH tiers and US EPA bio-preferred criteria; material policy shifts would require re-modeling of substitution timelines and compliance cost burdens. Recalibration cycles align with material shifts in agricultural commodity prices, ECHA substance registration deadlines, and FDA GRAS petition adjudications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Insoluble Fibers Market