
 Acetyl Isovaleryl Market | 2026-2036
Acetyl Isovaleryl Market Size, Share, and Industry Trends Forecast 2026-2036
Acetyl Isovaleryl Market Outlook
Synthetic musk precursors is shifting toward bio-based acetyl isovaleryl derivatives as manufacturers reformulate fragrance compounds to meet tightening environmental standards. Penta Manufacturing Company leverages its specialty chemical infrastructure to supply high-purity grades for flavor and fragrance houses across North America. Vigon International anchors its position through deep inventory of aroma chemical precursors and custom blending capabilities. Synerzine specializes in niche ester production, competing on molecular specificity rather than volume scale.
Acetyl isovaleryl denotes a branched C5 acyl derivative synthesized via acetylation of isovaleric acid or its salts, typically yielding colorless to pale yellow liquids with characteristic fruity, cheesy odor profiles valued at high dilution in flavor compounding. The compound serves primarily as a flavor modifier and fragrance intermediate, with acetyl isovaleryl acetate dominating commercial volumes due to its broad regulatory acceptance in food-grade applications. Acetyl isovaleryl ester represents the fastest-growing product type as cosmetic manufacturers seek novel scent molecules with improved biodegradability profiles. The pharmaceutical application segment remains comparatively mature, with margin pools concentrated in agricultural chemicals where acetyl isovaleryl chloride functions as a crop protection intermediate.
EPA oversight of volatile organic compound emissions and REACH registration requirements for fragrance substances jointly elevate compliance costs for acetyl isovaleryl manufacturers seeking multi-regional market access. FDA food additive regulations and FEMA GRAS listings determine which acetyl isovaleryl derivatives qualify for direct food contact, creating a bifurcated supply chain between food-grade and industrial-grade specifications. Stakeholders must monitor evolving biopreference policies in major economies that could accelerate substitution of petrochemical-derived acetyl isovaleryl with fermentation-based alternatives.
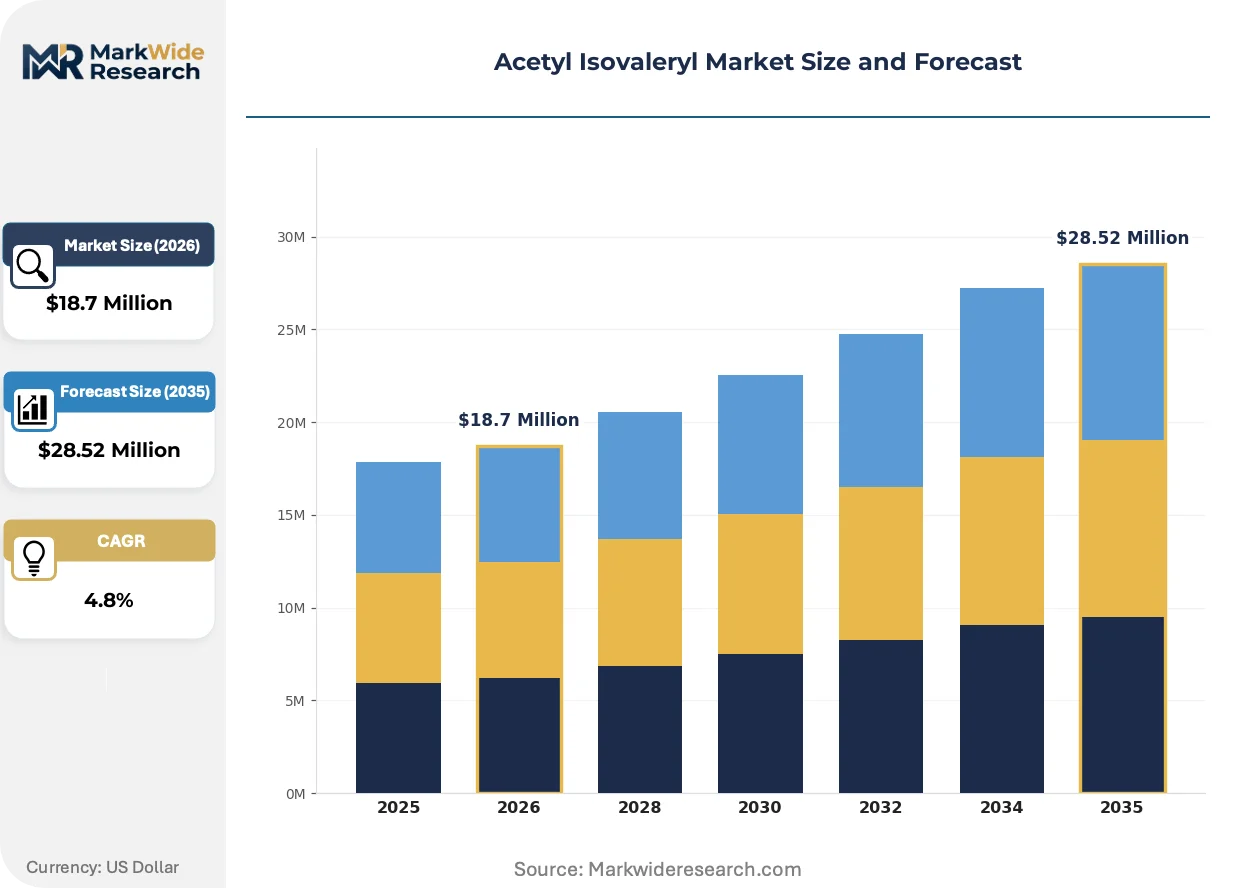
Market Dynamics
Clean-label formulation mandates across food and fragrance sectors are compressing acceptable feedstock lists, forcing acetyl isovaleryl producers to requalify supply chains for bio-derived precursors while maintaining cost parity with petrochemical routes.
Growth Catalysts
- REACH purity specifications:ECHA registration requirements for fragrance intermediates are filtering out low-grade suppliers, consolidating volume among compliant manufacturers serving European cosmetic houses.
- Fermentation-derived precursors:Advances in engineered yeast strains for isovaleric acid biosynthesis are reducing reliance on petroleum feedstocks for acetyl isovaleryl synthesis.
- China's captive production:Domestic flavor and fragrance producers in Jiangsu and Zhejiang provinces are scaling acetyl isovaleryl acetate output for regional cosmetic brand supply chains.
Market Restraints
- Feedstock volatility:Isovaleric acid supply fluctuates with petrochemical cracking margins and bio-fermentation batch yields, compressing producer margins during input price spikes.
- Specialty chemical concentration:North American supply depends heavily on a limited number of contract manufacturers with acetylation capability, creating single-source vulnerability.
- EPA VOC thresholds:Emission limits for volatile organic compounds in fragrance manufacturing are forcing capital expenditure on containment systems that smaller producers cannot absorb.
Strategic Opportunities
- India's FSSAI pathway:India's food safety regulator is expanding approved flavorant lists, creating first-mover advantage for acetyl isovaleryl suppliers establishing local technical dossiers.
- Agricultural chemical intermediates:Acetyl isovaleryl chloride applications in crop protection chemistry represent underexploited volume pools beyond fragrance and flavor segments.
- EU Green Deal biopreference:Carbon border adjustment mechanisms and renewable content mandates are creating preferential market access for fermentation-derived acetyl isovaleryl esters.
Industry Challenges
- Analytical chemist scarcity:Specialized expertise in chiral separation and trace impurity quantification for fragrance-grade certification is concentrated among retiring specialists in European and Japanese laboratories.
- Multi-jurisdiction dossier compilation:Simultaneous FDA FEMA GRAS, ECHA REACH, and China NMPA registrations require parallel toxicology studies with non-harmonized protocols, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetyl Isovaleryl Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.52 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetyl Isovaleryl Acetate, Acetyl Isovaleryl Chloride, Acetyl Isovaleryl Alcohol, Acetyl Isovaleryl Ester Application: Flavors, Fragrances, Pharmaceuticals, Agricultural Chemicals End User: Food Industry, Cosmetic Industry, Chemical Manufacturers, Pharmaceutical Companies Form: Liquid, Solid, Powder, Solution |
| Companies Covered | Penta Manufacturing Company, Wholechem, Vigon International, Synerzine, TCI America, Fenghen Group Co, Ltd, Parchem, Hisunny Chemical, BOC Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetyl Isovaleryl Market Strategic Shifts
Acetyl isovaleryl production is bifurcating between legacy petrochemical acetylation and emerging bio-fermentation routes, with regulatory preference increasingly tilting the investment calculus toward the latter despite yield penalties.
Continuous flow acetylation reactor technology is expanding into commercial-scale acetyl isovaleryl manufacturing, replacing batch kettle operations. German and Swiss engineering firms are installing modular flow chemistry units for flavor houses seeking tighter lot-to-lot consistency. This technology is expanding into mid-volume production runs previously dominated by conventional batch processing, compressing cycle times and reducing solvent waste volumes.
REACH authorization requirements for fragrance substances are tightening purity thresholds for acetyl isovaleryl derivatives entering European cosmetic supply chains. ECHA's 2024 updated guidance on respiratory sensitizers is forcing reformulation of fragrance compounds containing branched acyl intermediates. Fine fragrance houses in France and Germany are accelerating substitution timelines, prioritizing suppliers with pre-submitted full substance dossiers.
Direct contracting between flavor houses and fermentation technology developers is displacing traditional chemical distributor intermediaries for bio-derived acetyl isovaleryl procurement. North American clean-label food manufacturers are negotiating multi-year offtake agreements with synthetic biology startups, bypassing established aroma chemical traders. This pattern is most visible in California and Pacific Northwest food technology clusters where carbon accounting requirements drive feedstock traceability demands.
Acetyl Isovaleryl Market Segmentation
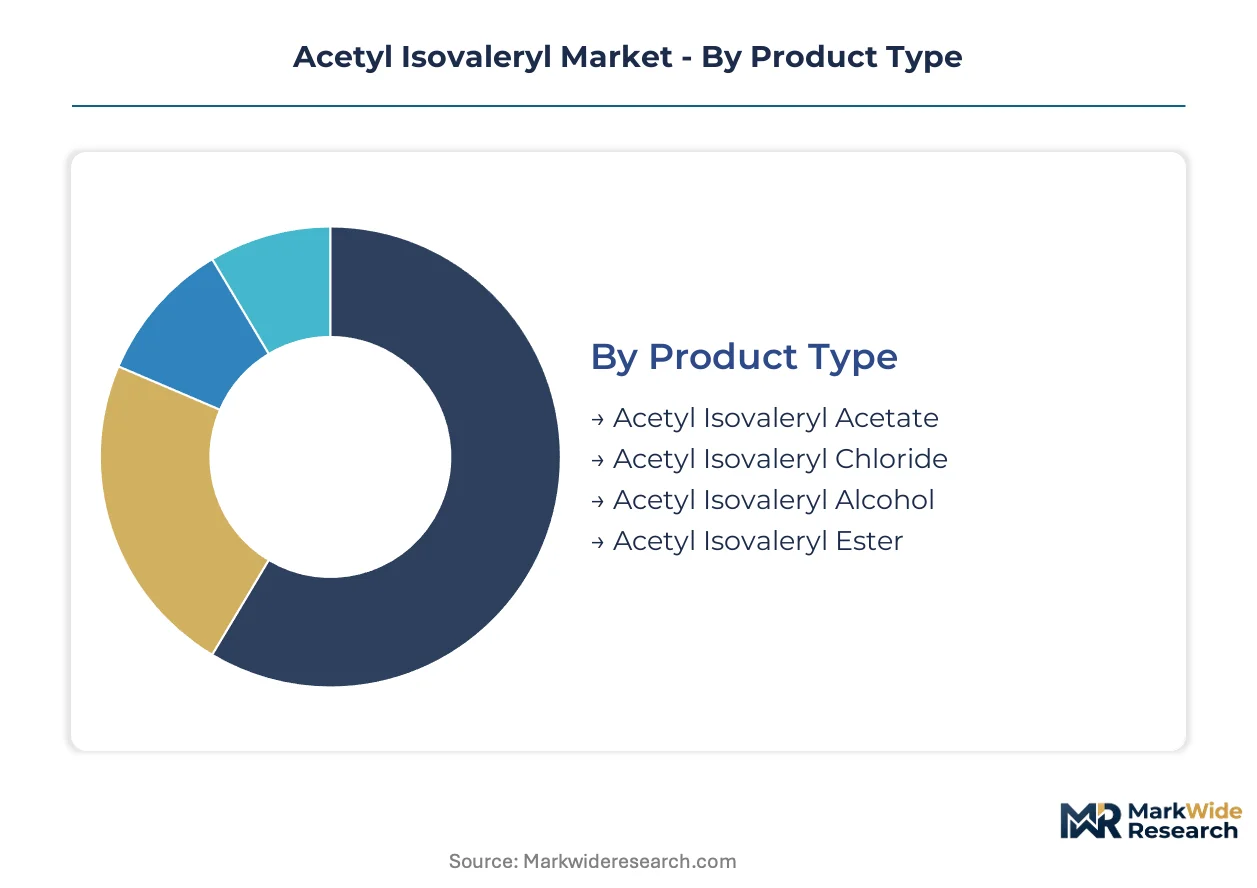
Segmentation in the acetyl isovaleryl market maps directly onto divergent regulatory pathways and purity specifications. Each category channels distinct certification burdens, from FDA FEMA GRAS listings for food-grade derivatives to ECHA REACH dossiers for fragrance intermediates.
Product Type:
Certification complexity varies sharply across this category, with food-grade esters requiring FDA FEMA GRAS submission while industrial chlorides face EPA TSCA scrutiny.
- Acetyl Isovaleryl Acetate:This colorless liquid ester dominates commercial volumes through broad regulatory acceptance in flavor compounding. Demand concentrates in China where Jiangsu and Zhejiang producers scale captive output for regional cosmetic supply chains, though REACH purity thresholds filter out low-grade European suppliers.
- Acetyl Isovaleryl Ester:Cosmetic manufacturers prioritize this derivative for novel scent molecules with improved biodegradability profiles. French and German fine fragrance houses accelerate substitution timelines toward this segment as ECHA's updated respiratory sensitizer guidance forces reformulation of legacy compounds.
- Acetyl Isovaleryl Chloride:Functions primarily as a crop protection intermediate with concentrated margin pools in agricultural chemistry.
- Acetyl Isovaleryl Alcohol:Serves niche applications where hydroxyl functionality enables downstream derivatization for specialty fragrance synthesis.
Acetyl isovaleryl acetate sits at the top of the volume ranking, with acetyl isovaleryl ester climbing the fastest.
Application:
Application segments stratify by margin structure, with flavors and fragrances commanding premium pricing against commoditized agricultural chemical offtake.
- Flavors:Clean-label formulation mandates compress acceptable feedstock lists, forcing producers to requalify supply chains for bio-derived precursors. California and Pacific Northwest food technology clusters drive carbon accounting requirements that favor fermentation-based acetyl isovaleryl procurement.
- Fragrances:REACH authorization requirements tighten purity thresholds for derivatives entering European cosmetic supply chains. ECHA's guidance on respiratory sensitizers forces capital expenditure on containment systems that smaller producers cannot absorb.
- Pharmaceuticals:This segment remains comparatively mature with stable demand for high-purity grades meeting pharmacopeial specifications.
- Agricultural Chemicals:Acetyl isovaleryl chloride applications in crop protection chemistry represent underexploited volume pools beyond core fragrance and flavor segments.
Fragrances generate the highest margin per kilogram, though agricultural chemicals are gaining share fastest as crop protection chemistry diversifies its intermediate slate.
End User:
End user concentration determines contract manufacturing relationships, with flavor and fragrance houses consolidating procurement around fewer compliant suppliers.
- Food Industry:Direct contracting between clean-label manufacturers and fermentation technology developers displaces traditional chemical distributor intermediaries. India's FSSAI pathway expansion creates first-mover advantage for suppliers establishing local technical dossiers.
- Cosmetic Industry:Fine fragrance houses prioritize suppliers with pre-submitted full substance dossiers under REACH. EU Green Deal biopreference policies and carbon border adjustment mechanisms create preferential market access for fermentation-derived inputs.
- Chemical Manufacturers:Contract acetylation capability concentrates among limited North American specialty chemical producers.
- Pharmaceutical Companies:Demand stable, high-purity grades with full analytical documentation for active pharmaceutical ingredient synthesis.
The food industry anchors volume demand, while the cosmetic industry expands most quickly on biopreference policy tailwinds.
Form:
Physical form selection traces to downstream processing requirements and storage stability considerations across climatic zones.
- Liquid:Dominates commercial handling for flavor and fragrance compounding due to ease of metered addition and homogeneous blending. German and Swiss engineering firms install modular flow chemistry units that favor liquid feedstock integration.
- Solution:Preferred where precise concentration standardization simplifies formulation mathematics for cosmetic manufacturers.
- Solid:Enables stabilized shipment to regions with limited cold chain infrastructure.
- Powder:Serves niche applications requiring extended shelf life or controlled release characteristics.
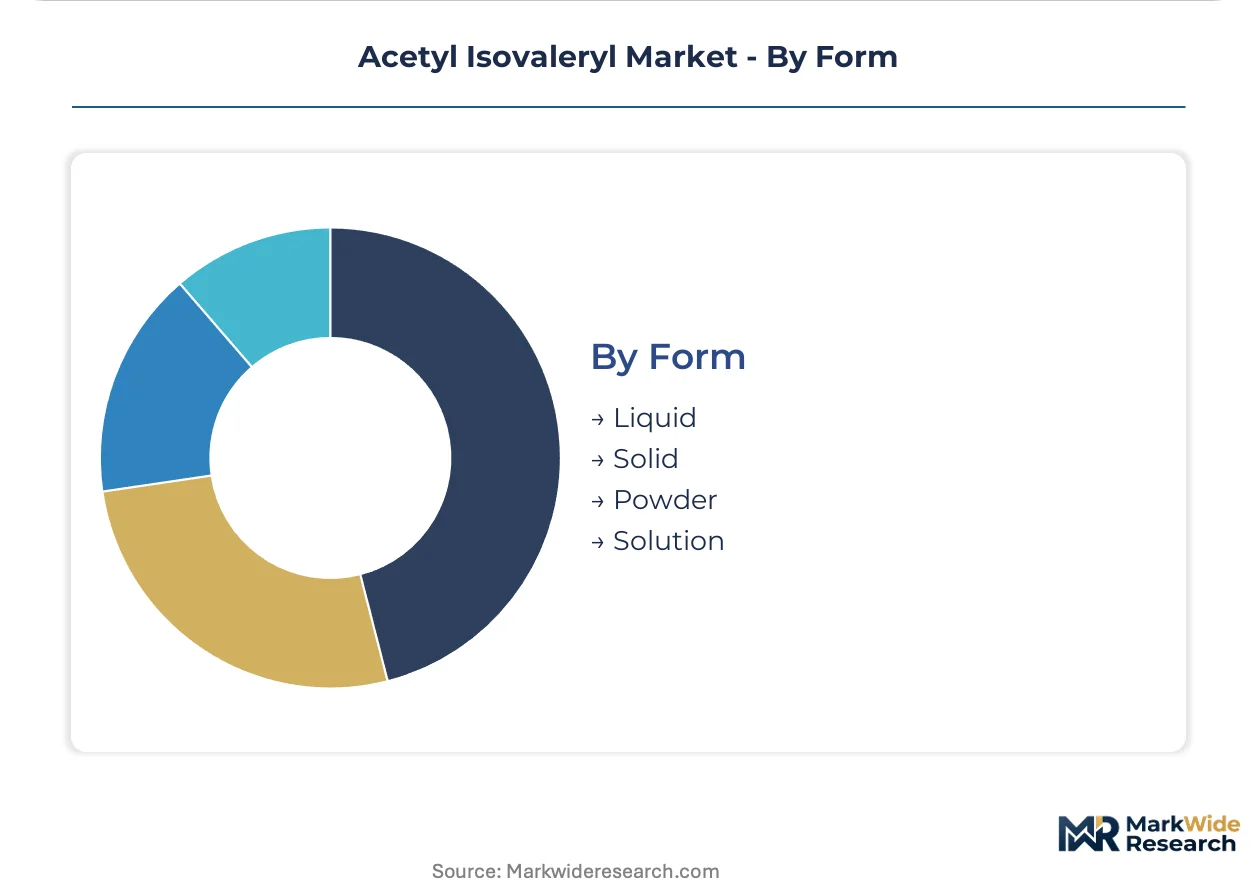
Liquid form maintains the steepest expansion trajectory on continuous flow reactor adoption, with solution form gaining share fastest among precision formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor the acetyl isovaleryl supply base, with flavor and fragrance manufacturers scaling captive production for regional cosmetic brands. Regulatory divergence across major economies is fragmenting compliance pathways, forcing producers to maintain parallel dossier portfolios for multi-regional market access.
China
Domestic flavor houses in Jiangsu and Zhejiang are expanding acetyl isovaleryl acetate output to supply regional cosmetic brand supply chains. NMPA registration requirements for fragrance intermediates are tightening purity documentation standards for imported derivatives. Shanghai and Hangzhou chemical parks concentrate the bulk of fermentation-derived precursor development.
United States
California and Pacific Northwest food technology clusters drive carbon accounting requirements that favor bio-derived acetyl isovaleryl procurement. EPA VOC emission thresholds for fragrance manufacturing are forcing capital expenditure on containment systems. New Jersey and Pennsylvania host the principal contract acetylation capacity serving North American flavor houses.
Germany
Fine fragrance houses in the Cologne-Düsseldorf corridor accelerate substitution timelines toward REACH-compliant acetyl isovaleryl derivatives. ECHA's updated guidance on respiratory sensitizers is filtering out suppliers without full substance dossiers. BASF and Bayer legacy chemical infrastructure in Ludwigshafen and Leverkusen supports high-purity intermediate production.
France
Grasse-based perfume manufacturers prioritize fermentation-derived acetyl isovaleryl esters for novel scent molecules with improved biodegradability profiles. EU Green Deal biopreference policies and carbon border adjustment mechanisms create preferential market access for bio-based inputs. ANSM oversight of cosmetic ingredient safety is elevating analytical documentation requirements.
India
Maharashtra and Gujarat chemical zones are emerging as alternative production sites for acetyl isovaleryl derivatives targeting export markets. FSSAI expansion of approved flavorant lists creates first-mover advantage for suppliers establishing local technical dossiers. Mumbai and Ahmedabad house the primary analytical laboratories capable of chiral separation certification for fragrance-grade materials.
Acetyl Isovaleryl Market Competitive Environment
Capacity expansion dominates the current landscape as fermentation technology developers scale bio-derived precursor output to meet clean-label procurement mandates. The vendor base stratifies between petrochemical acetylation specialists and synthetic biology startups, with mid-scale contract manufacturers occupying the contested middle tier. Three archetypes define competitive positioning: legacy chemical distributors with deep inventory, fermentation technology developers with direct flavor house relationships, and specialty ester producers competing on molecular specificity. Geographic expansion and technology licensing represent the dominant competitive moves, with players seeking to bypass traditional distributor intermediaries through direct offtake agreements.
Among North American specialty chemical suppliers, Penta Manufacturing Company and Vigon International exemplify the inventory-heavy distributor archetype, maintaining broad aroma chemical precursor availability for compounding houses. Synerzine occupies a position within the molecular specificity tier, competing on ester production precision rather than volume scale. Chinese producers including Fenghen Group Co, Ltd and Hisunny Chemical anchor the cost-optimized manufacturing segment, leveraging domestic isovaleric acid supply chains for regional market coverage. TCI America and BOC Sciences represent the research-grade supply tier, serving pharmaceutical and analytical applications with documented purity certifications.
| Leading Market Players |
|---|
| Penta Manufacturing Company |
| Wholechem |
| Vigon International |
| Synerzine |
| TCI America |
| Fenghen Group Co, Ltd |
| Parchem |
| Hisunny Chemical |
| BOC Sciences |
| Others |
Value Chain & Pricing Dynamics
Food-grade versus industrial-grade certification divergence splits the acetyl isovaleryl market into parallel pricing architectures, with FDA FEMA GRAS compliance commanding substantial premia over EPA TSCA-grade material and reshaping procurement patterns across flavor houses and fragrance compounders.
Pricing Analysis
Input-cost pass-through from isovaleric acid volatility governs contract structures, with petrochemical cracking margins and bio-fermentation batch yields transmitting directly to acetyl isovaleryl acetate quotations. Three-tier pricing structure across food-grade, fragrance-grade, and industrial-grade levels reflects certification burden differentials, with REACH dossier completeness emerging as the decisive price discriminator. Cost compression in standard-grade esters is intensifying because Chinese captive producers in Jiangsu and Zhejiang are expanding regional output. Agricultural chemical buyers exhibit highest price sensitivity, while French and German fine fragrance houses absorb premia for pre-submitted full substance dossiers.
Supply Chain Analysis
Reverse-logistics flows for fragrance-grade returns and requalification batches concentrate analytical burden in Mumbai and Ahmedabad laboratories capable of chiral separation certification. Supply concentrates in China, Germany, and India, with Jiangsu and Zhejiang provinces anchoring fermentation-derived precursor development. Raw material dependencies center on isovaleric acid feedstocks, acetic anhydride acetylation agents, and specialized yeast strains for bio-routes. Single-source vulnerability pervades North American contract acetylation capacity concentrated in New Jersey and Pennsylvania. Distribution runs through aroma chemical distributors and direct offtake agreements with synthetic biology developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in fermentation-derived acetyl isovaleryl esters as EU Green Deal biopreference policies and carbon border adjustment mechanisms tilt procurement toward bio-based inputs with traceable supply chains.
For Market Incumbents: To counter synthetic biology startup disruption in clean-label procurement channels, Penta Manufacturing Company and Vigon International archetypes should deepen backward integration into isovaleric acid fermentation capacity and secure multi-year offtake agreements with California and Pacific Northwest food technology clusters before channel displacement accelerates. For New Entrants and Emerging Players: Fermentation technology developers with direct flavor house relationships represent the most penetrable white-space target, with India's FSSAI pathway expansion offering first-mover advantage for suppliers establishing local technical dossiers in Maharashtra and Gujarat chemical zones ahead of incumbent REACH dossier replication. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical chemist scarcity concentrates expertise among retiring specialists in European and Japanese laboratories. Five-to-ten-year viability favors mid-scale contract manufacturers with modular flow chemistry capability and pre-submitted ECHA dossiers. Watch for EPA VOC threshold enforcement intensity as inflection signal for containment system capex absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive isovaleric acid supply secures margin control against petrochemical feedstock volatility. |
| REACH Dossier Pre-submission | Full substance documentation filters competitors from ECHA-authorized fragrance intermediate supply chains. |
| Modular Flow Chemistry Adoption | Continuous acetylation reactor installation compresses cycle times for flavor house lot-to-lot consistency demands. |
| Direct Offtake Agreement Structuring | Bypassing aroma chemical distributors captures margin from California clean-label manufacturer carbon accounting requirements. |
| FSSAI Technical Dossier Establishment | Local regulatory approval in Maharashtra and Gujarat zones preempts incumbent expansion into India's expanding flavorant lists. |
Study Parameters
Direct dialogue with flavor house procurement directors, fragrance compounder R&D leads, fermentation technology developers, contract acetylation plant managers, and ECHA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, SEC 10-K filings of listed specialty chemical producers, ACC and Cefic industry reports, and NMPA registration databases. Bottom-up and top-down triangulation cross-checked volume estimates against capacity announcements and offtake contract disclosures.
Bottom-up modeling segmented demand across product type, application, end user, and physical form dimensions, with additional stratification by certification tier and regional regulatory cluster. Top-down constraints applied macroeconomic indicators and end-use industry growth trajectories across the analysis window. CAGRs derived from weighted average of historical trajectory analysis and forward-looking capacity-expansion schedules, with fermentation yield improvement curves and REACH authorization timelines as chemical-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA VOC enforcement intensity, EU carbon border adjustment mechanism implementation pace, and bio-fermentation yield breakthrough timelines. Practitioners should monitor ECHA respiratory sensitizer guidance updates, FSSAI approved flavorant list expansions, and Chinese dual carbon policy acceleration for early signals of demand bifurcation between petrochemical and fermentation-derived supply chains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market