
 Europe Wireless Electric Vehicle Charging Market | 2026-2036
Europe Wireless Electric Vehicle Charging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wireless Electric Vehicle Charging Market Analytics
The gap between premium magnetic resonance systems and commodity inductive hardware is broadening as fleet operators demand higher efficiency while residential users prioritize cost. WiTricity Corporation leverages its patent portfolio to dominate high-power commercial installations. Continental AG sustains engineering partnerships with German automakers to anchor its position in integrated vehicle-side receivers. Robert Bosch GmbH competes through manufacturing scale across its European component plants.
Wireless electric vehicle charging transfers electrical energy across an air gap via electromagnetic induction or magnetic resonance coupling, typically operating at frequencies between 20–100 kHz with coil-to-coil efficiencies reaching 90–95% in commercial systems; its primary purpose is eliminating conductive cable connections for electric vehicles in high-frequency, high-convenience environments. Magnetic resonance technology leads in margin pools due to its tolerance for coil misalignment, while fleet operators represent the fastest-growing end-user category as logistics companies electrify depot operations. Residential installations remain mature with slower upgrade cycles, whereas highway charging stations attract infrastructure capital from public-private partnerships.
The EU Green Deal and F-Gas Regulation shape product standards by mandating efficiency thresholds and restricting fluorinated greenhouse gases in charging component cooling systems. EMA and national type-approval frameworks across Germany, France, and the Netherlands govern electromagnetic compatibility and safety certification for grid-connected equipment. Stakeholders must monitor how the EU AI Act's risk classification protocols will apply to autonomous parking alignment systems that integrate with wireless charging pads.
Market Dynamics
The EU Green Deal's 2035 internal combustion engine phase-out is redirecting automotive capital toward contactless charging infrastructure, compressing fleet electrification timelines and forcing alignment between vehicle OEMs and pad-based inductive system suppliers.
Growth Catalysts
- Fleet depot electrification:Logistics operators across Germany and Scandinavia are installing high-power inductive pads to eliminate cable handling during high-frequency charging cycles.
- EU Green Deal mandate:The 2035 ICE phase-out redirects OEM engineering budgets toward wireless receiver integration in next-generation vehicle platforms.
- Magnetic resonance maturation:Tolerance for coil misalignment up to 20 centimeters is expanding deployment scenarios beyond precision-parking applications.
Market Restraints
- Copper and ferrite supply concentration:Coil winding materials face price volatility due to concentrated mining and processing capacity in limited geographies.
- F-Gas Regulation cooling restrictions:The EU's fluorinated gas phase-down limits thermal management options for high-power transmitter electronics.
- Conductive cable substitution:Fast DC charging stations below 150 kW retain cost and efficiency advantages for intermittent users.
Strategic Opportunities
- Polish and Romanian freight corridors:East-west highway routes lack charging density, creating white space for dynamic wireless charging pilot installations.
- EU AI Act alignment systems:Autonomous parking integration with charging pads creates regulatory-compliant automation pathways for premium vehicle segments.
- Vehicle-to-grid convergence:Bidirectional inductive systems enable fleet operators to monetize stationary battery capacity through grid services.
Industry Challenges
- Electromagnetic compatibility certification:EMA type-approval timelines for grid-connected equipment extend 18-24 months, delaying product launches.
- Power electronics talent scarcity:RF engineering and magnetic design expertise concentrates among legacy industrial motor suppliers, constraining supplier scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wireless Electric Vehicle Charging Market |
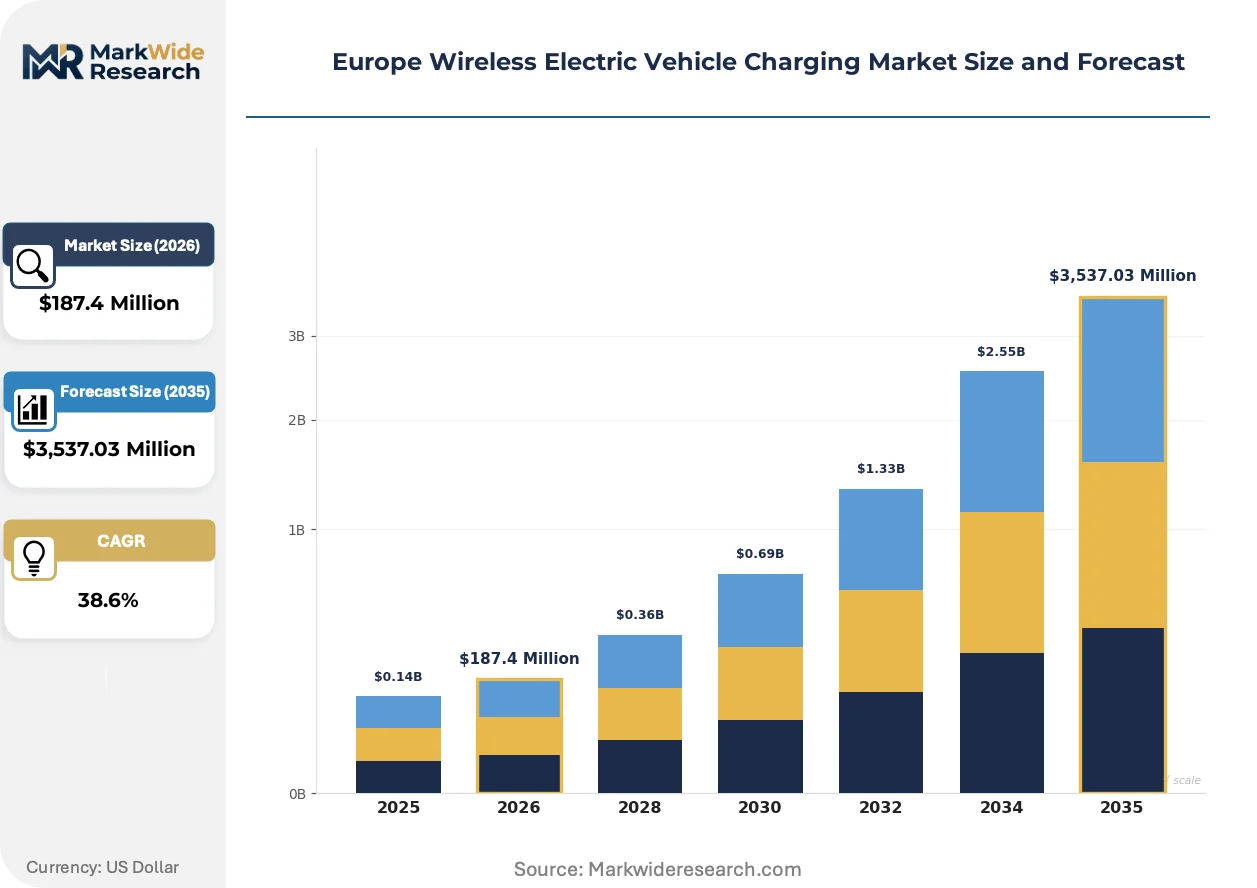
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,537.03 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Resonance, Inductive Charging, Capacitive Charging, Solar-Powered Systems End User: Private Users, Fleet Operators, Public Transport, Ride-Hailing Services Installation: Residential, Commercial, Urban Infrastructure, Highway Charging Stations Charging Speed: Low Power, Medium Power, High Power, Ultra-Fast |
| Companies Covered | WiTricity Corporation, Qualcomm Technologies, Continental AG, Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Toshiba Corporation, ZenS B.V, NXP Semiconductors, Momentum Dynamics Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wireless Electric Vehicle Charging Market Evolving Landscape
Wireless charging architectures are pivoting from static depot installations toward dynamic roadway integration, forcing component suppliers to re-engineer for durability under vibration and environmental stress.
Dynamic inductive power transfer coils embedded in roadway surfaces are rewriting highway infrastructure economics. German and Dutch transport authorities are piloting kilometer-scale electrified lanes for heavy freight corridors. This technology is compressing the total cost of ownership gap between battery-electric and diesel trucks for fixed-route logistics.
The EU AI Act's risk classification protocols for autonomous systems are reshaping parking alignment software requirements. Vehicle-side positioning algorithms must now demonstrate fail-safe operation before receiving CE marking for grid connection. German KBA and Dutch national regulators are coordinating pilot approvals for integrated charging-parking automation systems.
Fleet procurement departments are unbundling hardware ownership from energy service contracts. Logistics operators in Belgium and the Netherlands now prefer power-purchase agreements where charging infrastructure vendors retain asset ownership and monetize through per-kilowatt-hour delivery fees. This shift transfers capex burden to suppliers while accelerating deployment velocity among capital-constrained mid-size fleets.
Europe Wireless Electric Vehicle Charging Market Segmentation
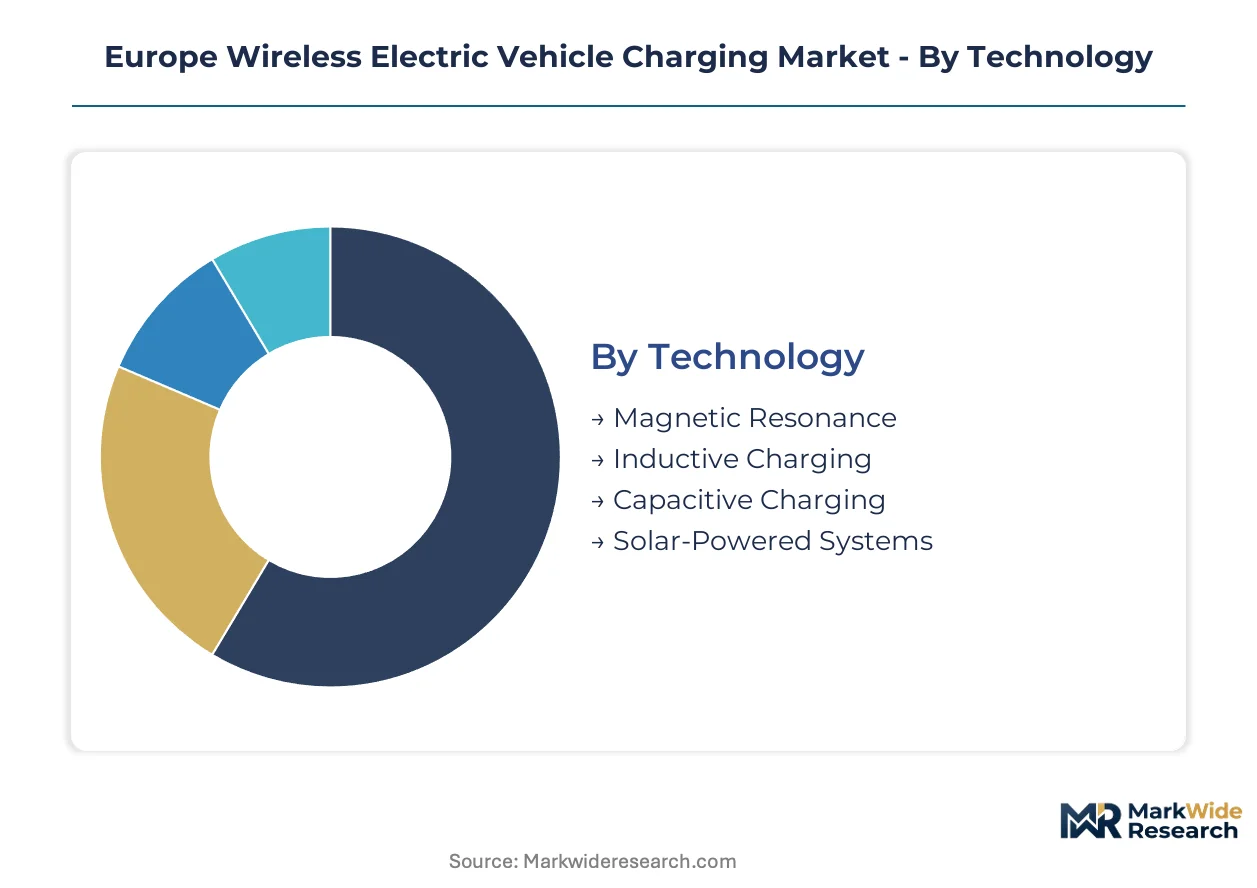
Wireless EV charging technology fragments across multiple decision axes. Fleet procurement teams prioritize power throughput and depot integration. Residential buyers weigh installation simplicity against vehicle compatibility.
Technology:
Engineering teams select coupling mechanisms based on misalignment tolerance and thermal load requirements.
- Magnetic Resonance:Operates via resonant inductive coupling with 20-centimeter lateral tolerance between coils. German freight operators around Berlin and Munich specify this architecture for automated depot positioning where driver precision is unreliable.
- Inductive Charging:Traditional electromagnetic induction with tighter alignment requirements but simpler power electronics. Scandinavian residential installations favor this technology for cost-controlled home garage retrofits where parking precision is driver-controlled.
- Capacitive Charging:Electric field coupling through plate electrodes rather than coils. Early-stage pilots in Dutch urban infrastructure test this approach for reduced electromagnetic interference in dense residential zones.
- Solar-Powered Systems:Photovoltaic integration with inductive or resonant transmitters. Belgian logistics yards experiment with off-grid depot charging for remote trailer parking areas lacking grid capacity.
Magnetic resonance leads on scale; capacitive charging leads on momentum.
End User:
Procurement authority and utilization intensity separate customer economics.
- Fleet Operators:Logistics companies with centralized depot operations and predictable duty cycles. German heavy freight electrification programs concentrate procurement volume here, with power-purchase agreements replacing direct hardware ownership.
- Public Transport:Municipal bus and tram operators with fixed-route, high-frequency charging needs. Dutch regional transit authorities pilot dynamic roadway integration for opportunity charging along dedicated lanes.
- Private Users:Individual vehicle owners with residential or workplace parking. Slower upgrade cycles characterize this segment as conductive cable charging retains cost advantage for intermittent use patterns.
- Ride-Hailing Services:Platform-coordinated vehicle fleets with high daily mileage and downtime minimization requirements. Urban infrastructure vendors in Paris and Madrid target this segment for curbside fast-charging pad networks.
Fleet operators dominate procurement volume; ride-hailing services show steepest expansion trajectory.
Installation:
Site control and grid access determine deployment feasibility and regulatory pathway.
- Commercial:Corporate campuses, retail parking, and fleet depots with dedicated electrical infrastructure. Belgian logistics parks anchor early high-power deployments due to consolidated land ownership and simplified permitting.
- Highway Charging Stations:Corridor infrastructure for intercity travel and long-haul freight. Polish and Romanian east-west freight routes present white space for dynamic charging pilot installations with EU infrastructure funding.
- Residential:Single-family and multi-unit dwelling installations with lower power requirements. German KBA type-approval timelines for grid-connected residential equipment extend product launch cycles.
- Urban Infrastructure:Curbside and municipal parking with shared access models. French and Dutch regulators coordinate electromagnetic compatibility certification for street-embedded transmitter pads.
Commercial installations lead on scale; highway charging stations lead on momentum.
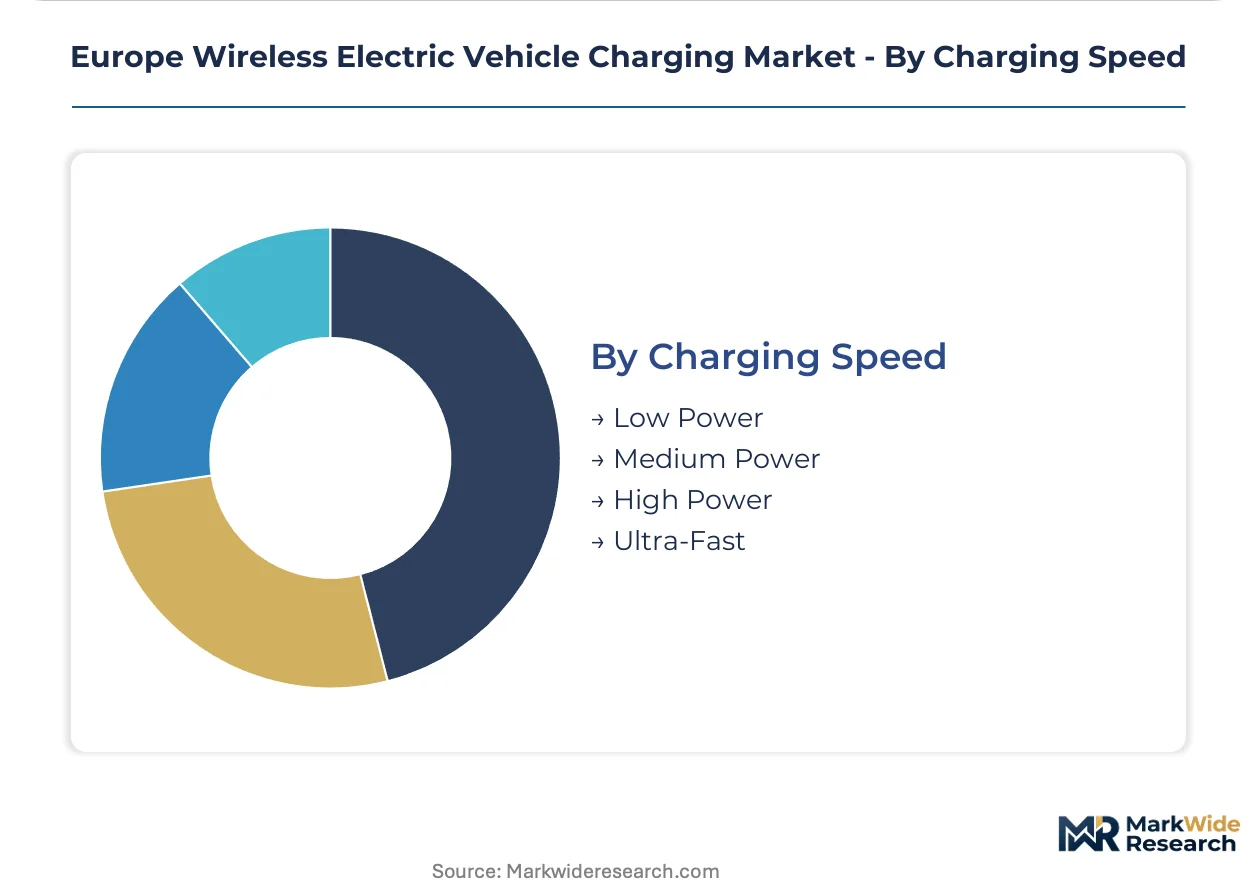
Charging Speed:
Power level selection trades equipment cost against vehicle downtime and battery stress.
- High Power:50–150 kW transmission for fleet depot opportunity charging. German automotive OEM partnerships specify this tier for integrated receiver platforms in next-generation commercial vehicles.
- Ultra-Fast:Above 150 kW for dynamic roadway and heavy freight applications. Dutch transport authority pilots on freight corridors test this architecture for battery-electric truck total cost of ownership parity with diesel.
- Medium Power:11–50 kW for workplace and extended-dwell parking. Scandinavian office campus installations favor this tier for employee vehicle charging during standard work hours.
- Low Power:Below 11 kW for overnight residential and long-dwell scenarios. Cost-sensitive private users in Southern Europe select this tier despite slower charge rates.
High power leads on scale; ultra-fast leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates wireless EV charging deployment more heavily than France, though Dutch infrastructure pilots are advancing faster on dynamic roadway integration.
Germany
Fleet depot electrification and OEM receiver integration dominate procurement. The KBA governs electromagnetic compatibility type-approval timelines extending 18-24 months for grid-connected equipment. Berlin and Munich anchor dense pilot networks where automotive partnerships with component suppliers test high-power inductive pads.
Netherlands
Dynamic roadway pilots for heavy freight corridors and municipal transit opportunity charging drive investment. Dutch national regulators coordinate with German KBA on integrated charging-parking automation approvals. The Eindhoven region hosts curbside fast-charging pad networks targeting ride-hailing services.
Belgium
Logistics operators prefer power-purchase agreements transferring hardware ownership to vendors. The EU Green Deal's 2035 ICE phase-out redirects capital toward contactless depot infrastructure. Consolidated land ownership in Antwerp-Brussels logistics parks simplifies permitting for high-power commercial installations.
Poland
East-west freight routes present white space for dynamic charging pilots with EU infrastructure funding. The F-Gas Regulation restricts thermal management options for transmitter electronics in high-power systems. Warsaw-Katowice corridor planning attracts public-private partnership capital for highway charging density.
Sweden
Scandinavian residential retrofits favor cost-controlled inductive systems where parking precision is driver-controlled. National efficiency thresholds under EU product standards shape equipment selection. Stockholm's municipal procurement programs test solar-powered off-grid depot charging for remote trailer parking.
Europe Wireless Electric Vehicle Charging Market Competitive Landscape
Top-tier vendors anchor integrated vehicle-side receiver partnerships, while mid-tier component suppliers compete on manufacturing scale and patent licensing. The market structure concentrates around three strategic archetypes: patent-holding technology licensors, tier-1 automotive suppliers with OEM relationships, and power electronics specialists with RF engineering depth. Dominant competitive moves include strategic partnerships for depot network deployment and backward integration into coil winding materials.
Among patent-centric developers, WiTricity Corporation occupies a position exemplifying high-power commercial installation focus, while Qualcomm Technologies represents the semiconductor-integrated approach to resonant coupling systems. Continental AG anchors the tier-1 automotive supplier archetype with its GmbH structure indicating German engineering partnership traditions. These three entities collectively illustrate the competitive tension between intellectual property monetization and manufacturing scale advantages.
| Leading Market Players |
|---|
| WiTricity Corporation |
| Qualcomm Technologies |
| Continental AG |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Toshiba Corporation |
| ZenS B.V |
| NXP Semiconductors |
| Momentum Dynamics Corporation |
| Others |
Value Network & Pricing Analysis
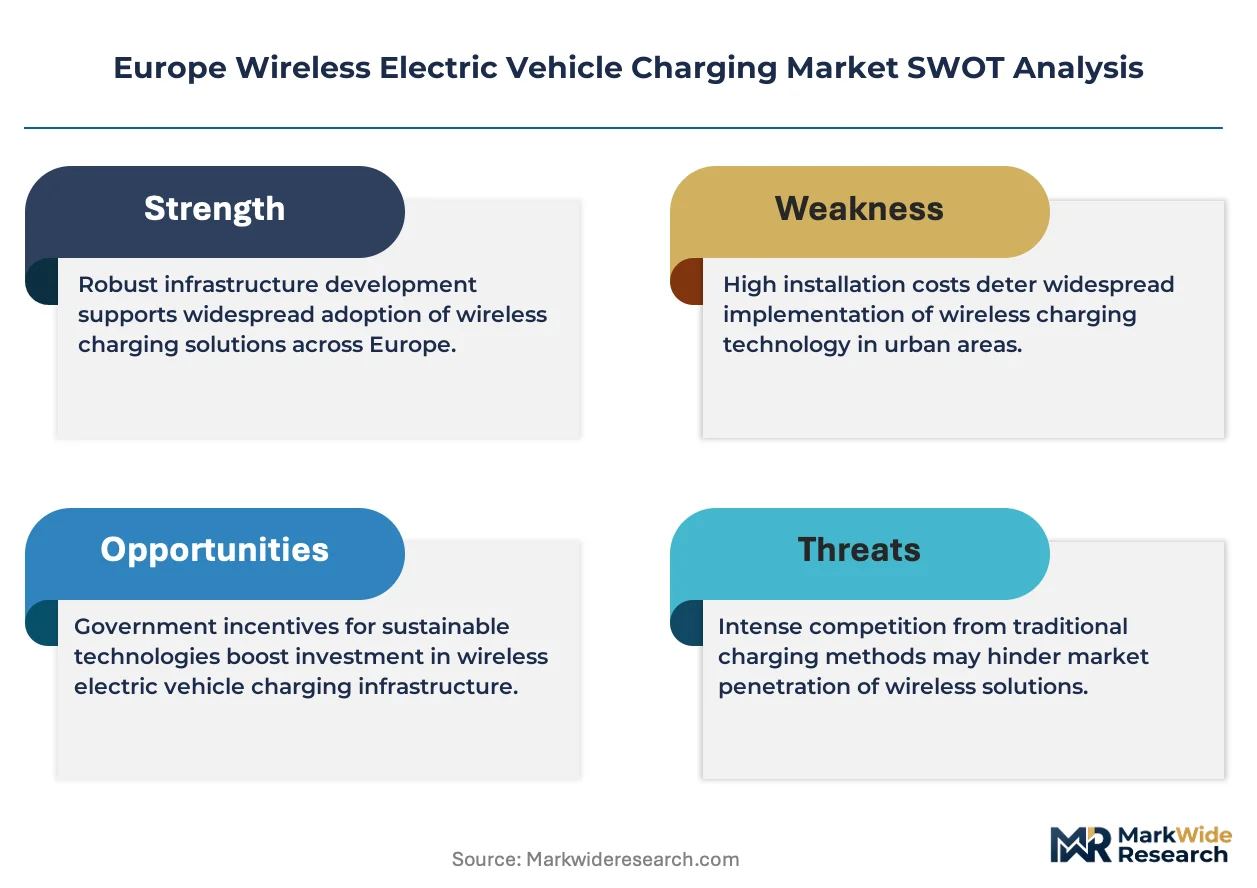
The EU Green Deal's 2035 ICE phase-out gates qualified supply and premium-tier pricing access by mandating efficiency thresholds that only magnetic resonance architectures satisfy, forcing fleet operators to pay certification premiums while commodity inductive hardware faces cost compression from unqualified Asian component imports.
Pricing Analysis
Capacity additions in Chinese power electronics manufacturing are reshaping price floors for inductive charging hardware below 50 kW, compressing margins on entry-tier residential systems. Three-tier pricing structure across premium magnetic resonance, standard inductive, and economy imported hardware segments differentiates on CE marking compliance and coil alignment tolerance. Cost compression in the economy tier intensifies because unbranded Asian suppliers bypass KBA type-approval timelines. Fleet operators with power-purchase agreements show least price sensitivity due to energy-service contract bundling, while Southern European private users exhibit highest price sensitivity.
Supply Chain Analysis
RF engineering talent scarcity in German and Dutch manufacturing geographies constrains coil winding and power electronics assembly scaling. Germany, China, and Japan anchor supply for ferrite cores, copper litz wire, and silicon carbide semiconductors. Raw material dependencies draw from Chilean copper concentrate, Chinese rare earth processing, and Japanese ferrite sintering capacity. Single-source vulnerability in Chinese rare earth magnet supply creates exposure to export restriction shocks. Distribution runs through Tier 1 automotive supplier networks with integrated vehicle-side receiver bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on magnetic resonance premium-tier capture as fleet procurement shifts from hardware ownership to energy-service contracts, transferring capex burden while locking in long-term per-kilowatt-hour premiums.
For Market Incumbents: Deepen backward integration into ferrite core and copper litz wire supply to defend against Chinese component price volatility and secure KBA type-approval pipeline priority. Anchor OEM receiver partnerships through exclusive engineering collaboration on next-generation commercial vehicle platforms. Patent licensing revenue from magnetic resonance architectures provides defensive moat against inductive hardware commoditization. For New Entrants and Emerging Players: Enter via Polish and Romanian highway corridor dynamic charging pilots where EU infrastructure funding covers deployment capex and incumbent presence remains thin. Target freight logistics operators with vehicle-to-grid enabled bidirectional systems as the most penetrable segment. Pursue power-purchase agreement structures that transfer hardware ownership risk to vendor balance sheets while capturing long-term energy delivery margins. For Investors and Strategic Acquirers: Roll-up economics work for power electronics specialists with RF engineering depth because patent-holding technology licensors face manufacturing scale constraints that favor acquisition over organic build. Five-to-ten year viability hinges on magnetic resonance architecture standardization displacing inductive hardware in fleet procurement. Watch German KBA and Dutch national regulator coordination on autonomous parking alignment CE marking as inflection signal for premium-tier automation integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Materials | Captive ferrite and copper supply secures margin against Chinese raw material price volatility. |
| OEM Receiver Platform Partnership | Continental AG and Robert Bosch GmbH anchor vehicle-side integration through German engineering collaboration. |
| Dynamic Roadway Pilot Deployment | Dutch transport authority freight corridor tests compress battery-electric truck total cost of ownership gap with diesel. |
| Power-Purchase Agreement Structuring | Belgian logistics operators transfer hardware capex to vendors while accelerating depot electrification velocity. |
| Autonomous Alignment Certification | EU AI Act risk classification protocols reshape parking software requirements for CE marking compliance. |
Research Methodology
Bottom-up fleet operator and residential user modeling reconciled against top-down component supplier capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet depot operations managers, and KBA regulatory affairs specialists combined with secondary validation from EU Green Deal policy filings, EMA electromagnetic compatibility databases, German automotive production statistics, and F-Gas Regulation implementation reports. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of magnetic resonance versus inductive technology deployment rates, fleet electrification capex cycles, and residential upgrade intervals informed projection frameworks across the analysis window. Segmentation dimensions modeled include coupling mechanism technology, end-user procurement authority, installation site control, and charging speed tier. CAGRs derived from logistic diffusion curves fitted to fleet pilot expansion patterns and OEM platform integration timelines. Power electronics cost learning curves and copper price volatility scenarios shaped forecast sensitivity bands.
The model holds under continued EU Green Deal enforcement and stable rare earth supply; deviation in Chinese export restrictions or F-Gas Regulation cooling system phase-down acceleration would shift deployment timelines and premium-tier pricing power. Forecasts reflect assumptions about KBA type-approval duration and magnetic resonance misalignment tolerance maturation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Latin America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Norway Electric Cars Market