
 Foldable Electric Vehicle Market | 2026-2036
Foldable Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Electric Vehicle Market Intelligence
The EU AI Act is broadening the cost-of-entry calculus for autonomous foldable vehicle platforms that rely on real-time navigation algorithms. Honda leverages its motorcycle manufacturing heritage to sustain foldable chassis engineering capabilities. Segway-Ninebot anchors the micro-mobility tier through intensive R&D in compact folding mechanisms. Xiaomi competes aggressively on consumer electronics integration, embedding smart connectivity into lightweight foldable frames.
Foldable electric vehicles combine collapsible frame architectures with battery-electric propulsion, typically achieving folded dimensions below one cubic meter through hinge-integrated battery packs and telescoping handlebars or seat posts. Their primary purpose is to eliminate parking scarcity constraints while preserving motorized range for urban and suburban mobility. Electric scooters dominate unit volume due to minimal folding complexity and lowest price points, though foldable trikes capture disproportionate margin pools through specialized accessibility and cargo applications. Lithium-polymer configurations are gaining ground where weight reduction determines folding portability, while lithium-ion sustains cost leadership in mass-market commuter segments.
FCC certification governs wireless connectivity modules in US-sold foldable vehicles, while NHTSA sets minimum lighting and braking standards for street-legal operation. China's MIIT enforces GB standards on battery safety and motor output that constrain import eligibility for foreign manufacturers. EMA's evolving framework for personal mobility device classification in Europe shapes clinical and insurance reimbursement pathways for mobility-impaired users. Stakeholders must monitor how divergent battery certification regimes across these jurisdictions fragment platform development roadmaps and force region-specific product variants.
Market Dynamics
Urban logistics operators in dense metropolitan zones are expanding procurement of compact foldable units to solve last-mile parking constraints, compressing deployment timelines and reshaping fleet composition strategies.
Growth Catalysts
- GB standards compliance:China's MIIT enforcement of battery safety and motor output standards is accelerating domestic manufacturer consolidation and raising import barriers for foreign platforms.
- Corporate commuter subsidies:German municipal programs and employer incentive schemes are accelerating adoption of foldable e-bikes and compact electric scooters among white-collar workforces.
- Lithium-polymer configurations:Weight reduction imperatives in premium portability segments are displacing heavier lithium-ion alternatives in specialized accessibility applications.
Market Restraints
- Cobalt and lithium price volatility:Raw material input costs for battery cathodes create margin compression for mass-market commuter segments unable to pass through pricing.
- Supply concentration in East Asian cell manufacturing:Dependence on concentrated cathode and cell production geographies exposes procurement to geopolitical disruption and logistics bottlenecks.
- F-Gas Regulation thermal management constraints:EU restrictions on refrigerants in battery cooling systems limit thermal architecture options and extend product development cycles.
Strategic Opportunities
- India's urban micromobility gap:Underpenetrated last-mile connectivity in tier-2 and tier-3 cities creates whitespace for lightweight foldable scooter deployment.
- AI Act autonomous navigation:EU regulatory frameworks for real-time algorithmic decision-making are creating compliance-driven demand for certified autonomous foldable platforms.
- Direct-to-fleet subscription channels:Logistics operators are bypassing retail distribution entirely, creating recurring revenue pools for manufacturers with captive financing capabilities.
Industry Challenges
- Battery certification timeline fragmentation:Divergent UN 38.3, GB, and UL testing regimes force region-specific product variants and duplicate validation expenditure.
- Foldable hinge fatigue engineering:Specialized mechanical design talent for repetitive-load hinge systems remains scarce relative to conventional automotive chassis engineering pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Electric Vehicle Market |
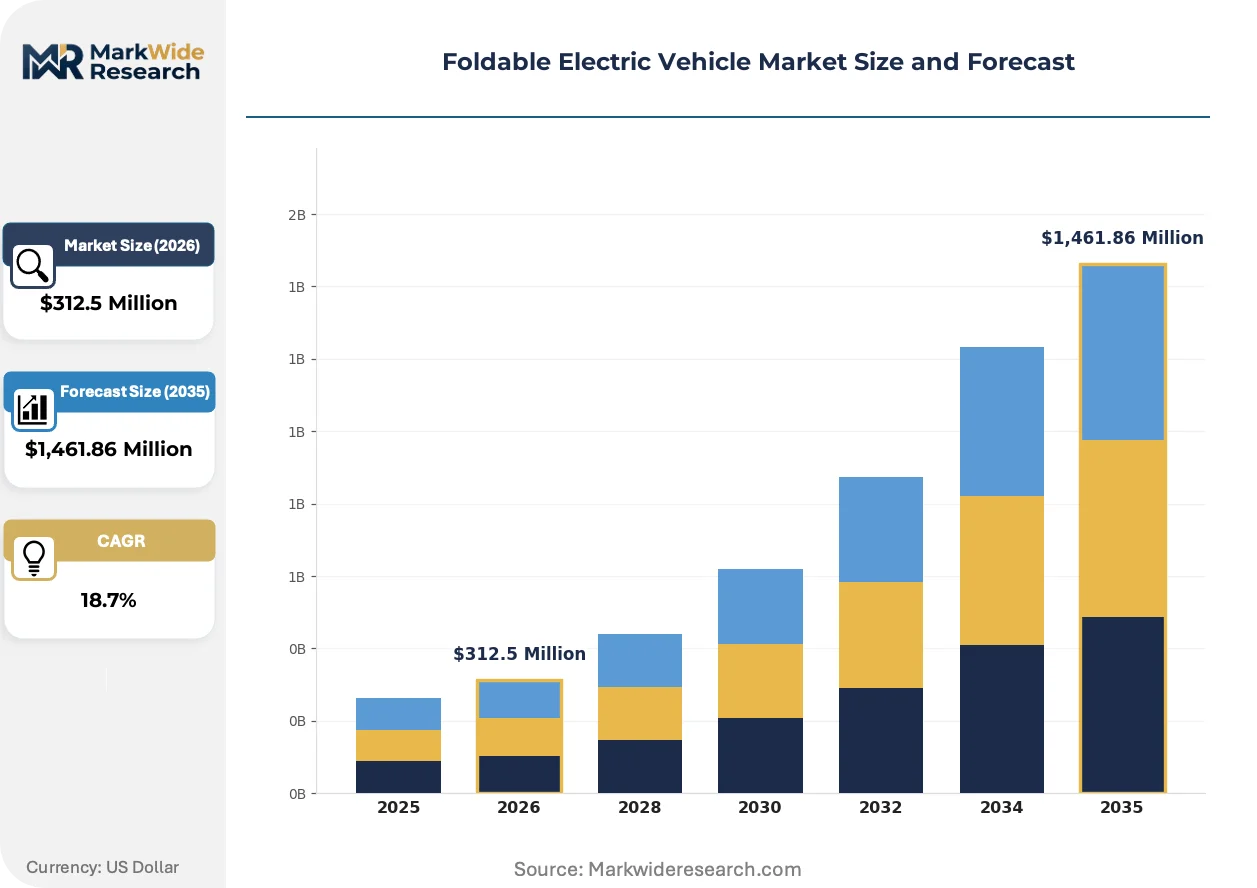
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Scooters, E-Bikes, Compact Cars, Foldable Trikes Technology: Lithium-Ion, Lithium-Polymer, Fuel Cell, Solar-Assisted End User: Commuters, Tourists, Urban Dwellers, Environmental Enthusiasts Distribution Channel: Online Retail, Dealerships, Specialty Stores, Direct Sales |
| Companies Covered | Honda, BYD, Xiaomi, XPeng, Rivian, Segway-Ninebot, Toyota, NIO, BMW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Electric Vehicle Market Strategic Shifts & Innovations
Real-time connectivity integration and thermal architecture miniaturization are compressing form factors while expanding functional capabilities across urban mobility segments.
Hinge-integrated battery pack architectures are electrifying chassis design by embedding cells directly into folding pivot points. Urban logistics fleets in Amsterdam and Singapore are adopting these configurations to maximize cargo density per vehicle. The technology is electrifying competitive positioning by enabling sub-15-kilogram folded weights that conventional frame-mounted battery placements cannot achieve.
The EU AI Act is reshaping autonomous navigation compliance for foldable vehicle platforms that deploy real-time pathfinding algorithms. Manufacturers must now document algorithmic transparency and risk classification before CE marking approval. Personal mobility device vendors targeting German and Dutch corporate commuter programs are accelerating investment in explainable AI stacks to satisfy conformity assessment requirements.
Fleet procurement departments are consolidating vendor relationships around outcome-based mobility-as-a-service contracts rather than unit purchase agreements. Logistics operators in Paris and Barcelona are unbundling hardware ownership from maintenance and software subscription services. This pattern is most visible in last-mile delivery verticals where parking scarcity and vehicle utilization rates dominate total cost of ownership calculations.
Foldable Electric Vehicle Market Segmentation
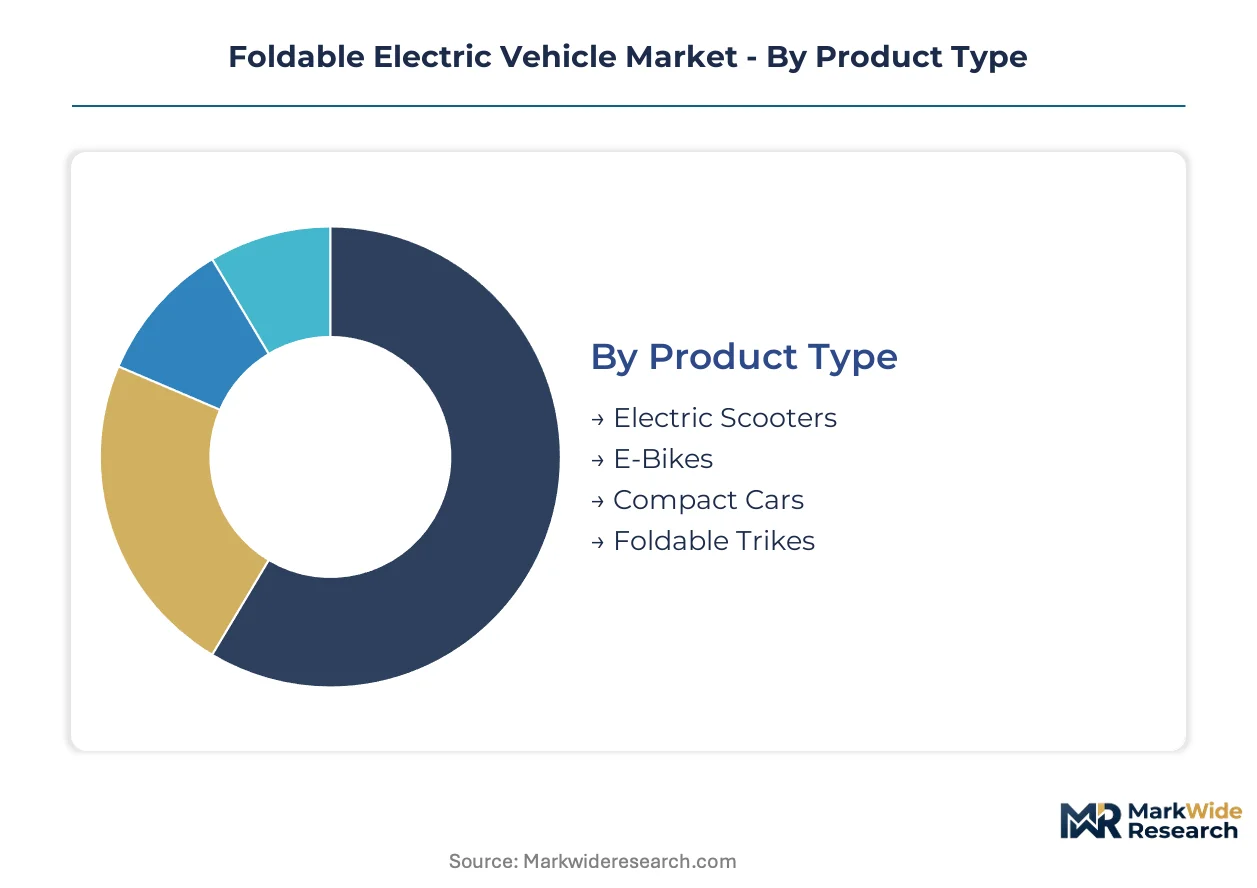
Segmentation in the foldable electric vehicle market exposes how portability requirements fracture across user mobility constraints, energy density trade-offs, and procurement channel preferences. Understanding these divisions clarifies why manufacturers cannot optimize a single platform for all buyers.
Product Type:
Purchase decisions hinge on parking severity and trip distance tolerance, with buyers accepting weight penalties only when cargo capacity or weather protection becomes non-negotiable.
- Electric Scooters:One-step folding mechanisms with stem-to-deck collapse achieve sub-12-kilogram portable weights. Last-mile logistics fleets in Amsterdam and Singapore standardize on these units for van-to-door handoff operations where elevator access is unreliable.
- E-Bikes:Hinge-integrated mid-frame pivots and removable battery packs preserve pedal efficiency while enabling trunk storage. German corporate commuter subsidies are accelerating procurement of foldable e-bikes among white-collar workforces in Munich and Hamburg.
- Compact Cars:Ultra-compact urban runabouts with collapsible cabin elements remain pre-commercial outside specialized demonstration projects.
- Foldable Trikes:Three-wheel stability architectures with seat-post battery integration serve accessibility and cargo applications where balance constraints exclude two-wheeled alternatives.
Volume sits with electric scooters; growth tilts toward foldable trikes.
Technology:
Energy-to-weight ratios determine folding feasibility, with premium portability segments accepting cell chemistry premiums that mass-market commuter categories cannot absorb.
- Lithium-Ion:Cylindrical and prismatic cell formats dominate cost-optimized commuter platforms through established supply chains and standardized BMS architectures. China's MIIT enforcement of GB standards on battery safety is accelerating domestic manufacturer consolidation around these proven configurations.
- Lithium-Polymer:Pouch cell geometries enable irregular form factors that conform to frame tubes and hinge junctions. Weight reduction imperatives in premium portability segments are displacing heavier lithium-ion alternatives in specialized German and Dutch accessibility applications.
- Fuel Cell:Hydrogen storage density challenges prevent meaningful folding integration at current stack miniaturization levels.
- Solar-Assisted:Photovoltaic panel integration on foldable surfaces remains experimental, with surface-area-to-energy-yield economics unfavorable for compact footprints.
Deployment concentrates in lithium-ion; lithium-polymer climbs the fastest.
End User:
User mobility constraints and environmental commitment intensity segment willingness-to-pay for foldable premium over conventional alternatives.
- Commuters:Time-predictable daily travelers prioritize reliability and weather-agnostic operation over absolute weight minimization. Paris and Barcelona logistics operators are unbundling hardware ownership from maintenance subscriptions for this cohort.
- Tourists:Seasonal demand with high sensitivity to rental availability and multilingual app interfaces drives resort-area deployment patterns.
- Urban Dwellers:Space-constrained apartment residents in dense metropolitan zones accept folding complexity for indoor storage security.
- Environmental Enthusiasts:Carbon-footprint-motivated early adopters over-index on lifecycle emissions data and repairability credentials.
Revenue pools center on commuters; environmental enthusiasts gain share fastest.
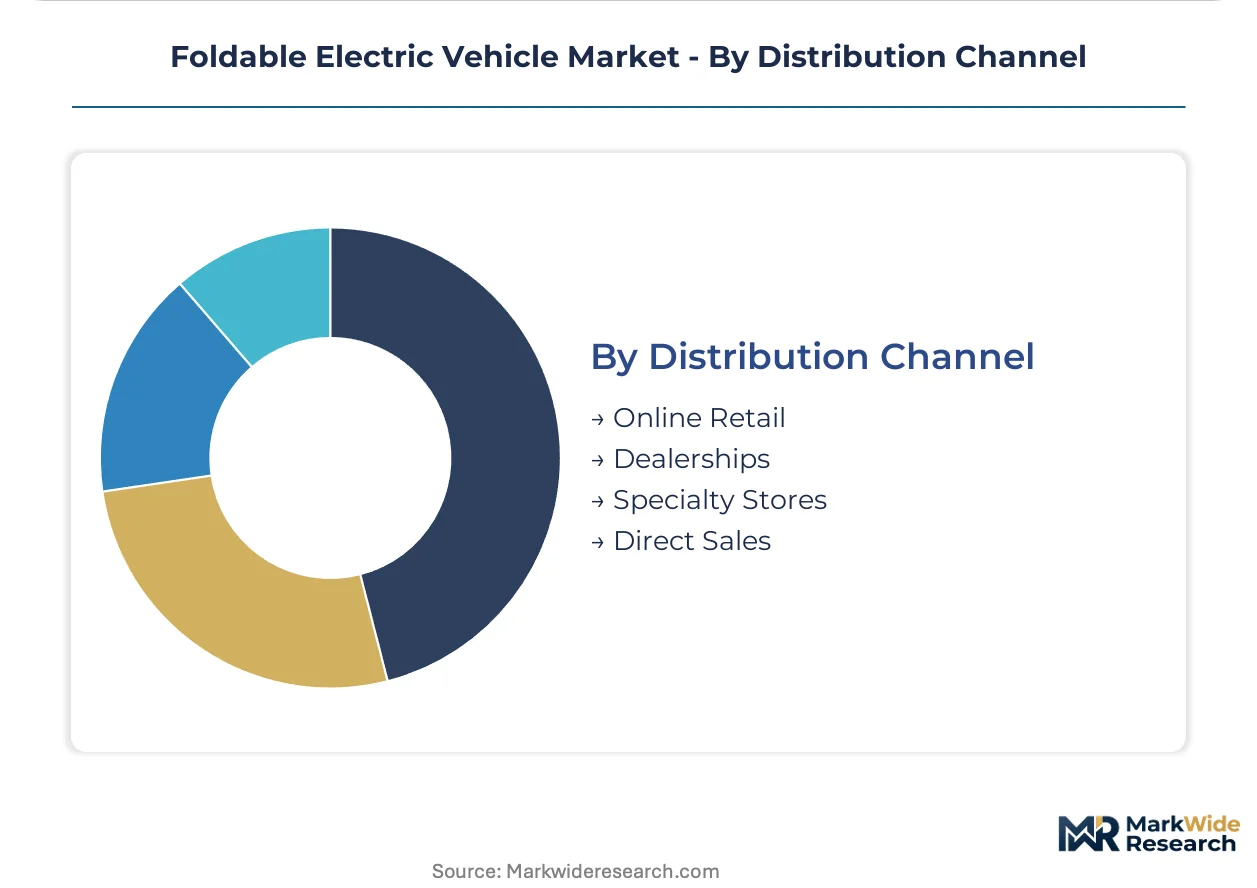
Distribution Channel:
Channel selection reflects buyer risk tolerance for after-sales support and immediacy requirements versus configuration flexibility.
- Online Retail:Direct-to-consumer platforms with video-assisted assembly support capture price-sensitive buyers comfortable with self-service maintenance. FCC certification documentation for US-bound wireless connectivity modules is standardizing in this channel.
- Dealerships:Test-ride availability and trade-in handling sustain relevance for higher-consideration e-bike and trike purchases.
- Specialty Stores:Urban mobility boutiques with in-house repair capabilities command loyalty among enthusiasts prioritizing component upgrade paths.
- Direct Sales:Fleet procurement departments are consolidating vendor relationships around outcome-based mobility-as-a-service contracts that bypass retail entirely.
Transaction volume flows through online retail; direct sales expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity clusters in Germany, where municipal bike-sharing programs and corporate commuter subsidies compress adoption timelines for foldable e-bikes and compact electric scooters.
Germany
KBA vehicle classification standards and employer commuter incentive schemes accelerate white-collar adoption in Munich and Hamburg. The EU F-Gas Regulation constrains battery thermal management architectures for platforms seeking CE marking approval. Stuttgart's automotive engineering cluster hosts multiple foldable chassis development programs targeting last-mile logistics integration.
China
Domestic manufacturer consolidation intensifies around GB standards compliance enforced by MIIT on battery safety and motor output specifications. Dual carbon goals at the national level redirect R&D investment toward lightweight foldable architectures. Shenzhen and Dongguan manufacturing corridors concentrate hinge-integrated battery pack production for export markets.
United States
NHTSA minimum lighting and braking standards shape street-legal product configurations for urban logistics fleets in New York and San Francisco. FCC certification requirements for wireless connectivity modules add compliance lead time for smart-enabled platforms. Los Angeles micromobility operators are piloting foldable scooter deployments for van-to-door handoff operations.
Netherlands
Amsterdam's municipal procurement specifications prioritize sub-15-kilogram folded weights for cargo density maximization in canal-zone logistics. EMA personal mobility device classification frameworks influence clinical reimbursement pathways for accessibility-oriented trike variants. Eindhoven's high-tech systems cluster supports thermal architecture miniaturization for compact battery enclosures.
Singapore
Land Transport Authority parking scarcity regulations drive fleet operator preference for one-step folding mechanisms in last-mile delivery verticals. Tropical climate humidity standards stress-test hinge fatigue engineering for daily collapse cycles. The Jurong innovation district hosts validation facilities for Southeast Asian market entry certification.
Foldable Electric Vehicle Market Key Industry Players
Chinese producers anchor the mass-manufacturing tier; Japanese and German specialists hold premium engineering positions. The vendor base stratifies across three tiers: diversified automotive conglomerates with captive foldable programs, pure-play micromobility fabricators, and consumer electronics integrators leveraging smart connectivity expertise. Consolidation pressure concentrates among mid-scale producers lacking vertical integration into battery cell supply. Strategic moves center on regional certification pre-positioning and direct-to-fleet subscription channel development.
Within the diversified automotive tier, Honda and Toyota occupy positions leveraging motorcycle and compact vehicle heritage. Among China-based fabricators, BYD and XPeng exemplify scale-driven platform development. Xiaomi represents the consumer electronics integration archetype, embedding connectivity modules into lightweight foldable frames. Segway-Ninebot sits within the pure-play micromobility specialist category, with Ninebot's Beijing origins and Segway's US acquisition history reflecting cross-border consolidation patterns in the space.
| Leading Market Players |
|---|
| Honda |
| BYD |
| Xiaomi |
| XPeng |
| Rivian |
| Segway-Ninebot |
| Toyota |
| NIO |
| BMW |
| Others |
Cost & Logistics Intelligence
German corporate commuter subsidies and Amsterdam municipal procurement specifications for sub-15-kilogram folded weights are compressing supplier margins and forcing manufacturers toward hinge-integrated battery architectures that reduce material intensity.
Pricing Analysis
Volume concentrates in mass-market electric scooters where lithium-ion cell standardization sustains cost leadership, while margin pools accumulate in foldable trikes and premium e-bikes where lithium-polymer configurations command portability premiums. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified platforms for Chinese domestic compliance from FCC-documented US-bound units and CE-marked European variants. Pricing pressure stems from cobalt and lithium cathode cost volatility that mass-market commuter segments cannot pass through to fleet buyers. Urban logistics operators show lowest price sensitivity due to total cost of ownership calculations dominated by parking scarcity and vehicle utilization rates, while individual consumers in online retail channels exhibit highest elasticity.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale buyer demand from Paris and Barcelona logistics operators, while online retail platforms serve fragmented individual consumers. Cell production concentrates in China, South Korea, and Japan, with Shenzhen and Dongguan corridors dominating hinge-integrated battery pack assembly. Raw material dependencies center on cobalt from the DRC, lithium from Chile and Australia, and rare earth elements for motor magnets. Single-source vulnerability in East Asian cathode manufacturing exposes procurement to geopolitical disruption and logistics bottlenecks at maritime chokepoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on backward integration into battery cell supply and captive control over hinge fatigue engineering talent pools.
For Market Incumbents: Extend certification pre-positioning across GB, FCC, and CE marking regimes to defend against mid-scale producers lacking duplicate validation expenditure capabilities. Deepen upstream control over lithium-polymer cell supply for premium portability segments where weight reduction determines folding feasibility. Lock in direct-to-fleet subscription contracts with Amsterdam and Singapore logistics operators before channel consolidation accelerates. For New Entrants and Emerging Players: Launch via direct-to-fleet subscription channels in India's tier-2 and tier-3 cities where last-mile connectivity remains underpenetrated and parking scarcity is acute. Target accessibility-oriented foldable trike applications where three-wheel stability architectures serve mobility-impaired users through EMA reimbursement pathways. Pursue white-label manufacturing partnerships with Shenzhen-based fabricators to compress GB standards compliance timelines. For Investors and Strategic Acquirers: The window for entry favors pure-play micromobility specialists with captive hinge engineering capabilities and established fleet subscription revenue streams. Long-term viability rests on consolidation of mid-scale producers lacking vertical integration into cell supply or regional certification breadth. Monitor EU AI Act autonomous navigation compliance investment as inflection indicator for platform differentiation potential.| Strategic Initiative | Industry Significance |
|---|---|
| Hinge-Integrated Battery Pack Development | Embedding cells into folding pivot points enables sub-15-kilogram weights for Amsterdam cargo density requirements. |
| GB Standards Compliance Investment | MIIT enforcement on battery safety and motor output accelerates domestic manufacturer consolidation and raises import barriers. |
| Direct-to-Fleet Subscription Launch | Outcome-based mobility-as-a-service contracts with Paris logistics operators bypass retail distribution entirely. |
| EU AI Act Navigation Certification | Explainable AI stack investment satisfies conformity assessment requirements for German and Dutch corporate commuter programs. |
| Lithium-Polymer Cell Backward Integration | In-house production of pouch cell geometries reduces dependence on East Asian supply concentration for premium portability segments. |
Research Approach
Multi-period observation of fleet procurement patterns, municipal subsidy program expansions, and battery certification timeline fragmentation anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers at urban logistics operators, and regulatory affairs specialists at personal mobility device vendors. Secondary validation drew from MIIT GB standards documentation, FCC equipment authorization databases, EMA personal mobility device classification frameworks, NHTSA lighting and braking compliance records, and customs trade data on lithium-ion cell imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting across product type, cell chemistry configuration, end-user mobility constraint, and distribution channel structure informed the analytical framework. CAGRs were derived from logistic diffusion modeling of adoption curves within commuter, tourist, urban dweller, and environmental enthusiast cohorts. Forecast inputs incorporated GB standards enforcement intensity, F-Gas Regulation thermal management constraint evolution, and fleet subscription contract penetration rates throughout the forecast period.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery miniaturization or hydrogen fuel cell stack folding integration would alter the outlook for weight-sensitive portability segments. Forecasts reflect assumptions on cobalt price stabilization, East Asian supply chain continuity, and EU regulatory harmonization progression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Scooter Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Latin America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Driveline Electric Vehicle Market