
 BEV Electric Drive Unit Market | 2026-2036
BEV Electric Drive Unit Market Size, Share, and Industry Trends Forecast 2026-2036
BEV Electric Drive Unit Market Insights
Modular unbundling of the electric motor from the inverter and gearbox is decoupling traditional powertrain procurement patterns. ZF Friedrichshafen leverages its integrated e-axle portfolio to anchor long-term supply agreements with European OEMs transitioning to dedicated EV platforms. BorgWarner competes through its specialized torque vectoring capabilities, while Nidec Corporation dominates high-volume permanent magnet motor production for Asian passenger car programs.
A BEV electric drive unit combines an electric motor, power electronics inverter, and reduction gearbox into a single propulsion system, typically operating at 400V or 800V DC bus voltage with peak power densities exceeding 3 kW per kilogram. Its primary purpose is to convert stored electrical energy into mechanical torque for vehicle propulsion while regenerating energy during deceleration. Integrated Drive Unit configurations lead volume shipments due to packaging efficiency and reduced assembly complexity, while Permanent Magnet Synchronous Motor technology occupies the dominant share of powertrain designs for passenger car applications. Induction Motor architectures sustain niche positions in performance-oriented and cost-optimized vehicle segments where rare-earth material exposure creates supply risk.
The EU's F-Gas Regulation and CE marking requirements shape thermal management system design and refrigerant selection across European supply chains, while China's GB standards and MIIT new-energy vehicle catalog rules dictate efficiency thresholds and local content requirements for domestic market access. The US EPA tailpipe standards and NHTSA safety protocols influence motor encapsulation and high-voltage isolation specifications for North American vehicle platforms. Stakeholders must monitor how 800V platform proliferation and silicon carbide inverter adoption reshape supplier qualification criteria and capital allocation across integrated versus modular architecture bets.
Market Dynamics
Platform consolidation around 800V architectures is compressing supplier qualification timelines and forcing capital reallocation toward silicon carbide inverter capacity. China's MIIT efficiency mandates and the EU's tightened CO2 standards are accelerating this voltage transition across passenger car programs.
Growth Catalysts
- China's MIIT Catalog Rules:Domestic new-energy vehicle efficiency thresholds are compelling OEMs to source integrated drive systems with higher power density ratings.
- Silicon Carbide Semiconductors:Wider bandgap materials are reducing inverter switching losses and enabling downsized thermal management hardware.
- Yangtze River Delta Clustering:Vertically integrated suppliers co-locating with battery cell production are shortening logistics lead times for drive unit assembly.
Market Restraints
- Rare-Earth Supply Concentration:Permanent magnet motor production depends on neodymium processing concentrated in China's Inner Mongolia refining corridor.
- Copper Winding Cost Volatility:Stator manufacturing faces input price pressure from London Metal Exchange copper contract fluctuations.
- F-Gas Regulatory Friction:The EU's phasedown of hydrofluorocarbon refrigerants is constraining thermal system design options for European-bound platforms.
Strategic Opportunities
- Commercial Vehicle Electrification:Heavy-duty truck and bus segments in India remain underpenetrated for integrated e-axle configurations.
- US IRA Manufacturing Credits:Domestic content requirements for clean vehicle tax credits are incentivizing North American inverter assembly capacity.
- Wireless Charging Convergence:Inductive power transfer systems are creating demand for onboard power electronics with bidirectional grid integration.
Industry Challenges
- High-Voltage Safety Certification:OEMs face extended validation timelines for 800V motor encapsulation under NHTSA isolation protocols.
- Power Electronics Talent Scarcity:Silicon carbide gate driver design and thermal simulation expertise remains concentrated among a limited pool of specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BEV Electric Drive Unit Market |
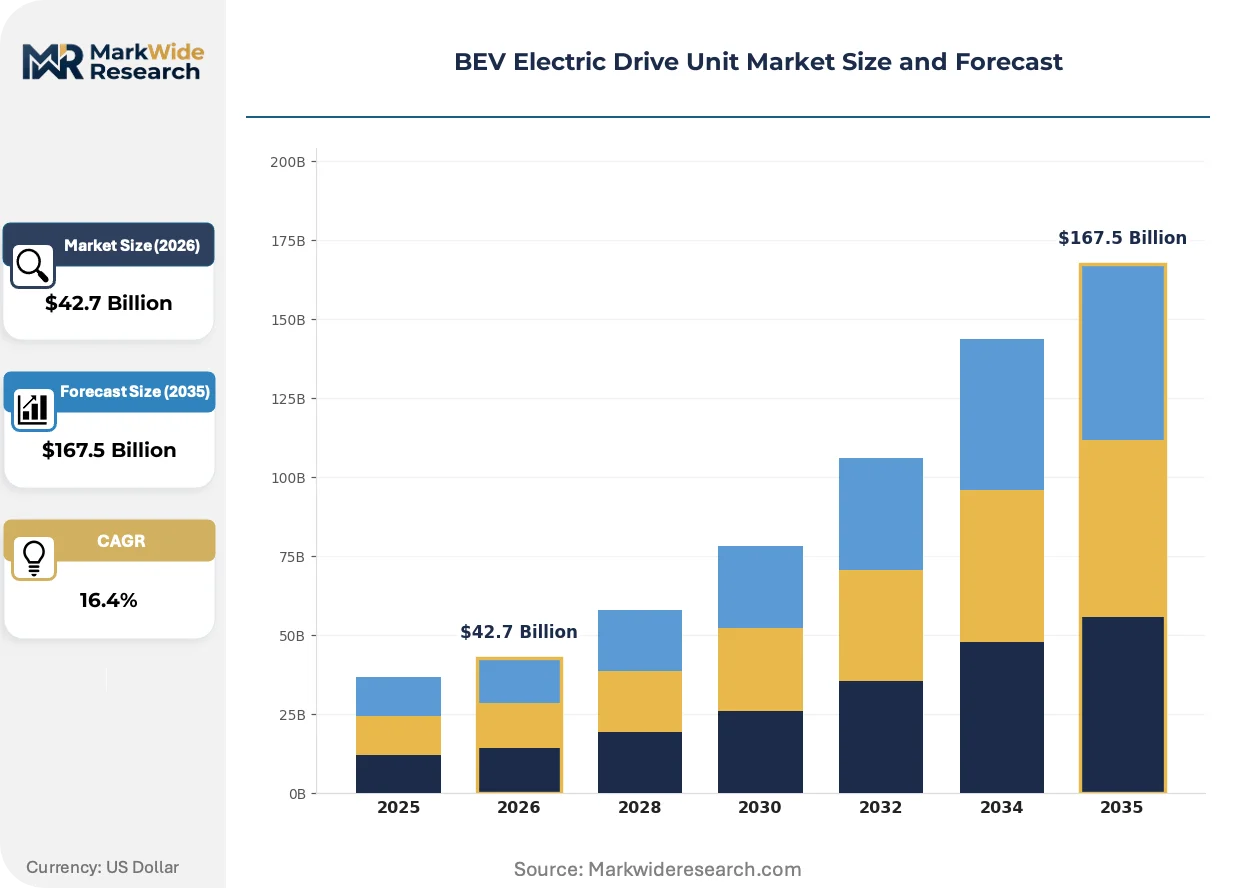
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $167.5 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Drive Unit, Separate Motor and Transmission, Axle Drive, Hub Motor, Torque Vectoring System Technology: Permanent Magnet Synchronous Motor, Induction Motor, Switched Reluctance Motor, Brushless DC Motor, Synchronous Reluctance Motor Application: Passenger Cars, Light Commercial Vehicles, Delivery Vans, Electric Buses, Autonomous Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Service Providers, Vehicle Refurbishers, Fleet Operators |
| Companies Covered | Robert Bosch, ZF Friedrichshafen, BorgWarner, Magna International, Nidec Corporation, Aisin Corporation, Schaeffler, Valeo, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BEV Electric Drive Unit Market Trends and Innovations
Voltage architecture migration and materials science advances are redefining competitive differentiation in electric propulsion systems. Suppliers are racing to qualify integrated platforms ahead of tightened efficiency deadlines.
Silicon carbide metal-oxide-semiconductor field-effect transistors are replacing silicon insulated-gate bipolar transistors in traction inverters. European premium OEMs are adopting these devices for 800V platforms launching through 2027. The technology is expanding into mass-market passenger car segments as device costs fall below silicon parity at higher power ratings.
The EU's F-Gas Regulation is mandating refrigerant transitions in thermal management circuits. Automotive suppliers must redesign cooling loops to accommodate lower-global-warming-potential working fluids. European drive unit manufacturers are accelerating heat pump integration to maintain cabin conditioning performance under stricter chemical constraints.
Fleet operators are consolidating procurement around total cost of ownership metrics rather than upfront component pricing. Commercial vehicle lessors are demanding guaranteed residual value support and predictive maintenance coverage from drive unit suppliers. This shift is most pronounced in Germany's long-haul trucking sector, where electrification mandates are compressing diesel fleet replacement cycles.
BEV Electric Drive Unit Market Segmentation
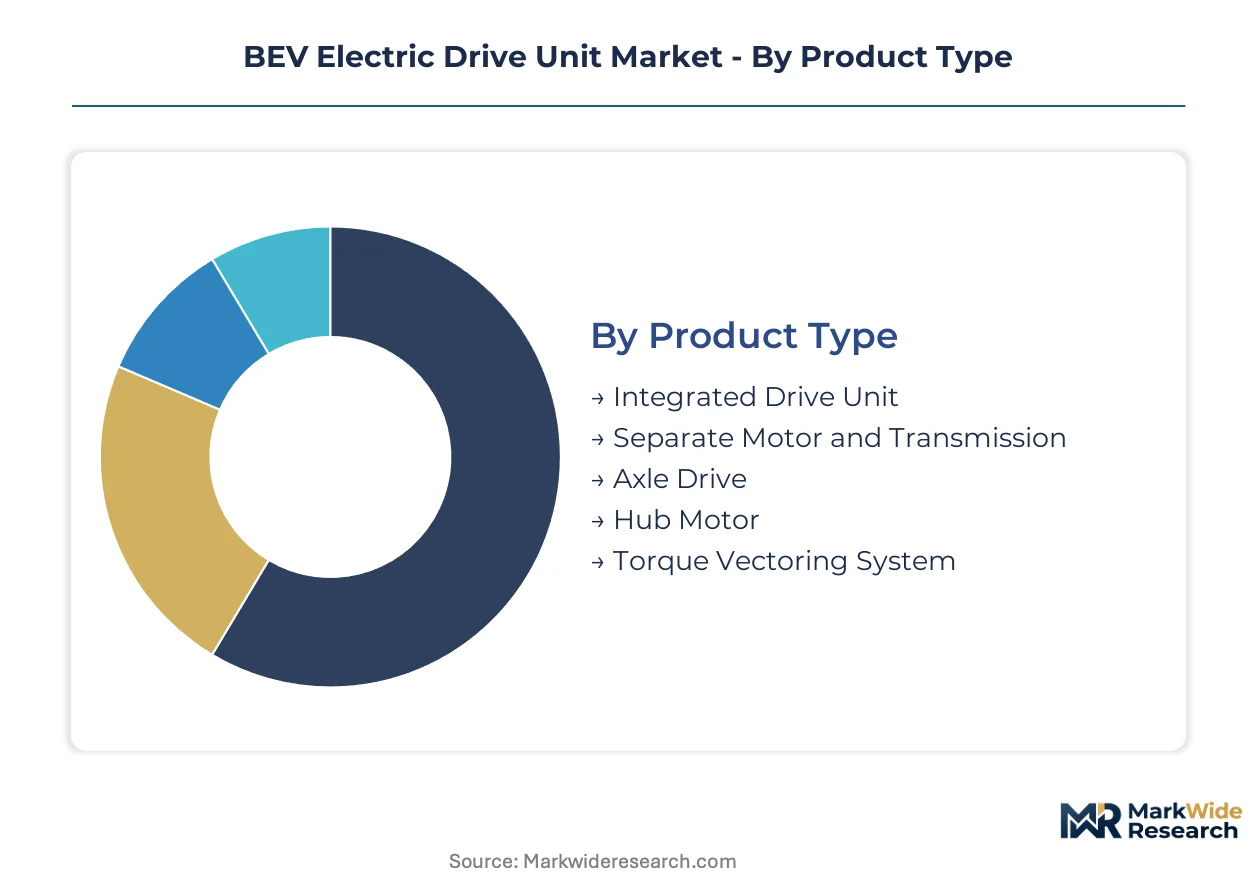
Segmentation in the BEV electric drive unit market reveals how voltage architecture migration and packaging preferences are splitting procurement patterns across passenger and commercial vehicle programs. Suppliers must qualify distinct platform configurations simultaneously as OEMs hedge between integrated and modular approaches.
Product Type:
Packaging density and assembly complexity define the primary axis of product differentiation, with thermal management integration becoming the decisive qualification criterion.
- Integrated Drive Unit:Combines motor, inverter, and reduction gearbox into a single housing with shared cooling circuits. Demand concentrates in China's Yangtze River Delta manufacturing cluster where vertically integrated suppliers co-locate with battery cell production to shorten logistics lead times for drive unit assembly.
- Separate Motor and Transmission:Modular architecture decouples motor procurement from gearbox sourcing, enabling multi-sourcing strategies for OEMs managing rare-earth supply risk. European premium passenger car programs favor this configuration for performance variants requiring specialized torque vectoring hardware.
- Axle Drive:Configured for rear-wheel-drive platforms with co-axial motor placement.
- Hub Motor:Eliminates driveline losses through direct wheel mounting; constrained by unsprung mass penalties.
- Torque Vectoring System:Adds differential torque control for vehicle dynamics optimization.
Integrated Drive Unit leads on scale; Torque Vectoring System leads on momentum.
Technology:
Motor topology selection hinges on the trade-off between power density and material supply security, with rare-earth exposure now a board-level procurement risk factor.
- Permanent Magnet Synchronous Motor:Delivers peak power densities exceeding 3 kW per kilogram through neodymium-iron-boron rotor magnets. China's MIIT efficiency mandates are compelling OEMs to source integrated drive systems with higher power density ratings, reinforcing dominance in Asian passenger car programs.
- Induction Motor:Operates without permanent magnets, eliminating rare-earth supply concentration risk concentrated in China's Inner Mongolia refining corridor. Cost-optimized vehicle segments and performance-oriented platforms in North America sustain niche demand for this architecture.
- Switched Reluctance Motor:Robust rotor construction suits high-temperature commercial vehicle applications.
- Brushless DC Motor:Simplified control electronics appeal to low-voltage micro-mobility platforms.
- Synchronous Reluctance Motor:Emerging alternative for medium-duty applications seeking magnet-free operation.
Permanent Magnet Synchronous Motor commands volume leadership; Induction Motor is gaining share fastest among risk-averse procurement strategies.
Application:
Vehicle duty cycles determine thermal sizing and regeneration capacity requirements, with commercial electrification timelines diverging sharply from passenger car adoption curves.
- Passenger Cars:400V and 800V DC bus architectures dominate, with silicon carbide inverter adoption accelerating platform consolidation. European premium OEMs are adopting these devices for 800V platforms as device costs fall below silicon parity at higher power ratings.
- Electric Buses:High-floor and low-floor configurations demand distinct axle packaging with continuous duty thermal management. Fleet operators in Germany's long-haul trucking sector are consolidating procurement around total cost of ownership metrics, compressing diesel replacement cycles.
- Light Commercial Vehicles:Payload-sensitive segments prioritize power-to-weight optimization.
- Delivery Vans:Stop-start duty cycles maximize regeneration value capture.
- Autonomous Vehicles:Redundant motor control architectures impose additional functional safety requirements.
Passenger Cars anchor current revenue; Electric Buses show the steepest expansion trajectory under fleet electrification mandates.
End User:
Procurement authority is shifting from component sourcing to system-level contracting as residual value guarantees become standard commercial terms.
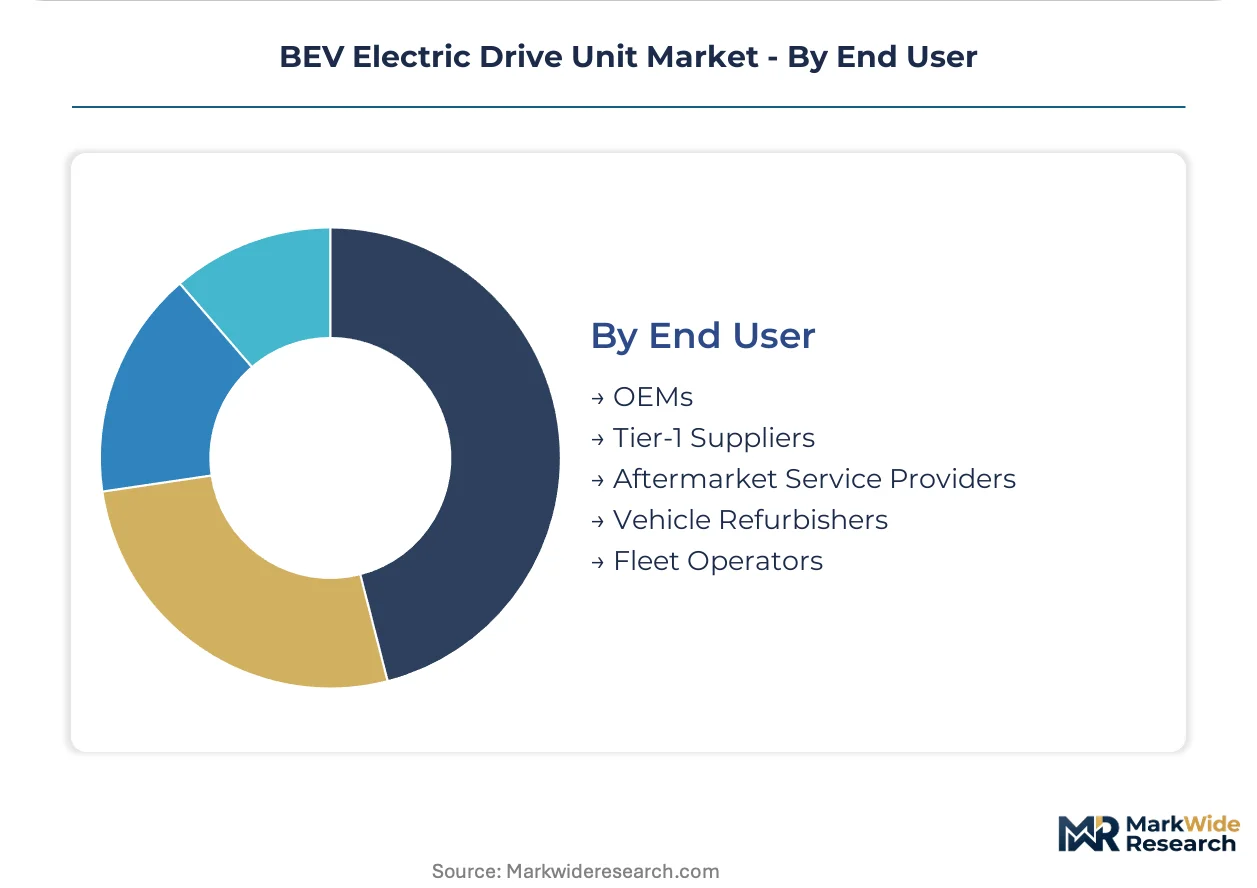
- OEMs:Direct platform integration responsibility with qualification timelines compressing under 800V architecture proliferation. The US IRA manufacturing credits are incentivizing North American inverter assembly capacity to meet domestic content requirements for clean vehicle tax credits.
- Fleet Operators:Consolidating procurement around guaranteed residual value support and predictive maintenance coverage from drive unit suppliers. Commercial vehicle lessors in Germany are demanding outcome-based service contracts rather than upfront component pricing.
- Tier-1 Suppliers:Intermediate system integrators managing subsystem qualification on behalf of OEMs.
- Aftermarket Service Providers:Repair and replacement demand concentrated in early BEV adopter markets.
- Vehicle Refurbishers:Emerging channel for battery and drive unit second-life applications.
OEMs retain volume concentration; Fleet Operators are climbing the fastest as procurement authority migrates to lessor balance sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric drive unit manufacturing originated in Germany's automotive engineering corridor during the early hybrid vehicle era. Production scale shifted decisively toward China's Yangtze River Delta after 2015 as battery cell fabrication concentrated there. Today's geographic distribution reflects this dual heritage: European system integration expertise anchors premium platforms while Chinese vertical integration drives volume economics.
China
Domestic OEMs source over seventy percent of their integrated drive systems from suppliers co-located with CATL and BYD battery facilities in Suzhou and Ningbo. MIIT catalog efficiency thresholds now mandate power density ratings above three kilowatts per kilogram for new energy vehicle qualification. The Yangtze River Delta cluster has compressed logistics lead times to under forty-eight hours for motor-inverter-gearbox assembly.
Germany
Long-haul fleet operators in Bavaria and North Rhine-Westphalia are consolidating procurement contracts around guaranteed residual value terms rather than upfront component pricing. The EU's F-Gas Regulation is forcing redesign of thermal management circuits to accommodate lower-global-warming-potential refrigerants. Stuttgart-based engineering groups anchor silicon carbide inverter qualification timelines for 800V platforms launching through 2027.
United States
Domestic content requirements under the IRA clean vehicle tax credits are incentivizing North American inverter assembly capacity expansion. EPA tailpipe standards and NHTSA high-voltage isolation protocols are extending validation timelines for 800V motor encapsulation. Michigan and Ohio manufacturing corridors are attracting Tier-1 suppliers seeking proximity to Detroit Three EV platform launches.
Japan
Permanent magnet motor production for Asian passenger car programs concentrates around Tokyo and Nagoya engineering centers. METI technology roadmaps are accelerating rare-earth recycling investments to reduce dependence on Chinese Inner Mongolia refining. Toyota and Honda supplier networks in Aichi Prefecture are qualifying induction motor alternatives for export markets sensitive to supply concentration risk.
India
Heavy-duty truck and bus electrification remains underpenetrated despite PLI scheme subsidies for domestic manufacturing. BIS efficiency standards and state-level electric mobility mandates in Maharashtra and Gujarat are creating procurement pull for integrated e-axle configurations. The Delhi-Mumbai Industrial Corridor is emerging as a testbed for commercial vehicle drive unit localization.
BEV Electric Drive Unit Market Competitive Landscape
The competitive structure tilts toward integrated system specialists with captive power electronics capability. Tier-1 automotive suppliers with legacy transmission expertise hold defensive positions in European premium platforms, while Asian motor specialists capture volume through rare-earth magnet supply chain proximity. Three archetypes dominate: full-system integrators owning inverter-motor-gearbox combinations, component specialists licensing motor topology IP, and captive OEM divisions serving affiliated vehicle platforms. Capacity expansion and silicon carbide semiconductor partnerships represent the dominant competitive moves as qualification timelines compress under 800V proliferation.
Among German-based fabricators, ZF Friedrichshafen and Schaeffler occupy positions within the integrated system tier, leveraging transmission heritage to anchor long-term supply agreements. BorgWarner represents the North American specialist archetype, while Nidec Corporation exemplifies the Asian volume motor producer with backward integration into magnet supply chains. These named entities serve as anchors for understanding how geographic proximity to battery production and rare-earth refining corridors shapes competitive positioning across voltage architecture transitions.
| Leading Market Players |
|---|
| Robert Bosch |
| ZF Friedrichshafen |
| BorgWarner |
| Magna International |
| Nidec Corporation |
| Aisin Corporation |
| Schaeffler |
| Valeo |
| DENSO Corporation |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper contract volatility cascades through stator manufacturing costs into three distinct procurement tiers across passenger car, commercial vehicle, and aftermarket replacement segments.
Pricing Analysis
Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation anchored in silicon carbide inverter certification grade and volume scale commitments. Premium-mid-economy pricing stratification separates 800V platform suppliers from 400V mass-market providers and cost-optimized induction motor specialists. Cost compression in standard-tier integrated drive units is intensifying because China's MIIT efficiency mandates are forcing redesign cycles. Fleet operators show lowest price sensitivity due to total cost of ownership contracting, while aftermarket service providers face acute margin pressure from copper winding spot market exposure.
Supply Chain Analysis
Neodymium-iron-boron magnet supply rests on Chinese Inner Mongolia refining corridors, South Korean specialty chemical processing, and Japanese powder metallurgy expertise. Permanent magnet rotors, silicon carbide substrates, and copper winding wire constitute the critical input trinity. Single-source vulnerability concentrates in rare-earth oxide separation capacity. Distribution runs through Yangtze River Delta manufacturing clusters co-located with CATL and BYD battery facilities, with European premium platforms served by Stuttgart-based engineering groups maintaining separate qualification pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide cost-down curves and 800V platform proliferation create margin expansion headroom for suppliers qualifying ahead of EU CO2 enforcement deadlines.
For Market Incumbents: Lock in long-term rare-earth supply agreements before China's dual carbon goals constrain Inner Mongolia refining expansion. Secure silicon carbide wafer partnerships with substrate specialists to defend against emerging fabless inverter designers. Prioritize NHTSA 800V isolation protocol pre-qualification to compress validation timelines for North American OEM programs. For New Entrants and Emerging Players: Begin with India's underpenetrated heavy-duty truck and bus electrification corridor, where PLI scheme subsidies offset capital intensity for integrated e-axle manufacturing. Target state-level electric mobility mandates in Maharashtra and Gujarat as anchor demand. Pursue wireless charging convergence partnerships to differentiate bidirectional power electronics capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where silicon carbide gate driver design expertise concentrates among limited specialist pools. Five-to-ten year viability favors acquirers of captive magnet recycling technology and thermal simulation software assets. Watch NHTSA 800V safety certification backlog as inflection signal for qualification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Partnership | Secures substrate supply for 800V platform qualification ahead of EU CO2 deadlines. |
| Rare-Earth Recycling Investment | Reduces magnet supply exposure to China's Inner Mongolia refining corridor concentration. |
| Yangtze River Delta Manufacturing Footprint | Co-locates assembly with CATL and BYD battery production to compress logistics lead times. |
| Thermal Management System Redesign | Accommodates EU F-Gas Regulation refrigerant phase-down for European-bound platforms. |
| Fleet Operator Service Contract | Captures residual value guarantee revenue from Germany's long-haul trucking electrification mandates. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, Tier 1 supplier production schedules, and regulatory filing databases — were reconciled against vehicle registration data and battery cell production records. Primary interviews with electric drive unit procurement managers, silicon carbide semiconductor specialists, thermal systems engineers, and fleet operator asset managers were cross-validated against MIIT new-energy vehicle catalog entries, EPA certification documents, and EU type-approval records. Bottom-up unit shipment estimates and top-down value chain assessments were triangulated to anchor market sizing.
Data-stream reconciliation applied vehicle class, voltage architecture, motor topology, and regional production cluster dimensions across the projection horizon. CAGRs were derived from segment-level growth rate differentials weighted by base-year revenue contribution. Modeled inputs included silicon carbide device cost curves, rare-earth oxide price indices, and OEM platform launch timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory threshold adjustments, geopolitical trade restriction escalations, and breakthrough motor topology displacements. Forecasts reflect stated OEM platform commitments and supplier capacity expansion announcements. A small set of named triggers — NHTSA 800V safety rule finalization, China's dual carbon policy implementation pace, and EU F-Gas refrigerant availability — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Electric Vehicle Battery on Demand Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market