
 Pre-Made Bags Market | 2026-2036
Pre-Made Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Made Bags Market Analytics
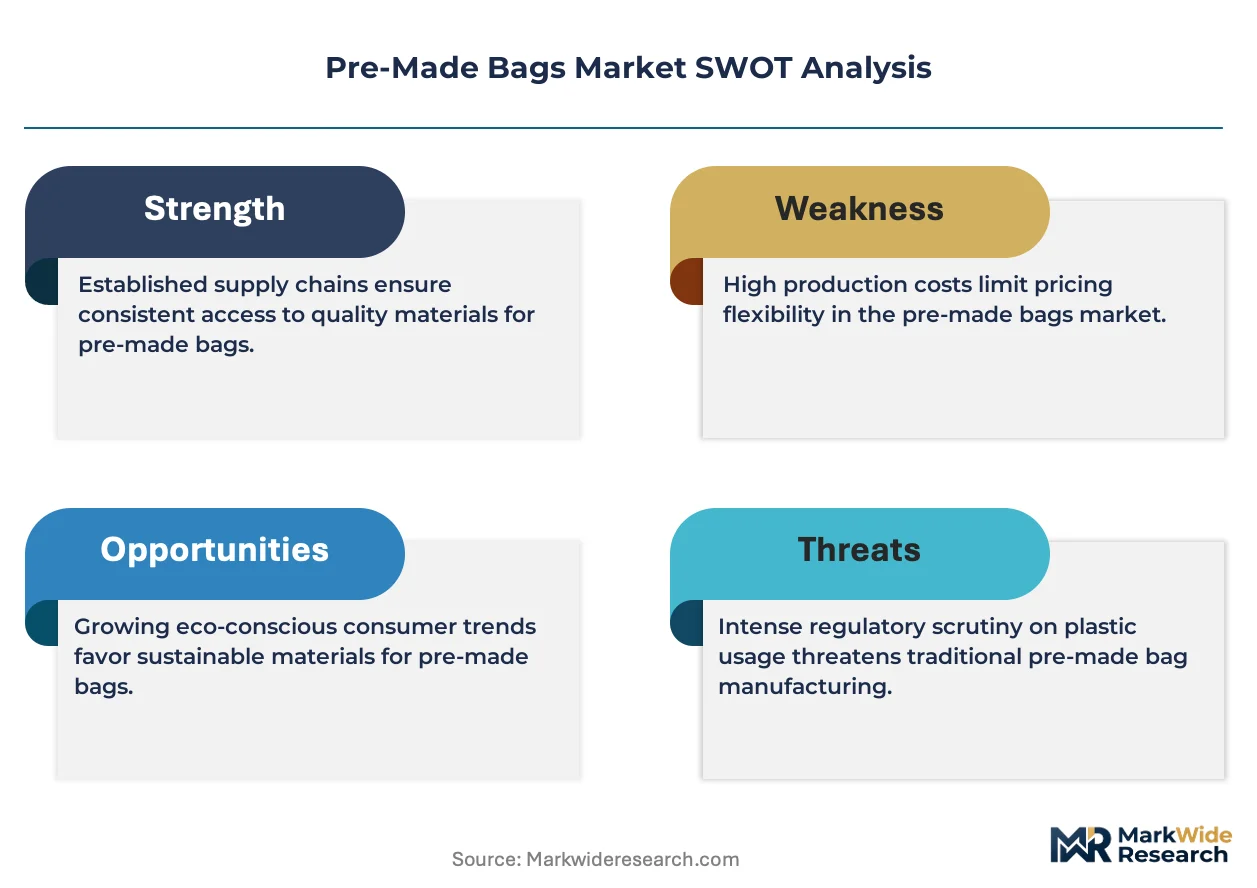
Consolidation among North American food service distributors is recalibrating procurement volumes for pre-made bag suppliers. Amcor plc leverages its integrated film manufacturing network to secure long-term supply contracts with institutional buyers. Berry Global Group Inc anchors its position through specialized multi-layer barrier films for protein packaging. Sealed Air Corporation differentiates via automated bagging equipment paired with consumable film sales.
Pre-made bags are factory-constructed flexible containers, typically formed from polyethylene, polypropylene, kraft paper, or woven polypropylene, with specified gauge, seal strength, and moisture vapor transmission rates designed for product containment, protection, and shelf-life extension. Plastic bags still occupy the largest volume share across industrial and retail channels, though biodegradable bags are recording the fastest expansion as compostable resin costs decline and retail mandates tighten. Ziplock closure formats lead in food service and consumer segments where resealability extends product usability, while adhesive closures dominate single-use retail applications where cost minimization governs specification.
The US EPA oversees landfill diversion targets that pressure manufacturers toward recyclable or compostable bag constructions, while the EU REACH regulation restricts certain phthalates and heavy metals in plastic film formulations, directly shaping material selection across export-oriented production. FDA food contact substance notifications govern barrier properties and migration limits for bags used in direct food applications, creating compliance thresholds that filter smaller film converters from institutional supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate certification requirements to anticipate which material platforms will retain market access across major economies.
Market Dynamics
Consolidation among North American food service distributors is compressing supplier margins while amplifying volume concentration toward film converters with captive resin supply. This structural force is accelerating backward integration among mid-tier bag manufacturers seeking procurement stability.
Growth Catalysts
- EU Single-Use Plastics Directive:The mandate is accelerating substrate substitution toward biodegradable polymers and fiber-based alternatives across retail and food service channels.
- Prepared meal delivery expansion:North American food service operators are scaling heat-sealed and ziplock pouch procurement for ready-to-eat distribution.
- Compostable resin cost curves:Declining unit economics for PLA and PHA blends are narrowing the premium versus conventional polyethylene in institutional buying.
Market Restraints
- Resin supply concentration:Polyethylene and polypropylene feedstock pricing remains tethered to Gulf Coast petrochemical complex volatility.
- Barrier performance gaps:Biodegradable substrates exhibit inferior moisture vapor transmission rates versus multi-layer barrier films in protein packaging.
- REACH compliance friction:ECHA restrictions on phthalates and heavy metals in film formulations are disqualifying legacy converters from EU export eligibility.
Strategic Opportunities
- Automated bagging equipment pairing:Film suppliers bundling consumables with capital equipment are capturing multi-year sole-source contracts.
- German retail consolidation:Supermarket and industrial packaging buyers are rationalizing supplier bases, creating volume concentration for qualified entrants.
- Extended producer responsibility frameworks:Emerging deposit-return and post-consumer content mandates are favoring converters with certified recycling infrastructure.
Industry Challenges
- Migration testing timelines:FDA food contact substance notifications require 12-18 month validation cycles that delay new barrier formulations.
- Legacy equipment retrofitting:Fiber-based and compostable substrates demand modified heat-seal parameters incompatible with installed thermoforming lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Made Bags Market |
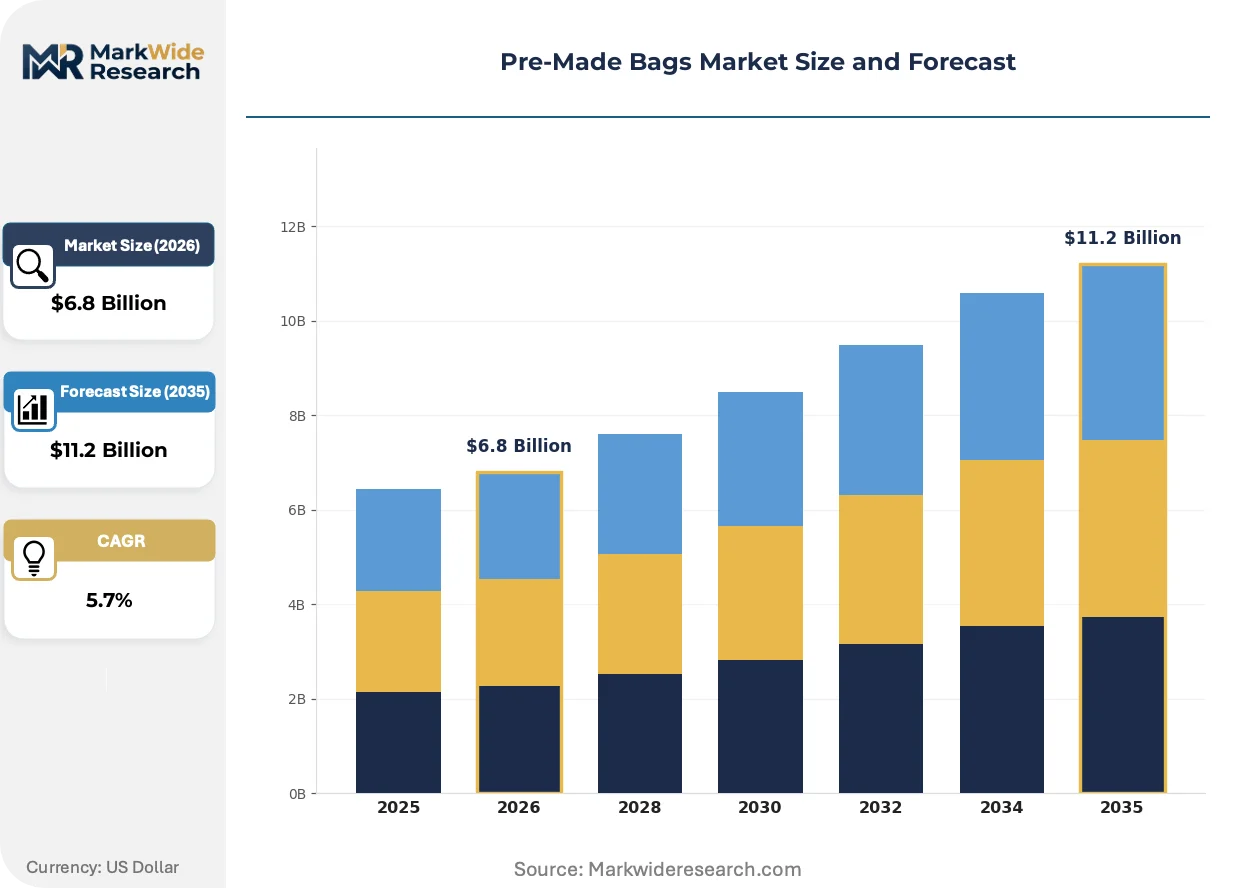
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Fabric Bags, Biodegradable Bags Usage: Retail, Food Service, Hospitality, Industrial Closure Type: Ziplock, Drawstring, Adhesive, Ties End User: Consumers, Manufacturers, Retailers, Distributors |
| Companies Covered | Amcor plc, Berry Global Group Inc, Sealed Air Corporation, Huhtamaki Oyj, Ampac Packaging, Clondalkin Group, ProAmpac Holdings, Constantia Flexibles, Scholle IPN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Made Bags Market Evolving Landscape
Material science advances and regulatory mandates are reconfiguring competitive advantage around substrate certification and equipment integration. The market is pivoting from commodity film supply toward solution architectures combining formulation, barrier engineering, and automated deployment.
Multi-layer coextrusion technology is converging with bio-based sealant layers to deliver oxygen and moisture barriers approaching petroleum-derived performance. Protein packagers in the US and Germany are piloting these constructions for case-ready meat applications. The technology is converging with compostable certification requirements to unlock premium positioning in retail private label programs.
REACH authorization procedures for novel plasticizers are extending compliance timelines for converters serving EU food contact applications. ECHA's evolving substance restrictions are forcing reformulation of legacy cling films and high-clarity pouches. German and French retail chains are responding by accelerating supplier audits and demanding pre-certified alternative formulations.
Food service distributors are consolidating procurement under category managers with technical specification authority, displacing fragmented spot buying. Institutional buyers now require migration test documentation and extended shelf-life validation as table stakes. This concentration is most visible in North American contract catering and meal kit fulfillment networks.
Pre-Made Bags Market Segmentation
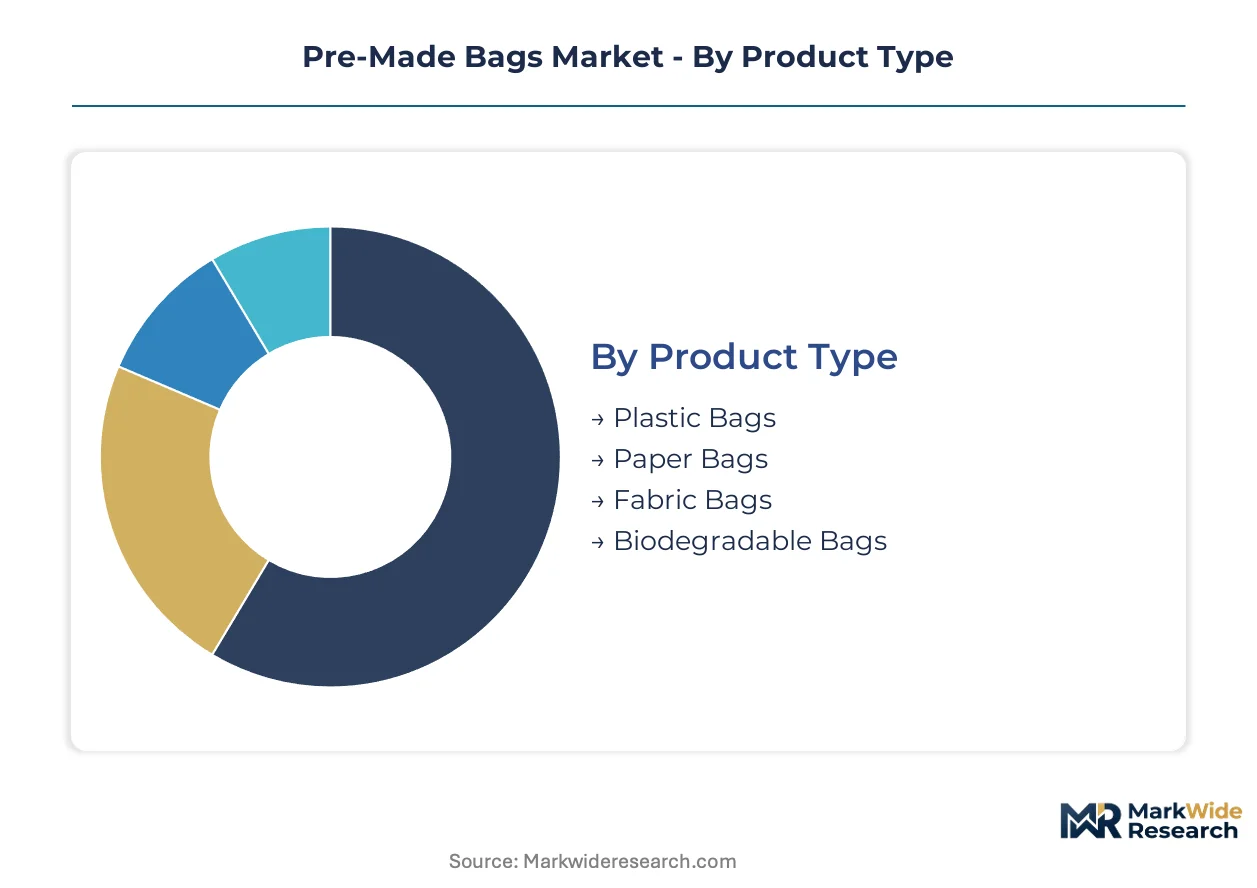
Pre-made bag specifications diverge sharply across procurement contexts. Material selection, closure mechanics, and buyer type each create distinct competitive arenas with different margin structures and certification requirements.
Product Type:
Cost tier separates commodity buyers from premium positioning seekers.
- Plastic Bags:Multi-layer polyethylene and polypropylene constructions dominate protein packaging and industrial containment. US food service distributors specify these for heat-sealed prepared meal distribution where moisture vapor transmission rates determine shelf-life performance.
- Biodegradable Bags:PLA and PHA blends with compostable certification are narrowing the premium versus conventional polyethylene in German retail procurement. EU Single-Use Plastics Directive mandates are accelerating substrate substitution in French and Italian supermarket chains.
- Paper Bags:Kraft constructions serve bakery and dry goods retail with fiber-based alternatives gaining traction where local landfill diversion targets apply.
- Fabric Bags:Woven polypropylene and cotton canvas target reusable applications in hospitality and promotional retail channels.
Plastic bags lead volumes today; biodegradable bags are gaining share fastest.
Usage:
Application context dictates barrier specifications and regulatory exposure.
- Food Service:Heat-sealed and ziplock pouches for ready-to-eat distribution require FDA food contact substance compliance. North American contract catering networks are consolidating procurement under technical specification authority.
- Retail:Private label programs demand certified compostable substrates and migration test documentation as table stakes. German supermarket chains are rationalizing supplier bases toward pre-certified converters.
- Industrial:Multi-layer barrier films for chemical and component containment prioritize seal strength and gauge consistency over sustainability credentials.
- Hospitality:Amenity and laundry applications favor cost-minimized polyethylene with basic closure mechanics.
Food service commands the highest specification intensity; retail is expanding most quickly.
Closure Type:
Customer type determines resealability requirements versus cost minimization priorities.
- Ziplock:Interlocking track mechanisms extend product usability in consumer and institutional segments. Meal kit fulfillment networks specify these for ingredient portioning where repeated access is required.
- Adhesive:Pressure-sensitive strips dominate single-use retail where unit economics govern specification and resealability is unnecessary.
- Drawstring:Cord-and-channel constructions serve lawn and leaf, laundry, and bulk commodity handling.
- Ties:Twist or clip fasteners persist in industrial and hospitality applications with low complexity requirements.
Ziplock leads in food contact applications; adhesive dominates unit volume.
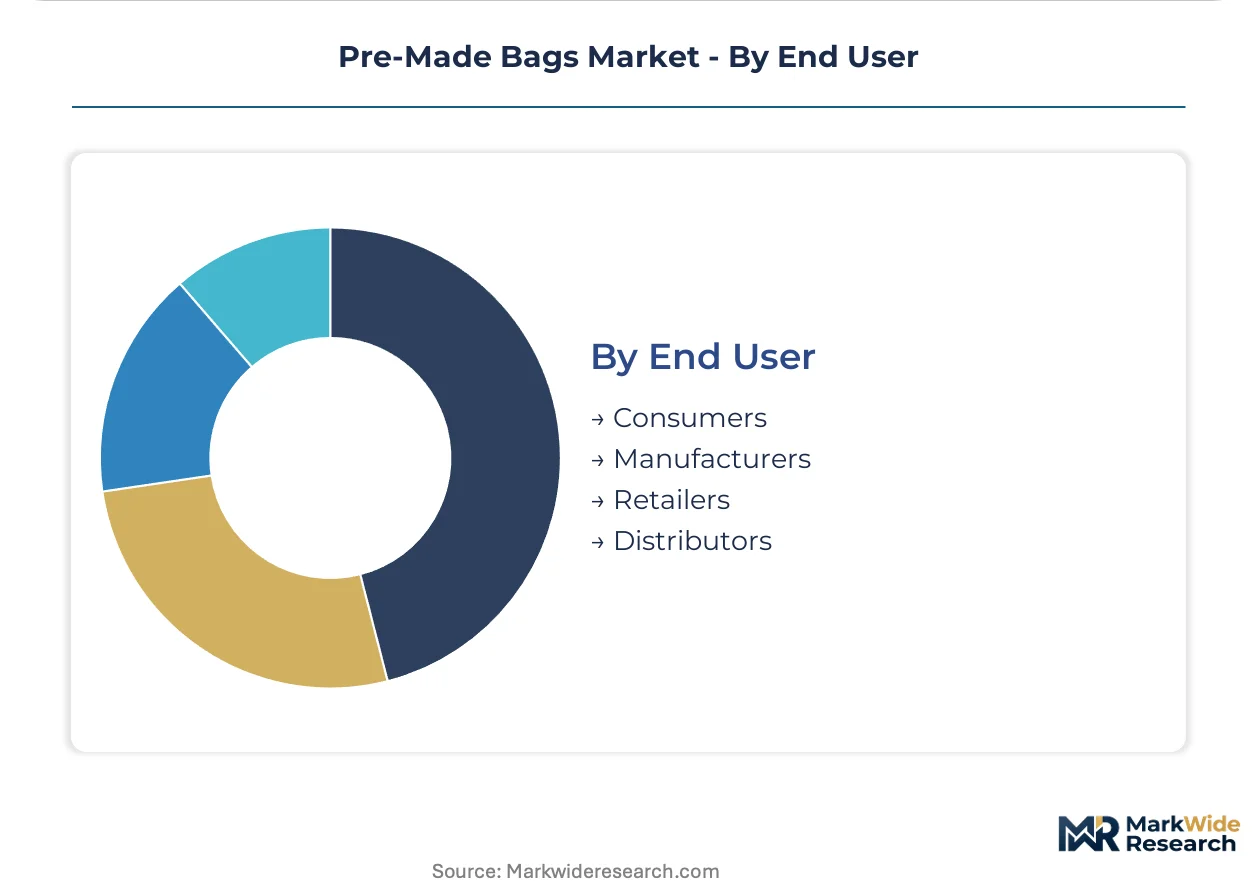
End User:
Volume concentration and technical capability separate procurement behaviors.
- Retailers:Category managers with specification authority are displacing fragmented spot buying. Extended shelf-life validation and substrate certification are mandatory for contract eligibility.
- Distributors:Consolidated North American food service distributors are compressing supplier margins while amplifying volume concentration toward converters with captive resin supply.
- Manufacturers:Industrial packaging buyers prioritize gauge consistency and seal strength for component and chemical containment.
- Consumers:Direct procurement through e-commerce channels favors SKU breadth and immediate availability over technical specification depth.
Retailers lead specification complexity; distributors concentrate volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates retail procurement authority while the United States anchors food service distributor consolidation, creating divergent demand patterns across Atlantic markets. Material substitution timelines and regulatory stringency separate these regional growth trajectories.
United States
Food service distributors in Chicago and Dallas-Fort Worth are compressing supplier margins through consolidated procurement under category managers with technical specification authority. The EPA oversees landfill diversion targets that pressure manufacturers toward recyclable or compostable bag constructions. Midwestern converter clusters around Illinois and Ohio are retrofitting lines for biodegradable substrates to retain institutional contracts.
Germany
Supermarket chains in Bavaria and North Rhine-Westphalia are rationalizing supplier bases toward pre-certified converters with compostable substrate documentation. ECHA restrictions on phthalates and heavy metals in film formulations disqualify legacy converters from export eligibility. The Rhine-Ruhr industrial corridor hosts concentrated flexible packaging capacity serving pan-European retail private label programs.
France
Retail mandates in the Île-de-France region are tightening compostable certification requirements for single-use bag procurement. The EU Single-Use Plastics Directive accelerates substrate substitution toward biodegradable polymers across French supermarket chains. Lyon-based packaging buyers are demanding pre-certified alternative formulations ahead of scheduled regulatory deadlines.
China
Flexible film converters in the Yangtze River Delta are scaling multi-layer coextrusion capacity for protein packaging export to North American and European buyers. NMPA and GB standards govern food contact substance compliance for bags used in direct food applications. Shanghai and Jiangsu province clusters are integrating bio-based sealant layers to access premium retail positioning in German and US markets.
India
Food service operators in Maharashtra and Gujarat are expanding heat-sealed pouch procurement for prepared meal delivery networks. FSSAI regulations on food contact materials create compliance thresholds that filter smaller film converters from institutional supply chains. The Mumbai-Pune industrial corridor is attracting investment in compostable resin compounding to serve domestic retail diversion targets.
Pre-Made Bags Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated resin supply and captive film manufacturing separate top-tier converters from fragmented regional competitors. Three archetypes dominate: integrated resin-to-film operators, equipment-integrated solution providers, and certified substrate specialists. M&A activity concentrates volume toward backward-integrated players while strategic partnerships pair film supply with automated deployment systems.
Within the integrated converter tier, Amcor plc and Berry Global Group Inc exemplify scale-driven positioning through captive manufacturing networks. Sealed Air Corporation occupies the equipment-integrated archetype, bundling consumable film sales with capital deployment systems. These three anchors represent divergent competitive vectors: resin integration, barrier specialization, and automation pairing.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group Inc |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Ampac Packaging |
| Clondalkin Group |
| ProAmpac Holdings |
| Constantia Flexibles |
| Scholle IPN Corporation |
| Others |
Value Network & Pricing Analysis
Polyethylene resin costs originating from Gulf Coast petrochemical complexes cascade through three pricing tiers downstream: commodity spot buyers absorb volatility directly, contract food service distributors lock in quarterly adjustments, and certified compostable converters command premiums through EU Single-Use Plastics Directive compliance.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for multi-layer barrier films exported to North American protein packagers. Three-tier pricing structure across premium compostable certification, standard multi-layer barrier, and economy single-polyethylene tiers separates buyers by migration test documentation requirements. Pricing pressure stems from consolidated North American distributor procurement compressing supplier margins. Food service distributors exhibit highest price sensitivity; German retail chains with private label programs show lowest sensitivity due to certification compliance premiums.
Supply Chain Analysis
Post-consumer film collection and mechanical recycling infrastructure in Germany and the Netherlands feeds back into certified recycled content supply for EU retail compliance. Raw material supply concentrates in the United States, China, and Germany for polyethylene resin, multi-layer coextrusion equipment, and compostable PLA compounding respectively. The chain draws from Gulf Coast petrochemical feedstock, Yangtze River Delta film extrusion capacity, and Rhine-Ruhr converter clusters. Single-source vulnerability persists in bio-based sealant resin supply. Distribution runs through consolidated North American food service distributors and rationalized German supermarket procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pre-made bags rests on compostable resin cost curves declining toward parity with conventional polyethylene, unlocking premium-tier positioning for certified converters.
For Market Incumbents: To counter backward integration by mid-tier competitors seeking resin supply security, Amcor plc and Berry Global Group Inc should deepen captive polyethylene compounding capacity in Illinois and Ohio while accelerating FDA food contact substance notification pipelines for novel barrier formulations. Certification investment in BPI and TUV compostable standards represents the critical lever for EU retail retention. For New Entrants and Emerging Players: Enter via certified compostable substrate supply to French and Italian supermarket chains ahead of EU Single-Use Plastics Directive enforcement deadlines. White-space targets include automated bagging equipment bundling for North American meal kit fulfillment networks and fiber-based alternatives for German bakery retail. A technical specification authority go-to-market angle bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA compliance timelines filter smaller converters from institutional food service supply chains. Long-term viability favors converters with integrated resin supply and certified recycling infrastructure. Acquisition targets include mid-tier Midwestern film converters with retrofitting capability for biodegradable substrates. Monitor ECHA substance restriction announcements for inflection signals on legacy formulation obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply secures volume commitments from consolidated North American distributors. |
| Compostable Certification Investment | BPI and TUV certifications unlock German retail private label procurement rationalization. |
| Automated Bagging Equipment Bundling | Sealed Air Corporation's model captures multi-year sole-source contracts in food service. |
| Multi-Layer Coextrusion Capacity Expansion | Yangtze River Delta additions serve protein packaging export demand from US and EU buyers. |
| FDA Food Contact Notification Pipeline | Accelerated migration test documentation displaces non-compliant legacy converters. |
Research Methodology
Bottom-up food service and retail procurement modeling reconciled against top-down resin supply and converter capacity tracking forms the analytical core. Primary interviews with film converter plant managers, food service distributor category managers, supermarket private label buyers, and compostable certification auditors combined with secondary validation from FDA food contact substance databases, ECHA REACH restriction updates, and flexible packaging trade association production surveys. Top-down triangulation against customs export data and petrochemical feedstock pricing indices anchored volume estimates.
Input-output matrices across material type, closure mechanism, end-use application, and geographic regulatory cluster drove segment-level projections throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves for prepared meal delivery expansion and EU substrate substitution mandates. Industry-specific forecast inputs included compostable resin cost curve trajectories and FDA notification approval timelines.
Inputs from primary converter interviews and certification body documentation were available through the study window; gaps in real-time procurement contract terms introduce uncertainty bands around distributor consolidation timing assumptions. Practitioners should monitor ECHA substance restriction proposals and EPA landfill diversion target revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Textile Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Twin Seal Bags Market