
 Solar Insect Trap Market | 2026-2036
Solar Insect Trap Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Insect Trap Market Insights
Chinese photovoltaic module manufacturers is broadening the supply base for solar-powered insect trap producers across Asia. Syngenta leverages its agrochemical distribution networks to position solar trap solutions alongside integrated pest management portfolios. Rentokil Initial anchors its commercial pest control operations with technology-led service models that incorporate solar trapping systems in agricultural contracts.
A solar insect trap integrates photovoltaic panels with ultraviolet LED arrays, pheromone dispensers, and electrocution grids or adhesive capture surfaces to attract and neutralize insect pests without chemical agents. The device converts solar energy into targeted spectral emissions, typically operating at wavelengths between 365 and 395 nanometers to exploit phototactic responses in lepidopteran and dipteran species. Outdoor traps dominate unit volumes due to their deployment across expansive agricultural acreage, while hybrid systems that combine solar generation with attractant-based lures command margin premiums through enhanced capture efficiency in high-infestation zones. Greenhouse applications represent the fastest-growing segment as controlled-environment agriculture operators seek residue-free compliance for export-oriented produce.
The EPA regulates pesticidal device claims under FIFRA, compelling manufacturers to substantiate efficacy data or risk enforcement action that restricts interstate commerce. India's CEA standards for solar photovoltaic systems and BIS certification requirements for electronic equipment create dual compliance pathways that shape product design and market entry timelines. Stakeholders must monitor evolving pesticide residue limits under the EU Green Deal's Farm to Fork targets, as these thresholds directly determine substitution economics for solar trapping versus conventional chemical applications.
Market Dynamics
Precision agriculture adoption is compressing the substitution economics between chemical pesticides and solar-powered trapping systems, particularly as export-oriented producers face tightening residue thresholds in destination markets.
Growth Catalysts
- EU Green Deal pesticide reduction mandates:The Farm to Fork Strategy's residue limit reductions are compelling fruit and vegetable growers across Mediterranean horticulture belts to deploy non-chemical alternatives.
- Photovoltaic cost deflation:Chinese module manufacturers have driven solar component prices downward, expanding addressable markets for price-sensitive agricultural operators in emerging economies.
- Controlled-environment agriculture expansion:Greenhouse operators in export-oriented production clusters are prioritizing residue-free compliance to maintain market access in premium segments.
Market Restraints
- Lithium-ion battery supply concentration:Energy storage component sourcing remains concentrated among East Asian cell manufacturers, exposing trap assemblers to input volatility and logistics bottlenecks.
- UV LED wavelength standardization gaps:Absence of unified spectral efficacy protocols forces manufacturers to maintain multiple product variants, elevating inventory carrying costs.
- Seasonal utilization constraints:Northern latitude agricultural operations face extended dormancy periods where trap deployment generates minimal returns, compressing capital recovery timelines.
Strategic Opportunities
- India's PLI agricultural mechanization incentives:Domestic manufacturing subsidies create localized production advantages for serving South Asian and Middle Eastern demand corridors.
- IoT-enabled predictive pest monitoring:Integration of trap-mounted sensors with farm management software platforms opens recurring revenue streams through data subscription models.
- Organic certification premium capture:Third-party verified trap efficacy documentation enables producers to command price premiums in certified organic supply chains.
Industry Challenges
- Field calibration expertise scarcity:Optimal trap placement and spectral tuning require entomological knowledge that distributor networks often lack, degrading realized efficacy and customer retention.
- Dual certification pathway complexity:India's CEA photovoltaic standards and BIS electronic equipment requirements impose parallel compliance processes that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Insect Trap Market |
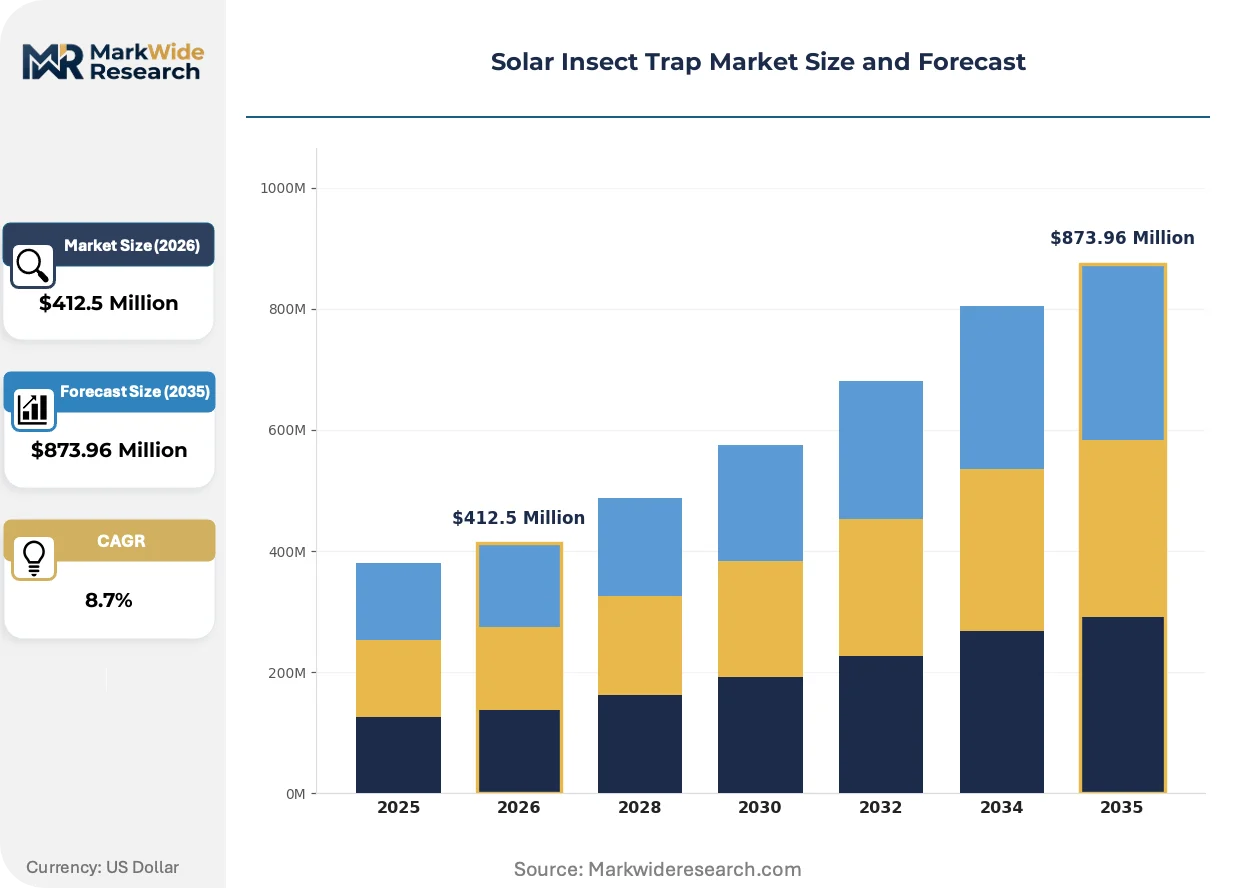
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor Traps, Indoor Traps, Home Solutions, Commercial Units Technology: Solar-Powered, Electric, Attractant-Based, Hybrid Systems Application: Agricultural Fields, Residential Gardens, Industrial Areas, Greenhouses End User: Farmers, Homeowners, Pest Control Companies, Environmental Agencies |
| Companies Covered | Sickle Innovations Private Limited, Vinspire Agrotech (I) Private Limited, Vinglob Greentech Pvt Ltd, Marker Electronic Equipments, PNGR Ever Green Technology, Syngenta, PIC Corporation, Rentokil Initial, Thermacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Insect Trap Market Trends and Innovations
Hardware-software convergence is redefining competitive differentiation beyond capture mechanisms toward integrated pest intelligence platforms that command recurring revenue relationships.
Hybrid solar-attractant systems are consolidating market positioning around efficacy-per-watt metrics. Large-scale vineyard and orchard operators in California and Spain are deploying these configurations across contiguous acreage. The technology is consolidating vendor selection criteria toward integrated solution providers capable of delivering both hardware and pest population analytics.
REACH authorization requirements for pheromone-based attractants are tightening substance approval pathways for European market entry. Manufacturers must now submit comprehensive environmental fate studies to ECHA before commercializing new lure formulations. Greenhouse vegetable producers in the Netherlands and Belgium are accelerating qualification of alternative biological attractants to preempt supply disruption.
Equipment-as-a-service contracting is displacing outright purchase arrangements among mid-scale agricultural cooperatives. Brazilian citrus growers and Vietnamese dragon fruit exporters are piloting per-hectare subscription models that bundle trap deployment, maintenance, and efficacy monitoring. This shift transfers capital burden to vendors while locking in multi-season customer relationships through performance guarantees.
Solar Insect Trap Market Segmentation
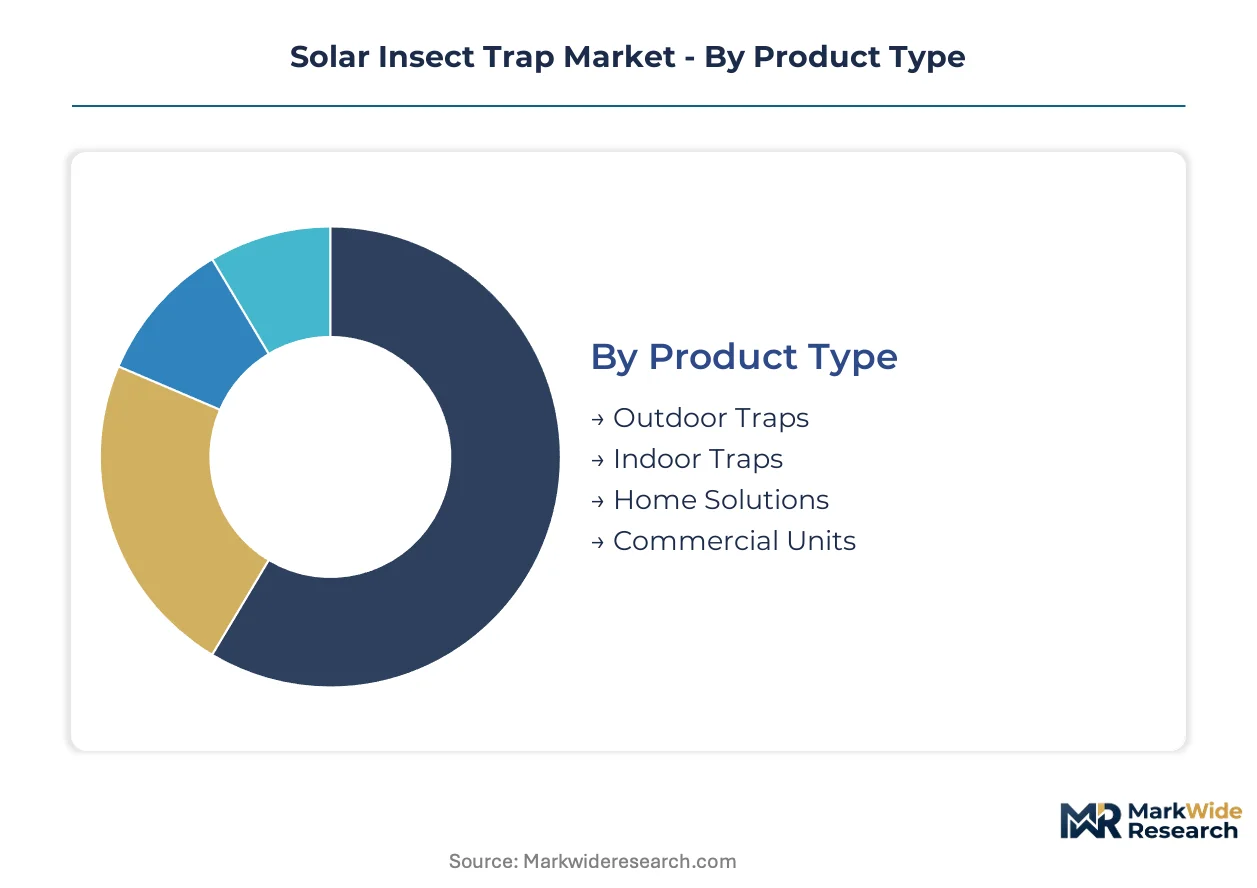
Product architecture and deployment context determine procurement economics in solar insect trap markets. Buyers prioritize capture efficiency per unit energy cost, spectral tuning flexibility, and compliance documentation for residue-sensitive export channels.
Product Type:
Application scale and environmental exposure dictate enclosure specifications and photovoltaic array sizing across buyer segments.
- Outdoor Traps:These units integrate weather-rated housings with high-capacity electrocution grids and expandable solar panel surfaces for open-field deployment. Demand concentrates among Maharashtra and Gujarat fruit and vegetable growers seeking chemical-free compliance under EU Farm to Fork residue thresholds.
- Commercial Units:Designed for contiguous acreage coverage with centralized monitoring capabilities, these systems support per-hectare service contracting models. California vineyard operators and Spanish orchard managers are consolidating procurement around integrated solution providers offering population analytics alongside hardware.
- Indoor Traps:Compact units with adhesive capture surfaces target controlled-environment agriculture and food processing facilities requiring zero-residue protocols.
- Home Solutions:Consumer-grade devices with simplified UV LED arrays and reduced pheromone capacity serve residential garden markets with limited technical support infrastructure.
Volume sits with Outdoor Traps; growth tilts toward Commercial Units.
Technology:
Energy autonomy and attractant integration separate premium configurations from commodity alternatives in vendor portfolios.
- Hybrid Systems:Combining photovoltaic generation with pheromone dispensers and multi-spectral LED arrays, these configurations maximize capture efficiency per watt. Dutch and Belgian greenhouse vegetable producers are accelerating qualification to preempt REACH authorization disruptions for conventional attractants.
- Solar-Powered:Standalone units with battery storage and UV LED emission at 365-395 nanometer wavelengths exploit phototactic responses in lepidopteran pests. Indian agricultural cooperatives leverage PLI scheme subsidies to compress capital recovery timelines for price-sensitive field deployment.
- Attractant-Based:Systems relying on biological lures without electrocution grids face tightening ECHA environmental fate study requirements for European market entry.
- Electric:Grid-dependent units with reduced photovoltaic content serve peri-urban applications with reliable infrastructure and lower sun-hour profiles.
Procurement concentrates on Solar-Powered configurations; margin expansion tracks Hybrid Systems.
Application:
Residue limit stringency and export market access requirements shape deployment intensity across use cases.
- Agricultural Fields:Large-scale open deployment across row crops and orchards dominates unit volumes, with Brazilian citrus growers and Vietnamese dragon fruit exporters piloting subscription-based service models.
- Greenhouses:Controlled-environment operators in the Netherlands prioritize residue-free compliance for premium export segments, driving fastest adoption velocity among application categories.
- Residential Gardens:Fragmented demand across homeowner segments with limited technical calibration support degrades realized efficacy and repeat purchase rates.
- Industrial Areas:Food processing and storage facilities deploy traps as component of integrated pest management audits for third-party certification maintenance.
Revenue aggregates in Agricultural Fields; adoption velocity peaks in Greenhouses.
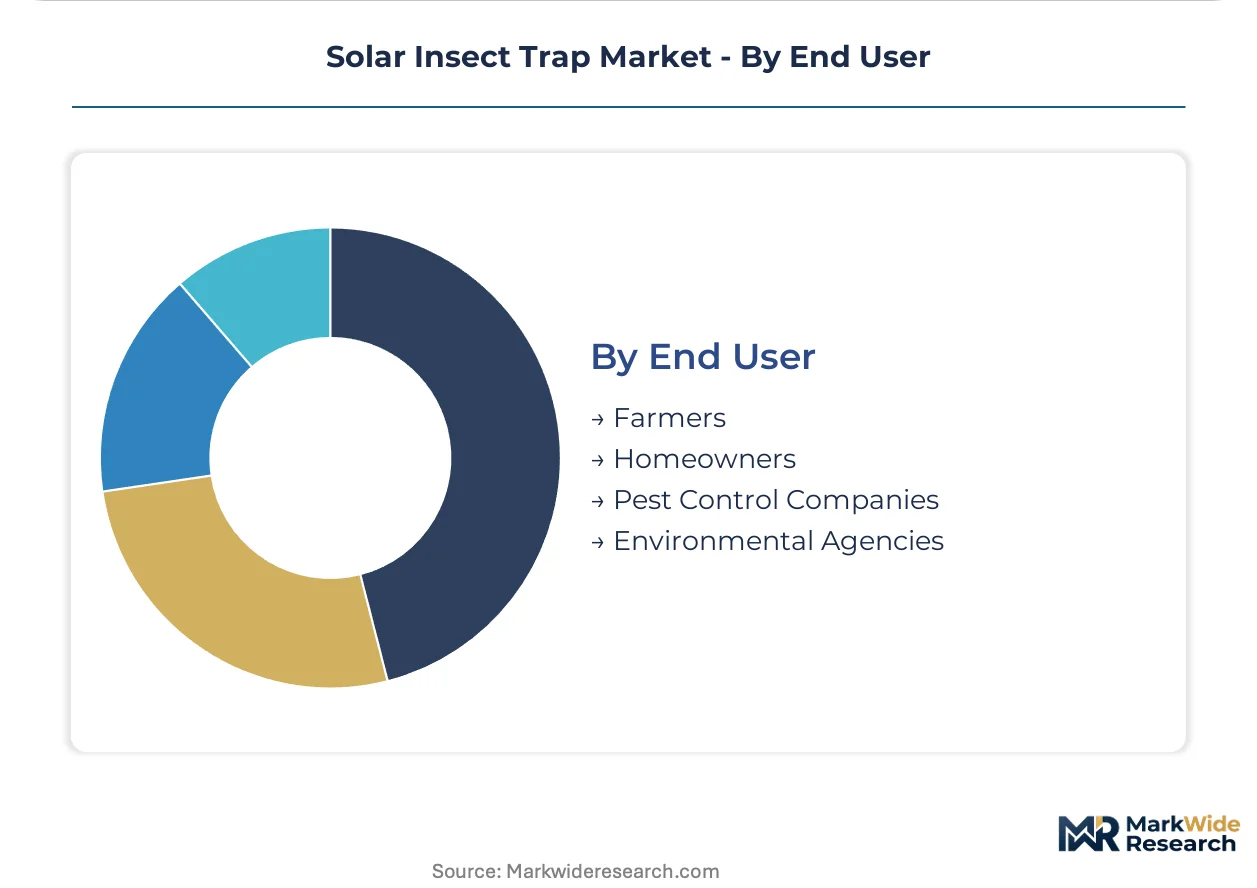
End User:
Technical expertise availability and capital structure determine service model preferences and vendor selection criteria.
- Farmers:Direct procurement by export-oriented producers with entomological staff drives demand for IoT-enabled predictive monitoring and spectral tuning capabilities.
- Pest Control Companies:Rentokil Initial and similar operators anchor technology-led service contracts with performance guarantees, transferring capital burden from agricultural cooperatives.
- Homeowners:Price-sensitive segment with high return rates due to suboptimal placement and lack of field calibration expertise.
- Environmental Agencies:Public procurement for ecological monitoring and invasive species surveillance programs with standardized efficacy documentation requirements.
Contract value concentrates with Pest Control Companies; unit volume flows through Farmers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photovoltaic module manufacturing clusters in Jiangsu and Anhui provinces supply solar panel components to trap assemblers worldwide. Regional demand patterns diverge sharply between export-oriented horticulture belts and domestic food security zones.
United States
California vineyard operators deploy commercial solar trap arrays across contiguous acreage to meet Whole Foods and Costco residue specifications. The EPA regulates pesticidal device claims under FIFRA, requiring efficacy documentation for interstate commerce. Central Valley processing tomato growers are consolidating procurement around integrated pest management service contracts.
India
Maharashtra and Gujarat fruit exporters seek chemical-free compliance for EU-bound pomegranate and mango shipments. The CEA photovoltaic standards and BIS electronic equipment requirements create dual certification pathways that extend product launch timelines. Anand and Nashik districts host demonstration farms where cooperatives pilot per-hectare subscription models.
Netherlands
Greenhouse vegetable producers in Westland prioritize residue-free protocols for premium German and Scandinavian retail channels. REACH authorization requirements for pheromone-based attractants are tightening substance approval pathways through ECHA. Wageningen University research clusters accelerate qualification of alternative biological lures to preempt supply disruption.
Spain
Valencian citrus cooperatives and Catalan vineyard associations deploy hybrid solar-attractant systems across Mediterranean horticulture belts. The EU Green Deal's Farm to Fork Strategy mandates pesticide reduction targets that reshape procurement standards for export-oriented producers. Murcia's intensive agriculture zone concentrates deployment of IoT-enabled predictive monitoring arrays.
Brazil
São Paulo state citrus growers and Minas Gerais coffee cooperatives pilot equipment-as-a-service contracting to transfer capital burden from agricultural operators. ANVISA maintains residue limit protocols that determine substitution economics between chemical applications and solar trapping. Piracicaba research stations field-test spectral tuning configurations for lepidopteran pest populations.
Solar Insect Trap Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue IoT-enabled predictive monitoring and per-hectare service contracting. The vendor base spans photovoltaic component fabricators, agrochemical distributors repositioning around integrated pest management, and specialized trap manufacturers. Three archetypes dominate: Chinese module suppliers extending downstream, European greenhouse technology specialists, and agricultural equipment assemblers leveraging India's PLI subsidies. Competitive moves center on hardware-software convergence and backward integration into battery storage systems.
Within the agrochemical repositioning tier, Syngenta leverages its distribution networks to bundle solar trap solutions alongside conventional portfolios. Among facility services operators, Rentokil Initial anchors technology-led agricultural contracts with performance-guaranteed deployment models. Chinese fabricators exemplify the component-to-system expansion pattern, with Zhengzhou-based and Jiangsu-based producers representing the photovoltaic supply anchor archetype.
| Leading Market Players |
|---|
| Sickle Innovations Private Limited |
| Vinspire Agrotech (I) Private Limited |
| Vinglob Greentech Pvt Ltd |
| Marker Electronic Equipments |
| PNGR Ever Green Technology |
| Syngenta |
| PIC Corporation |
| Rentokil Initial |
| Thermacell |
| Others |
Pricing and Supply Chain Analysis
Photovoltaic engineering talent concentrated in Jiangsu and Anhui provinces feeds labor-cost differentials that separate premium hybrid system pricing from economy-grade standalone units. Warranty bundling and field calibration services widen spreads between vendor tiers as buyers weigh capital recovery against operational risk.
Pricing Analysis
Warranty and maintenance bundling separates premium vendor offerings from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EPA FIFRA documentation requirements and BIS electronic equipment standards. Cost compression in the economy tier intensifies as Chinese module manufacturers expand downstream. Export-oriented greenhouse operators in the Netherlands and Belgium show least price sensitivity; Indian agricultural cooperatives leveraging PLI subsidies exhibit highest elasticity.
Supply Chain Analysis
Direct-to-farm channels handle hyperscale buyer demand across contiguous California vineyard acreage and Spanish orchard associations. Photovoltaic module fabrication concentrates in China, battery cell production in South Korea and Japan, and pheromone synthesis in Switzerland and the Netherlands. Lithium-ion cell sourcing, UV LED arrays, and weather-rated enclosure materials anchor material dependencies. Single-source vulnerability in East Asian battery supply exposes assemblers to logistics bottlenecks. Distribution runs through agrochemical distributor networks and specialized agricultural equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated solution providers as hardware-software convergence eliminates pure-play component vendors. REACH authorization tightening for pheromone attractants and IoT platform development costs force weaker assemblers toward exit.
For Market Incumbents: Hedge against pure-play hardware commoditization by acquiring predictive analytics capabilities or partnering with farm management software platforms. Backward integration into lithium-ion battery pack assembly reduces exposure to East Asian cell supply volatility. Prioritize BIS and CEA dual certification completion to defend Indian market positioning against PLI-subsidized domestic entrants.
For New Entrants and Emerging Players: The mid-tier price gap between Syngenta-integrated premium systems and unbranded economy traps creates white-space for subscription-based per-hectare service models. Target Brazilian citrus cooperatives and Vietnamese dragon fruit exporters piloting equipment-as-a-service contracting. Penetrate through pest control company partnerships rather than direct farmer sales to bypass field calibration expertise scarcity.
For Investors and Strategic Acquirers: Re-rating potential sits with IoT-enabled predictive monitoring specialists given hardware-software convergence reshaping vendor selection criteria. Long-term viability favors integrated solution providers capable of delivering population analytics alongside trap hardware. Acquisition target archetype: European greenhouse technology specialists with REACH-compliant attractant portfolios. Watch ECHA authorization timelines for biological lure substances as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Trap-mounted sensors feeding farm management software command recurring revenue relationships beyond hardware sales. |
| Backward Integration into Battery Storage | In-house lithium-ion pack assembly reduces exposure to East Asian cell supply concentration and logistics bottlenecks. |
| REACH Authorization Pathway | ECHA-compliant pheromone attractant portfolios secure European market access as conventional lure approvals tighten. |
| Per-Hectare Service Contracting | Equipment-as-a-service models transfer capital burden from agricultural cooperatives while locking multi-season relationships. |
| Dual Certification Investment | Simultaneous BIS electronic and CEA photovoltaic compliance compresses product launch timelines for Indian market entry. |
Research Methodology
Independent corroboration across agrochemical distributor interviews, greenhouse operator procurement panels, and photovoltaic component manufacturer disclosures underwrites the qualitative findings. Primary fieldwork engaged trap assemblers, entomological calibration specialists, agricultural cooperative managers, and pest control service contract officers. Secondary validation drew from EPA FIFRA registration databases, ECHA REACH authorization filings, Indian CEA photovoltaic standards documentation, and EU Farm to Fork Strategy implementation reports. Bottom-up unit deployment estimates triangulated against top-down addressable acreage calculations.
Comparable-period anchoring matched historical deployment trajectories in California vineyard and Spanish orchard markets against emerging adoption curves in Indian Maharashtra fruit belts and Brazilian citrus zones. The analytical framework modeled segmentation across product architecture, attractant technology, application environment, and end-user technical sophistication. CAGRs were derived from slope-consistent growth pattern matching across analogous agricultural mechanization adoption curves. Forecast inputs incorporated PLI subsidy phase-in effects and EU Green Deal residue threshold implementation pacing.
Inputs from ECHA authorization timelines and Indian PLI scheme disbursement records were available through the study window; gaps in real-time farm-level efficacy monitoring data introduce uncertainty bands around adoption velocity assumptions. Forecasts reflect documented base-case assumptions regarding photovoltaic cost deflation continuity and pheromone supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Global Yield Monitoring Devices Market