
 Intelligent Milking Robot Market | 2026-2036
Intelligent Milking Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Milking Robot Market Insights
Large enterprise dairy operations is decoupling from traditional smallholder demand as the primary growth vector for intelligent milking systems. DeLaval leverages its vertical integration across hardware and herd management software to sustain premium positioning in automated parlors. Lely anchors its competitive stance through specialized focus on free-flow robotic units, while GEA Group Aktiengesellschaft competes via manufacturing scale in centralized milking infrastructure for industrial farms.
Intelligent milking robots are electromechanical systems integrating optical sensors, pneumatic teat cups, and machine learning algorithms to execute unsupervised milking cycles with real-time somatic cell monitoring and automated cleaning protocols. Their primary commercial purpose is to replace manual labor in dairy parlors while capturing individual-cow yield data for precision herd management. Automatic milking systems dominate current installed base value due to proven reliability in 24/7 operations, though robotic milking units represent the fastest-growing product category as sensor miniaturization reduces per-stall capital requirements. Software-controlled systems increasingly concentrate margin pools through recurring subscription revenue tied to predictive health analytics and breeding optimization tools.
FDA dairy equipment sanitation standards and the EU's CE marking requirements for agricultural machinery shape product development timelines and cross-border market access for equipment manufacturers. The EU Green Deal's methane reduction targets and national farm sustainability audits in Germany and France are accelerating replacement of conventional parlors with sensor-rich robotic systems that document environmental compliance. Stakeholders must monitor how evolving animal welfare certification schemes and carbon accounting rules reshape procurement criteria for dairy cooperatives evaluating capital-intensive automation investments.
Market Dynamics
Labor scarcity across dairy belts is forcing capital substitution at unprecedented velocity. The EU Green Deal's methane mandates and national farm sustainability audits are compressing replacement cycles for conventional parlors.
Growth Catalysts
- EU Farm to Fork Strategy:Binding animal welfare and emissions standards under the European Green Deal compel Dutch and German cooperatives to document compliance through sensor-rich robotic systems.
- Optical sensor miniaturization:Teat-detection cameras and machine-learning vision systems are cutting per-stall capital requirements, opening robotic units to mid-scale operations previously priced out.
- Netherlands dairy clustering:Dense cooperative networks in Friesland and Overijssel generate concentrated upgrade cycles as early-adopter farms trigger competitive replacement among neighbors.
Market Restraints
- Stainless steel and semiconductor input costs:Volatility in pneumatic component supply chains and chip shortages inflate manufacturing lead times for teat-cup assemblies and control modules.
- CE marking complexity:Agricultural machinery certification under EU machinery directives creates cross-border friction, with divergent national interpretations delaying market access for non-EU manufacturers.
- Conventional parlor durability:Existing herringbone and rotary infrastructure delivers decades of service life, stretching replacement cycles and diluting near-term addressable demand.
Strategic Opportunities
- Carbon accounting integration:The EU's CSRD disclosure requirements position robotic systems as compliance infrastructure, with per-cow methane monitoring becoming a procurement criterion for sustainability-certified dairies.
- Predictive health analytics subscriptions:Software layers atop milking hardware capture recurring revenue through somatic cell trend alerts and breeding optimization tools.
- Free-flow robotic penetration:Voluntary cow traffic systems are gaining traction in pasture-based operations across Ireland and New Zealand, displacing forced-traffic designs.
Industry Challenges
- Electro-mechanical technician scarcity:Dairy regions lack sufficient service capacity for pneumatic, optical, and software-integrated repair, stretching response times for 24/7 operations.
- Legacy herd management integration:Proprietary data protocols from incumbent software vendors block seamless data portability, forcing costly middleware development or siloed system operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Milking Robot Market |
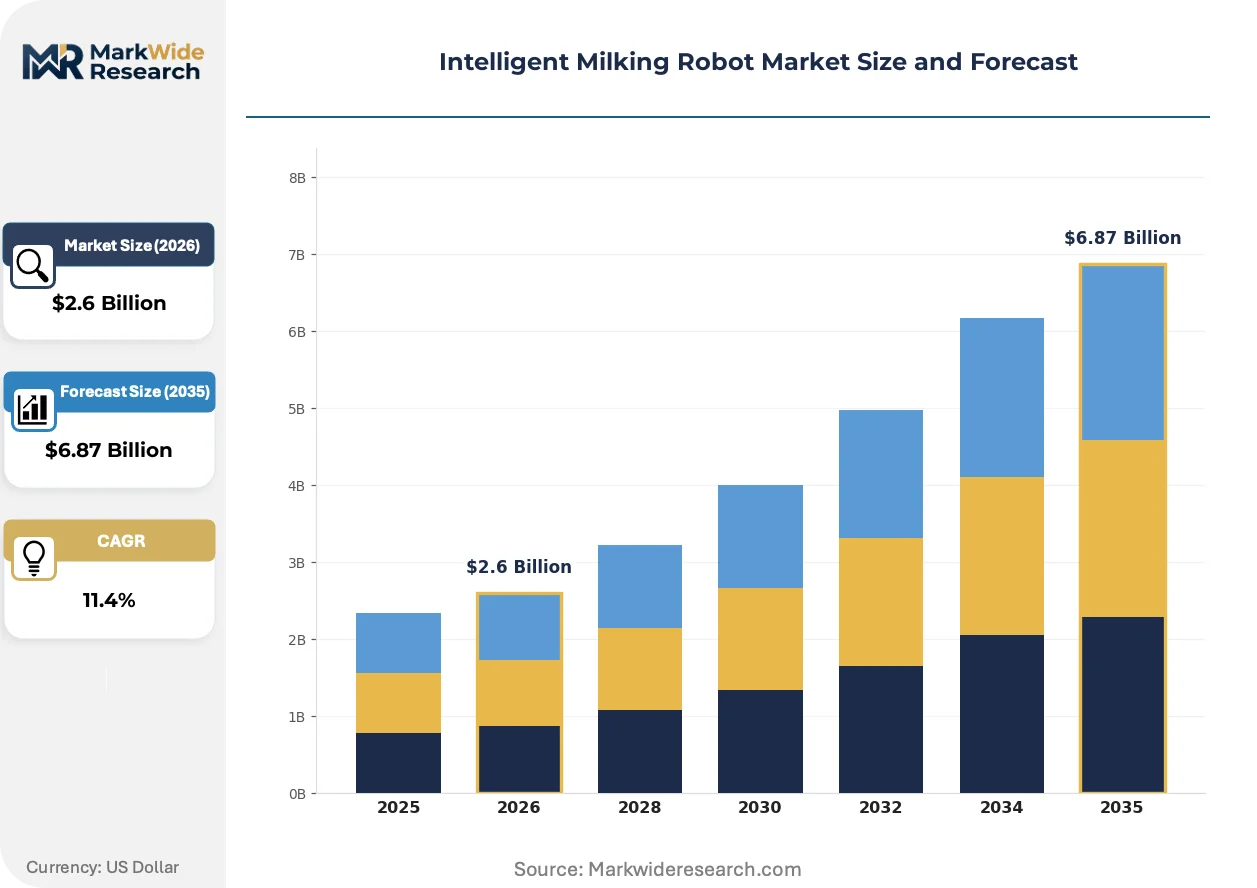
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Milking Systems, Robotic Milking Units, Centralized Milking Solutions, Software-Controlled Systems End User: Dairy Farms, Co-operative Farms, Large Enterprises, Smallholder Farmers Technology: Machine Learning, Sensor Technology, Real-Time Monitoring, Data Analytics Installation: On-Farm Installations, Off-Farm Installations, Retrofitting Services, Turnkey Solutions |
| Companies Covered | DeLaval, GEA Group Aktiengesellschaft, Lely, DAIRYMASTER, BouMatic, Fullwood Packo, Afimilk Ltd, S.A. Christensen & Co., Hokofarm Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Milking Robot Market Trends and Innovations
Sensor fusion and edge computing are compressing the latency between biological event and mechanical response. Three developments are restructuring how milking infrastructure is specified, financed, and serviced.
Machine-vision teat-detection systems are automating the spatial mapping and attachment process that previously required human judgment. Large commercial dairies in Denmark and Wisconsin are deploying these systems at scale, replacing manual pre-dipping and cup-attachment labor. The technology is automating workforce reduction while capturing subclinical mastitis signals days before visible symptoms emerge.
The EU AI Act's risk-classification framework for agricultural automation is reshaping product development timelines. High-risk system designations for autonomous livestock handling trigger conformity assessment burdens that extend certification cycles by 8-14 months. German and French equipment manufacturers are front-loading documentation and algorithmic transparency requirements into R&D roadmaps to preempt regulatory delay.
Dairy cooperatives are unbundling capital expenditure from operational technology ownership. Equipment-as-service models spread across the Netherlands and Belgium, with per-liter milking fees replacing upfront hardware purchases. This restructuring concentrates financial risk with manufacturers while accelerating adoption among capital-constrained farms in Friesland's cooperative networks.
Intelligent Milking Robot Market Segmentation
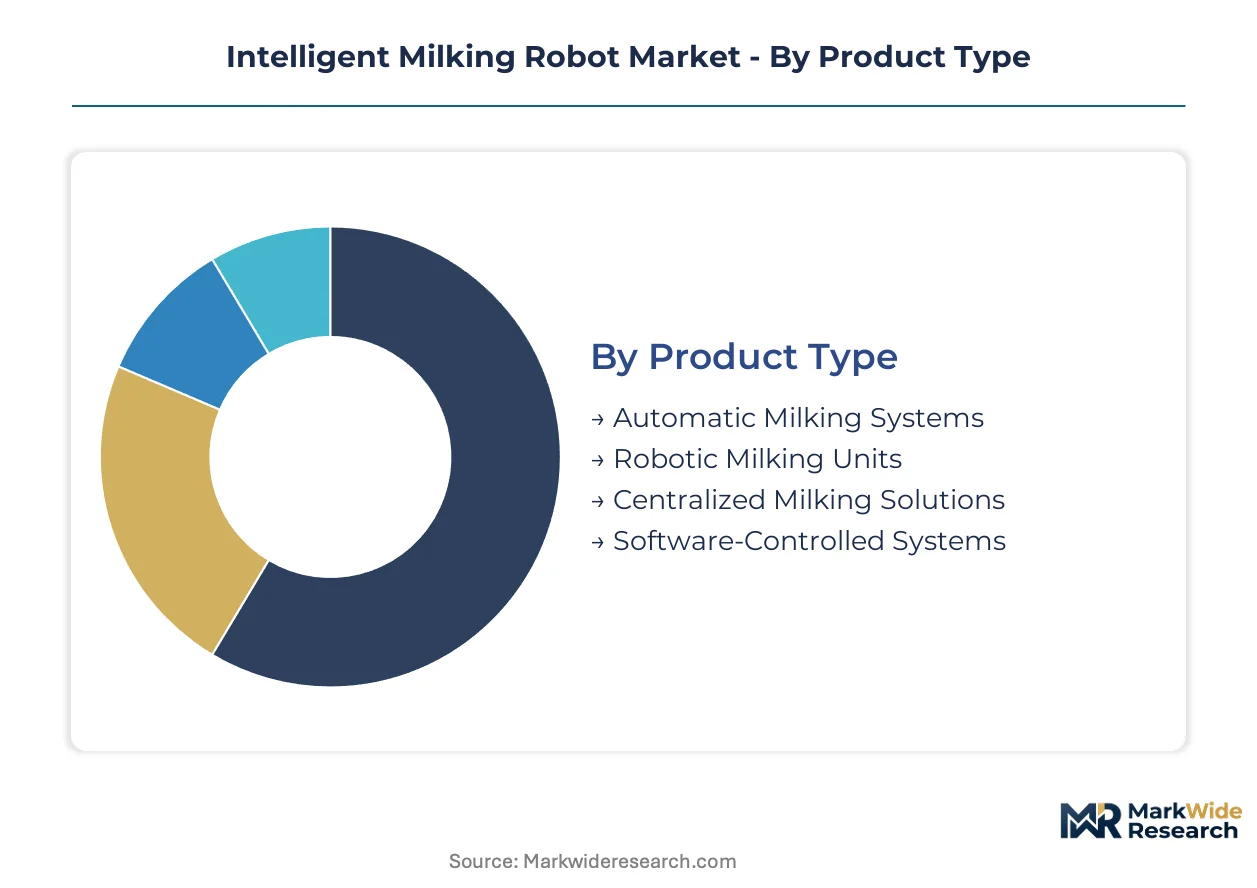
Segmentation in intelligent milking robots reveals how capital deployment, labor substitution needs, and data monetization opportunities split across farm scales and technology architectures. Understanding these divisions exposes where margin pools concentrate and which integration models win in saturated versus emerging dairy belts.
Product Type:
Standalone installations dominate high-volume operations, while embedded configurations penetrate mid-scale farms seeking modular upgrade paths without full infrastructure replacement.
- Automatic Milking Systems:These electromechanical platforms integrate rotary or parallel parlor designs with automated gate controls and milk metering. Dutch cooperative networks in Friesland concentrate replacement demand here as early-adopter farms trigger competitive upgrade cycles among neighbors.
- Robotic Milking Units:Free-flow and forced-traffic single-box designs deploy machine-vision teat detection and pneumatic cup attachment for unsupervised 24/7 operation. German and French sustainability audits under the EU Green Deal accelerate specification of these sensor-rich systems for methane documentation compliance.
- Centralized Milking Solutions:Industrial-scale rotary infrastructure serving 500+ cow herds with synchronized vacuum systems and bulk cooling integration.
- Software-Controlled Systems:Subscription-based herd management layers capturing recurring revenue through predictive health analytics and breeding optimization tools.
Automatic Milking Systems lead volumes today; Software-Controlled Systems are gaining share fastest.
End User:
Capital intensity and labor availability create divergent procurement patterns across farm ownership structures, with cooperative networks amplifying technology diffusion through peer effects.
- Dairy Farms:Family-owned operations with 50-200 cows represent the core installed base for first-generation robotic retrofits. Irish pasture-based producers increasingly specify free-flow voluntary traffic designs as labor scarcity intensifies.
- Co-operative Farms:Dense clustering in the Netherlands generates concentrated upgrade cycles through shared technical service capacity and bulk purchasing leverage. Belgium's equipment-as-service models spread fastest through these networks, replacing upfront capital expenditure with per-liter milking fees.
- Large Enterprises:Industrial-scale operations with 1000+ cow herds deploy centralized rotary systems with integrated carbon accounting for CSRD disclosure requirements.
- Smallholder Farmers:Capital constraints and long replacement cycles for existing herringbone parlors limit near-term penetration despite falling per-stall costs from sensor miniaturization.
Co-operative Farms anchor current revenue concentration; Large Enterprises show the steepest expansion trajectory as carbon compliance hardens procurement criteria.
Technology:
Hardware-software integration depth determines margin capture, with edge-computing architectures reducing latency between biological events and mechanical responses.
- Machine Learning:Vision algorithms for teat identification and attachment optimization run on embedded GPUs within robotic arm controllers. Wisconsin and Denmark dairies deploy these at scale for workforce reduction and subclinical mastitis detection.
- Sensor Technology:Optical cameras, pneumatic pressure transducers, and milk conductivity probes generate real-time somatic cell data. The EU AI Act's high-risk system designation for autonomous livestock handling extends certification cycles for manufacturers integrating these sensor fusion stacks.
- Real-Time Monitoring:Continuous vacuum level and milk flow telemetry enabling immediate intervention alerts.
- Data Analytics:Cloud-based trend analysis for herd-level productivity optimization and genetic selection support.
Sensor Technology commands the largest current spend; Machine Learning is climbing the fastest as algorithmic transparency requirements reshape R&D roadmaps.
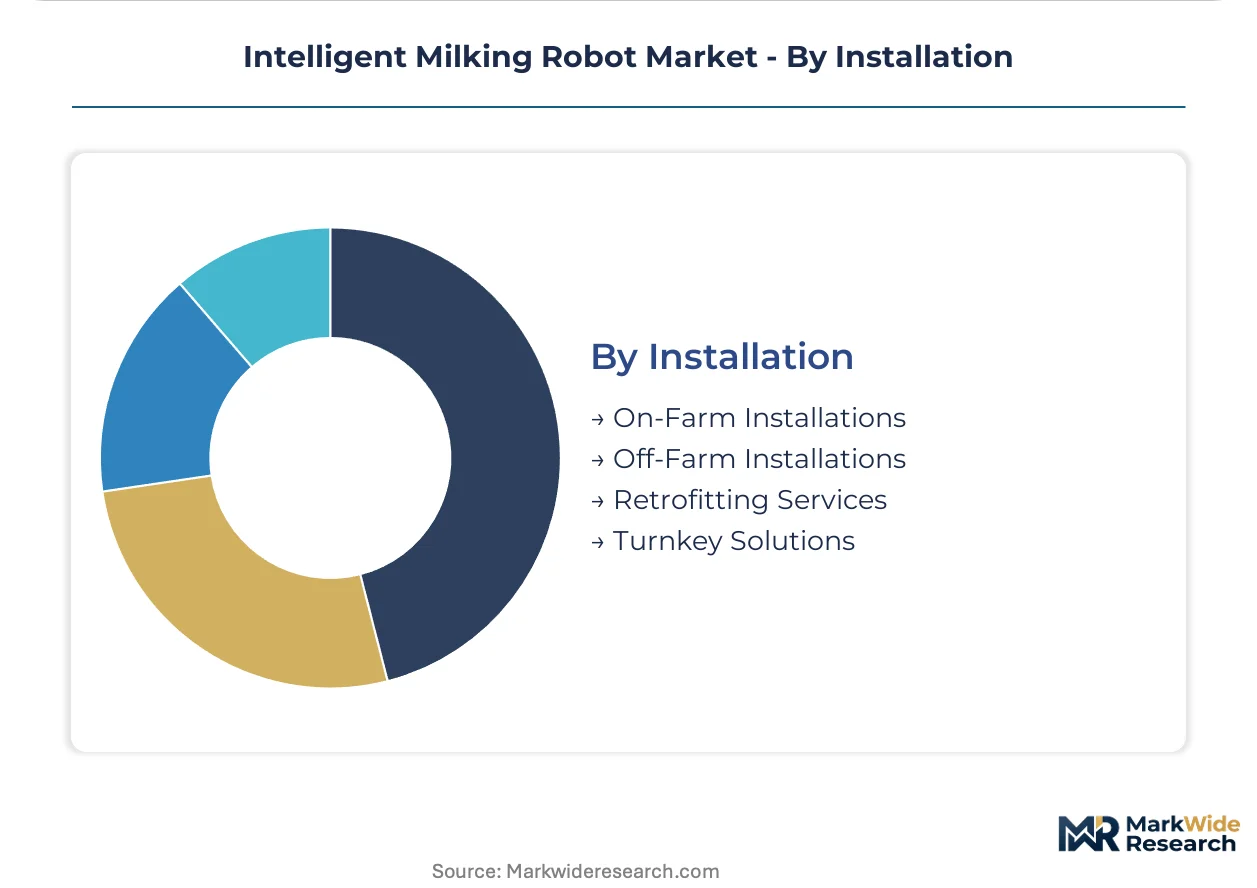
Installation:
Service model unbundling is restructuring capital ownership, with manufacturers absorbing financial risk to accelerate adoption among liquidity-constrained operations.
- On-Farm Installations:Greenfield construction of dedicated milking facilities with customized stall layouts and utility integration. German manufacturers front-load CE marking documentation to preempt cross-border friction under EU machinery directives.
- Retrofitting Services:Conversion of existing herringbone and rotary parlors with robotic box additions or automated gate systems. This segment penetrates mid-scale operations previously priced out of full replacement as optical sensor miniaturization cuts per-stall capital requirements.
- Off-Farm Installations:Mobile or shared-use milking infrastructure serving multiple small producers.
- Turnkey Solutions:Design-build-operate contracts bundling hardware, software, and maintenance under long-term service agreements.
On-Farm Installations retain volume leadership; Retrofitting Services are expanding most quickly as conventional parlor durability stretches replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Friesland's cooperative dairy networks in the Netherlands concentrate the densest installed base of intelligent milking infrastructure. Labor scarcity and emissions compliance are accelerating capital deployment across distinct national dairy belts.
Netherlands
Dutch cooperative farms in Friesland and Overijssel trigger concentrated replacement cycles through peer-effect technology diffusion. The EU Farm to Fork Strategy binds these operations to document animal welfare and methane compliance via sensor-rich robotic systems. Equipment-as-service models spread fastest through Randstad and Brabant networks, replacing upfront hardware purchases with per-liter milking fees.
Germany
German dairy enterprises face compressed replacement cycles for conventional parlors under national farm sustainability audits. The EU Green Deal's methane reduction targets position robotic systems as mandatory compliance infrastructure in Bavaria and Lower Saxony. Baden-Württemberg manufacturers front-load CE marking documentation to preempt cross-border friction under EU machinery directives.
United States
Large commercial dairies in Wisconsin deploy machine-vision teat-detection systems at scale for workforce reduction and subclinical mastitis detection. FDA dairy equipment sanitation standards shape product development timelines for cross-border market access. The Pacific Northwest and Midwest dairy belts show accelerating specification of free-flow voluntary traffic designs as labor scarcity intensifies.
France
French sustainability audits under the EU Green Deal accelerate specification of sensor-rich systems for methane documentation compliance. The EU AI Act's high-risk system designation for autonomous livestock handling extends certification cycles for manufacturers integrating sensor fusion stacks. Île-de-France and Auvergne-Rhône-Alpes concentrate early-adopter deployment among industrial-scale operations.
New Zealand
Pasture-based producers increasingly specify free-flow voluntary traffic designs as Irish-style labor scarcity patterns emerge. The country's national agricultural regulator enforces equipment standards that favor modular retrofit paths over full infrastructure replacement. Canterbury and Waikato dairy clusters drive concentrated upgrade demand through cooperative technical service networks.
Intelligent Milking Robot Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers absorb financial risk through equipment-as-service models to accelerate adoption. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with captive dairy divisions, specialized robotic automation pure-plays, and precision livestock software vendors. M&A activity and geographic licensing partnerships represent the dominant competitive moves as players secure regional service capacity and algorithmic training data.
Among diversified industrial conglomerates, GEA Group Aktiengesellschaft anchors the scale-driven tier with manufacturing breadth in centralized milking infrastructure. Lely exemplifies the specialized robotic pure-play archetype through focused development of free-flow single-box units. DeLaval occupies a position spanning both hardware integration and recurring software revenue through predictive analytics subscriptions. These three players collectively represent how vertical control across electromechanical systems and data layers concentrates margin capture in saturated dairy belts.
| Leading Market Players |
|---|
| DeLaval |
| GEA Group Aktiengesellschaft |
| Lely |
| DAIRYMASTER |
| BouMatic |
| Fullwood Packo |
| Afimilk Ltd |
| S.A. Christensen & Co. |
| Hokofarm Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal methane mandates and CSRD disclosure requirements are forcing Dutch and German cooperatives to specify sensor-rich robotic systems with embedded carbon accounting, compelling manufacturers to absorb semiconductor and stainless steel volatility into equipment-as-service pricing models rather than pass through spot-market spikes.
Pricing Analysis
Stainless steel and semiconductor input-cost pass-through dominates pricing dynamics for teat-cup assemblies and control modules. Three-tier pricing structure across premium, standard, and economy levels separates DeLaval's integrated software-hardware bundles from Lely's specialized robotic units and GEA's scale-driven centralized infrastructure. Cost compression in mid-scale retrofit segments is intensifying because optical sensor miniaturization cuts per-stall capital requirements while pneumatic component shortages inflate manufacturing lead times. Cooperative farms in Friesland show highest price sensitivity due to equipment-as-service liquidity constraints, while large enterprises in Bavaria demonstrate lowest sensitivity as carbon compliance hardens procurement criteria irrespective of upfront cost.
Supply Chain Analysis
Dual-sourcing requirements for pneumatic pressure transducers and machine-vision cameras are mandatory among Dutch cooperative procurement committees to preempt chip shortage disruptions. Manufacturing concentration centers on Germany, the Netherlands, and Denmark for robotic arm assemblies and control module integration. Raw material dependencies draw from Chinese rare-earth processing for embedded GPU controllers, Swedish stainless steel for teat-cup fabrication, and Taiwanese semiconductor foundries for sensor fusion chips. Single-source vulnerability in EU machinery directive CE marking certification creates cross-border friction for non-EU component suppliers. Distribution runs through cooperative technical service networks in Friesland and Overijssel, with aftermarket parts flowing via manufacturer-direct field technician depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent milking robot market functions as a geographic-arbitrage play where EU regulatory compliance costs in Germany and the Netherlands exceed US Midwest labor-substitution economics by a factor that favors concentrated investment in carbon-accounting-integrated systems.
For Market Incumbents: Hedge against margin erosion from equipment-as-service risk concentration by deepening backward integration into pneumatic component manufacturing and captive sensor calibration facilities in Baden-Württemberg. Lock in cooperative farm network exclusivity through long-term per-liter milking fee contracts that bundle predictive health analytics subscriptions, preempting Lely's free-flow robotic penetration in pasture-based segments. For New Entrants and Emerging Players: Machine-vision algorithm specialization for subclinical mastitis detection offers a technology-first wedge into mid-scale Irish pasture operations where labor scarcity intensifies but DeLaval's premium positioning leaves price-accessible gaps. Target retrofit services for existing herringbone parlors in New Zealand's Canterbury cluster, deploying modular robotic box additions under turnkey design-build-operate contracts that circumvent capital constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with precision livestock software vendors possessing training datasets from 10,000+ cow herds and existing API integrations with incumbent hardware platforms. Five-to-ten-year viability hinges on algorithmic transparency compliance under the EU AI Act's high-risk system designation. Watch for inflection in German sustainability audit enforcement intensity as the signal that carbon-accounting-integrated procurement becomes mandatory rather than discretionary.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-Service Model Expansion | Concentrates financial risk with manufacturers while accelerating adoption among liquidity-constrained Friesland cooperatives. |
| Sensor Fusion Stack Certification | EU AI Act high-risk system designation extends CE marking cycles by 8-14 months for algorithmic transparency compliance. |
| Carbon Accounting Integration | CSRD disclosure requirements position robotic systems as mandatory compliance infrastructure for German sustainability audits. |
| Retrofit Services Penetration | Optical sensor miniaturization cuts per-stall capital requirements, opening mid-scale operations previously priced out of full replacement. |
| Predictive Health Analytics Subscription | Recurring revenue capture through somatic cell trend alerts and breeding optimization tools shifts margin pools toward software layers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with dairy cooperative procurement managers, robotic equipment maintenance technicians, herd management software developers, and agricultural machinery CE marking consultants with secondary validation against EU Farm to Fork Strategy documentation, FDA dairy equipment sanitation standards filings, SEC 10-K disclosures from diversified industrial conglomerates, and Dutch agricultural census data on Friesland cooperative network scale. Bottom-up installed base modeling and top-down addressable market sizing triangulated volume estimates.
Segment-weighting across product type, end user, technology, and installation dimensions structured the analytical framework over the projection horizon. Automatic milking systems, robotic milking units, centralized milking solutions, and software-controlled systems each carried distinct growth assumptions based on sensor miniaturization cost curves and regulatory compliance deadlines. CAGRs derived from replacement cycle compression under labor scarcity and methane mandate pressures, with cross-elasticity between retrofit services and greenfield installations modeled against conventional parlor durability assumptions.
The model holds under sustained EU Green Deal enforcement and semiconductor supply normalization; deviation in CE marking directive interpretation or pneumatic component trade restriction would shift the outlook materially. Deviation in cooperative farm network liquidity constraints or pasture-based free-flow design adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Battery Powered Sprayer Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Global Subsoiler Market