
 Rotavator Market | 2026-2036
Rotavator Market Size, Share, and Industry Trends Forecast 2026-2036
Rotavator Market Outlook
India's PLI scheme for farm mechanization is hardening demand for domestically produced tillage equipment. Maschio Gaspardo leverages its Italian engineering heritage to compete in premium mounted segments across European vineyards. Mahindra & Mahindra Ltd. anchors its position through extensive dealer networks spanning rural India. Kubota Corporation differentiates via compact rotavator lines tailored to East Asian horticulture.
A rotavator is a rotary tillage implement employing horizontally mounted blades on a central shaft, typically operating at 200-400 RPM to pulverize soil to depths of 15-25 centimeters for seedbed preparation. The device mechanically breaks clods, incorporates crop residue, and levels terrain to optimize planting conditions. Mounted rotavators dominate sales volumes due to lower capital outlay and compatibility with existing tractor fleets, while autonomous units represent the fastest-growing category as labor costs rise and precision agriculture protocols expand. PTO-driven systems sustain the largest installed base, though electric power sources are gaining traction in peri-urban landscaping applications where emission restrictions tighten.
India's BIS certification mandates blade safety guards and drive shaft shields, compelling design modifications that add manufacturing cost but reduce liability exposure. The EU Machinery Directive and CE marking requirements govern export access for Indian and Chinese manufacturers, creating compliance barriers that favor established European brands. Stakeholders must monitor evolving powertrain electrification standards and residue management regulations that will reshape product development priorities and aftermarket service architectures.
Market Dynamics
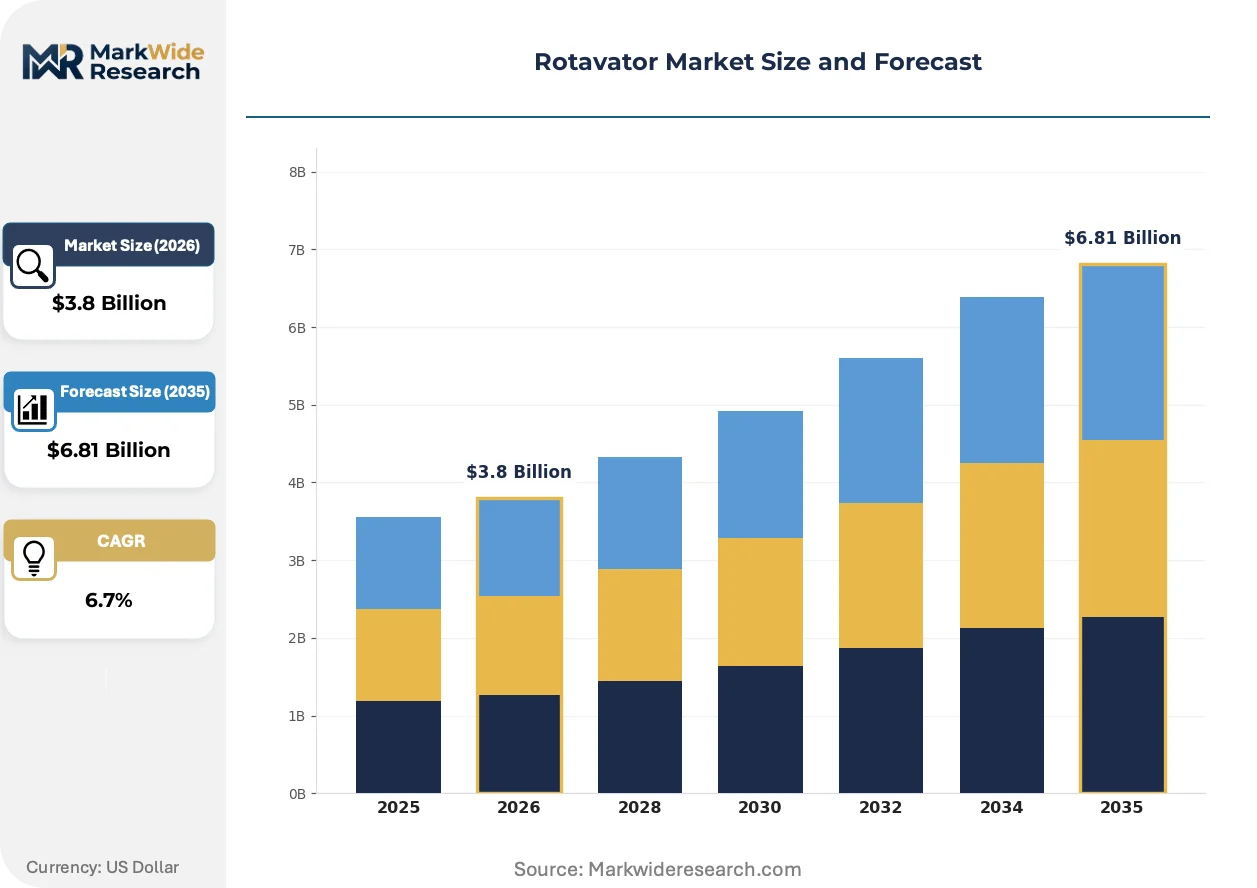
India's PLI scheme for farm mechanization is concentrating manufacturing capacity within its borders, while Brazil's soybean expansion and Southeast Asia's smallholder consolidation create divergent demand profiles for PTO-driven versus compact electric units.
Growth Catalysts
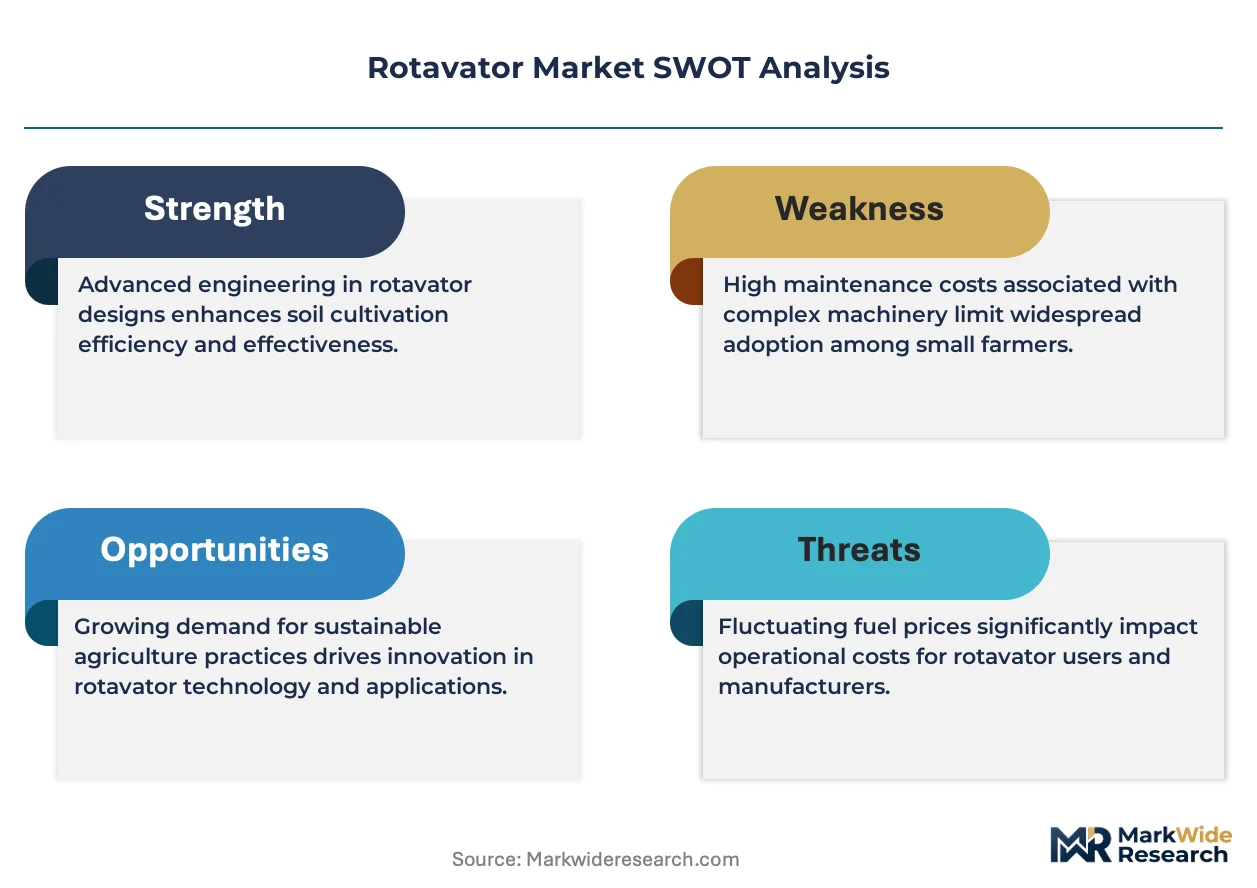
- India's PLI scheme:Production-linked incentives for farm mechanization harden domestic manufacturing of tillage equipment. The policy reduces import dependency for blade assemblies and gearboxes.
- Precision agriculture protocols:Autonomous rotavator adoption accelerates as labor costs rise in East Asian horticulture. Sensor-integrated units enable depth-controlled tillage for specialty crop beds.
- Brazil's soybean belt:Heavy-duty PTO-driven demand concentrates in Mato Grosso and Paraná as farm sizes expand. Double-cropping intensity requires residue incorporation at scale.
Market Restraints
- High-grade alloy steel volatility:Blade material costs fluctuate with nickel and chromium supply from South African and Indonesian concentrate markets. Foundry energy costs add margin pressure.
- EU Machinery Directive compliance:CE marking requirements for blade guards and emergency stops create export barriers for Indian and Chinese manufacturers. Testing timelines extend market entry by 8-14 months.
- Used equipment arbitrage:Refurbished European and Japanese tractors with attached rotavators flood secondary markets in Africa and Central Asia. Price undercutting limits new equipment penetration.
Strategic Opportunities
- Peri-urban landscaping electrification:Battery-powered compact units gain traction in European and North American municipalities with emission restrictions. Noise ordinances favor electric drivetrains for residential applications.
- Vietnam's Mekong Delta consolidation:Smallholder cooperative formation creates pooled procurement of mounted rotavators. Shared equipment models reduce individual capital barriers.
- Residue management mandates:India's Commission for Agricultural Costs and Prices incentivizes straw incorporation. Rotavator-based stubble management displaces burning in Punjab and Haryana.
Industry Challenges
- PTO speed standardization gaps:Tractor output shaft ratings vary across 540/720/1000 RPM configurations. Gearbox redesign requirements fragment product lines and inventory.
- Aftermarket service network density:Blade replacement and bearing maintenance demand technician availability in rural catchments. Dealer coverage gaps in Bihar and eastern Uttar Pradesh delay repair cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotavator Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mounted, Trailed, Autonomous, Mini End Use Industry: Agriculture, Horticulture, Landscaping, Forestry Power Source: PTO, Diesel, Electric, Gasoline Size: Small, Medium, Large, Heavy Duty |
| Companies Covered | Maschio Gaspardo, Yanmar Co., Ltd., Mahindra & Mahindra Ltd., Shaktiman, Tractors and Farm Equipment Ltd., Kubota Corporation, CLAAS, AGCO Corporation, John Deere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotavator Market Strategic Shifts
Powertrain electrification and precision depth control are rewriting competitive differentiation in rotary tillage, while regulatory pressure on emissions and residue management reshapes product development priorities across manufacturing bases.
Variable-rate tillage technology is rewriting how seedbed preparation integrates with planting workflows. Sensor-equipped rotavators adjust blade engagement depth based on real-time soil resistance data. Large-scale row-crop operators in Iowa and Illinois adopt these units to reduce fuel consumption and preserve soil structure. The technology is compressing the traditional separation between tillage and planting equipment decisions.
India's BIS certification mandates for blade safety guards and drive shaft shields took full effect in recent compliance cycles. The standards compel design modifications that add manufacturing cost but reduce liability exposure for domestic producers. Export-oriented manufacturers in Ludhiana and Pune have retooled stamping and welding lines to meet these specifications, creating capability spillovers for CE-marked production.
Equipment-as-a-service models are emerging in European vineyard and orchard operations. French and Italian wine cooperatives now lease compact rotavators with seasonal maintenance bundled, displacing traditional ownership. The shift transfers blade wear risk to OEMs and concentrates procurement decisions among fewer technical buyers with multi-year contracting authority.
Rotavator Market Segmentation
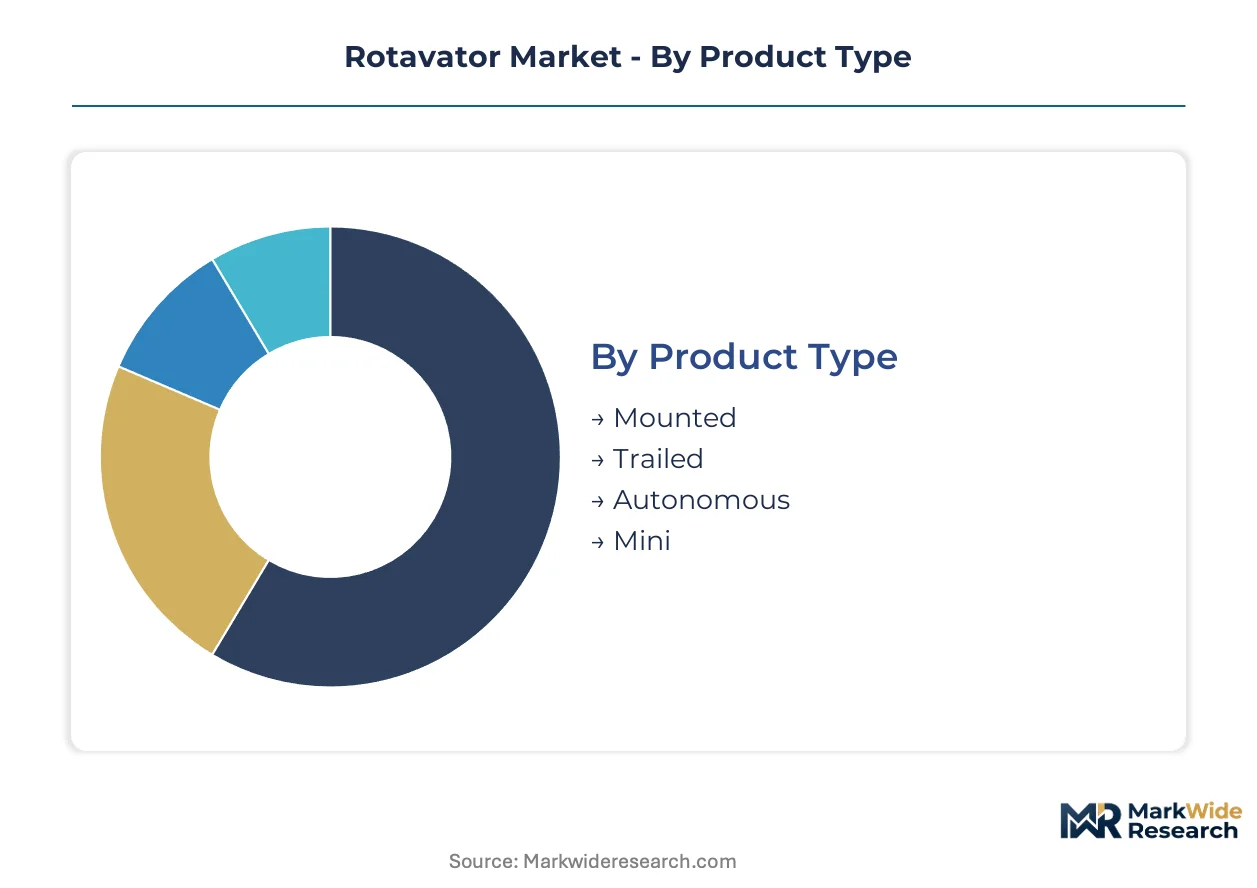
Rotavator procurement decisions hinge on tractor compatibility, field scale, and labor availability. Segmentation reveals divergent equipment strategies across smallholder cooperatives and large-scale commercial operations.
Product Type:
Standardization dominates at the commodity end while premium tiers demand application-specific engineering and attachment modularity.
- Mounted:Three-point hitch attachment systems integrate with existing tractor fleets across India and Brazil. Smallholder farms in Southeast Asia prioritize this category for capital efficiency and shared equipment pools.
- Autonomous:GPS-guided units with RTK positioning enable unmanned operation in East Asian horticulture. Labor cost pressures in Japan and South Korea accelerate deployment for precision seedbed preparation in greenhouse complexes.
- Trailed:Heavy-duty frames suit large field operations in Mato Grosso soybean belts. Hydraulic depth control accommodates variable residue loads.
- Mini:Compact rotary tillers serve peri-urban landscaping and vineyard inter-row maintenance. European municipalities specify these for noise-restricted zones.
Leading the category by volume: Mounted. Expanding most quickly: Autonomous.
End Use Industry:
Application intensity varies from seasonal seedbed preparation to continuous maintenance cycles, reshaping blade wear economics and service intervals.
- Agriculture:Row-crop and broadacre farming drives bulk demand for residue incorporation and primary tillage. India's stubble management mandates in Punjab and Haryana concentrate PTO-driven procurement.
- Horticulture:Specialty crop beds require shallow, uniform tillage with minimal soil structure disruption. East Asian protected cultivation facilities specify compact units with precise depth control.
- Landscaping:Municipal parks and golf courses demand low-emission equipment for aesthetic terrain preparation. European cities specify electric units for emission-restricted zones.
- Forestry:Site preparation for plantation establishment requires robust blade assemblies to break compacted soils and integrate slash. Brazilian eucalyptus and pine expansion sustains niche demand.
Agriculture commands the largest installed base. Horticulture shows the steepest technology premium capture.
Power Source:
Energy transition pressures and infrastructure availability create divergent adoption curves across rural and peri-urban deployment contexts.
- PTO:Mechanical power take-off systems from tractor engines sustain the dominant installed base. Brazil's expanding farm sizes and double-cropping intensity reinforce demand for high-torque PTO configurations.
- Electric:Battery-powered units eliminate exhaust emissions for greenhouse and residential applications. European municipalities with tightening air quality standards specify these for urban landscaping contracts.
- Diesel:Self-propelled engines serve remote operations lacking tractor infrastructure. African and Central Asian secondary markets absorb refurbished diesel units.
- Gasoline:Lightweight engines power mini rotavators for homeowner and small-scale horticulture use. Noise and fuel cost disadvantages limit commercial adoption.
PTO systems retain volume leadership. Electric configurations gain share fastest in regulated urban markets.
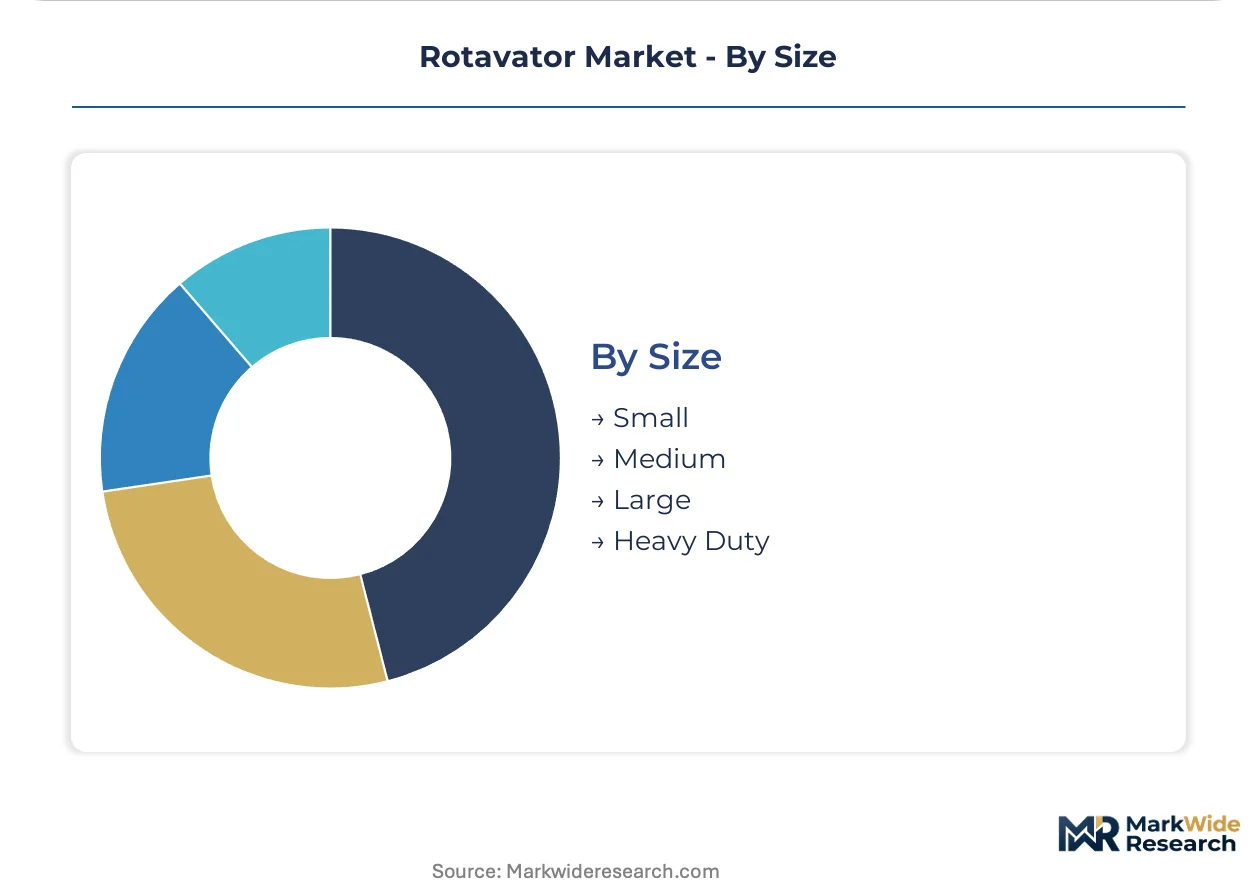
Size:
Field dimensions and tractor horsepower ratings dictate frame width and blade rotor specifications, fragmenting manufacturing runs.
- Small:Working widths under 1.2 meters suit compact tractors in Japanese rice paddies and European vineyards. Maneuverability in confined spaces commands price premiums.
- Heavy Duty:Reinforced gearboxes and blade carriers withstand abrasive soils and high-residue conditions in Brazilian Cerrado conversion zones. Extended service intervals justify capital outlay for large operators.
- Medium:Versatile configurations bridge smallholder and commercial farm requirements. India's cooperative procurement models favor this category for equipment sharing.
- Large:High-horsepower matching for broadacre operations in North American corn belts and Ukrainian grain zones. Transport width regulations constrain design flexibility.
Medium sizes dominate unit shipments. Heavy duty specifications capture the highest margin per blade assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludhiana anchors rotavator manufacturing density in India's northern agricultural belt. The Punjab industrial corridor concentrates blade forging and gearbox assembly operations serving domestic and export markets.
India
Smallholder consolidation in Punjab and Haryana drives mounted rotavator procurement for residue management. The PLI scheme for farm mechanization hardens domestic manufacturing capacity. Ludhiana and Pune industrial clusters retool stamping lines to meet BIS blade guard mandates.
Brazil
Soybean belt expansion in Mato Grosso and Paraná concentrates demand for heavy-duty PTO-driven units. ANVISA oversees agricultural equipment safety compliance alongside national mechanization programs. Sorocaba's machinery district fabricates reinforced frames for double-cropping operations.
Germany
Vineyard and orchard operators in Baden-Württemberg specify compact precision tillage equipment. CE marking under the EU Machinery Directive governs blade guard and emergency stop requirements. Stuttgart's engineering corridor hosts drivetrain specialists serving premium mounted segments.
Japan
Protected cultivation facilities in Chubu and Kansai regions accelerate autonomous rotavator deployment. METI guidelines shape agricultural robot certification pathways. Nagoya's precision manufacturing base supplies sensor-integrated tillage systems for greenhouse complexes.
Italy
Wine cooperatives in Veneto and Emilia-Romagna adopt equipment-as-a-service leasing models. EU Green Deal residue management protocols incentivize straw incorporation technology. Bologna's agricultural machinery district specializes in vineyard inter-row maintenance equipment.
Rotavator Market Competitive Environment
The competitive structure tilts toward diversified agricultural equipment conglomerates with captive distribution networks. Tiered positioning separates premium Italian engineering heritage from scale-driven Indian manufacturing. Three archetypes dominate: tractor-integrated OEMs with dealer density advantages, standalone implement specialists with attachment modularity, and precision agriculture technology integrators. Geographic expansion through licensed production and strategic procurement partnerships represent the dominant competitive moves.
Among diversified tractor-integrated manufacturers, Mahindra & Mahindra Ltd. and Kubota Corporation exemplify scale-driven archetypes with extensive rural dealer networks. Maschio Gaspardo occupies a position within the European specialist tier. CLAAS and AGCO Corporation represent conglomerate-backed implement portfolios. John Deere anchors the precision agriculture integration vector. Yanmar Co., Ltd. sits within the compact equipment specialization cluster serving East Asian horticulture.
| Leading Market Players |
|---|
| Maschio Gaspardo |
| Yanmar Co., Ltd. |
| Mahindra & Mahindra Ltd. |
| Shaktiman |
| Tractors and Farm Equipment Ltd. |
| Kubota Corporation |
| CLAAS |
| AGCO Corporation |
| John Deere |
| Others |
Value Chain & Pricing Dynamics
Powertrain electrification in compact landscaping units simultaneously compresses manufacturing cost curves and redistributes supply chain gravity toward battery cell and motor controller clusters in East Asia. This dual shift fragments legacy pricing hierarchies anchored to mechanical PTO systems while opening margin capture for OEMs mastering integrated electric drivetrain sourcing.
Pricing Analysis
Throughput-based pricing anchors premium tiers, with autonomous units commanding lease rates tied to hectares tilled per season rather than capital outlay. Three-tier pricing structure across premium sensor-integrated, standard PTO-driven, and economy refurbished segments stratifies buyer access. Cost compression in economy tiers intensifies because used European and Japanese equipment floods African and Central Asian secondary markets. Smallholder cooperatives in Southeast Asia exhibit highest price sensitivity, while Japanese greenhouse operators accept technology premiums for labor displacement.
Supply Chain Analysis
Container freight volatility from Indian forging clusters to Brazilian soybean belt distribution hubs reshapes landed cost calculations for blade assemblies and gearboxes. Manufacturing concentrates in India, Italy, and Japan, with Ludhiana's Punjab corridor dominating forged blade output and Bologna's district specializing in vineyard inter-row equipment. Supply chains draw from South African and Indonesian nickel-chromium concentrate markets for blade alloys, tethering margins to foundry energy costs. Single-source vulnerability concentrates in precision gearbox machining from Nagoya's precision manufacturing base. Distribution runs through tractor OEM captive dealer networks and independent agricultural implement distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotavator sector occupies a technology-transition phase where autonomous navigation and electric powertrains displace mechanical PTO dependency in peri-urban and protected cultivation segments.
For Market Incumbents: Anticipate margin compression in standard mounted categories from Indian PLI-scheme domestic manufacturing scale-up. Defensive positioning demands backward integration into blade forging capacity in Ludhiana or Pune clusters to secure alloy steel throughput. Certification investment in CE marking and BIS compliance creates export moats against unqualified Chinese competitors.
For New Entrants and Emerging Players: Vietnamese Mekong Delta smallholder cooperatives represent an underserved buyer archetype with pooled procurement potential and limited incumbent service coverage. White-space targets include equipment-as-a-service leasing models for European vineyard cooperatives and battery-powered compact units for emission-restricted North American municipalities. Go-to-market execution favors seasonal maintenance bundling to transfer blade wear risk from operators to OEMs.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision agriculture technology integrators with autonomous navigation software stacks and sensor-integrated tillage platforms. Long-term viability favors targets with demonstrated deployment in Japanese greenhouse complexes and East Asian horticulture facilities. The inflection signal to monitor is autonomous rotavator penetration rates in protected cultivation exceeding threshold adoption for operational labor displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Forging | Captive alloy steel processing in Indian industrial corridors insulates margin from South African concentrate volatility. |
| Autonomous Navigation Certification | METI pathway completion in Japan unlocks greenhouse deployment in Chubu and Kansai protected cultivation facilities. |
| Equipment-as-a-Service Launch | French and Italian wine cooperative leasing contracts transfer blade wear risk and concentrate multi-year procurement authority. |
| Electric Powertrain Platform Development | Battery-integrated compact units satisfy European municipal emission restrictions and noise ordinance compliance. |
| Residue Management Technology Partnership | Punjab and Haryana stubble incorporation mandates align rotavator procurement with India's Commission for Agricultural Costs and Prices incentives. |
Study Parameters
Multi-period observation of PLI scheme implementation trajectories, autonomous unit deployment rates in Japanese greenhouse facilities, and Brazilian soybean belt mechanization intensity anchored the trend analysis, supplemented by interviews with agricultural equipment procurement managers at Indian cooperative federations, aftermarket service heads in Bihar and eastern Uttar Pradesh, OEM platform engineers at Italian vineyard equipment specialists, and regulatory affairs leads navigating BIS certification pathways. Secondary validation drew from Indian customs export data for tillage implements, ANVISA agricultural equipment safety filings, EU Machinery Directive compliance registries, and tractor OEM dealer network disclosures. Bottom-up unit shipment modeling triangulated against top-down farm mechanization spend projections.
Segment-weighting approaches applied differential growth assumptions across autonomous, mounted, trailed, and mini product categories, with power source transitions from PTO to electric receiving distinct elasticity coefficients. End-use agriculture versus horticulture versus landscaping splits incorporated residue management mandate compliance rates and protected cultivation expansion data. CAGRs derived from fitted curves on historical mechanization intensity ratios and projected smallholder consolidation trajectories. Forecast inputs included alloy steel price indices from South African and Indonesian concentrate markets and PTO speed standardization adoption timelines.
Revisions become necessary when Indian PLI scheme disbursement delays, EU Machinery Directive enforcement escalations, or autonomous navigation regulatory pathway blockages materialize. Forecasts reflect documented assumptions on cooperative formation rates and labor cost trajectories in East Asian horticulture. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Powder Feed Center Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market