
 Hatchery Equipment Market | 2026-2036
Hatchery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hatchery Equipment Market Insights
Buyer concentration among integrated poultry processors is shifting as mid-sized commercial hatcheries in Southeast Asia and Latin America fragment procurement across specialized equipment vendors. Petersime sustains technology leadership through advanced climate control algorithms for multi-stage incubation. Jamesway anchors North American supply with heavy-duty hatcher platforms engineered for high-throughput operations. Vencomatic Group differentiates via integrated automation spanning egg handling through chick processing.
Hatchery equipment encompasses climate-controlled mechanical systems designed to maintain temperature within 0.1°C precision, humidity at 50-60% relative levels, and automated egg turning at 45° angles to optimize embryonic development for poultry and aquaculture production. Incubators and hatchers constitute the core revenue pool where margin concentrates among vendors offering integrated digital control platforms. Automated systems within the technology dimension are displacing manual control configurations as labor costs rise and biosecurity protocols tighten across commercial hatcheries. Environmental monitoring modules represent the fastest-expanding sub-category, driven by real-time data logging requirements for traceability compliance.
The USDA and FDA shape US market access through HACCP-aligned biosecurity standards and Salmonella reduction mandates that dictate equipment sanitation protocols. EU operators navigate EFSA hygiene regulations and CE marking requirements for electromagnetic compatibility in automated control systems. Stakeholders must weigh capital deployment toward fully automated hatchery lines against modular upgrade paths that preserve operational flexibility amid evolving regulatory thresholds for pathogen control and energy efficiency.
Market Dynamics
Automated climate control systems are compressing capital deployment timelines as commercial hatcheries race to meet HACCP-aligned biosecurity mandates while labor availability tightens across poultry-dense regions.
Growth Catalysts
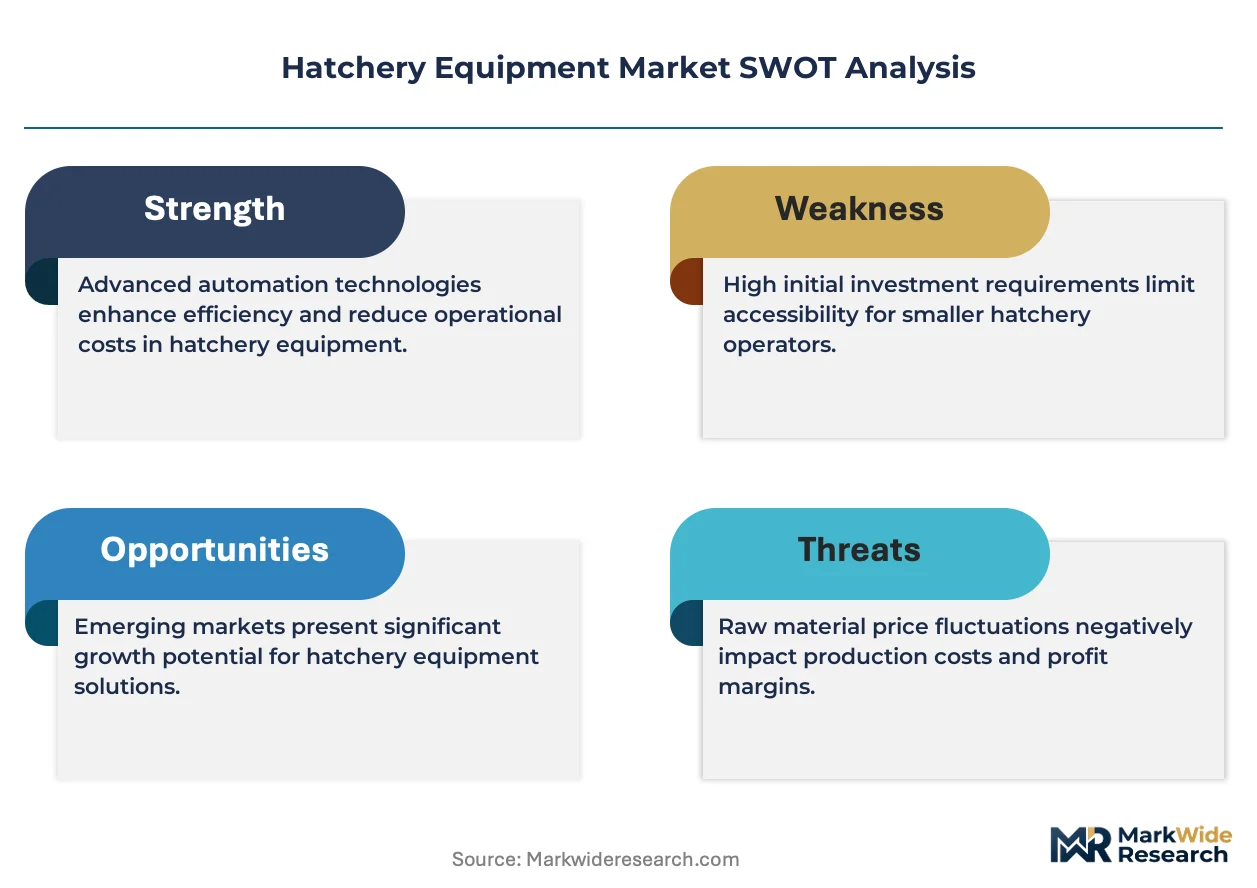
- USDA Salmonella Reduction Mandates:Federal pathogen control requirements are forcing manual hatcheries toward digital environmental monitoring to maintain compliance and avoid facility shutdowns.
- Multi-stage incubation algorithms:Advanced climate control software is optimizing embryonic survival rates while reducing energy consumption per chick produced.
- Brazilian integrated processors:Seara and BRF-scale operations are driving large-scale facility investments that pull through automated egg handling and chick processing lines.
Market Restraints
- Stainless steel input volatility:Sanitation-grade 316L steel price swings are compressing equipment margins and extending quotation validity periods to 90 days.
- Control system supplier concentration:European PLC and sensor vendors dominate critical automation components, exposing buyers to euro-denominated cost pressure.
- Biosecurity retrofit complexity:Legacy concrete structures resist modification for negative-pressure ventilation and automated washdown systems.
Strategic Opportunities
- Vietnam and Indonesia commercial expansion:Mid-scale poultry operations in Southeast Asia remain underpenetrated by integrated automation vendors serving only tier-one processors.
- Aquaculture hatchery adaptation:Shrimp and finfish producers are repurposing poultry climate control architectures for marine species with modified salinity tolerance.
- EU Green Deal energy efficiency incentives:Recovery and Resilience Facility funding is offsetting capex for heat recovery ventilation and solar-integrated incubation facilities.
Industry Challenges
- Mechatronics technician scarcity:Automated hatchery operations require hybrid mechanical-electrical skills that vocational programs have not scaled to match equipment deployment.
- CE-UL dual certification timelines:Equipment vendors face 14-18 month approval cycles to serve both European and North American buyers with unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hatchery Equipment Market |
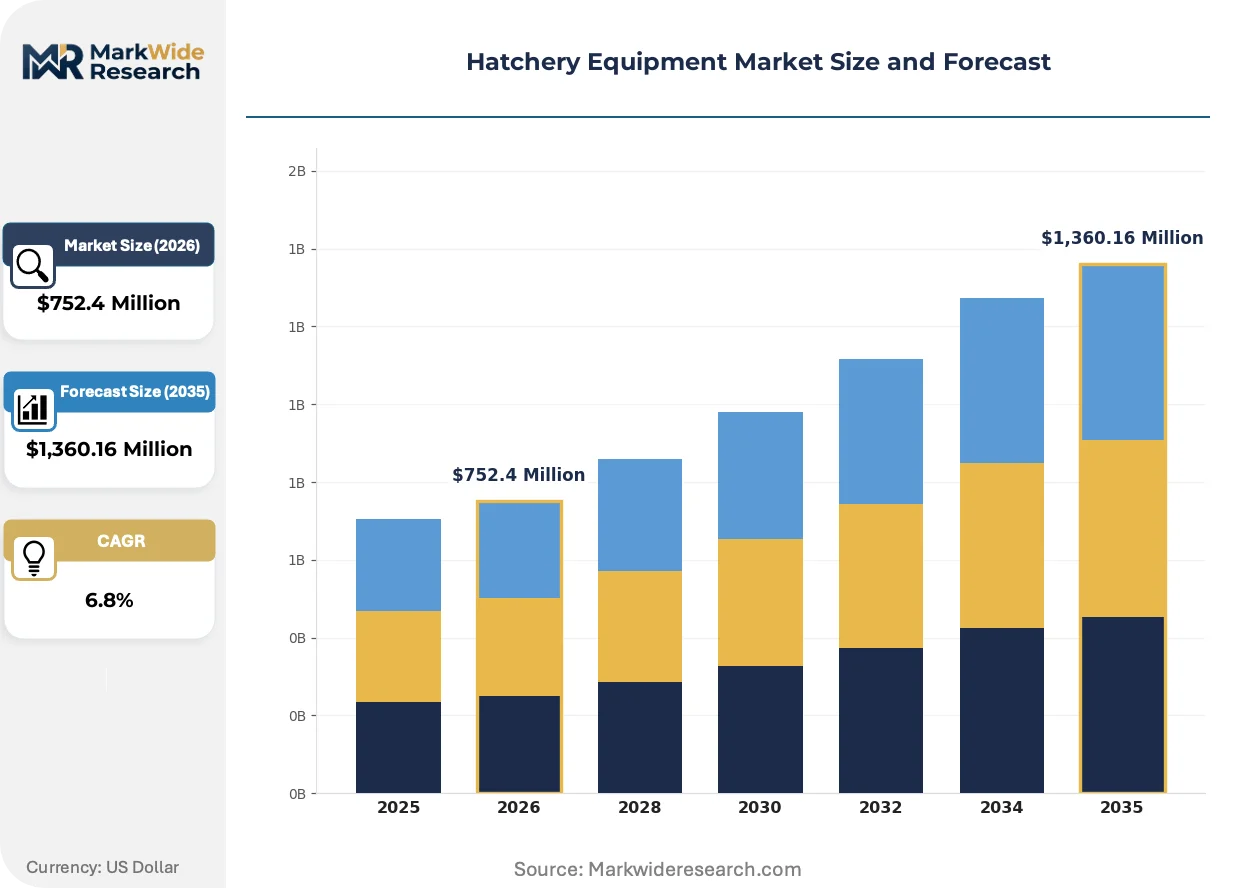
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $1,360.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Hatchers, Nesting Racks, Heating Systems Technology: Digital Control, Manual Control, Environmental Monitoring, Automated Systems End User: Poultry Farms, Aquaculture, Research Facilities, Commercial Hatcheries Application: Egg Incubation, Larval Rearing, Research Purposes, Educational Use |
| Companies Covered | HatchTech Incubation Technology, Jamesway, Petersime, Vencomatic Group, Pas Reform, EmTech Hatchery Systems, Innovatec Hatchery Automation, SALMET GmbH & Co., LINCO INCUBATOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hatchery Equipment Market Trends and Innovations
Digital twin modeling is compressing commissioning timelines and enabling predictive maintenance contracts that reshape vendor-customer relationships across hatchery operations.
Machine vision for embryo viability assessment is converging with cloud-based hatchery management platforms. Large-scale operators in the Netherlands and Thailand are deploying camera arrays that classify embryonic development stages without candling disruption. This convergence is compressing labor requirements while improving cull-rate accuracy and traceability documentation.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in climate control equipment. Hatchery builders must retool for CO2 transcritical or ammonia systems that demand higher pressure vessel certification. European equipment vendors are absorbing redesign costs fastest, while North American suppliers face catch-up investment to maintain cross-Atlantic competitiveness.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts. Brazilian and Mexican processors now procure incubation hardware from specialized vendors while sourcing predictive analytics separately from agricultural software firms. This pattern is most visible in Latin America, where integrated poultry groups prioritize operational data ownership over turnkey vendor relationships.
Hatchery Equipment Market Segmentation
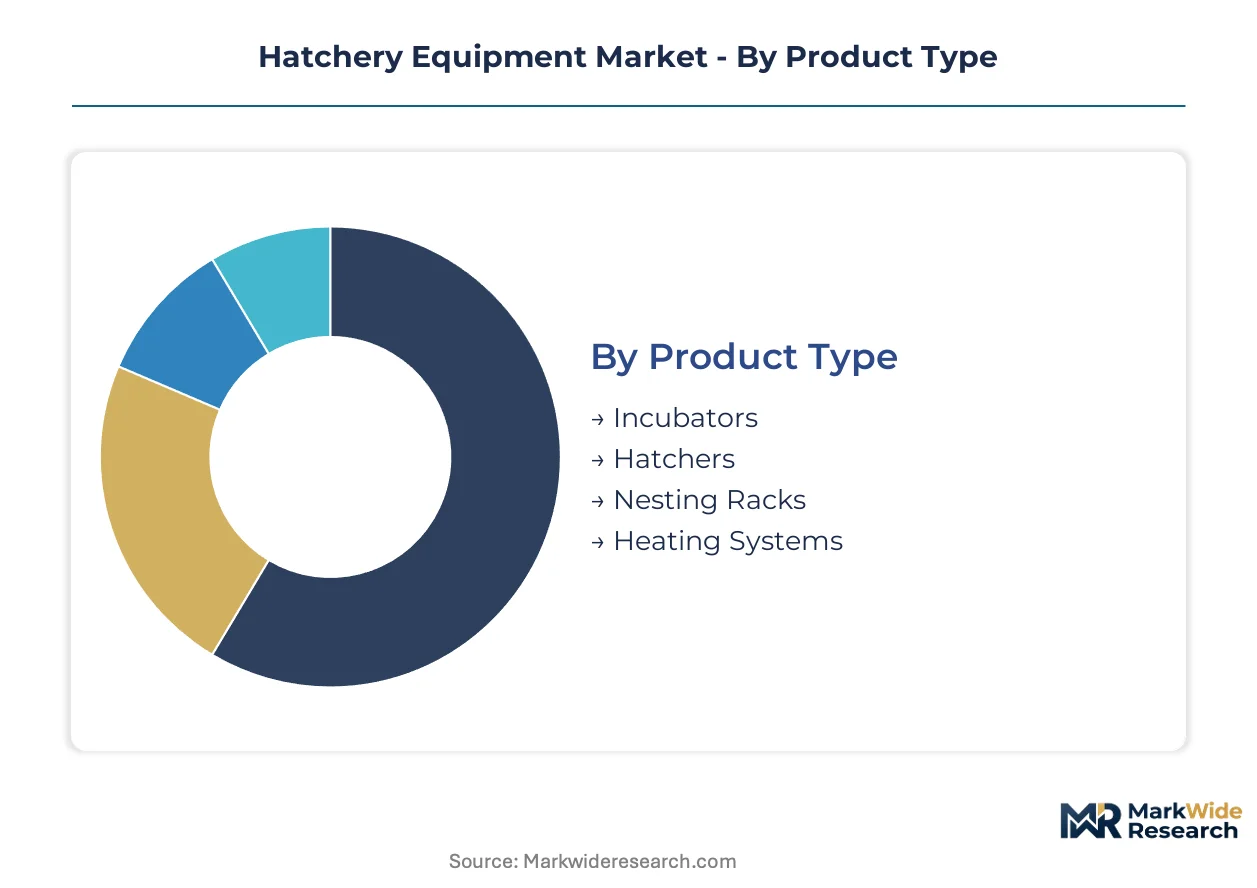
Hatchery equipment segmentation reflects divergent capital deployment strategies across integrated processors and independent operators. Equipment configuration choices directly determine biosecurity compliance pathways and labor substitution economics.
Product Type:
Standalone incubation units serve smaller operations with modular upgrade paths, while fully integrated hatchery lines embed climate control within facility-wide automation architectures.
- Incubators:Multi-stage cabinet systems maintain temperature precision within 0.1°C through forced-air circulation and programmable humidity modules. Brazilian integrated processors at Seara and BRF scale drive demand for 100,000+ egg capacity units with centralized digital control platforms.
- Hatchers:Single-stage hatcher baskets engineered for 95%+ hatch rate optimization incorporate automated chick separation and debris removal systems. North American heavy-duty platforms from Jamesway anchor high-throughput operations where downtime costs exceed $50,000 per hour.
- Nesting Racks:Roll-away egg collection systems reduce floor egg contamination in breeder house operations.
- Heating Systems:Radiant and forced-air configurations serve regional climate adaptation requirements across tropical and temperate installations.
Volume placements concentrate in Incubators; the faster expansion belongs to Hatchers.
Technology:
Cost tier stratification separates premium digital platforms from economy manual configurations, with mid-market hybrid systems capturing price-sensitive upgrade demand.
- Digital Control:PLC-based environmental management systems integrate temperature, humidity, CO2, and turning angle parameters through touchscreen interfaces. Petersime's multi-stage algorithms optimize embryonic survival while reducing energy consumption per chick produced.
- Automated Systems:Robotic egg transfer, candling, and chick processing lines eliminate human biosecurity breach vectors. Vencomatic Group's integrated automation spans egg handling through vaccination and sexing operations.
- Environmental Monitoring:Real-time data logging modules satisfy HACCP-aligned traceability mandates for USDA and FDA compliance.
- Manual Control:Dial thermostat and timer-based configurations persist in small-scale operations with limited capital availability.
Capital deployment tilts toward Digital Control in developed markets; Automated Systems gain share fastest in Southeast Asia and Latin America.
End User:
Customer type segmentation maps directly to procurement sophistication, with integrated poultry processors demanding turnkey solutions versus research facilities specifying component-level customization.
- Commercial Hatcheries:Large-scale integrated operations require 24/7 uptime guarantees and predictive maintenance contracts. These buyers consolidate procurement through multi-year framework agreements with primary equipment vendors.
- Poultry Farms:Independent and contract grower operations favor modular incubator additions that scale with flock expansion cycles.
- Aquaculture:Shrimp and finfish producers repurpose poultry climate architectures with salinity-tolerant modifications for marine hatchery applications.
- Research Facilities:Universities and breeding institutes specify precision-grade equipment with data export capabilities for experimental documentation.
Procurement volume clusters in Commercial Hatcheries; Aquaculture represents the steepest expansion trajectory.
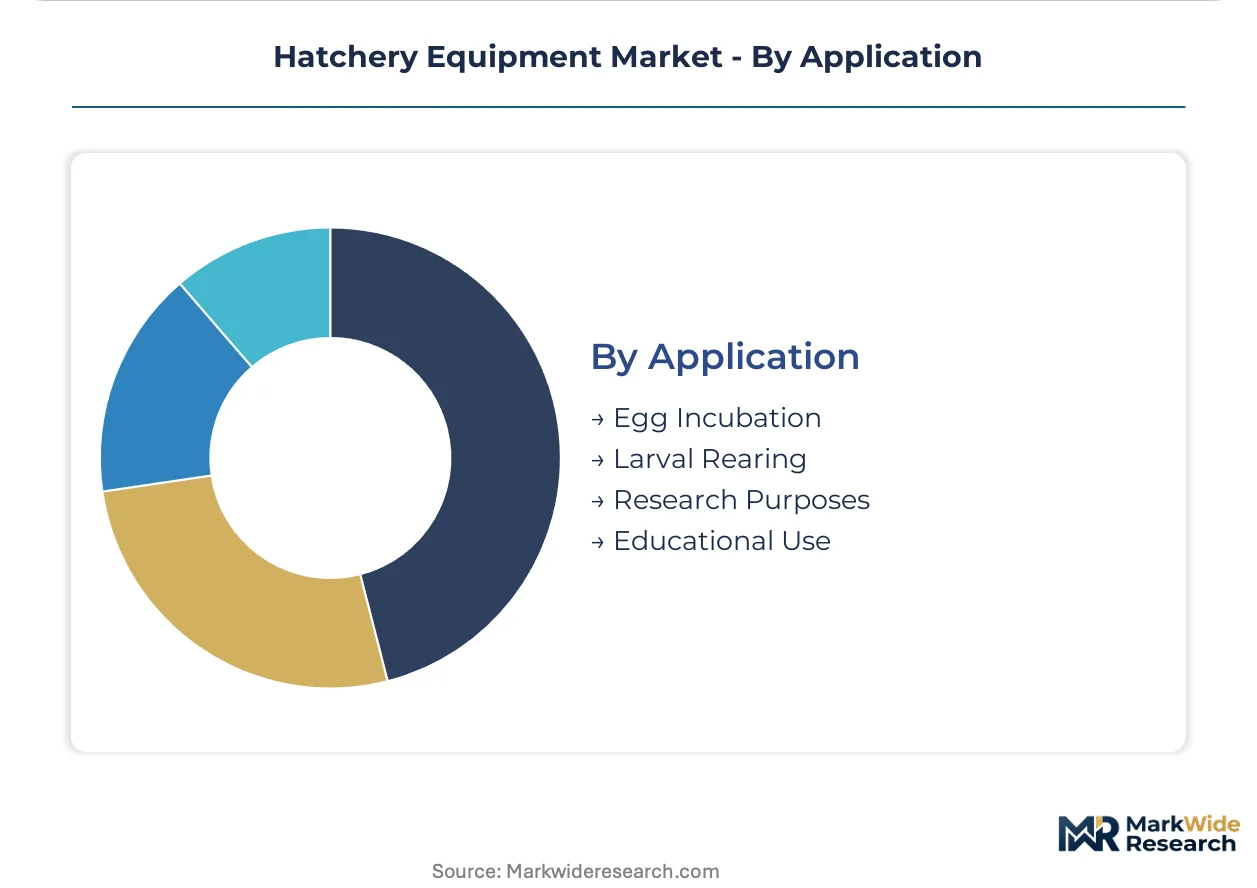
Application:
Maturity differentiation separates established egg incubation workflows from emerging larval rearing protocols adapted for marine species.
- Egg Incubation:Standardized temperature-humidity-turning protocols dominate poultry production, with 21-day chicken and 28-day turkey cycles driving equipment specification.
- Larval Rearing:Aquaculture hatcheries require modified climate control for water temperature management and salinity monitoring in shrimp and finfish production.
- Research Purposes:Controlled environment chambers support genetic selection experiments and vaccine development trials.
- Educational Use:Small-scale demonstration units serve agricultural extension programs and vocational training curricula.
Deployment scale favors Egg Incubation; Larval Rearing climbs fastest as aquaculture protein demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated poultry processors in Brazil command the largest equipment procurement volumes, while Southeast Asian commercial hatcheries and North American biosecurity retrofit projects fragment demand across specialized vendors.
Brazil
Seara and BRF-scale operations drive multi-million-dollar facility investments for automated egg handling and chick processing lines. ANVISA hygiene regulations align with USDA-equivalent Salmonella reduction protocols, forcing equipment sanitation upgrades. São Paulo state concentrates the densest cluster of commercial hatchery capacity expansion projects.
United States
Biosecurity retrofit demand surges as legacy concrete hatcheries adapt to negative-pressure ventilation mandates. USDA HACCP-aligned standards and FDA Salmonella reduction rules dictate automated environmental monitoring procurement. The Midwest poultry belt spanning Iowa and Arkansas anchors heavy-duty hatcher platform deployments.
Netherlands
Machine vision embryo assessment and cloud-based hatchery management platforms diffuse rapidly among large-scale operators. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, accelerating CO2 transcritical system adoption. The Gelderland region hosts concentrated digital twin modeling and predictive maintenance contract development.
Vietnam
Mid-scale poultry operations remain underpenetrated by integrated automation vendors serving only tier-one processors. The country's national food safety authority enforces emerging traceability standards that pull through basic environmental monitoring modules. The Mekong Delta concentrates contract grower hatchery expansion with modular incubator additions.
Thailand
Camera-array embryo viability classification systems deploy at commercial scale without candling disruption. National agricultural extension programs align equipment specifications with export market biosecurity requirements. The Central Plains region clusters aquaculture hatchery adaptation projects repurposing poultry climate architectures for shrimp production.
Hatchery Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aquaculture adaptation and predictive analytics unbundling. The vendor base stratifies across three maturity tiers: European technology leaders with multi-stage algorithm portfolios, North American heavy-duty platform specialists, and Asian modular system fabricators. Two strategic archetypes dominate competitive positioning: integrated automation providers spanning egg-to-chick workflows, and climate-control pure-plays with energy efficiency specialization. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Within the integrated automation tier, Petersime and Vencomatic Group exemplify platform breadth, while Jamesway anchors North American supply for high-throughput operations. HatchTech Incubation Technology occupies a position among climate-control specialists with algorithm-driven incubation systems. These three entities represent divergent geographic and technological positioning archetypes without implying specific market share claims.
| Leading Market Players |
|---|
| HatchTech Incubation Technology |
| Jamesway |
| Petersime |
| Vencomatic Group |
| Pas Reform |
| EmTech Hatchery Systems |
| Innovatec Hatchery Automation |
| SALMET GmbH & Co. |
| LINCO INCUBATOR |
| Others |
Pricing and Supply Chain Analysis
Backward integration into stainless steel fabrication and PLC component assembly anchors pricing power for European hatchery equipment vendors serving HACCP-aligned biosecurity mandates. This captive production of sanitation-grade 316L steel enclosures and climate control modules insulates margin structures from commodity volatility while compressing quotation cycles for Brazilian integrated processors.
Pricing Analysis
Volume placements cluster in multi-stage incubators above 100,000-egg capacity, while margin concentrates in automated chick processing lines with integrated vaccination and sexing modules. Price differentiation hinges on CE-UL dual certification status and predictive maintenance contract bundling. Cost compression in economy-tier manual configurations is intensifying because Southeast Asian contract growers prioritize modular upgrade paths over turnkey automation. Independent poultry farms exhibit highest price sensitivity; research facilities demonstrate lowest sensitivity due to precision-grade specification requirements.
Supply Chain Analysis
Direct-to-hatchery channels handle integrated processor demand in Brazil and the United States, while distributor networks serve fragmented mid-scale operators across Vietnam and Indonesia. Component sourcing draws from Germany for precision sensors, China for steel fabrication, and the Netherlands for machine vision arrays. Single-source vulnerability in European PLC vendors exposes buyers to euro-denominated cost pressure. Distribution runs through specialized agricultural equipment dealers with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stainless steel input volatility and mechatronics technician scarcity constrain capacity expansion, propping pricing power for vendors with captive fabrication and training infrastructure.
For Market Incumbents: Deepen predictive maintenance contract penetration to lock in multi-year revenue streams against emerging software unbundling threats from agricultural analytics firms. Expand certified technician training programs in São Paulo and Iowa to alleviate mechatronics scarcity that threatens uptime guarantees. Prioritize CE-UL dual certification investment to compress approval timelines for unified product platforms. For New Entrants and Emerging Players: Cloud-based hatchery management platforms offer the lowest customer acquisition cost route into machine vision embryo assessment segments currently dominated by Dutch and Thai operators. Target Vietnam's Mekong Delta contract grower clusters with modular environmental monitoring modules that satisfy emerging national traceability standards without full automation capex. Pursue aquaculture hatchery adaptation for shrimp producers repurposing poultry climate architectures. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated automation platforms seeking climate-control algorithm portfolios. Long-term viability favors vendors with energy efficiency specialization aligned with EU Green Deal heat recovery incentives. Watch EU F-Gas Regulation enforcement timelines as inflection indicator for CO2 transcritical system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive 316L production insulates margins from commodity volatility for HACCP-compliant equipment. |
| Predictive Maintenance Contract Expansion | Multi-year service agreements lock in revenue against software unbundling trends in Latin America. |
| CE-UL Dual Certification Investment | Unified product platforms compress 14-18 month approval cycles for cross-Atlantic market access. |
| Aquaculture Hatchery Adaptation | Salinity-tolerant climate systems open shrimp and finfish segments beyond poultry saturation. |
| Mechatronics Technician Training Scale-Up | Hybrid skill programs alleviate scarcity threatening automated hatchery uptime guarantees. |
Research Methodology
Document review covered equipment vendor technical specifications, USDA and FDA regulatory filings, and ANVISA hygiene protocols, complemented by interviews with hatchery operations managers, OEM procurement leads at Brazilian integrated processors, agricultural equipment distributors, and climate control system engineers. Secondary validation drew from customs trade data, SEC filings of publicly traded poultry processors, and EU F-Gas Regulation implementation reports. Bottom-up equipment shipment analysis triangulated against top-down protein demand projections.
Segment-level value outputs were derived through modeling across product type, technology tier, end-user configuration, and application maturity dimensions throughout the forecast period. CAGRs were computed from installed base expansion rates and replacement cycle analysis. Industry-specific inputs incorporated Salmonella reduction mandate compliance timelines and energy efficiency incentive uptake curves.
The model holds under stable regulatory enforcement and input cost assumptions; deviation in stainless steel price volatility or biosecurity retrofit subsidy levels would shift capital deployment trajectories. Forecasts reflect documented assumptions regarding integrated processor expansion rates and aquaculture protein demand acceleration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Bean Harvester Market