
 Harrows Market | 2026-2036
Harrows Market Size, Share, and Industry Trends Forecast 2026-2036
Harrows Market Outlook
Modular harrow configurations is decoupling attachment sales from tractor OEM bundling, forcing independent component decisions at the dealer level. Deere & Company leverages its precision agriculture ecosystem to anchor premium positioning across integrated tillage suites. AGCO Corporation competes through aftermarket modularity, sustaining dealer margin pools on retrofit attachments. KUBOTA Corporation specializes in compact folding designs for mid-acreage operators in fragmented Asian landholding structures.
A harrow is a soil tillage implement featuring curved or angled tines, discs, or blades mounted on a frame to break, smooth, and aerate soil surfaces; steel-tine variants typically operate at working depths of 5–15 centimeters with tine spacing calibrated to residue volume and soil texture. Its primary commercial purpose is seedbed preparation and weed control in mechanized row-crop and broadacre systems. Folding harrows dominate transport logistics and dealer inventory economics across high-acreage markets, while retractable configurations capture fastest growth in minimum-tillage transitions where rapid depth adjustment reduces pass counts. Steel remains the material baseline for abrasion resistance in rocky soils, though composite tine inserts gain traction in corrosion-intensive rice paddy applications where weight reduction extends tractor hydraulic life.
EPA agricultural equipment emissions standards and EU F-Gas Regulation on tractor refrigerants shape engine-platform compatibility requirements that cascade into harrow hitch and hydraulic specifications. OSHA farm machinery guarding rules and ISO 4254 safety standards for soil-working equipment mandate shielding configurations that influence tine geometry and frame clearances. Stakeholders must monitor evolving carbon-accounting methodologies for soil disturbance intensity, as emerging certification schemes for climate-smart commodities will likely embed equipment-performance thresholds into procurement criteria and farm-level compliance obligations.
Market Dynamics
Carbon sequestration mandates under the EU Green Deal are compressing tillage pass counts and forcing equipment specification changes toward minimum-disturbance designs across major grain-producing regions.
Growth Catalysts
- EU Green Deal soil health frameworks:Carbon sequestration mandates in the European Union are mandating reduced soil disturbance intensity, accelerating replacement of conventional tillage implements with low-disturbance harrow configurations.
- Consolidation in the US Corn Belt:Industrial-scale farming operations across Iowa, Illinois, and Indiana are driving capital expenditure on precision tillage equipment with integrated depth control and residue management capabilities.
- Composite tine technology:Corrosion-resistant composite inserts for rice paddy applications are extending tractor hydraulic system life and opening replacement demand in water-intensive cropping systems across Southeast Asian deltas.
Market Restraints
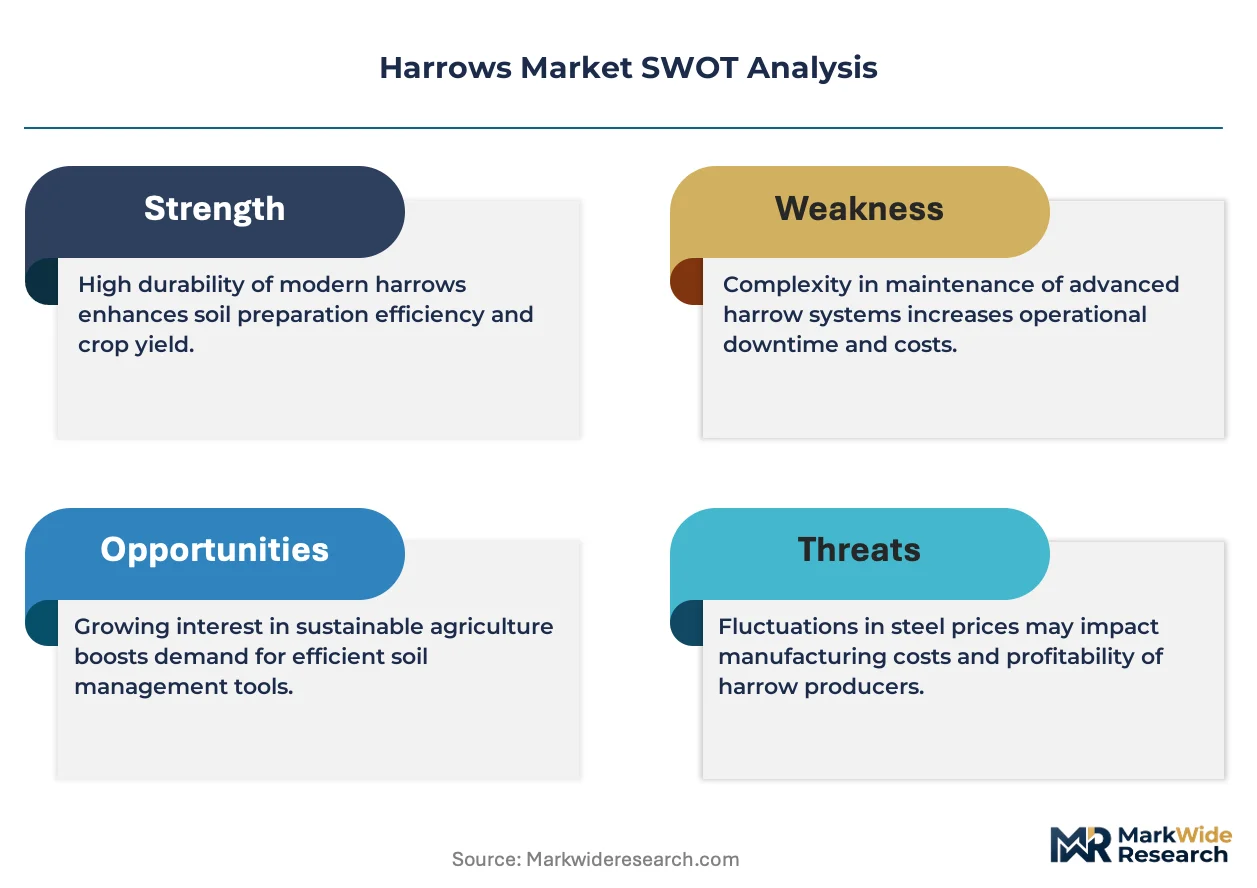
- Steel price volatility:Abrasion-resistant steel alloys constitute the primary material baseline for rocky soil applications, exposing manufacturers to input cost swings that compress margin pools on standard-duty implements.
- Tractor OEM bundling concentration:Integrated tillage suites from major agricultural equipment manufacturers limit independent attachment sales in North American dealer networks, constraining market access for specialized harrow producers.
- Working depth limitations:Steel-tine variants operating at 5–15 centimeter depths cannot substitute for primary tillage in heavy residue conditions, capping addressable share in conventional inversion tillage systems.
Strategic Opportunities
- Black Sea grain expansion:Industrial-scale operations across Ukraine and southern Russia present underpenetrated demand for folding transport configurations suited to high-acreage logistics and dealer inventory economics.
- Climate-smart commodity certification:Emerging carbon-accounting methodologies for soil disturbance intensity will embed equipment-performance thresholds into procurement criteria, creating compliance-driven replacement cycles.
- Retrofit modularity channel:Aftermarket attachment sales decoupled from new tractor purchases enable dealer margin capture on precision depth-control retrofits to existing implement fleets.
Industry Challenges
- Precision agriculture skill gaps:Dealer service networks face shortages of technicians capable of calibrating integrated tillage suites with variable-rate control systems and telemetry platforms.
- ISO 4254 safety compliance timelines:Shielding configurations mandated under international soil-working equipment standards require frame redesign cycles that delay product launches by 12–18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harrows Market |
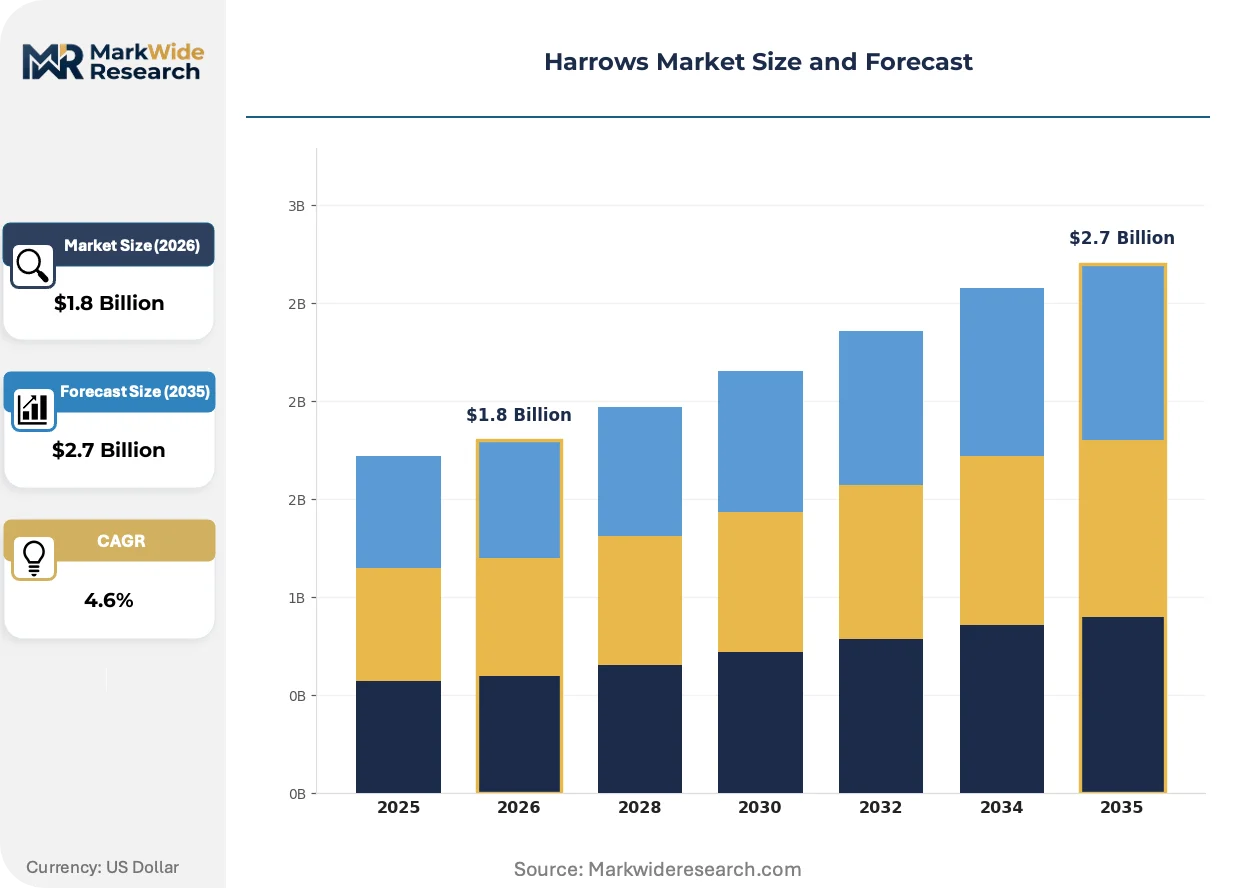
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed, Folding, Retractable, Offset End User: Farmers, Contractors, Agricultural Cooperatives, Hobbyists Material: Steel, Aluminum, Cast Iron, Composite Application: Tillage, Soil Preparation, Seedbed Preparation, Landscaping |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., KUBOTA Corporation, CLAAS KGaA mbH, KUHN SAS, LEMKEN GmbH & Co. KG, Mahindra & Mahindra Ltd, John Deere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harrows Market Strategic Shifts
Active sensor integration and material science advances are compressing the gap between precision agriculture platforms and mechanical soil preparation, reshaping how tillage implements interface with farm management systems.
Variable-depth hydraulic control systems with real-time soil resistance feedback are integrating GPS-guided implement management platforms used in large-scale row-crop operations. Deere and AGCO are deploying these configurations across premium tillage suites in the US Corn Belt and Canadian prairies. This convergence is integrating harrow operations into unified field-task sequencing that optimizes fuel consumption and soil disturbance metrics.
EPA agricultural equipment emissions standards and EU F-Gas Regulation on tractor refrigerants are cascading into hitch and hydraulic specification requirements that force platform redesigns. Engine compatibility mandates are narrowing the attachment interface standards that independent harrow manufacturers must support. European dealers are responding by consolidating inventory around Tier 4 Final and Stage V compatible folding configurations that satisfy cross-border transport logistics.
Capital expenditure decisions among grain cooperatives and custom applicator fleets are unbundling tillage service contracts from equipment ownership models. Rental and lease channels for seasonal harrow deployments are displacing outright purchase in fragmented Midwest landholding structures. This pattern concentrates most visibly across Kansas and Nebraska where operational scale variability favors flexible access over fixed asset deployment.
Harrows Market Segmentation
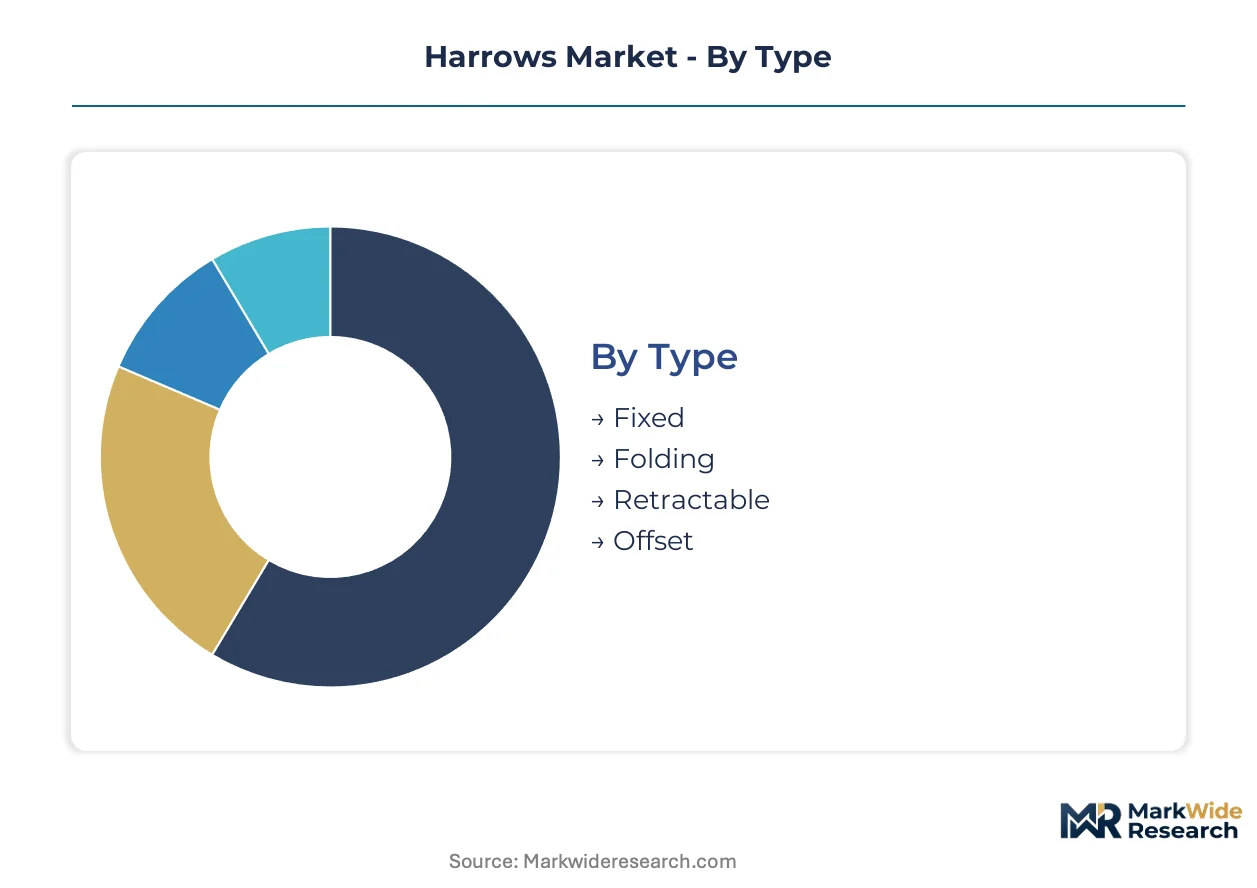
Harrows equipment segments diverge sharply in capital requirements and depreciation profiles, with transport configuration and material selection driving total cost of ownership calculations across divergent operational scales. Equipment financing structures and replacement cycle timing vary systematically by segment, reshaping manufacturer pricing power and dealer inventory strategies.
Type:
Folding configurations command the steepest upfront capital outlays due to hydraulic transport systems and reinforced hinge assemblies, while fixed-frame variants minimize entry costs for low-acreage operators.
- Fixed:Rigid-frame construction with welded tine bars eliminates hydraulic complexity and reduces maintenance intervals. Demand clusters among hobbyist operators and smallholder cooperatives in fragmented European landholding structures where transport distances remain minimal.
- Folding:Articulated wing sections with hydraulic folding mechanisms enable road-legal transport widths and reduce logistics costs for high-acreage operations. Corn Belt grain cooperatives and Black Sea commercial farms prioritize these configurations despite 40-60% capital premiums over fixed alternatives.
- Retractable:Variable-width tine arrays with mechanical or hydraulic retraction systems for rapid field-to-road conversion. Precision agriculture adopters favor these for integrated implement management platforms.
- Offset:Asymmetric frame geometry for boundary cultivation and obstacle navigation. Orchard and vineyard specialists in Mediterranean climates specify these for confined-space operations.
Folding configurations absorb the bulk of installed capacity; retractable designs are expanding most quickly.
End User:
Customer scale determines specification complexity, with commercial operators prioritizing telemetry integration and custom applicators emphasizing rapid attach-detach compatibility.
- Farmers:Owner-operators across mid-scale row-crop and broadacre systems. US Corn Belt and Canadian prairie producers drive specification toward GPS-guided depth control and residue management integration.
- Contractors:Custom tillage service providers with seasonal equipment utilization maximization requirements. Fleet standardization around folding transport configurations dominates this channel.
- Agricultural Cooperatives:Pooled-equipment entities with centralized maintenance facilities. EU Green Deal compliance obligations accelerate their replacement cycles toward minimum-disturbance designs.
- Hobbyists:Small-acreage landowners and part-time operators with price-sensitive procurement patterns. Compact tractor compatibility constrains specification in this tier.
Farmers represent the dominant procurement volume; agricultural cooperatives are gaining share fastest.
Material:
Abrasion resistance and corrosion tolerance drive material selection, with soil chemistry and residue chemistry determining replacement intervals and lifecycle economics.
- Steel:Boron-alloy and high-carbon formulations for rocky soil durability. Baseline specification across North American grain regions where stone damage accelerates tine wear.
- Aluminum:Lightweight frame components reducing draft requirements and fuel consumption. Gaining traction in conservation tillage transitions where pass count reduction offsets material cost premiums.
- Cast Iron:Dense, vibration-dampening construction for heavy clay soil penetration. Traditional specification in Eastern European black earth regions.
- Composite:Glass-fiber and carbon-fiber tine inserts for corrosion-intensive rice paddy applications. Southeast Asian delta operations specify these to extend tractor hydraulic system life.
Steel dominates current installed base; composite inserts are climbing the fastest.
Application:
Task specificity determines implement geometry, with seedbed preparation commanding the most precise depth calibration and residue management integration.
- Tillage:Secondary soil disturbance for weed control and residue incorporation. Minimum-tillage transitions compress pass counts and reshape equipment specifications.
- Soil Preparation:Primary surface conditioning ahead of planting. Heavy residue conditions in no-till corn-soy rotations drive demand for aggressive tine angles.
- Seedbed Preparation:Final surface refinement for uniform germination environments. Precision depth control and clod sizing specifications concentrate demand in vegetable and specialty crop regions.
- Landscaping:Non-agricultural surface conditioning for turf establishment and erosion control. Municipal and golf course maintenance contracts sustain this niche.
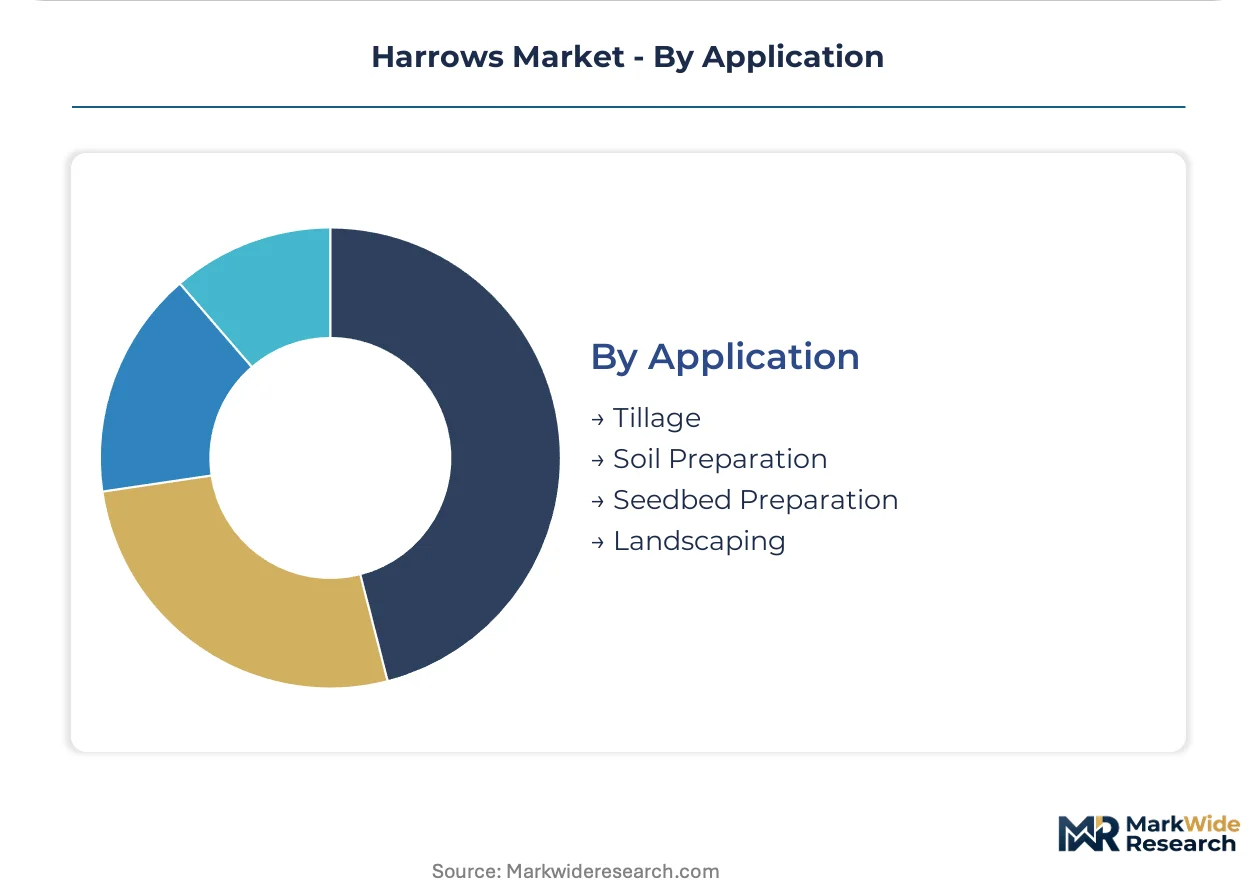
Soil preparation captures the largest equipment population; seedbed preparation is gaining specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harrows production concentrates in Germany and the United States while consumption gravity shifts toward grain-exporting zones in Eastern Europe and South America. Manufacturing clusters in Baden-Württemberg and Iowa anchor precision tillage supply chains. Emerging demand pockets in Ukraine and Brazil reshape procurement patterns for transport-optimized folding configurations.
United States
EPA agricultural equipment emissions standards and Tier 4 Final engine compatibility mandates cascade into hydraulic hitch specifications for Corn Belt operators. Iowa, Illinois, and Indiana grain cooperatives drive capital expenditure on GPS-guided depth control systems. Dealer networks in Des Moines and Peoria prioritize folding transport configurations for high-acreage logistics.
Germany
EU Green Deal carbon sequestration frameworks compress tillage pass counts and accelerate minimum-disturbance equipment replacement cycles. REACH compliance on steel alloy formulations shapes tine material specifications for rocky soil applications. LEMKEN GmbH & Co. KG anchors precision tillage manufacturing in Alpen, with distribution radiating across Black Sea grain corridors.
Brazil
Consolidation into industrial-scale soybean and corn operations in Mato Grosso and Goiás drives mechanized soil preparation procurement. ANVISA agricultural machinery safety protocols align with ISO 4254 shielding standards for residue-intensive conditions. São Paulo-based dealer networks stock folding configurations for seasonal custom applicator fleets.
Ukraine
Black Sea grain expansion creates underpenetrated demand for high-acreage folding harrows suited to consolidated commercial farms. National soil health frameworks under EU accession alignment pressure drive minimum-tillage transitions. Kherson and Odesa oblasts concentrate replacement demand from industrial-scale operators rebuilding equipment fleets.
India
BIS agricultural equipment standards and PLI scheme incentives for farm mechanization reshape domestic manufacturing capacity. Maharashtra and Gujarat tractor OEM bundling limits independent attachment sales in dealer networks. Compact folding designs gain traction in Punjab and Haryana where mid-acreage operators fragment landholding structures.
Harrows Market Competitive Environment
The competitive structure tilts toward diversified agricultural equipment conglomerates with precision agriculture ecosystems. Tiered positioning separates integrated tillage suite providers from modular attachment specialists. Three archetypes dominate: tractor OEM-anchored full-line suppliers, independent implement specialists with regional fabrication depth, and aftermarket retrofit providers capturing dealer margin pools. Competitive moves concentrate on precision agriculture platform integration and folding transport configuration patents.
Within the diversified conglomerate tier, Deere & Company and AGCO Corporation exemplify integrated ecosystem positioning, while KUBOTA Corporation represents compact equipment specialization for fragmented Asian landholding structures. German fabricators LEMKEN GmbH & Co. KG and KUHN SAS occupy positions in European precision tillage design, with CLAAS KGaA mbH anchoring harvester-adjacent soil preparation portfolios. Indian and Japanese entrants Mahindra & Mahindra Ltd and KUBOTA Corporation sit within mid-scale mechanization tiers targeting price-sensitive procurement in emerging grain regions.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| KUBOTA Corporation |
| CLAAS KGaA mbH |
| KUHN SAS |
| LEMKEN GmbH & Co. KG |
| Mahindra & Mahindra Ltd |
| John Deere |
| Others |
Value Chain & Pricing Dynamics
Composite tine technology diffusion is compressing cost structures for corrosion-intensive applications while concentrating procurement leverage among Southeast Asian component specialists. This shift simultaneously erodes steel-alloy pricing premiums and redraws supplier qualification maps around rice paddy mechanization clusters.
Pricing Analysis
Margin tightening in folding transport configurations reflects Tier 4 Final engine compatibility mandates that cascade into hydraulic system cost inflation. Three-tier pricing structure across premium, standard, and economy levels segments buyers by telemetry integration depth and GPS-guided depth control capability. Agricultural cooperatives in the EU exhibit highest price sensitivity due to Green Deal compliance budget constraints, while US Corn Belt grain operations absorb premiums for integrated precision agriculture suites.
Supply Chain Analysis
ISO 4254 safety certification gating delays product launches by 12–18 months, compressing supplier pools to fabricators with proven shielding design capabilities. Manufacturing concentrates in Germany, the United States, and India, with Baden-Württemberg and Iowa anchoring precision tillage fabrication. Supply chains draw from boron-alloy steel suppliers, hydraulic actuator manufacturers, and composite insert molders. Single-source vulnerability concentrates in European folding hinge assembly specialists. Distribution runs through OEM-anchored dealer networks and independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Harrows Market is consolidating around precision agriculture ecosystem providers, with tractor OEM bundling concentration forcing independent attachment specialists toward niche modularity plays or exit.
For Market Incumbents: Anticipate margin compression from steel price volatility by securing captive supply of abrasion-resistant alloys through backward integration into European steel fabrication. Defend dealer relationships against AGCO and Deere ecosystem lock-in by accelerating ISO 4254 certification pipelines for rapid frame redesign cycles. Prioritize retrofit modularity channels to capture margin pools on precision depth-control attachments decoupled from new tractor sales. For New Entrants and Emerging Players: E-commerce direct-to-farmer platforms offer lowest-friction entry vectors around compact folding designs for mid-acreage operators in fragmented Asian landholding structures. Target Ukrainian Black Sea grain corridors where industrial-scale fleet rebuilding creates underpenetrated demand for transport-optimized configurations. Pursue climate-smart commodity certification pre-alignment to embed equipment-performance thresholds into procurement criteria ahead of compliance-driven replacement cycles. For Investors and Strategic Acquirers: Re-rating potential sits with composite tine technology specialists given corrosion-resistant insert adoption curves in Southeast Asian rice deltas. Long-term viability favors acquisition targets with established folding transport configuration patents and dealer network density in minimum-tillage transition zones. Monitor EU carbon-accounting methodology finalization as inflection signal for compliance-driven equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Deere and AGCO ecosystem anchoring locks in premium tillage suite pricing across Corn Belt dealer networks. |
| Composite Tine Manufacturing Scale-Up | Corrosion-resistant insert production expansion extends tractor hydraulic life in Southeast Asian paddy applications. |
| Backward Integration into Steel Alloys | Captive boron-alloy supply secures margin pools against commodity price volatility in rocky soil configurations. |
| Climate-Smart Certification Pre-Alignment | EU Green Deal carbon-accounting methodology embedding creates compliance-driven replacement demand capture. |
| Folding Transport Configuration Patent Expansion | Intellectual property density in hydraulic hinge assemblies protects high-acreage logistics market share. |
Study Parameters
Trade association filings, customs and excise records, and SEC 10-K disclosures formed the secondary backbone for equipment shipment and revenue triangulation. Primary interviews with agricultural cooperative procurement managers, OEM tillage product directors, independent dealer principals, and aftermarket service heads validated specification trends and replacement cycle timing. Bottom-up unit economics across folding, fixed, and retractable configurations were cross-checked against top-down market sizing from machinery registration databases.
Historical trendline analysis of capital expenditure patterns across US Corn Belt grain cooperatives and EU agricultural equipment fleets established baseline growth trajectories. The forecast framework models demand across transport configuration type, end-user scale tier, material specification, and application intensity dimensions. CAGRs were derived from regression analysis of precision agriculture adoption curves and minimum-tillage transition velocities, with composite tine technology penetration and carbon sequestration mandate compliance timelines as industry-specific demand shapers.
The model holds under steady EU Green Deal implementation and stable grain commodity price regimes; deviation in Black Sea export corridor stability or EPA emissions standard acceleration would shift replacement cycle timing. Forecasts reflect assumptions around dealer inventory economics and OEM bundling concentration persistence. A model refresh is warranted upon material change in carbon-accounting methodology certification thresholds or composite insert cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Oil Expellers Market